

Key Takeaways
- Disney beat estimates with $25.95 billion of fiscal fourth-quarter revenue and said again that it is exploring a free, ad-supported version of Disney+.
- A free Disney+ would compete for the same price-sensitive viewers as Netflix’s $8.99-a-month U.S. ads plan.
- Netflix cut its 2026 ad forecast to about $2.7 billion from about $3 billion in October, and analysts expect its revenue growth to keep slowing through 2028.
- Netflix trades at about 17x forward earnings, and its 2027 guidance in January is the next test.
Disney (DIS) beat Wall Street’s estimates on Tuesday, Nov. 17, though the stock closed down 1.15% at $117.33. The most interesting thing CEO Josh D’Amaro said on the call was about something Disney doesn’t even sell yet: a free version of Disney+.
That’s a problem for Netflix (NFLX). In March, it raised the price of its cheapest U.S. plan, the one with ads, to $8.99 a month from $7.99, and that plan is a big part of how Netflix expects to keep growing. Netflix shares fell 1.76% the same day to $59.68, their lowest close in a year, as the S&P 500 fell 1%.
Disney is going after the price-sensitive viewer
Disney earned an adjusted $1.77 a share on revenue of $25.95 billion in its fiscal fourth quarter, ahead of the $1.68 and $25.2 billion analysts expected.
Then D’Amaro returned to an idea he first raised on Disney’s August call:
“We are exploring a free product,” he told investors, adding that it could reach more price-sensitive consumers and bring in new Disney+ subscribers.
He added that a free tier would give Disney more ad inventory and “a key retention tool that, quite frankly, we currently don’t have.”
TIKR tracks 32 analysts on Disney. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Disney, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Disney’s Analyst Ratings
Netflix’s ads plan has a lot riding on it
That viewer is exactly who Netflix’s $8.99 plan is built for: someone who’ll sit through ads to pay less. Today, Disney+ with ads costs $12.49 a month, $3.50 more than Netflix’s ads plan. Free would flip that.
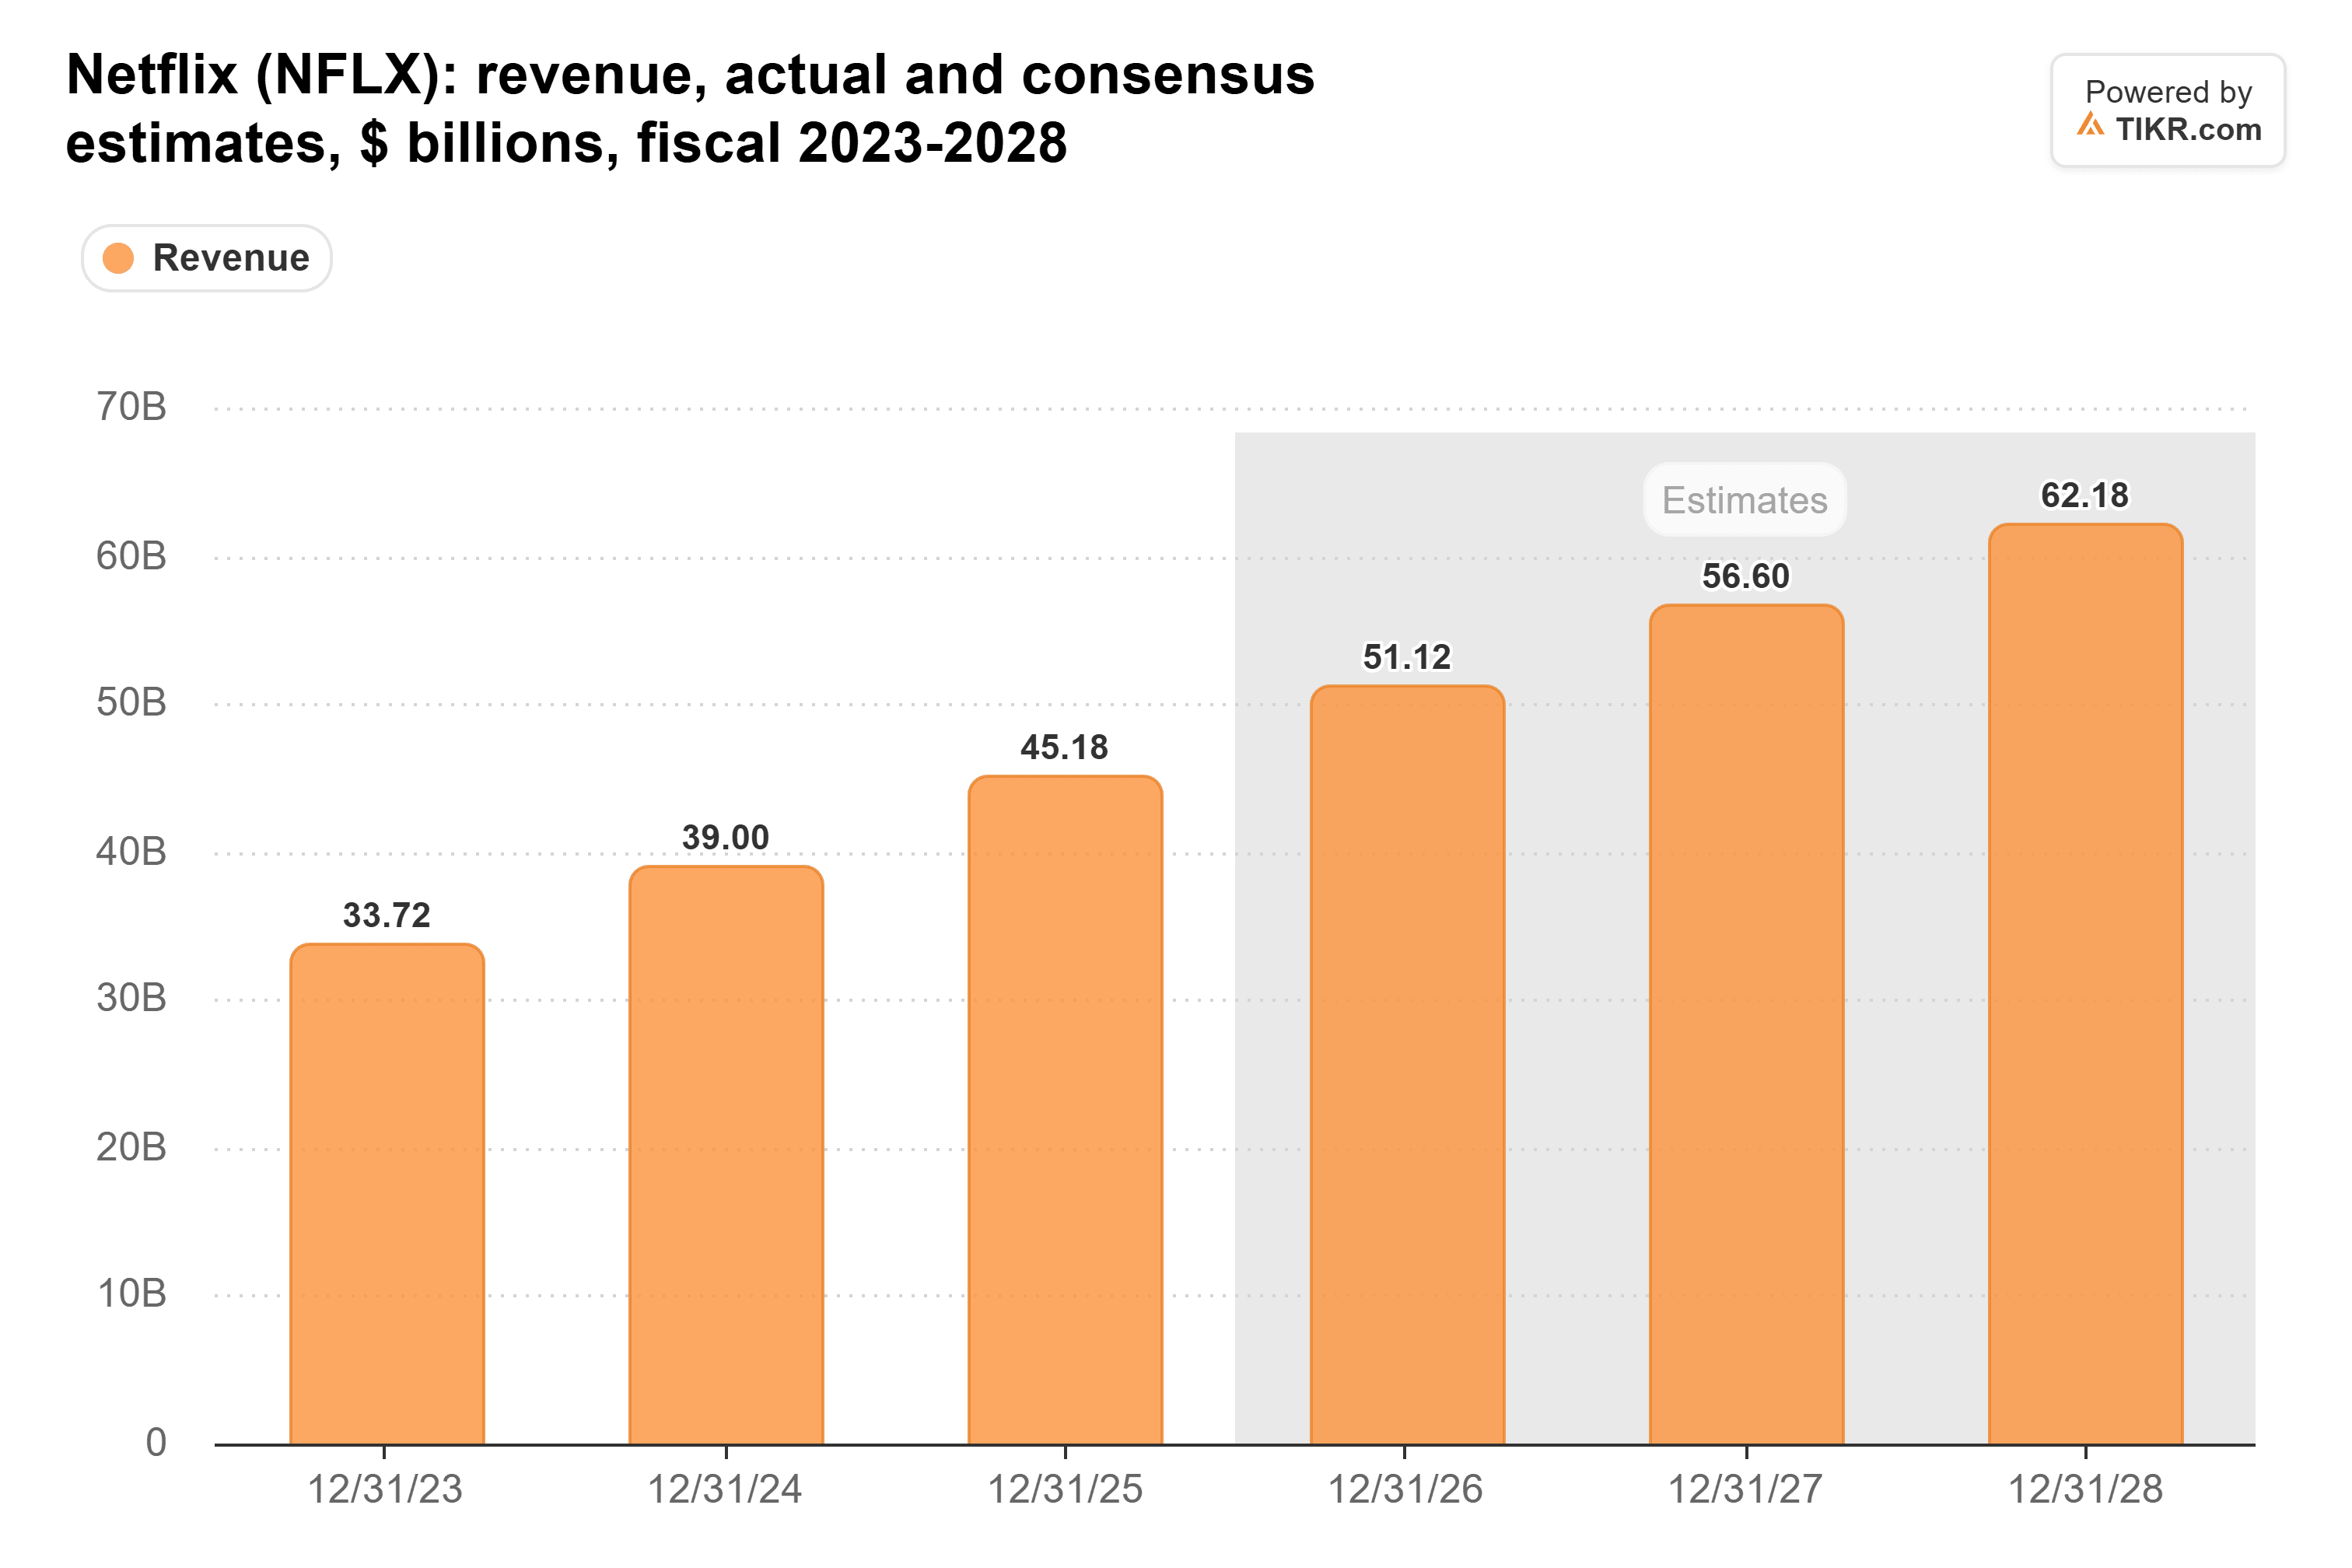
And Netflix needs that plan growing. Its revenue growth slowed every quarter, from 17.6% in the fourth quarter of 2025 to 11.8% in the third quarter of 2026, and analysts expect it to keep slowing for years:
Ads were supposed to help close that gap. Instead, in October Netflix cut its 2026 ad revenue forecast to about $2.7 billion, from about $3 billion. The Wall Street Journal reported last year that Netflix is aiming for $9 billion of ad revenue by 2030, which would now take growth of about 35% a year.
A free Disney+ would make Netflix’s next price increase on the $8.99 plan a harder sell. More Disney ad inventory could also make it harder for Netflix to raise what it charges advertisers.
Netflix’s ads are small, and its stock is cheap
Disney is only exploring a free tier, and it hasn’t said what it would include, where it would launch or when. Netflix is weighing the same idea: co-CEO Greg Peters said in July that a free offering could make sense in some markets, while warning it could cannibalize paid plans.
Ads are also a small slice of Netflix: 5.3% of the $51.1 billion of revenue it forecasts for 2026. The ads plan has reach of its own, passing 250 million monthly active viewers in May by Netflix’s count, up from 190 million in November 2025.
A lot of that worry is already in the price, too. Netflix sits at a one-year low and trades at about 17x forward earnings, roughly half its five-year average of 32x:

The five-year low was about 15.5x, in May 2022.
A ceiling on the $8.99 plan
A free Disney+ could put a ceiling on what Netflix can charge for its ads plan, and that’s the plan Netflix most needs to grow. Still, the market already expects slower growth, and a product Disney hasn’t launched is a thin reason to sell Netflix at about 17x earnings.
Netflix reports in January and will give its 2027 revenue guidance and ad outlook. Analysts expect 2027 revenue of $56.6 billion, up about 11%. A guide below that, or another cut to the ad forecast, would show the pressure is real. The fourth quarter is also Netflix’s biggest live quarter yet, and that should show up in its ad revenue.
So what is Netflix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Netflix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


