Key Takeaways
- Dell stock fell 16% in the past week as AI hardware sold off after Jensen Huang resigned as Nvidia’s CEO, and Super Micro and CoreWeave fell too.
- Steve Eisman warns Dell will slow along with Nvidia, but Cisco just raised its AI forecast and analysts have raised Dell’s earnings estimates slightly.
- Dell’s bigger exposure is the money it lends to customers: its lowest-grade financing receivables more than doubled to $4.4 billion in six months.
- Dell trades below its usual forward multiple, but its Nov. 24 report needs to show free cash flow catching up with profits before the stock looks like a buy.
Dell Technologies (DELL) is down 16% in the past week, and almost none of the news behind the drop was Dell’s own. Nvidia (NVDA) announced Jensen Huang’s resignation as CEO on Nov. 12, and AI hardware sold off with it: Nvidia fell 13%, Super Micro Computer (SMCI) 20% and CoreWeave (CRWV) 21%.
Steve Eisman, host of The Real Eisman Playbook podcast, thinks the damage will spread. “The picks and shovels companies like Arista, Cisco and Dell will also slow along with NVIDIA, proportionate to the slowdown in data center build out,” he said on his Nov. 13 episode. But the day before, Cisco (CSCO) had raised its forecast for this fiscal year’s AI infrastructure revenue from hyperscalers to $9 billion, more than double last year’s total.
Dell got pulled into Nvidia’s mess
Dell did get one headline of its own. Before the open on Nov. 13, a report traced banned Nvidia H800 chips to a Shanghai data center. Documents showed that Singapore’s Aperia Cloud Services had bought 22 Dell servers carrying them. Dell had already cut off Aperia in February 2025, so that’s old news. On Nov. 16, Morgan Stanley cut its target to $403 from $511 and Citi cut its target to $550 from $600, and both kept their ratings. A day later, Bernstein held its $650 target. Nvidia’s stronger-than-expected report on Nov. 17 lifted Dell before the next day’s open, but the gain faded as the broader market fell.
TIKR tracks 29 analysts on Dell Technologies. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Dell Technologies, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Dell Technologies’ Analyst Ratings
No slowdown in the numbers yet
Super Micro, which competes with Dell for the same Nvidia rack orders, isn’t seeing a slowdown either. Its September-quarter sales hit $19.9 billion, up from $5.0 billion a year earlier. It now guides to $72 billion to $82 billion for its fiscal year ending June 2027. Analysts have also raised their normalized EPS estimates for Dell a little this month, to $26.01 for the year ending January 2027 and $30.65 for the year after:
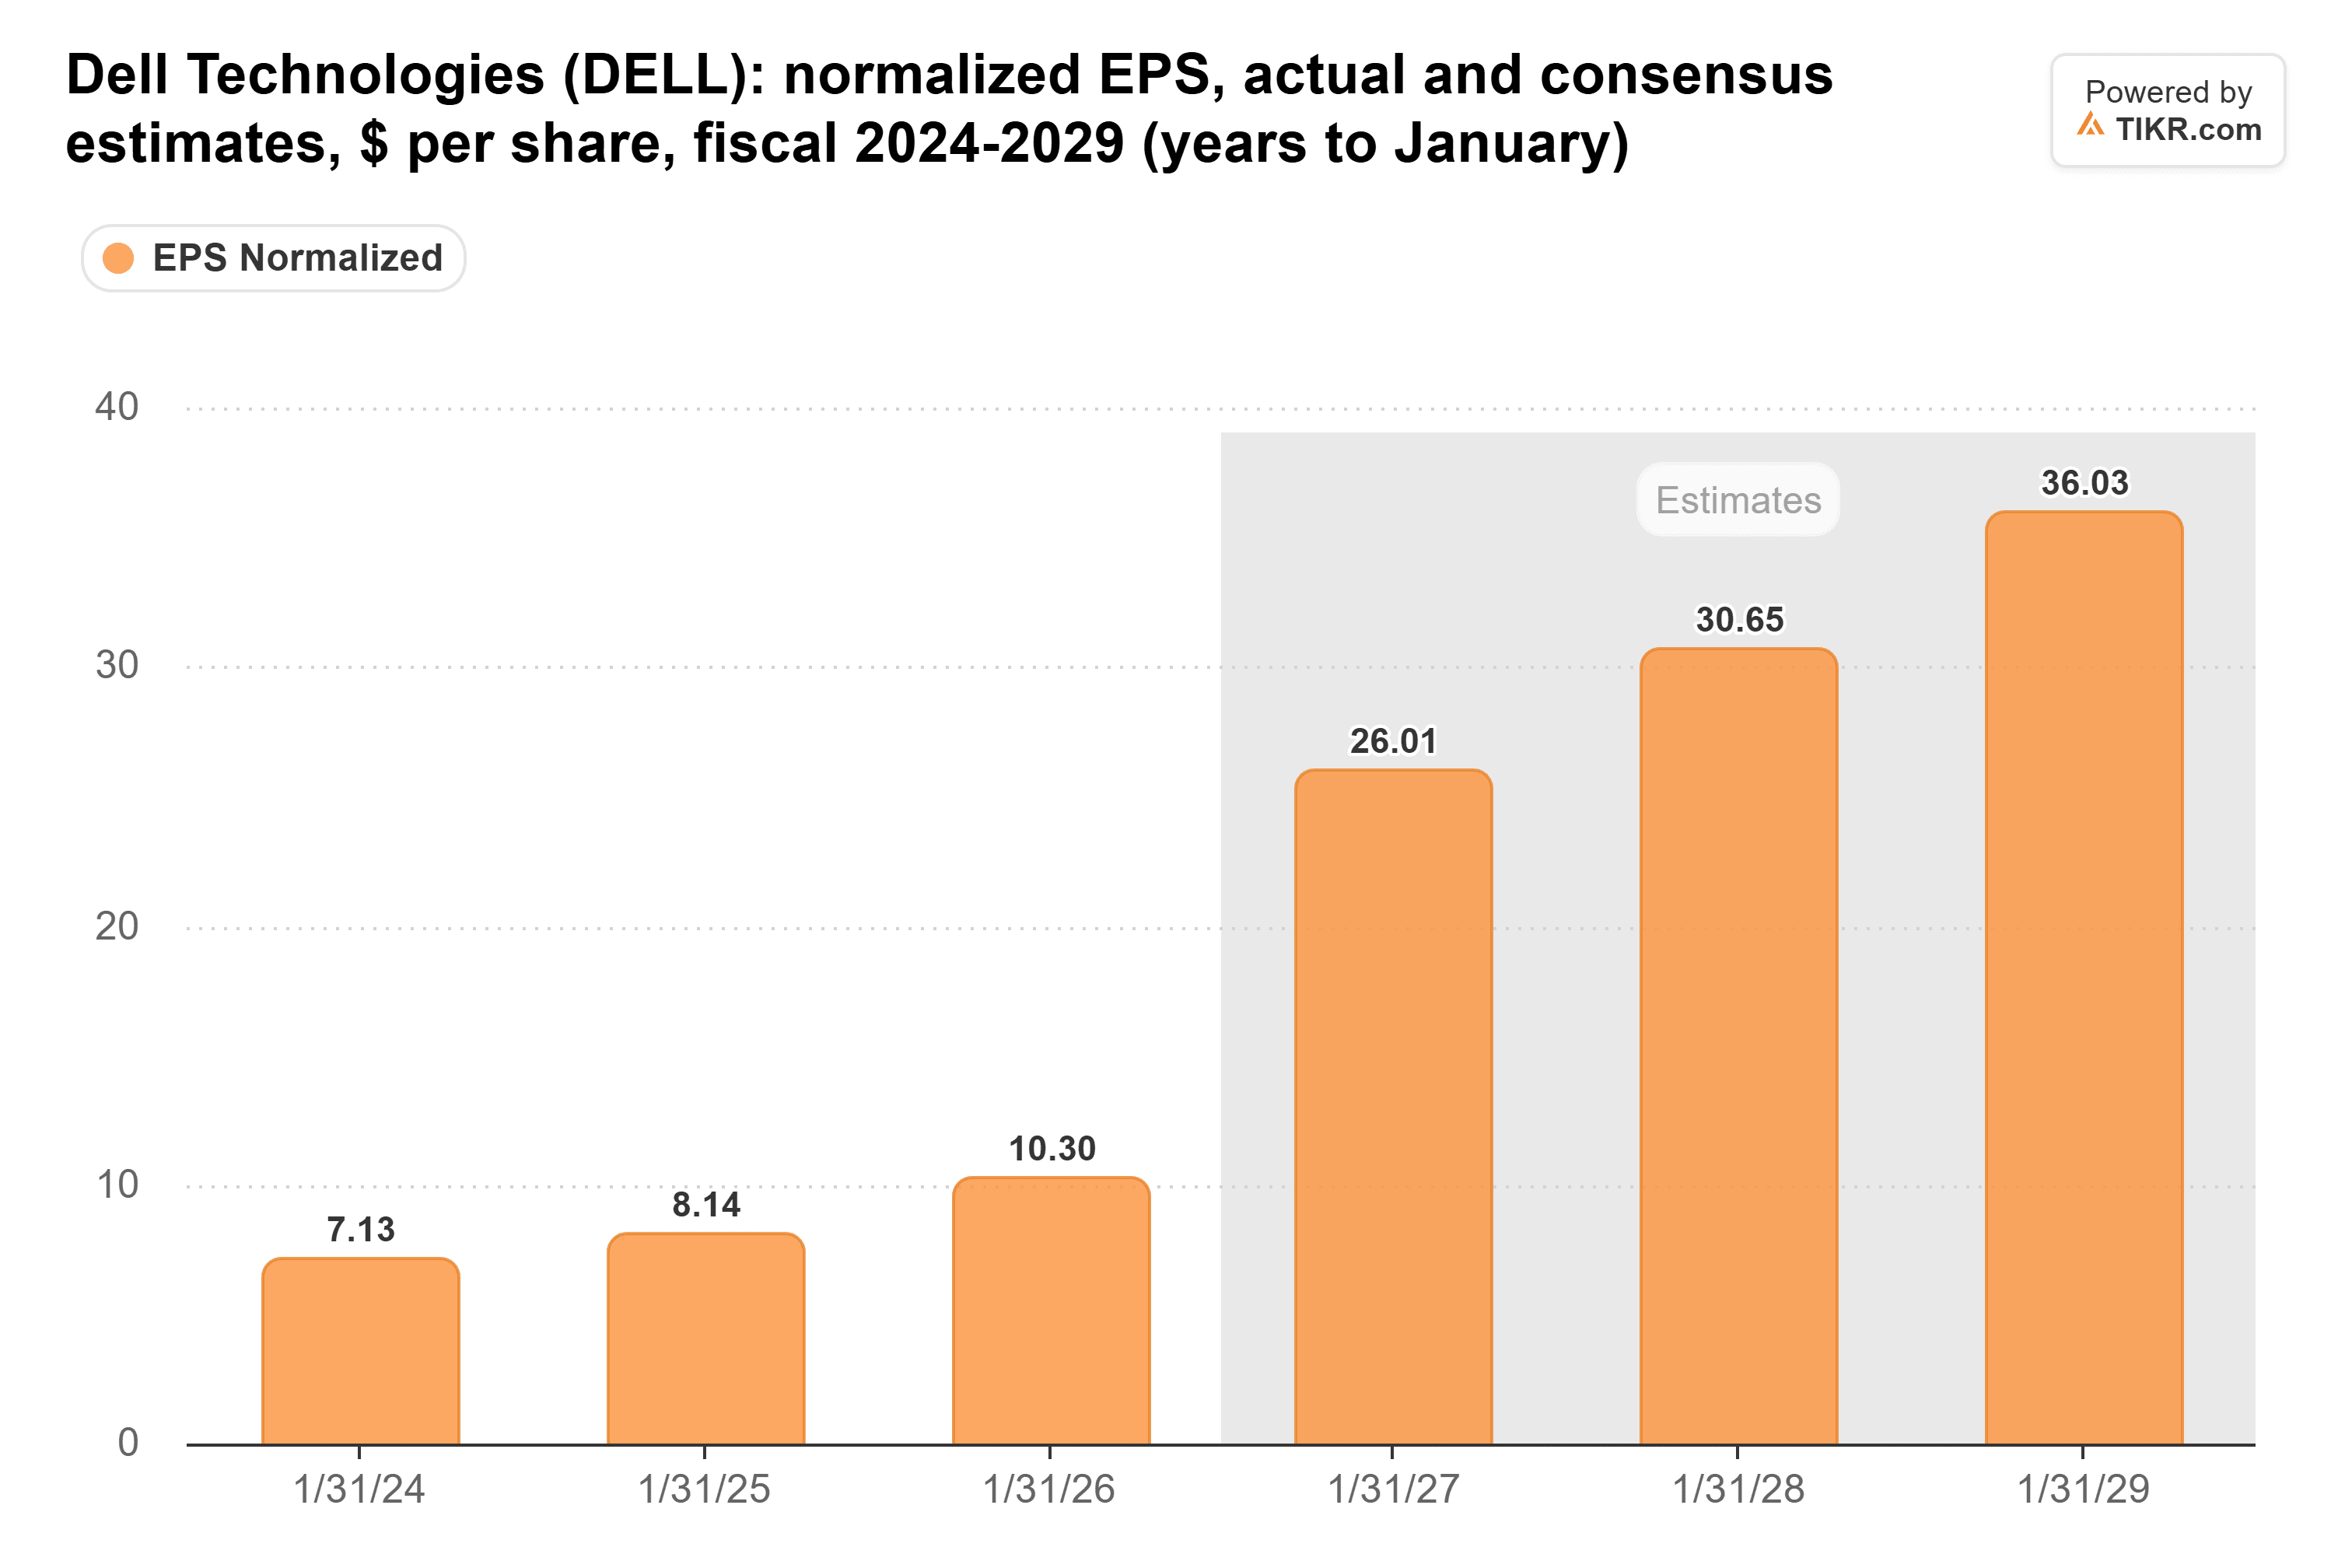
That’s 18% growth, so the whole drop came out of the stock’s multiple.
Dell’s loans are the soft spot
If Eisman turns out to be right, the money Dell lends its customers worries me most. Dell’s financing receivables, the loans it makes to customers buying its gear, rose to $20.4 billion at July 31 from $14.3 billion in January. Loans in its lowest credit grade more than doubled to $4.4 billion over those six months, and the Fed’s Nov. 13 Financial Stability Report flagged “circular financing” in the AI trade. CoreWeave, one of the big AI customers Dell has said it builds clusters for, is still losing money: its third-quarter net loss widened to $709 million from $110 million a year earlier. Meanwhile, Dell’s first-half free cash flow was flat at $4.1 billion while its GAAP net income more than tripled to $7.6 billion.
Cheap, but I want to see the cash
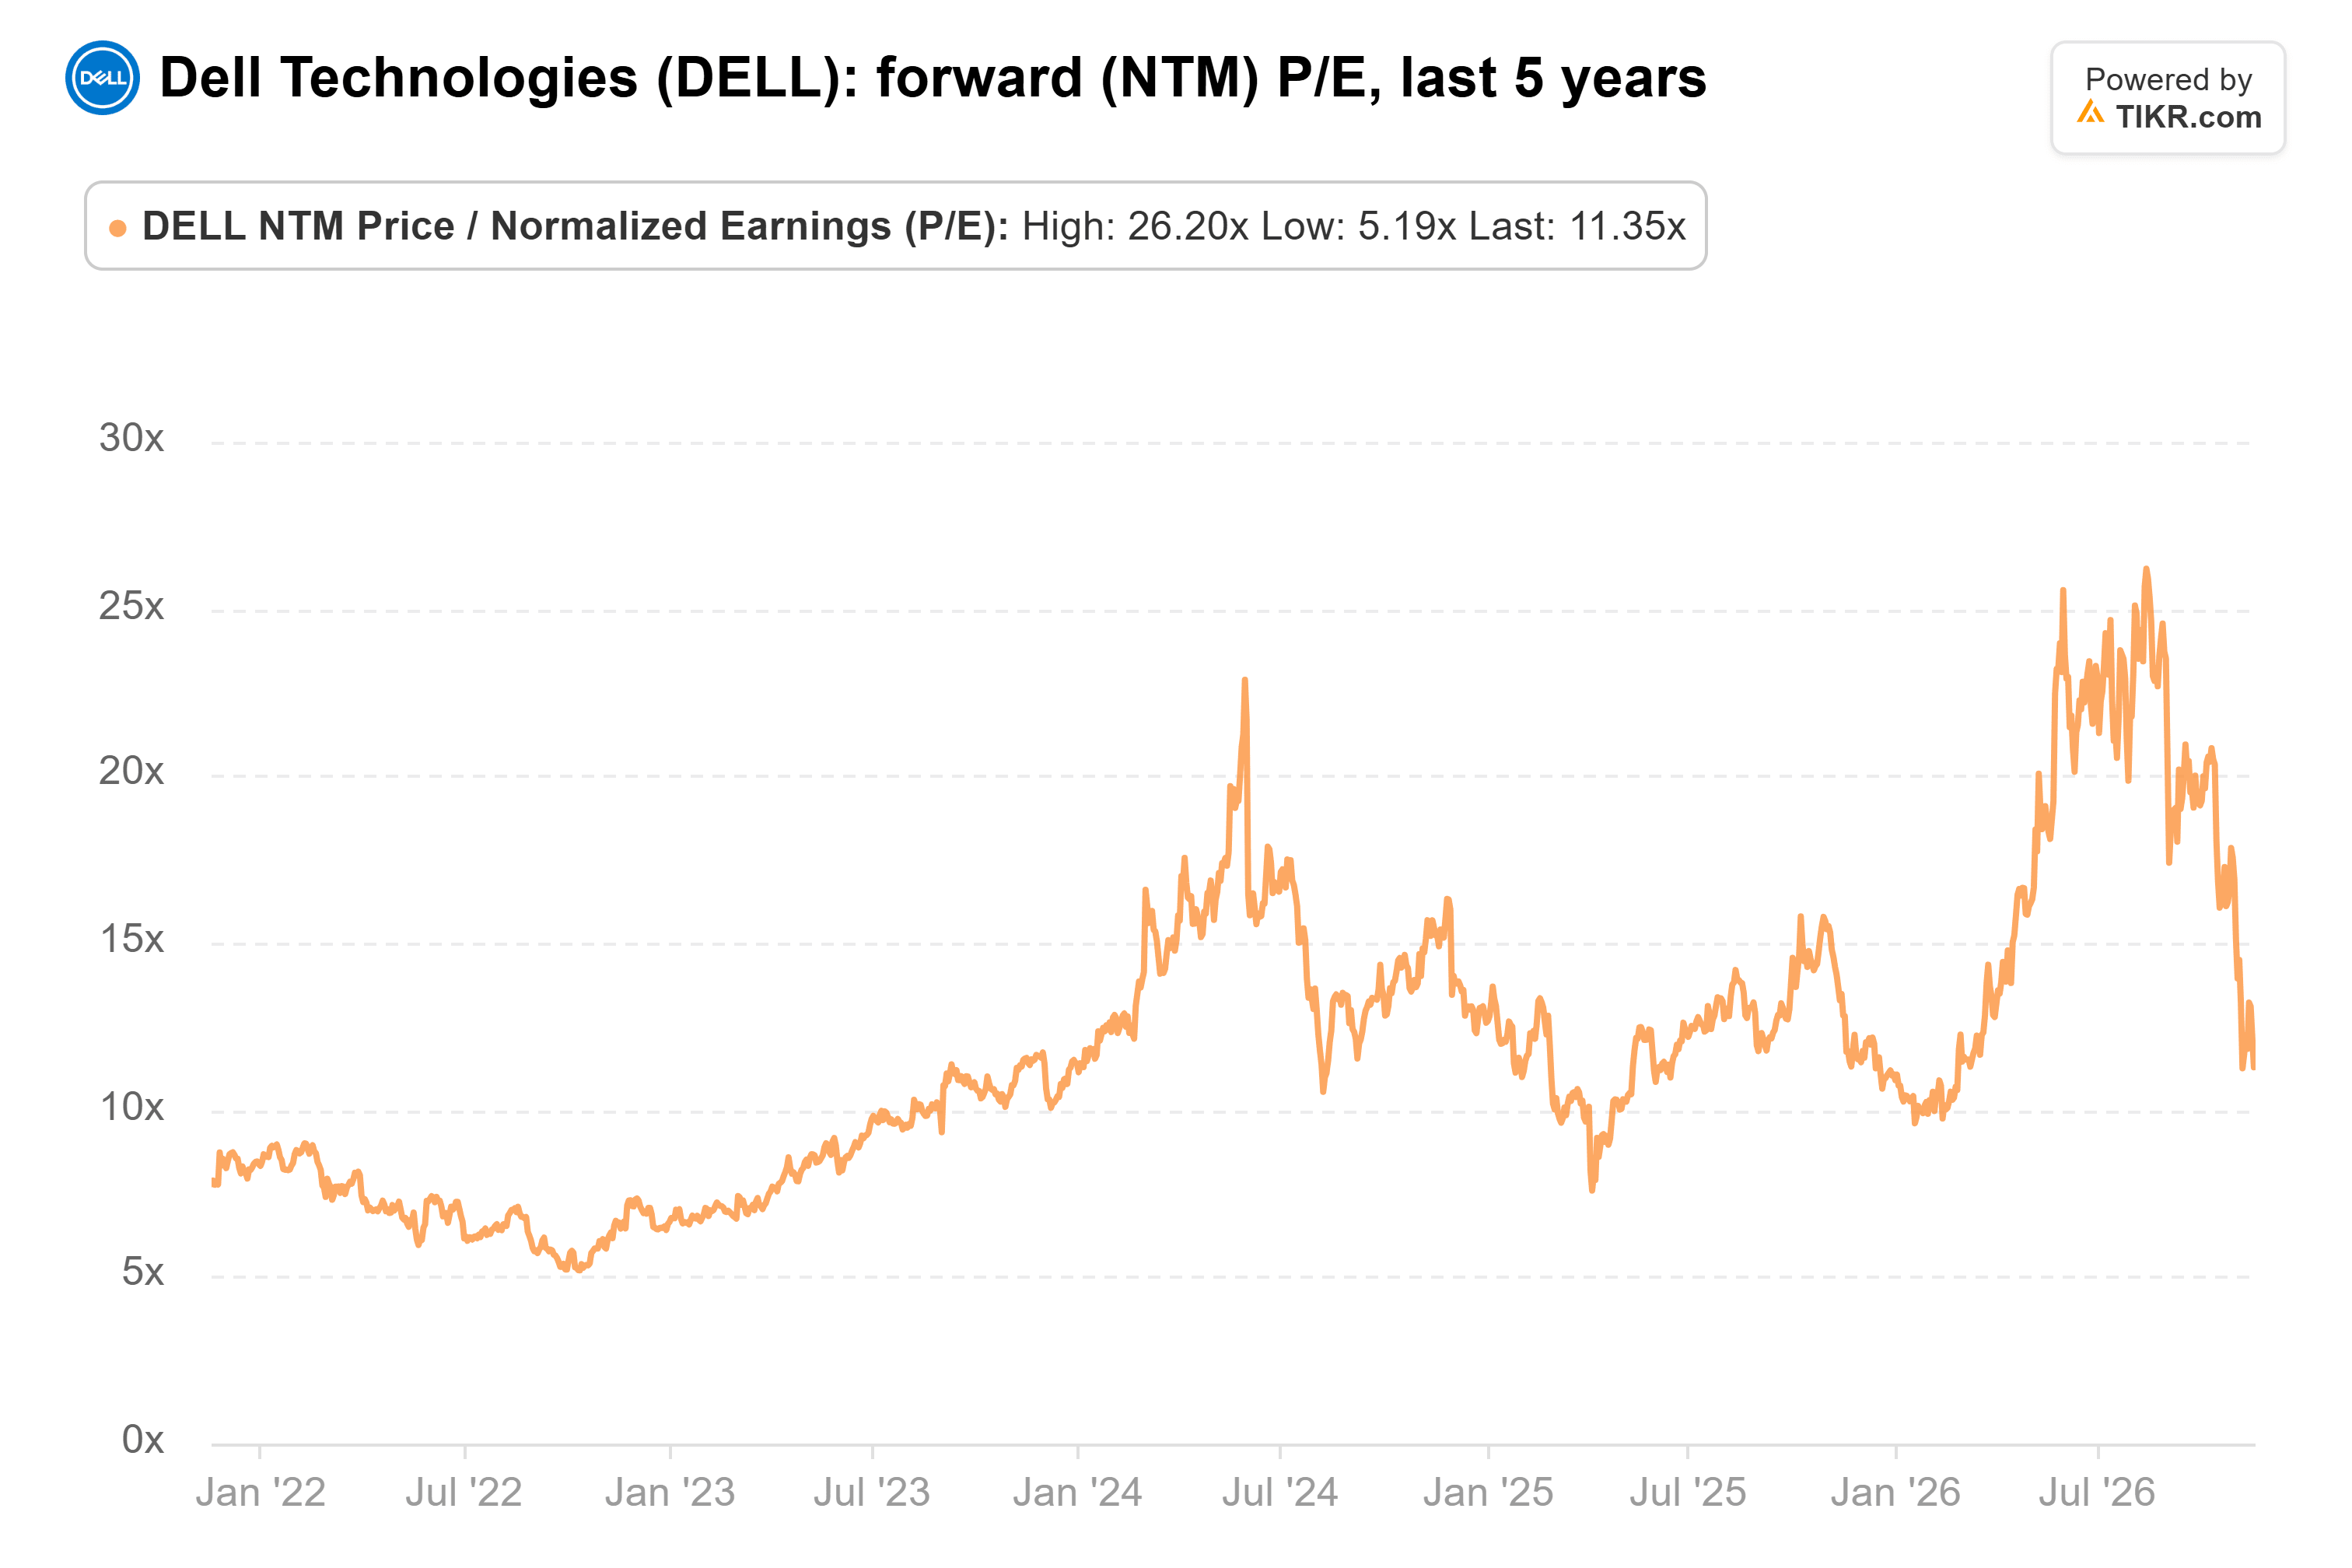
Dell trades at about 11x forward earnings. That’s below its five-year average of 12x and less than half the 26x it hit in August:
Dell reports on Nov. 24, with its call at 3:30 p.m. Central. It has guided to $19 billion of AI server revenue for the quarter. Beyond that, I want to see three things: free cash flow catching up with net income, a loan-loss provision under the last quarter’s $122 million, and lower-grade receivables holding near $4.4 billion.
I’d wait for that report before buying. At 11x, Dell is priced for a slowdown that Cisco’s and Super Micro’s numbers don’t show. But if Dell keeps lending out more of its profit to customers, a cheap stock can stay cheap.
So what is Dell stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Dell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!