Key Takeaways
- Datadog fell more than 12% on Nov. 4 on a flat fourth-quarter guide, as its largest customer, an AI company, cuts its usage to its contract minimum.
- Analysts still raised their 2027 normalized EPS estimate to $3.16 from $2.98, so the whole fall came from a lower multiple.
- Cloudflare’s higher fourth-quarter guide points to a problem limited to Datadog, and Snowflake reports next, on Dec. 2.
- The rising 2027 estimate outweighs the flat quarter, though February’s 2027 outlook could pull estimates back down.
Datadog (DDOG) fell more than 12% on Nov. 4, the day it guided fourth-quarter revenue to $1.19 billion to $1.20 billion. That’s flat with the $1.20 billion it had just reported for the third quarter.
But analysts came out of the same report expecting Datadog to earn more in 2027.
On a Nov. 17 episode of the RiskReversal Pod, RBC Capital Markets software analyst Matthew Hedberg put Datadog in a small group: “I have seen clear AI leadership from five or six names that I cover where there’s real acceleration like a Datadog or a Cloudflare or CrowdStrike or a Palo Alto and a Snowflake.” So Cloudflare (NET) and Snowflake (SNOW) holders need to know whether one AI customer’s cutback stops at Datadog.
One customer, one flat quarter
Third-quarter revenue rose 35%. The trouble is Datadog’s largest customer, an unnamed AI company, which is cutting its usage. The fourth-quarter guide counts it only at its minimum commitment, for growth of 25% to 26%, or the low to mid-30s percent without that customer.
Anything it spends above that floor is revenue the guide doesn’t count, and CFO David Obstler said it still spent above its minimum in the third quarter. Outside AI, growth is in the high 20s, the fifth straight quarter it has sped up.
TIKR tracks 49 analysts on Datadog. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Datadog, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Datadog’s Analyst Ratings
Investors are paying far less for higher earnings
Analysts raised their estimates anyway. Consensus normalized EPS for 2027 rose to $3.16 from $2.98, about 6%, and has edged up to $3.18 since. The estimates for this year and 2028 are higher too:

With higher earnings expected, all of the fall came out of the forward multiple. Datadog trades at about 56x forward earnings, down from 103x at the end of September:

That’s not far above February’s low of 47x, and well below the 76x Datadog has averaged at quarter-ends since late 2022.
The rest of the AI crowd is still speeding up
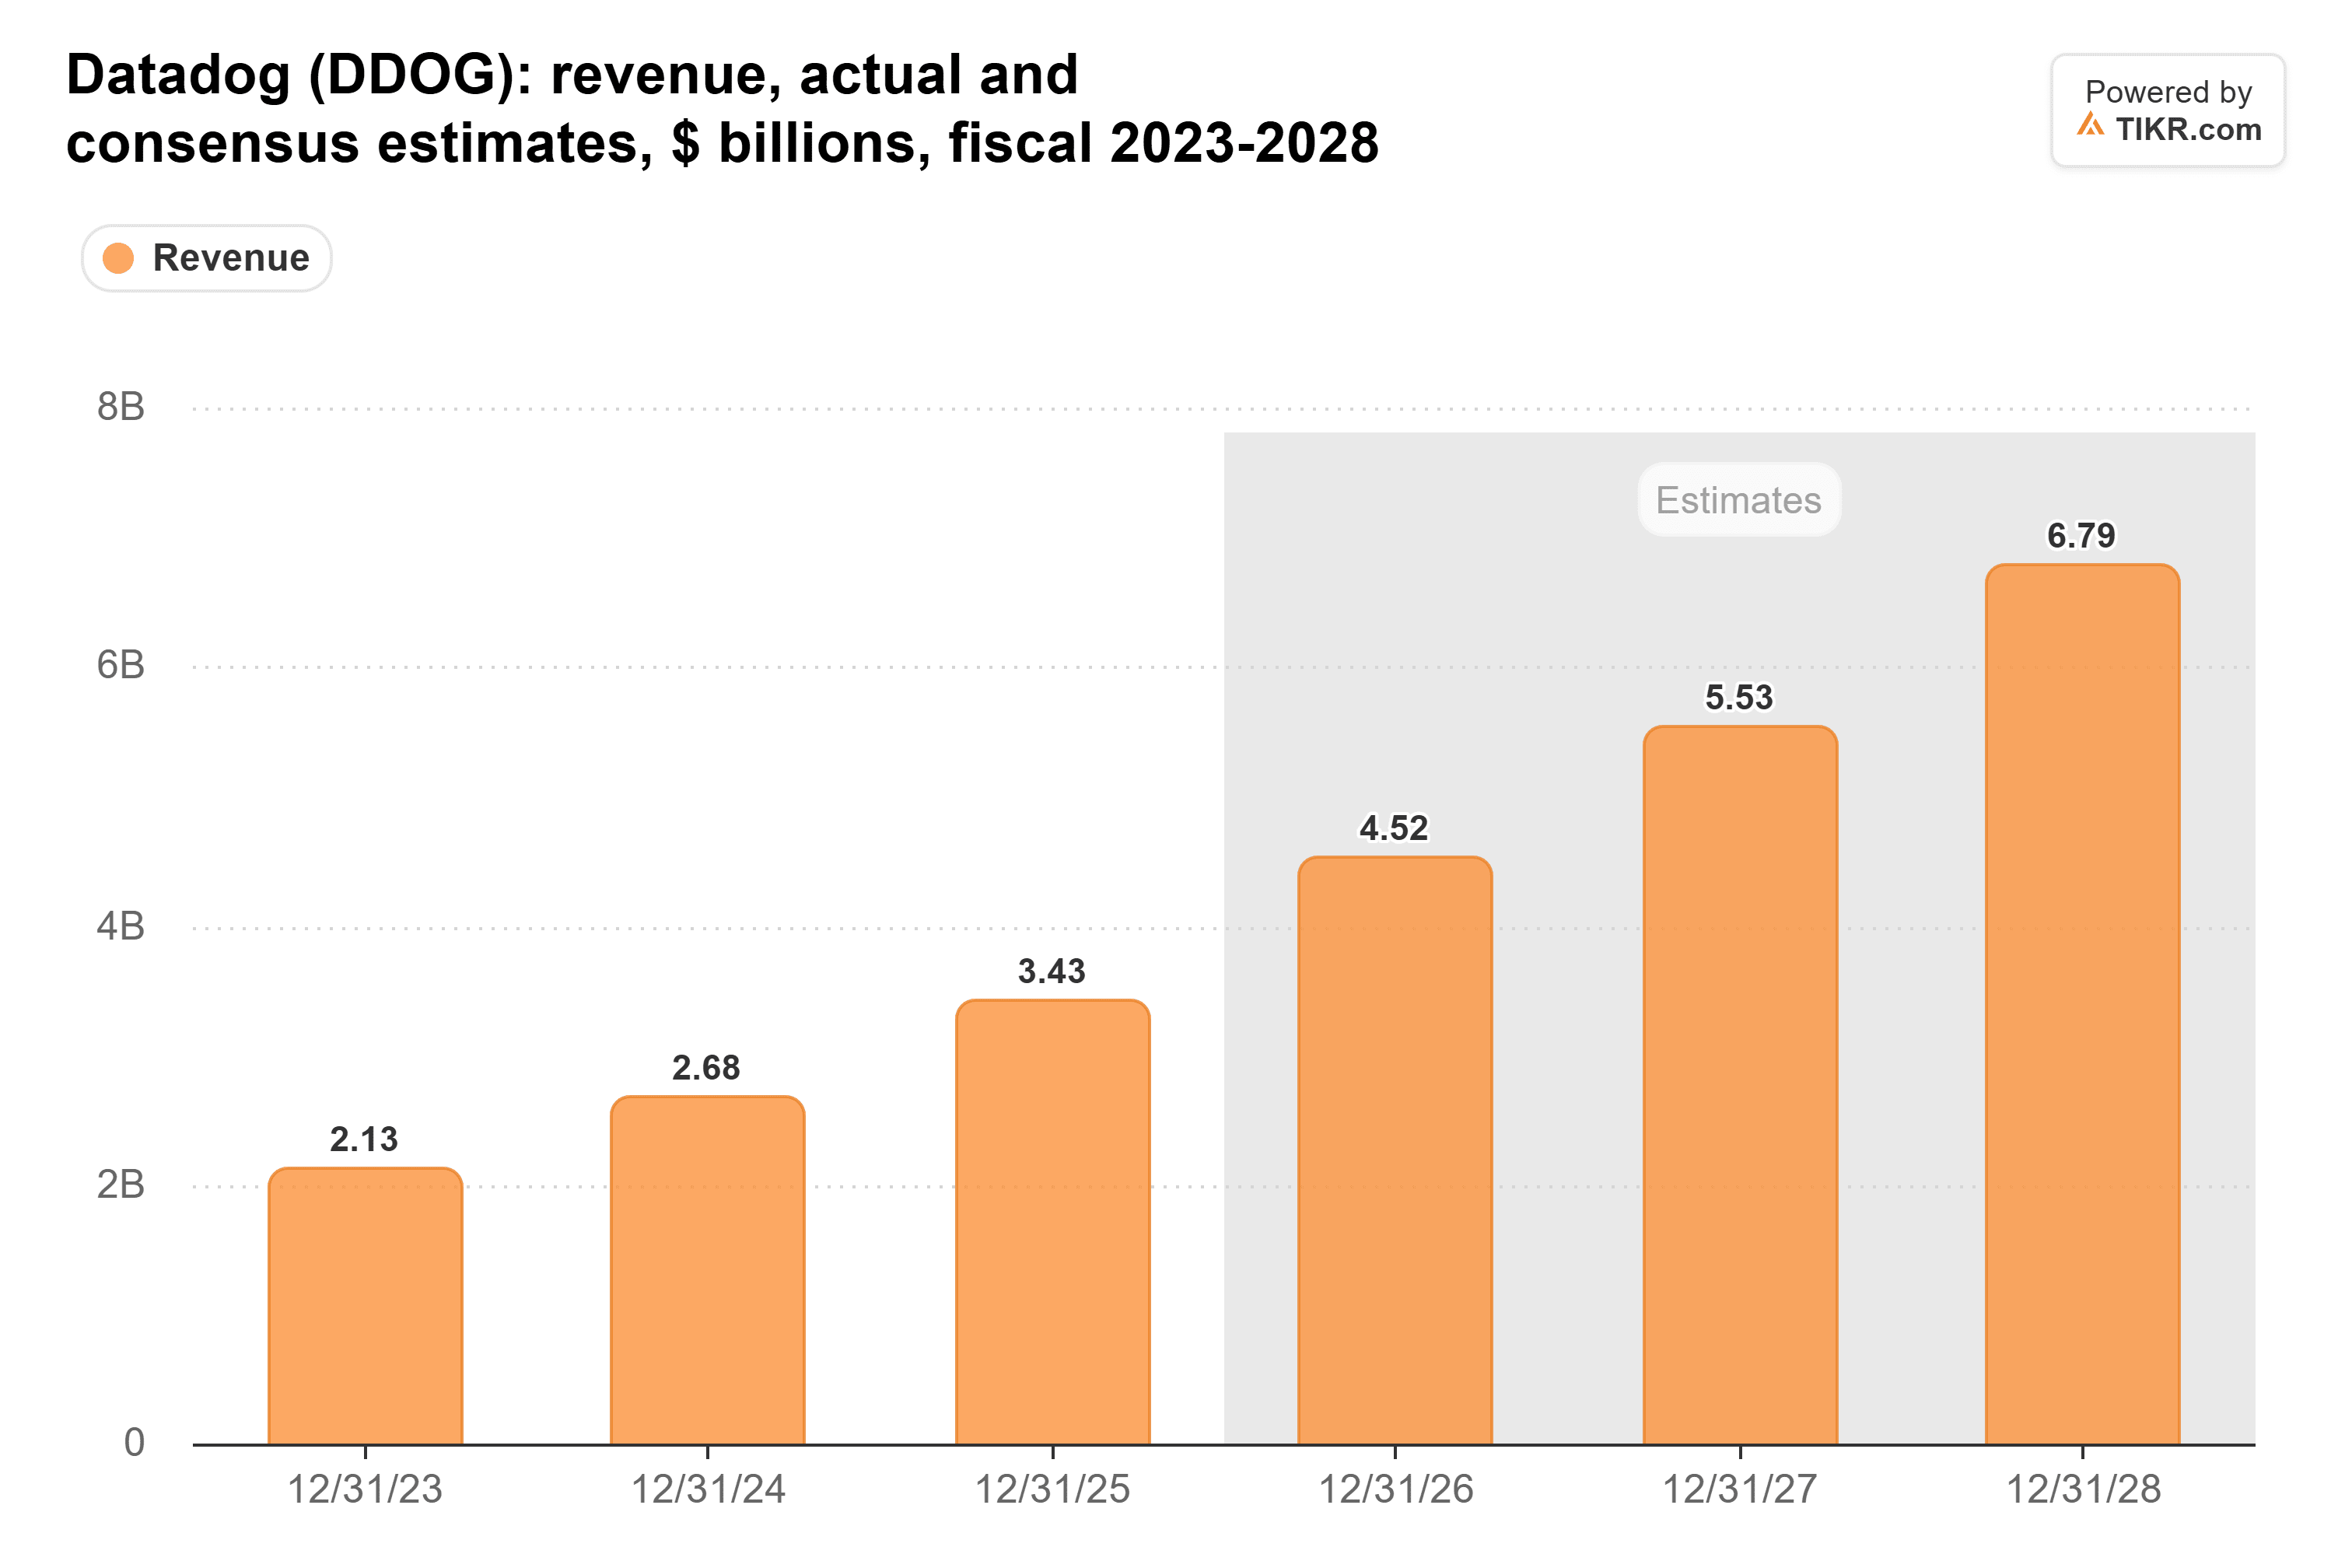
Analysts still expect revenue to grow about 22% to 23% a year in 2027 and 2028, after about 32% this year:
Cloudflare’s report the next day points the same way: third-quarter revenue rose 39% to $782.5 million, and it guided the fourth quarter to $845 million to $846 million, another step up. A broad pullback by AI buyers would likely have hit it too.
Snowflake reports next, on Dec. 2, after product revenue rose 37% in its quarter ended July 31. Product revenue near the $1.59 billion top of its guide would suggest AI customers are still buying across vendors, while a miss would make Datadog’s cutback look like the start of a wider trend.
The catch is in the adjusted numbers
Normalized EPS leaves out stock pay, which equaled 21.9% of Datadog’s 2025 revenue. It also includes interest on $5.2 billion of cash and securities, and management guided to about $180 million of net interest and other income for 2026, worth roughly $0.38 a share. A big acquisition would shrink that part of earnings. And the fourth-quarter guide cuts the adjusted operating margin to about 24% from 28%.
The way I see it, the rising 2027 estimate deserves more weight than one flat quarter, since the rest of the business keeps speeding up.
The real test comes in February, with Datadog’s first 2027 outlook. It needs to support the $5.53 billion of 2027 revenue analysts expect, about 22% growth, with the adjusted operating margin back above 24%. A guide well short of that would mean the market was right to sell first.
So what is Datadog stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Datadog could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!