Key Takeaways
- Dan Loeb’s Third Point made Meta Platforms its largest US stock holding in the third quarter, with a new stake worth $475 million at Sept. 30.
- Meta has fallen 15% since then, after its third-quarter capital spending ran ahead of the cash its business brought in.
- Meta trades at 19x forward earnings, below its 21x five-year average, and analysts’ $848 average target is about 20x their 2028 earnings estimate.
- Meta’s earnings outlook and valuation support Loeb’s bet, and the next test is the 2027 spending plan Meta gives in late January.
Dan Loeb has a new No. 1 stock, and it’s Meta Platforms (META).
Third Point’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows a new stake of 655,000 shares worth $475 million at quarter-end prices. That’s 10.5% of the $4.54 billion of US stocks in its 13F. It sits ahead of two other new positions, Unum and NVIDIA, at a firm that manages $28.73 billion in all.
A rough stretch since Sept. 30
Meta has fallen 15% from its Sept. 30 price and is 21% below its 52-week high. That’s the stock’s move from quarter-end. The filing doesn’t show what Third Point paid, or whether it still holds every share. Since then, Meta has given investors a few reasons to worry. Third-quarter revenue grew 26% to $64.6 billion. But capital spending of $34.9 billion was more than the $32.8 billion of cash its operations brought in, so free cash flow turned negative. On Oct. 21, a New Mexico court also ordered Meta to pay a $25 billion penalty in one of its youth lawsuits, and Meta plans to appeal.
TIKR tracks 62 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
The ad business is still doing the heavy lifting
Meta’s ad business is still growing fast. In the third quarter, price per ad rose 14% and ad impressions rose 10%. Management guides fourth-quarter revenue to $73 billion to $76 billion, 22% to 27% above a year earlier. It also credits upgrades to its ad-ranking models for conversion gains of 1.4% to 9.6% across different campaign types, and those models run on the compute Meta is buying.
Analysts expect normalized EPS to stall this year as costs climb, then grow again in 2027 and 2028:
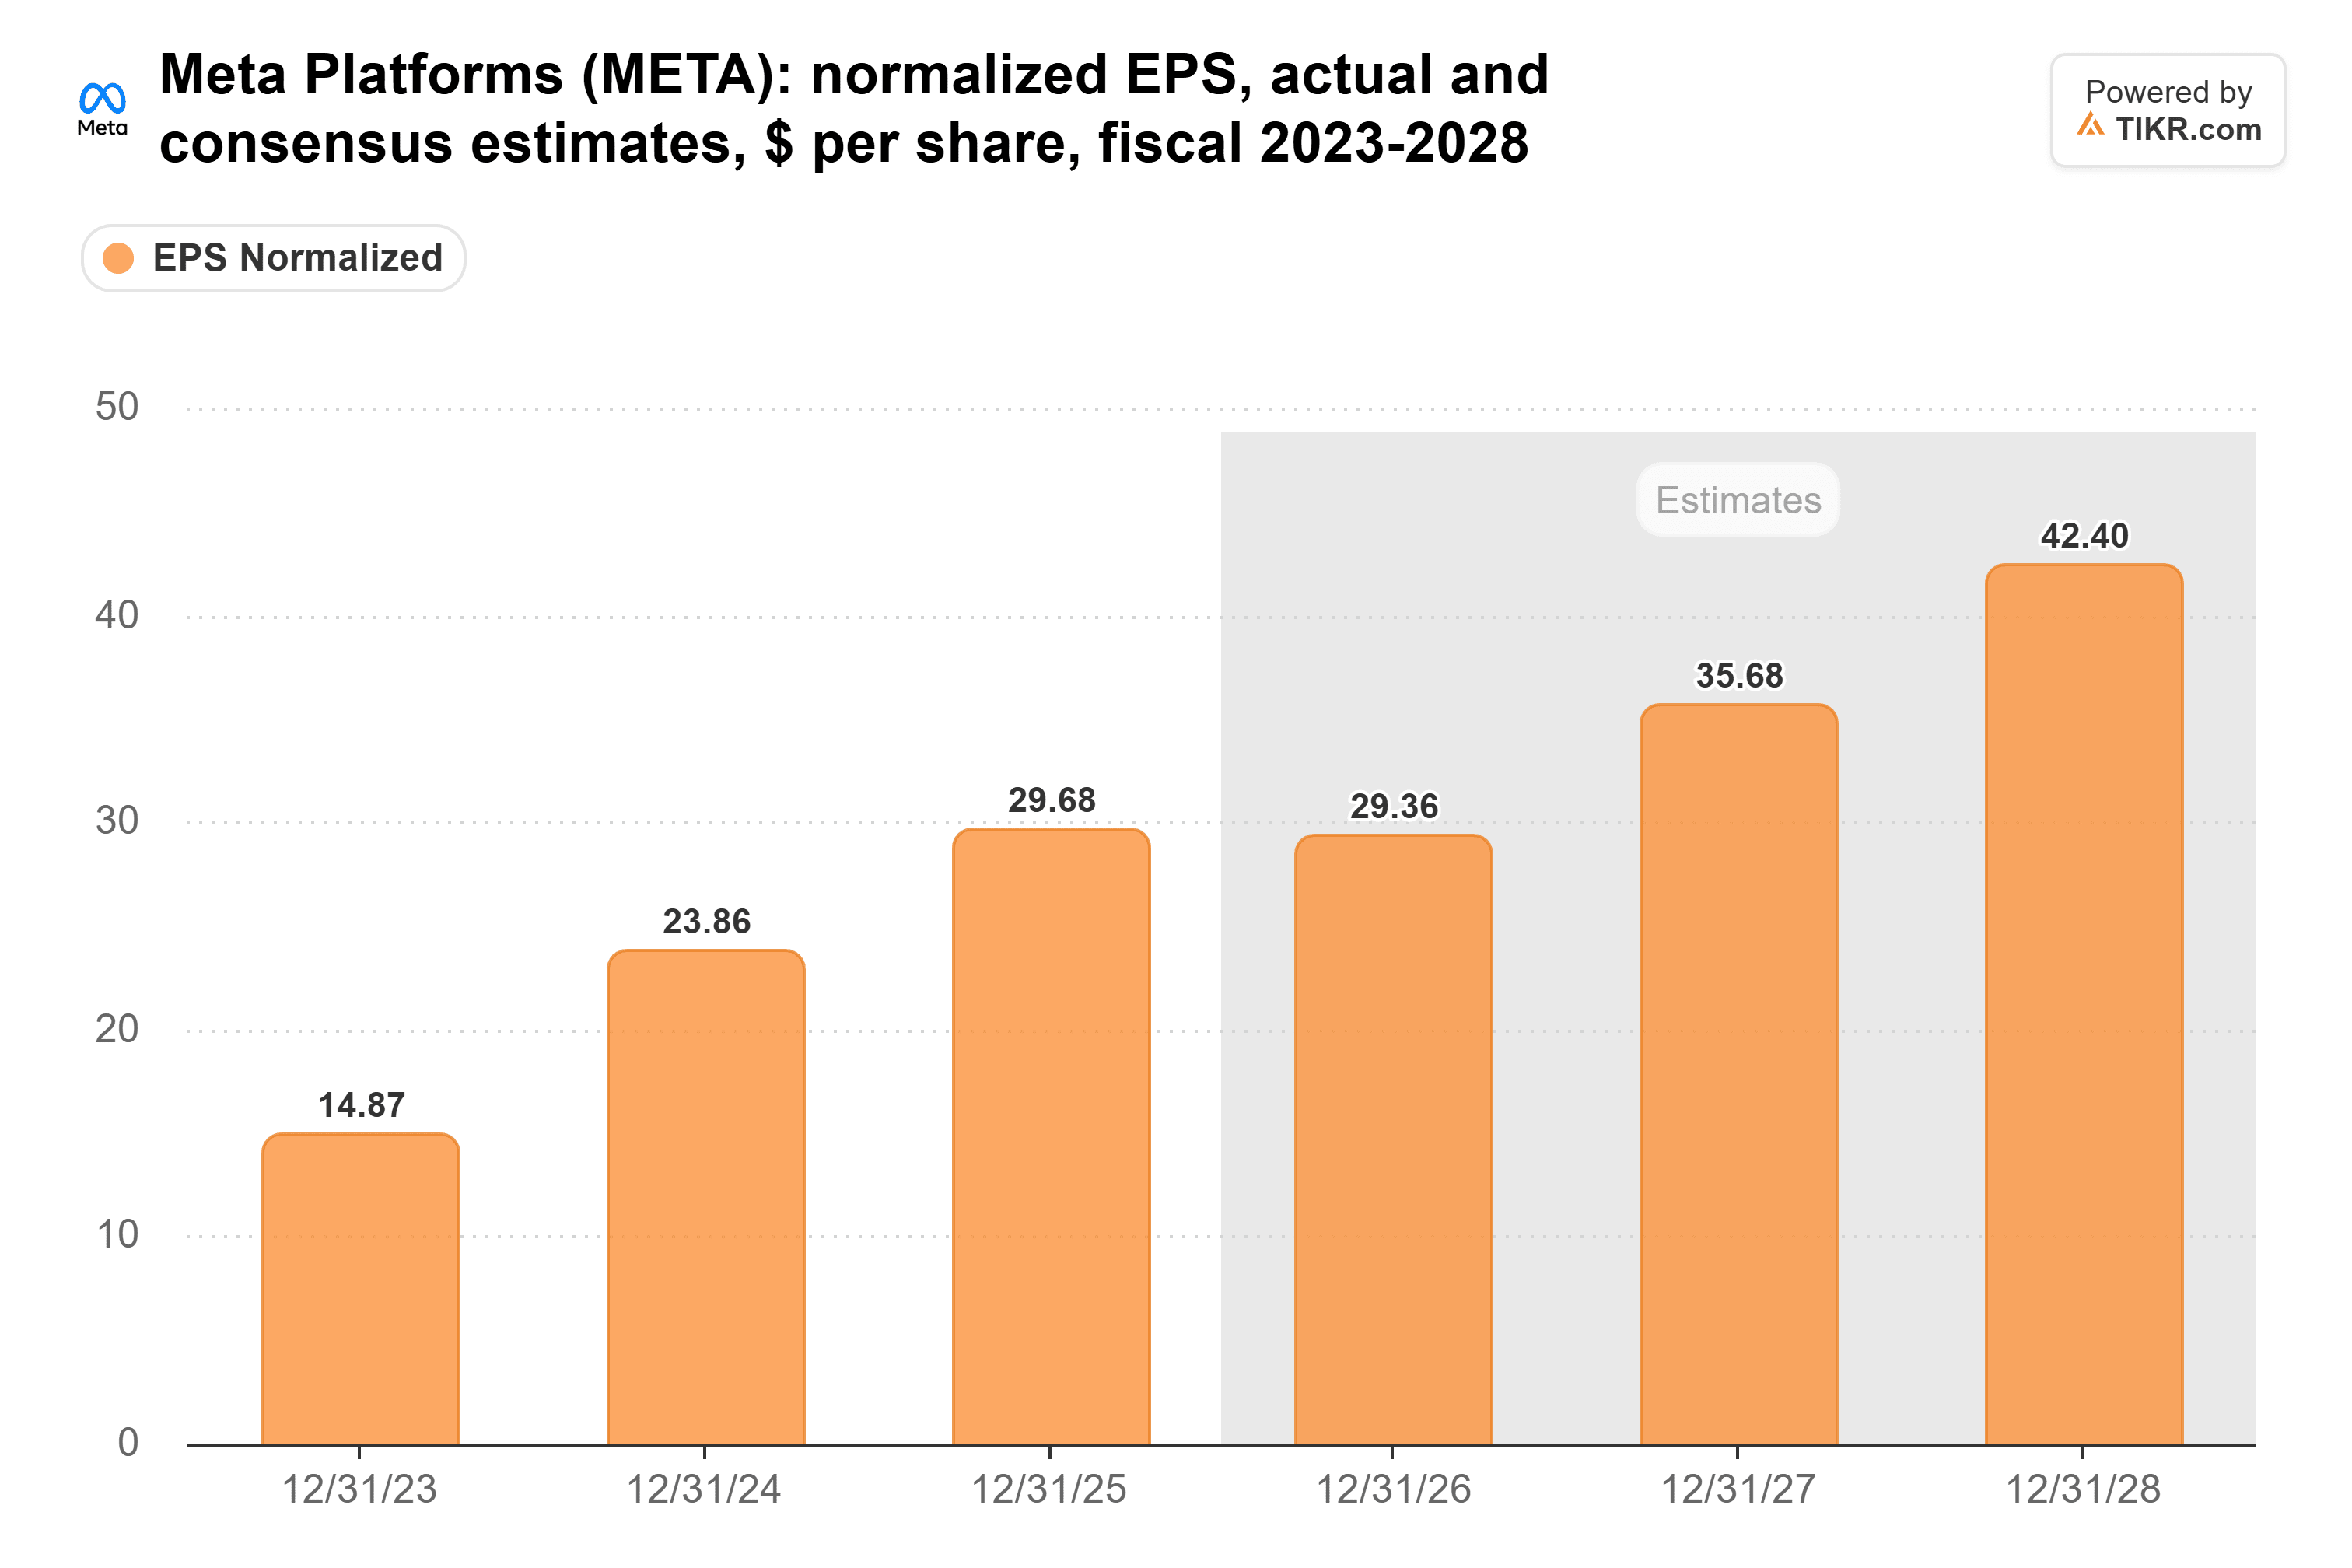
If the estimates hold, earnings go from $29.36 in 2026 to $42.40 in 2028, which works out to about 20% a year.
Wall Street’s target doesn’t need a richer multiple
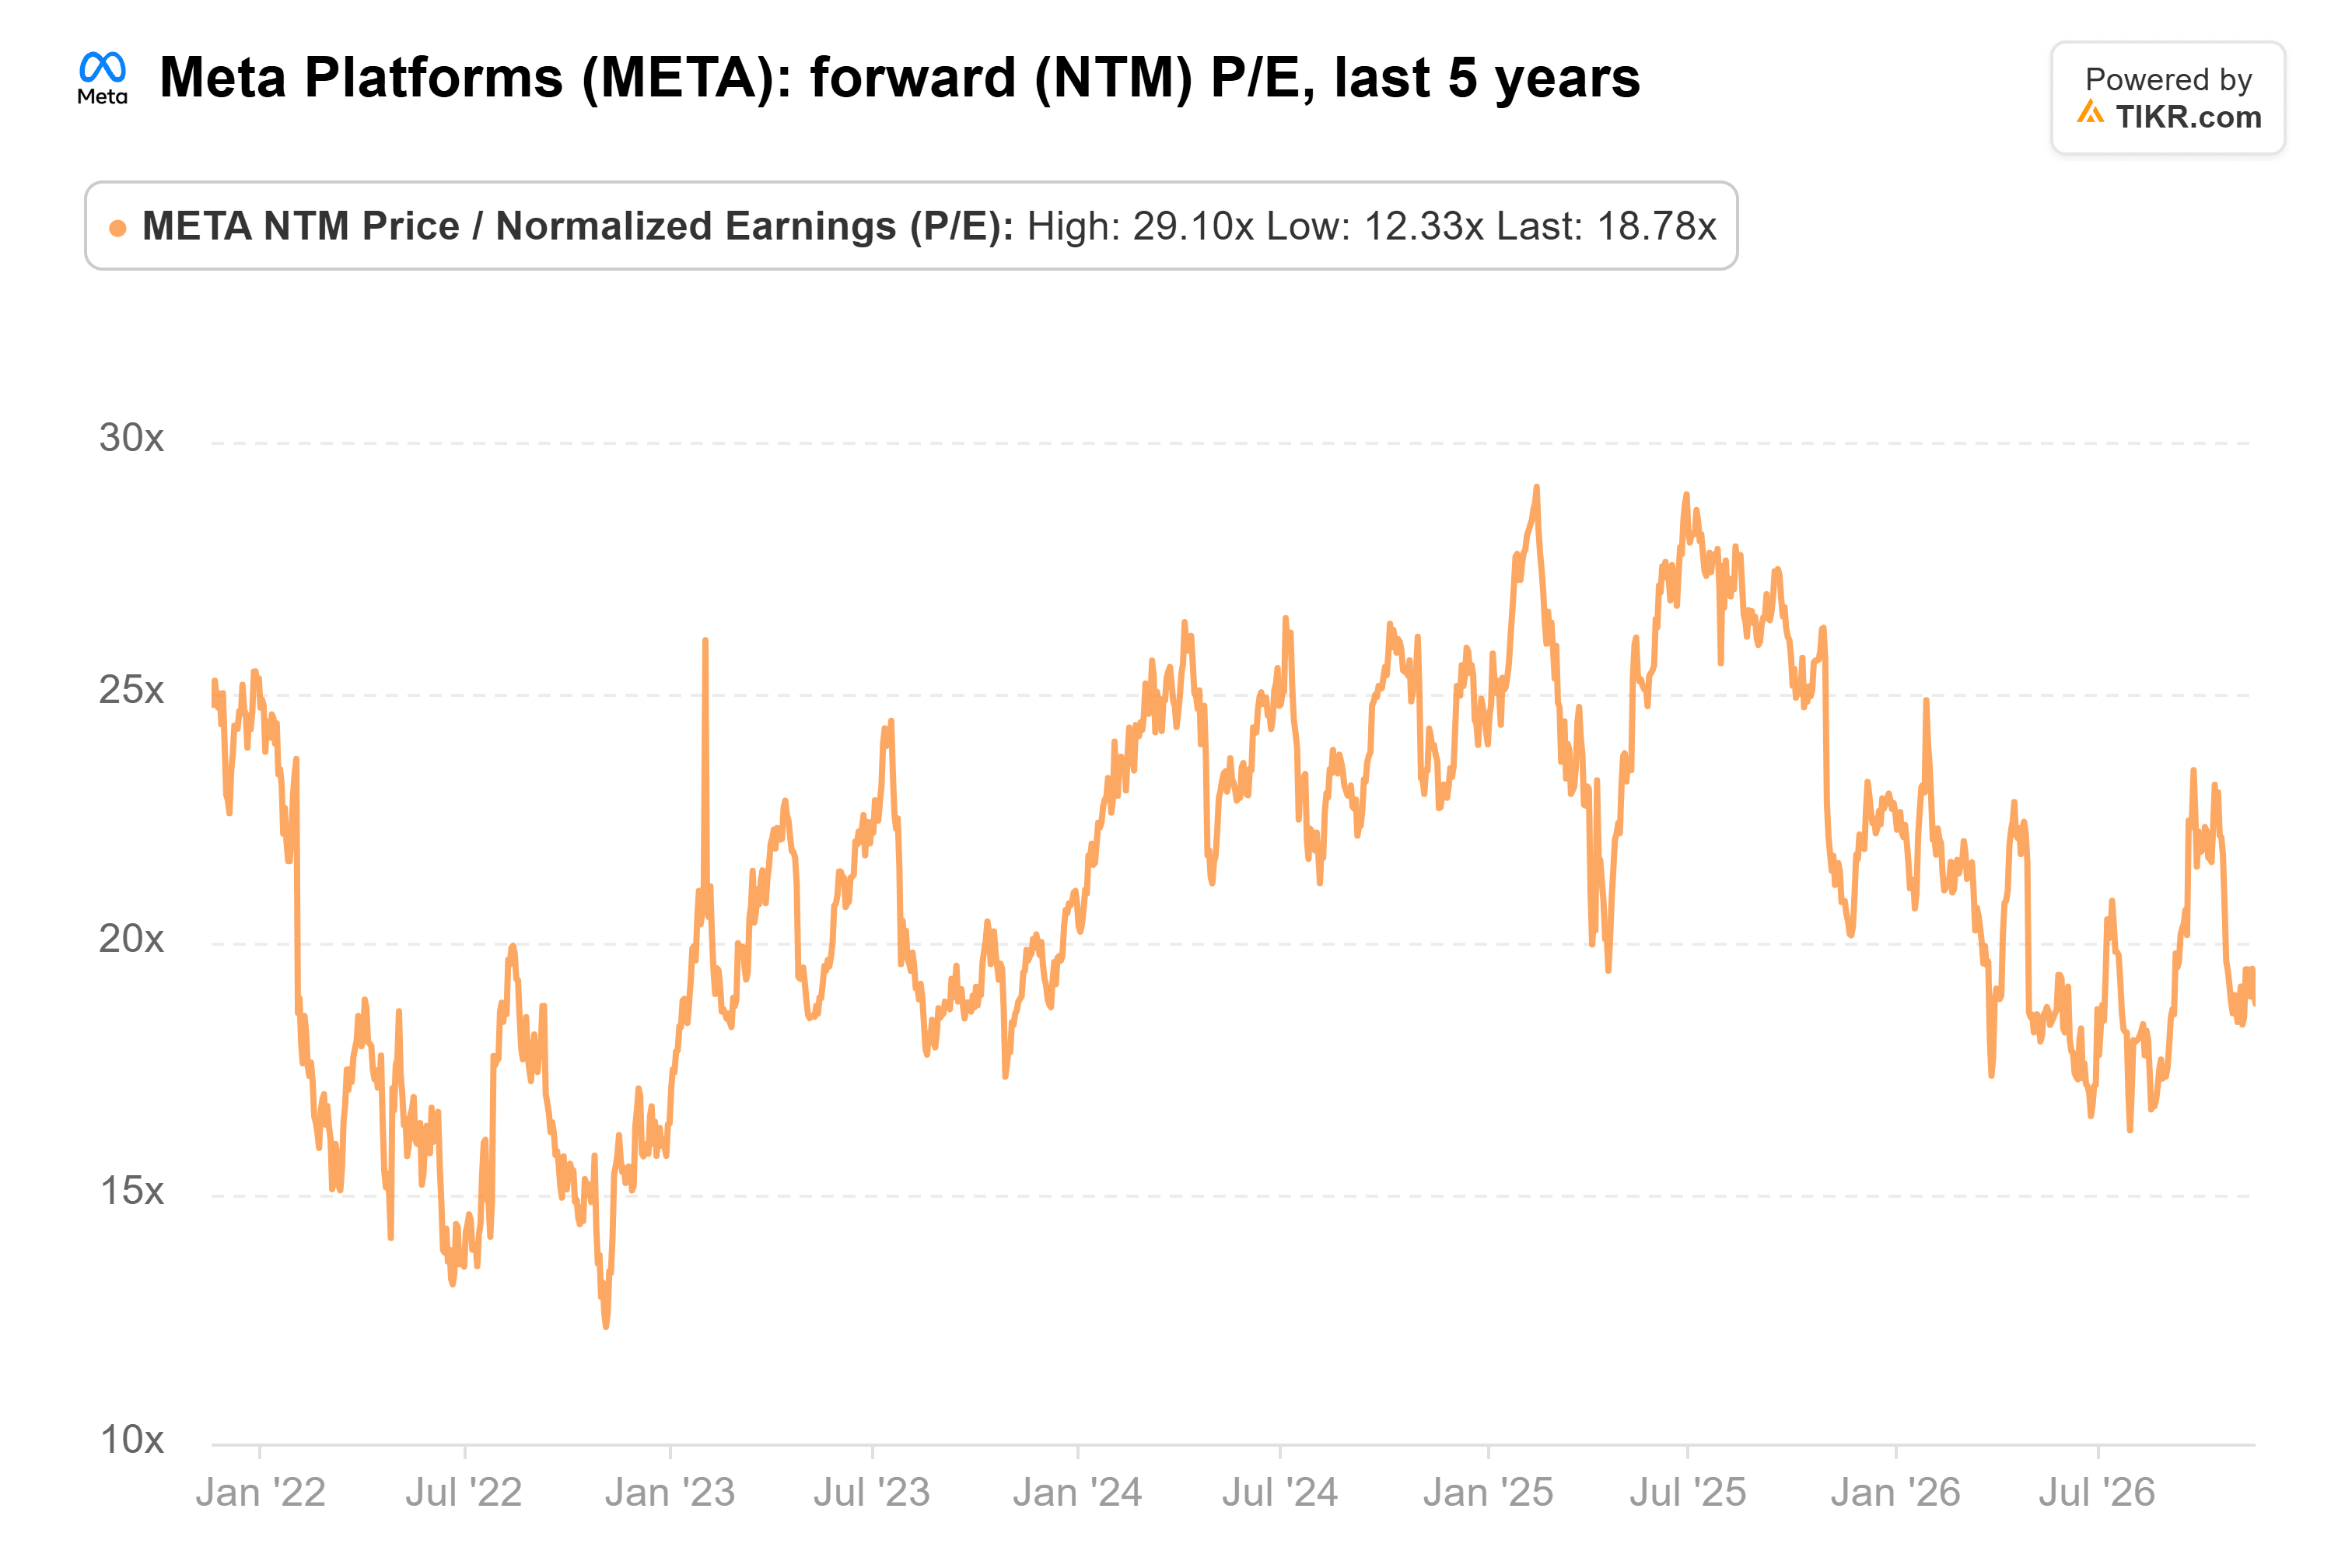
Meta trades at 19x forward earnings, below its 21x average over the past five years:
The 62 analysts’ average target has stayed between $754 and $864 over the past year. At $848, it’s 37% above Meta’s latest close:
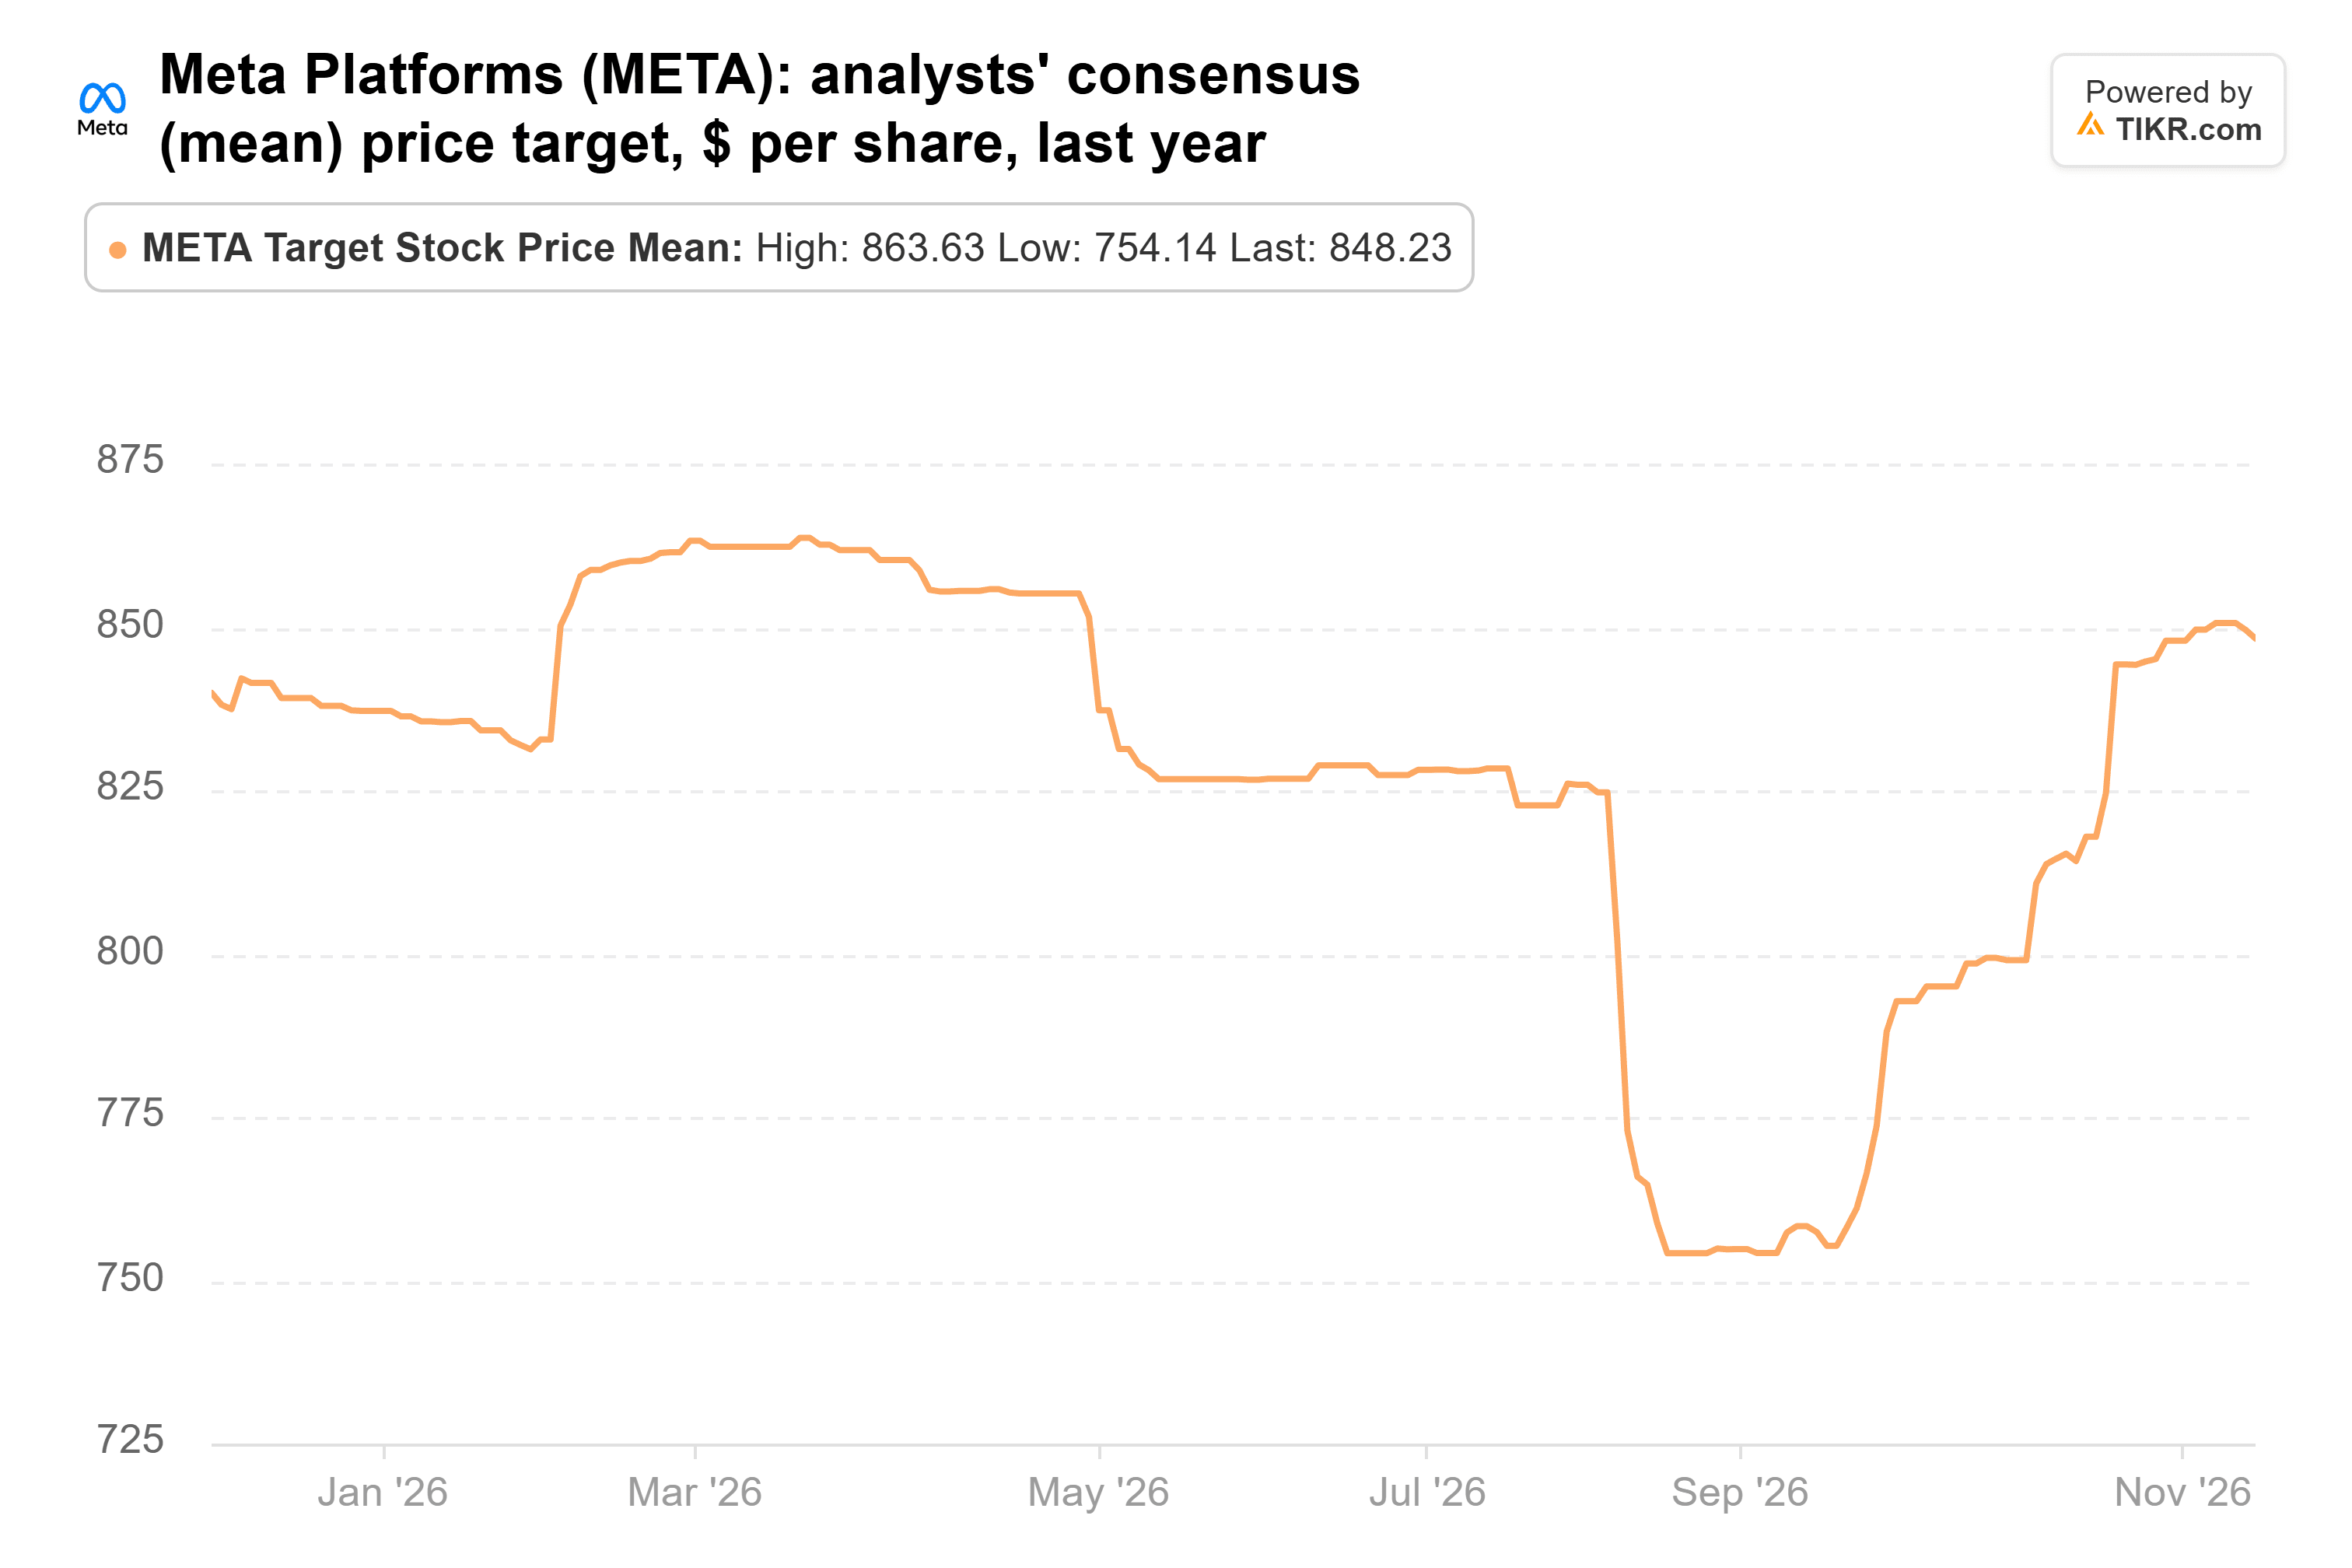
By my math, $848 is about 20x the 2028 earnings estimate, and 2028 is the year the market will be pricing a year from now. That’s slightly above today’s 19x forward multiple and below Meta’s 21x average. So the target doesn’t need investors to pay a higher multiple. It only needs the estimates to hold.
The cash is the catch
Consensus has Meta’s free cash flow bottoming at negative $48.0 billion in 2027, with capital spending around $210 billion. Meta has also raised more than $60 billion of new funding since late October, and its newest dollar notes pay more than last year’s. Its $83.7 billion of debt was already more than its $82.45 billion of cash and marketable securities at Sept. 30. Not every fund agrees with Loeb, either: Senvest Management sold all 70,000 of its Meta shares in the third quarter, while a $15 billion fund bought in.
Still, I think Loeb has this one right. Investors are paying 19x forward earnings for a company whose ad revenue grew 26% last quarter, and Wall Street’s target only asks for the estimates to hold. Anyone buying today also gets Meta 15% below its Sept. 30 price.
The test comes in late January, when Meta reports fourth-quarter results and sets out its 2027 spending plan. Revenue in the upper half of the $73 billion to $76 billion range, plus 2027 capital spending at or below the roughly $210 billion analysts expect, would make the bet look even better. Third Point’s next 13F, due in mid-February, will show whether it held on.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!