Key Takeaways
- Apple is worth about $615 billion more than Nvidia after Thursday’s AI selloff took 9% off Nvidia’s stock.
- Wedbush Securities analyst Dan Ives thinks about 15% of Apple’s Services revenue will come from AI over the coming years, and he values that at $75 a share.
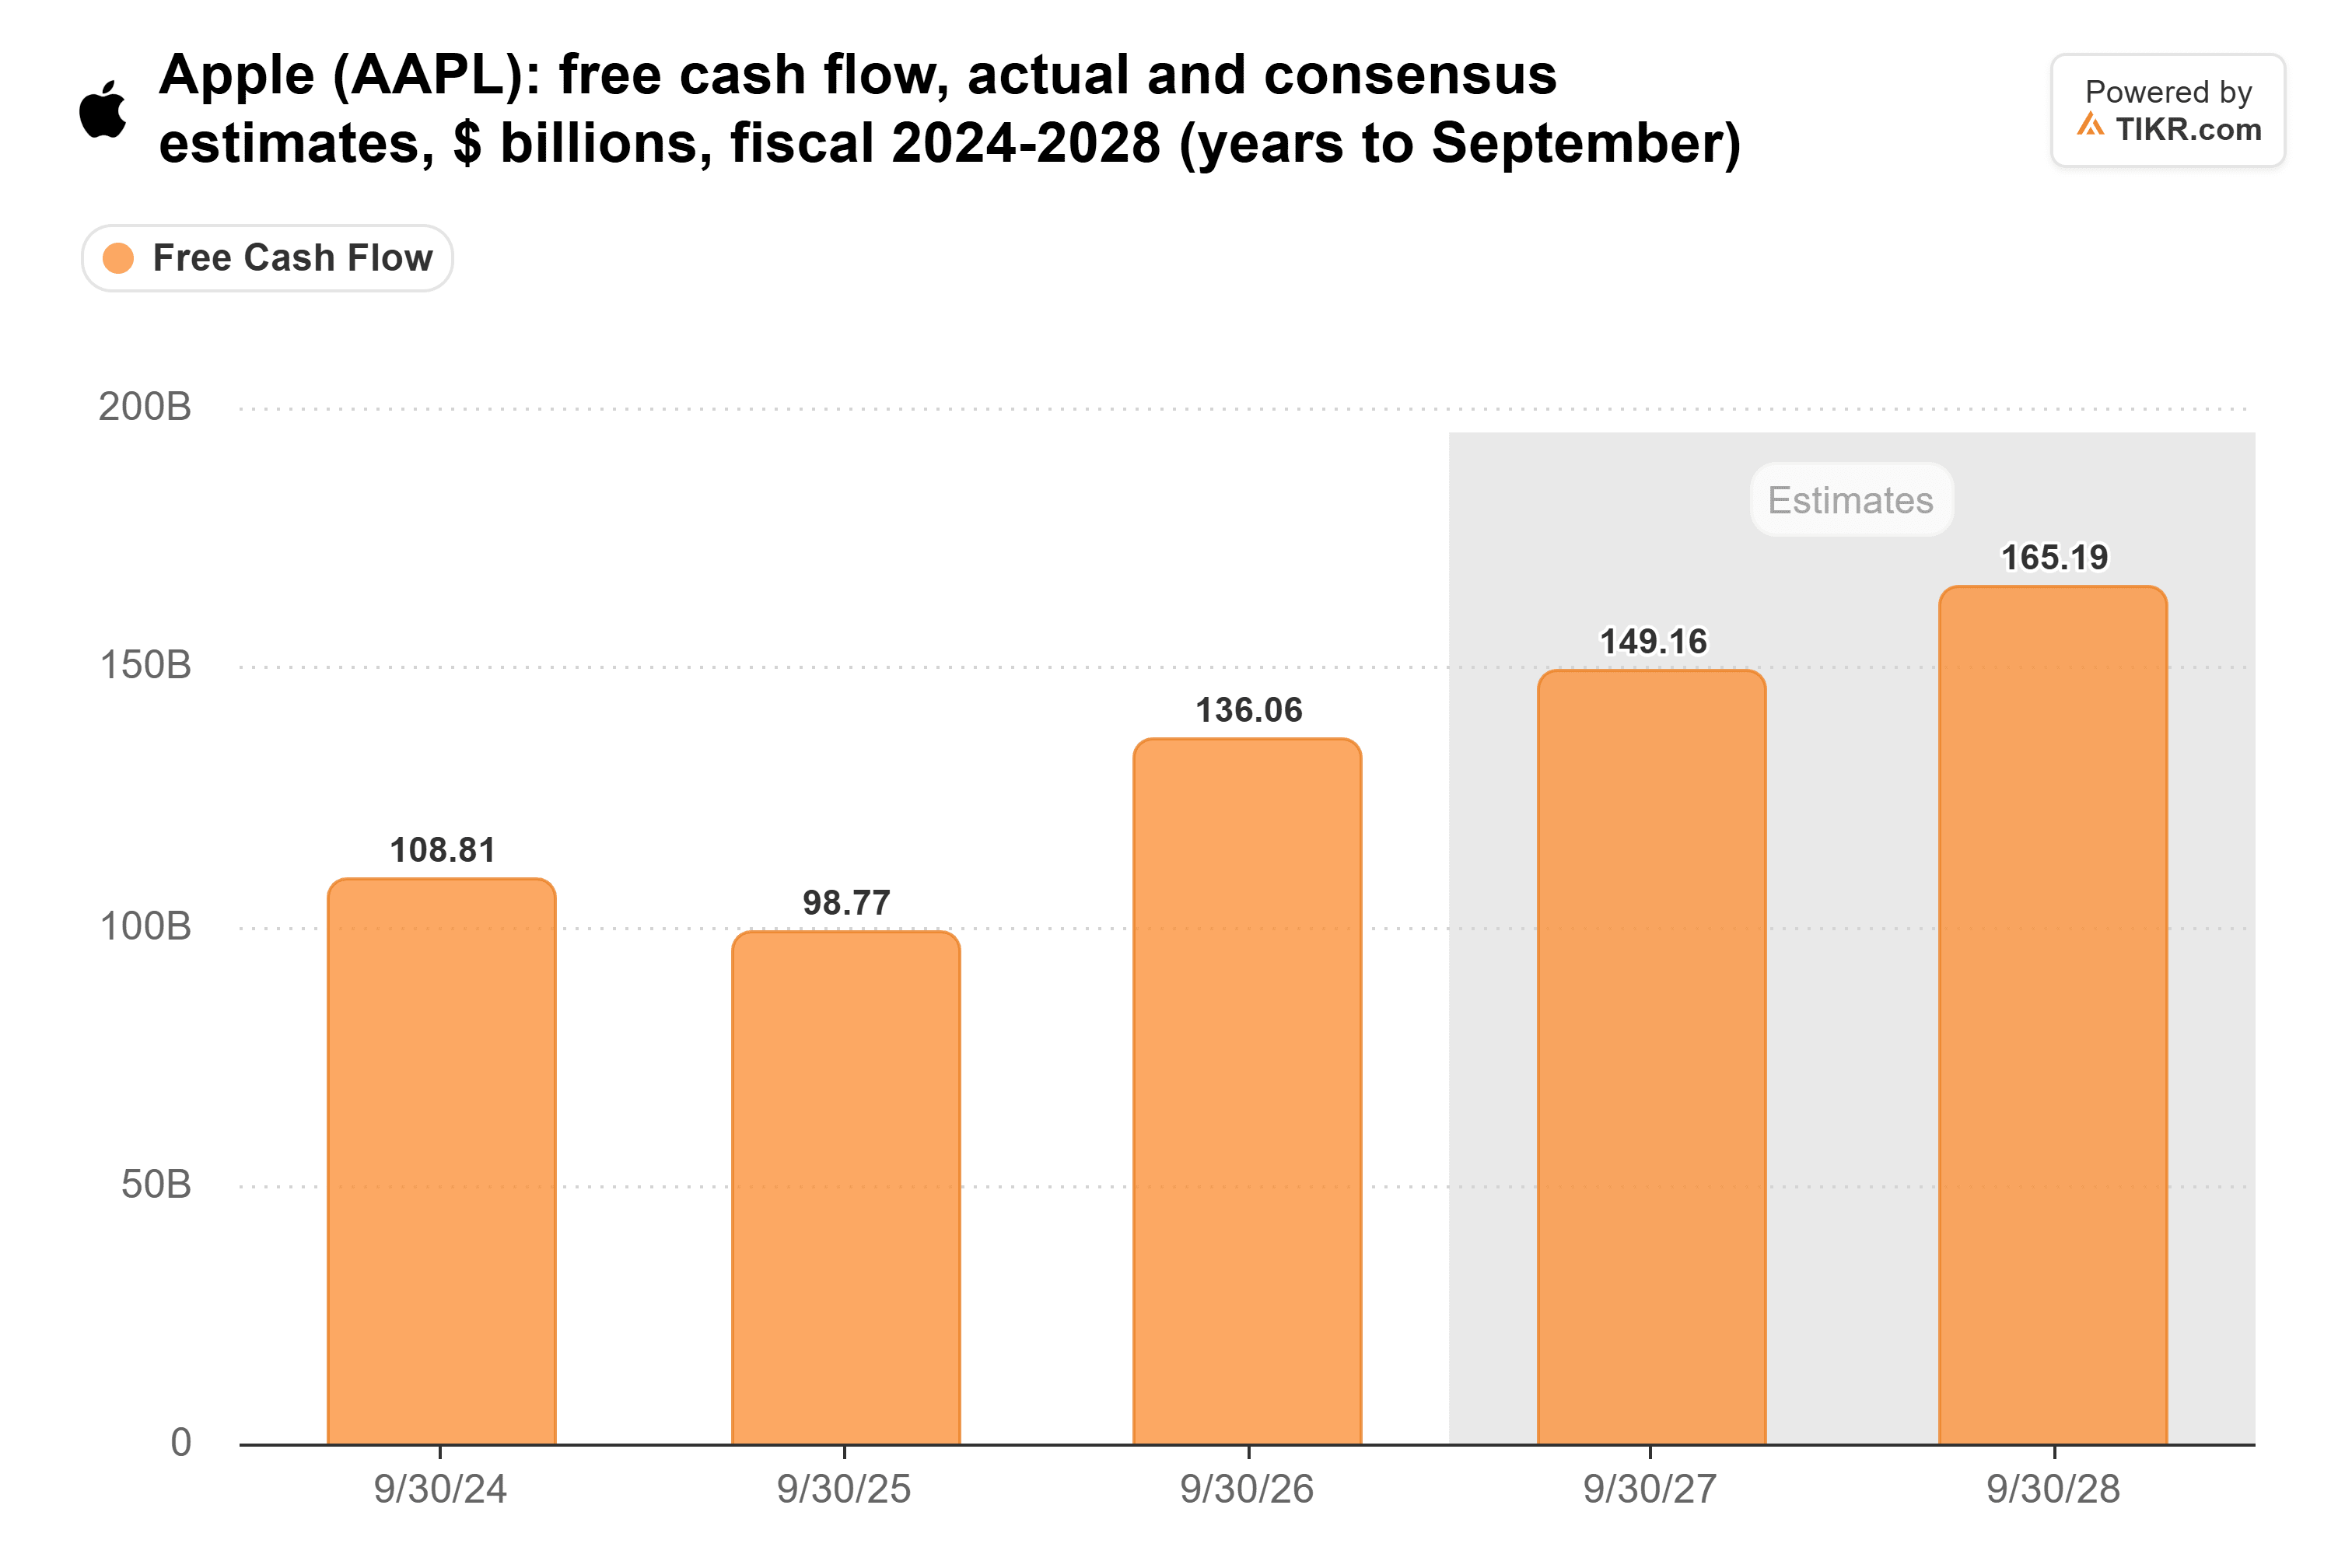
- Apple produced $136 billion of free cash flow in fiscal 2026 while cutting its capital spending, and analysts expect $149 billion in fiscal 2027.
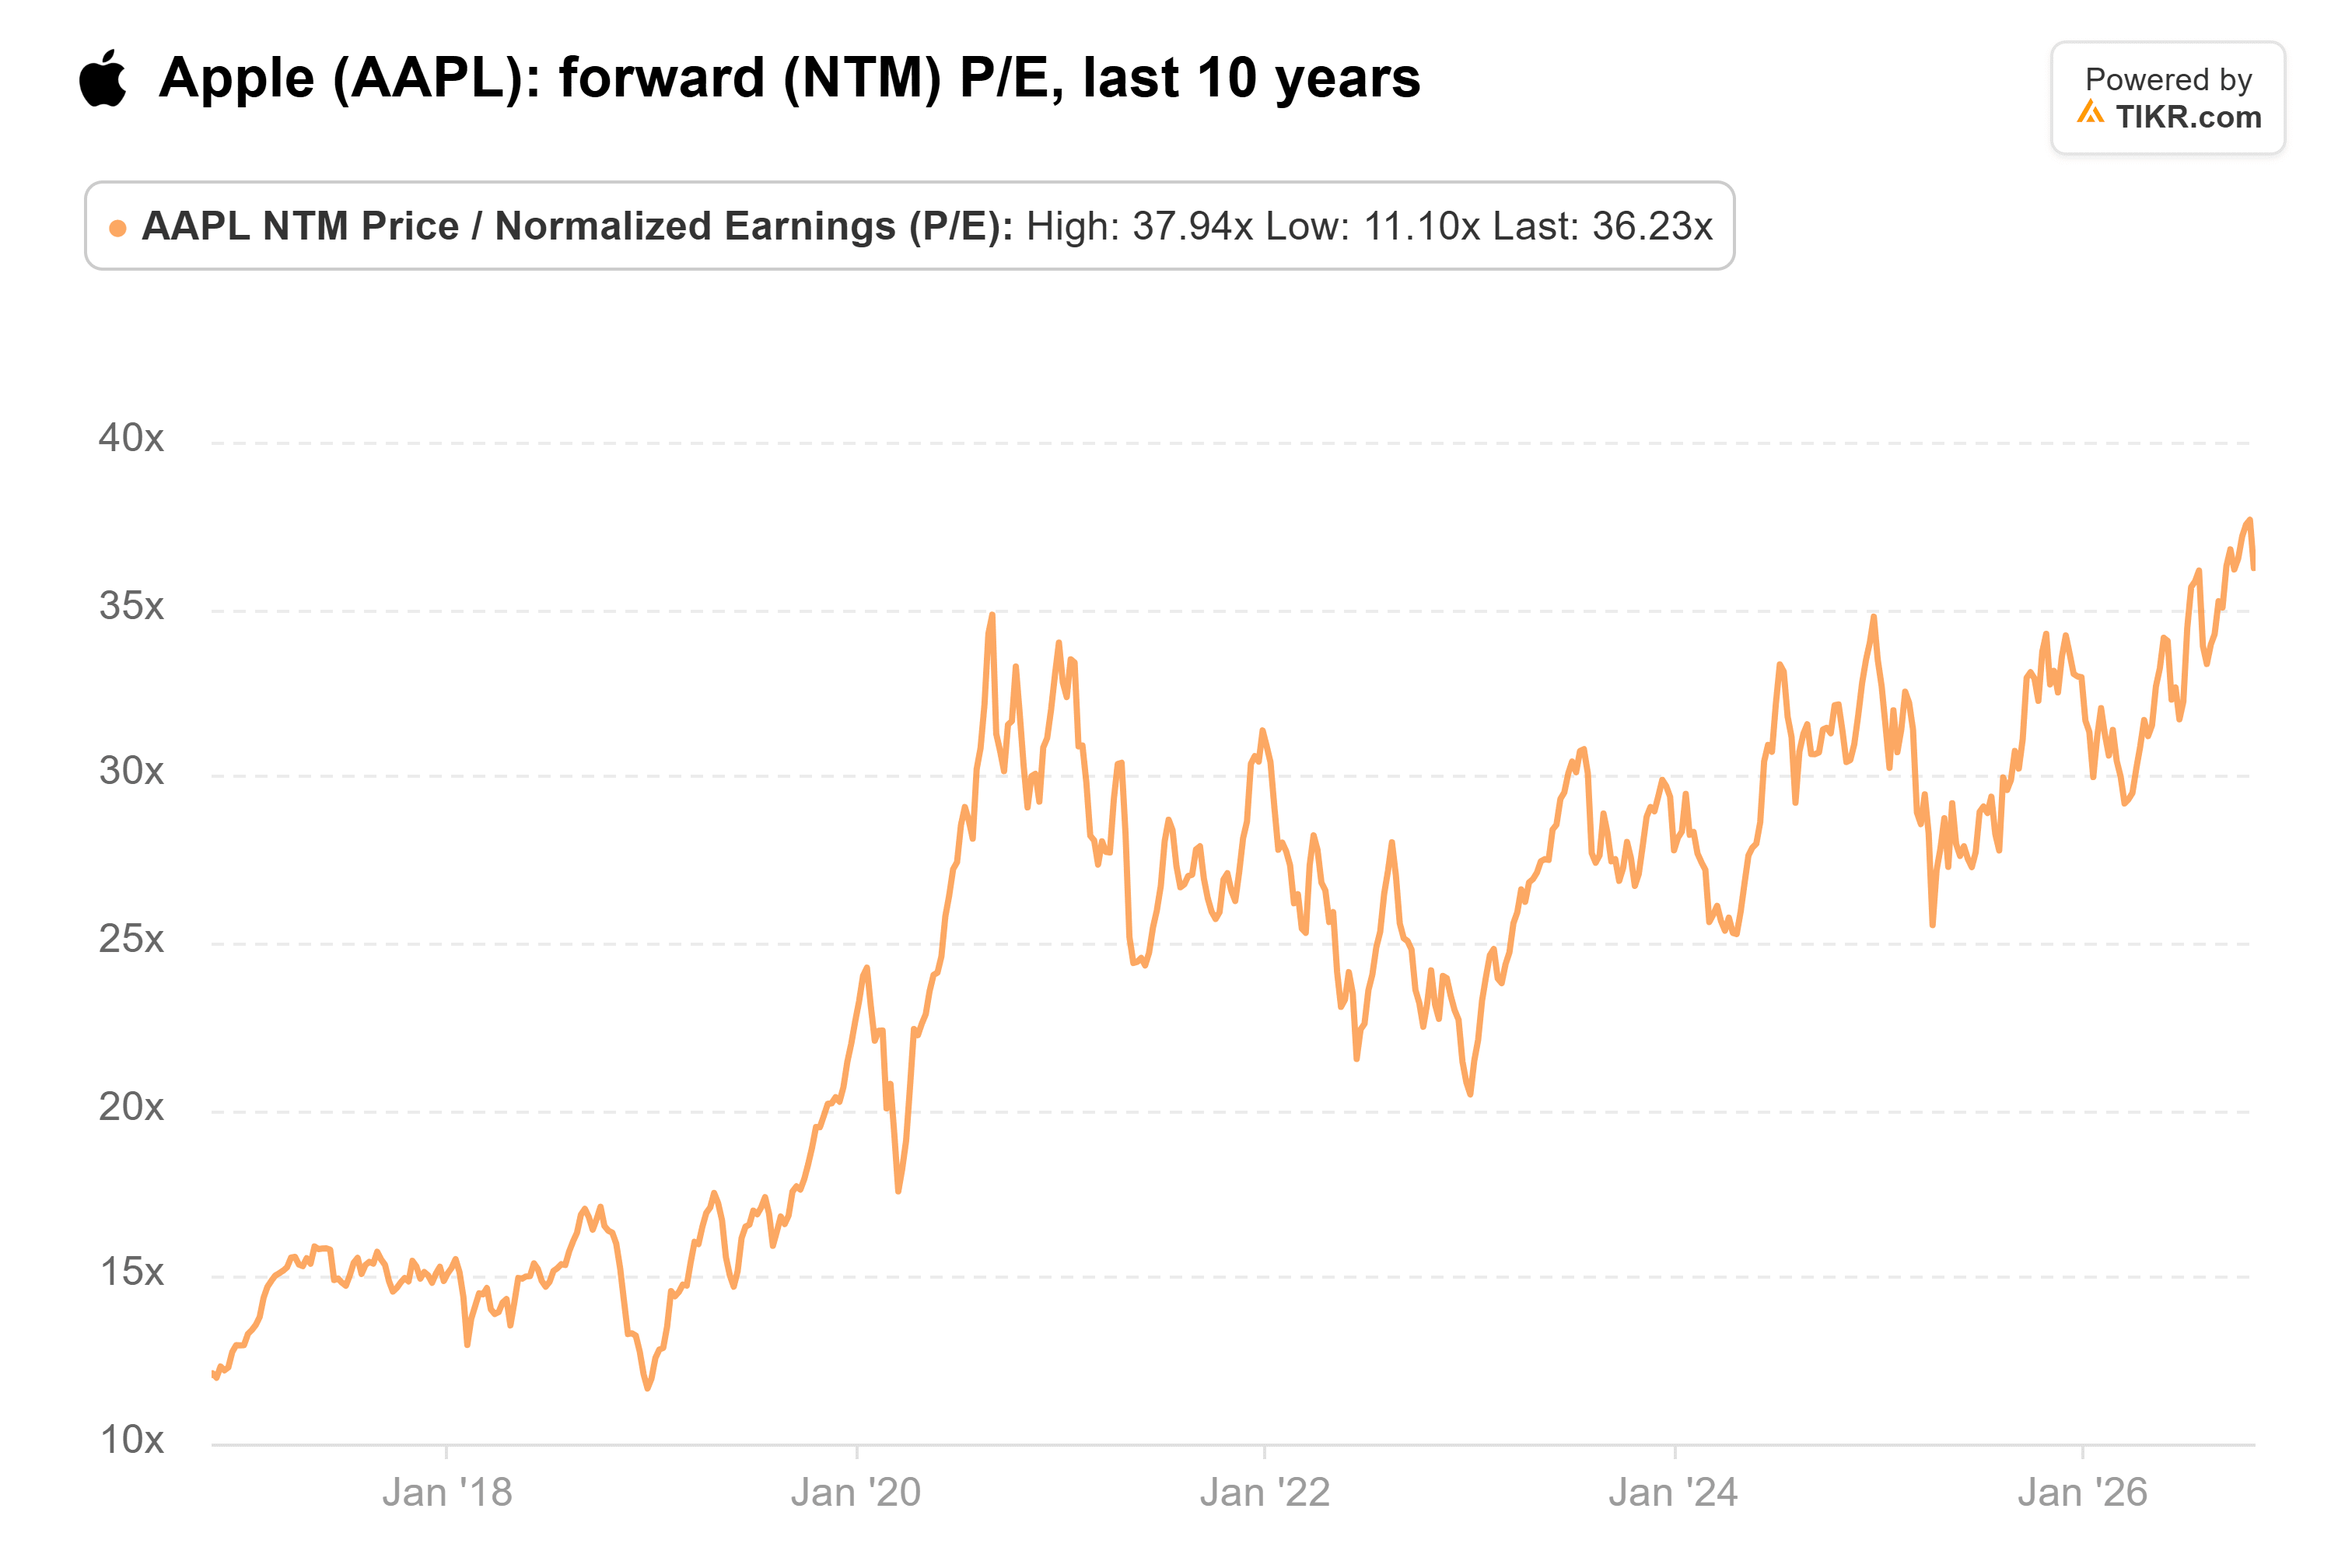
- Apple now trades at 36x forward earnings against a 10-year average of 24x, so the stock already reflects much of that AI upside.
Apple (AAPL) closed Thursday worth $5.00 trillion. That’s about $615 billion more than Nvidia (NVDA), whose stock fell 9% on fears that a Democratic Congress will slow the build-out of AI data centers.
Two days earlier, Bloomberg Talks asked Wedbush Securities’ Dan Ives to sum up Apple’s AI strategy after Monday’s earnings call.
He called it “genius.” Apple has found a way to “basically spend very little when it comes to AI,” he said, and its installed base has kept growing.
Then he made the bigger claim: “20% of the world will access A.I. through an Apple device.”
That’s a good place to be in a week like this one.
TIKR tracks 43 analysts on Apple. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Apple already has the customers
On its fourth-quarter call Monday, Apple said it has more than 2.5 billion active devices and over 1.5 billion paid subscriptions. (Every iPad, Mac and Watch is in that count, so it covers fewer people than devices.) Still, those devices are already in people’s hands, ready for AI.
Apple also isn’t paying the capital bill to reach them. Its capex fell 28% to $6.8 billion in the first nine months of fiscal 2026, while R&D rose 33% to $34.0 billion.
That’s the other side of Nvidia’s business. Data center sales were $89.0 billion of Nvidia’s $96.2 billion of revenue in its fiscal second quarter. That money comes from the companies building AI capacity, so a slower build-out hits Nvidia’s sales first.
Ives expects developers to build AI features and apps on Apple’s platforms, with Apple collecting the money. When asked whether that would show up in Services, he said:
“I think about 15% of services over the coming years will be AI, which is our view like $75 per share incremental to the story just from an AI perspective.”
For scale, Apple closed Thursday at $344.17.
The cash keeps coming
Robert Schiffman, a senior credit analyst at Bloomberg Intelligence, discussed Apple’s new bond sale on Bloomberg Tech Thursday. He said everyone in the hyperscaler space “is bleeding cash.” Apple isn’t: “We think Apple’s going to generate $150 billion of free cash in fiscal 2027.”
Analysts agree with him. Apple’s free cash flow rose from $98.8 billion in fiscal 2025 to $136 billion in fiscal 2026, and the consensus of 16 analysts is $149 billion for fiscal 2027:
Apple has dropped its net-cash-neutral target, so Schiffman expects much of that cash to go to buybacks, and possibly to higher dividends.
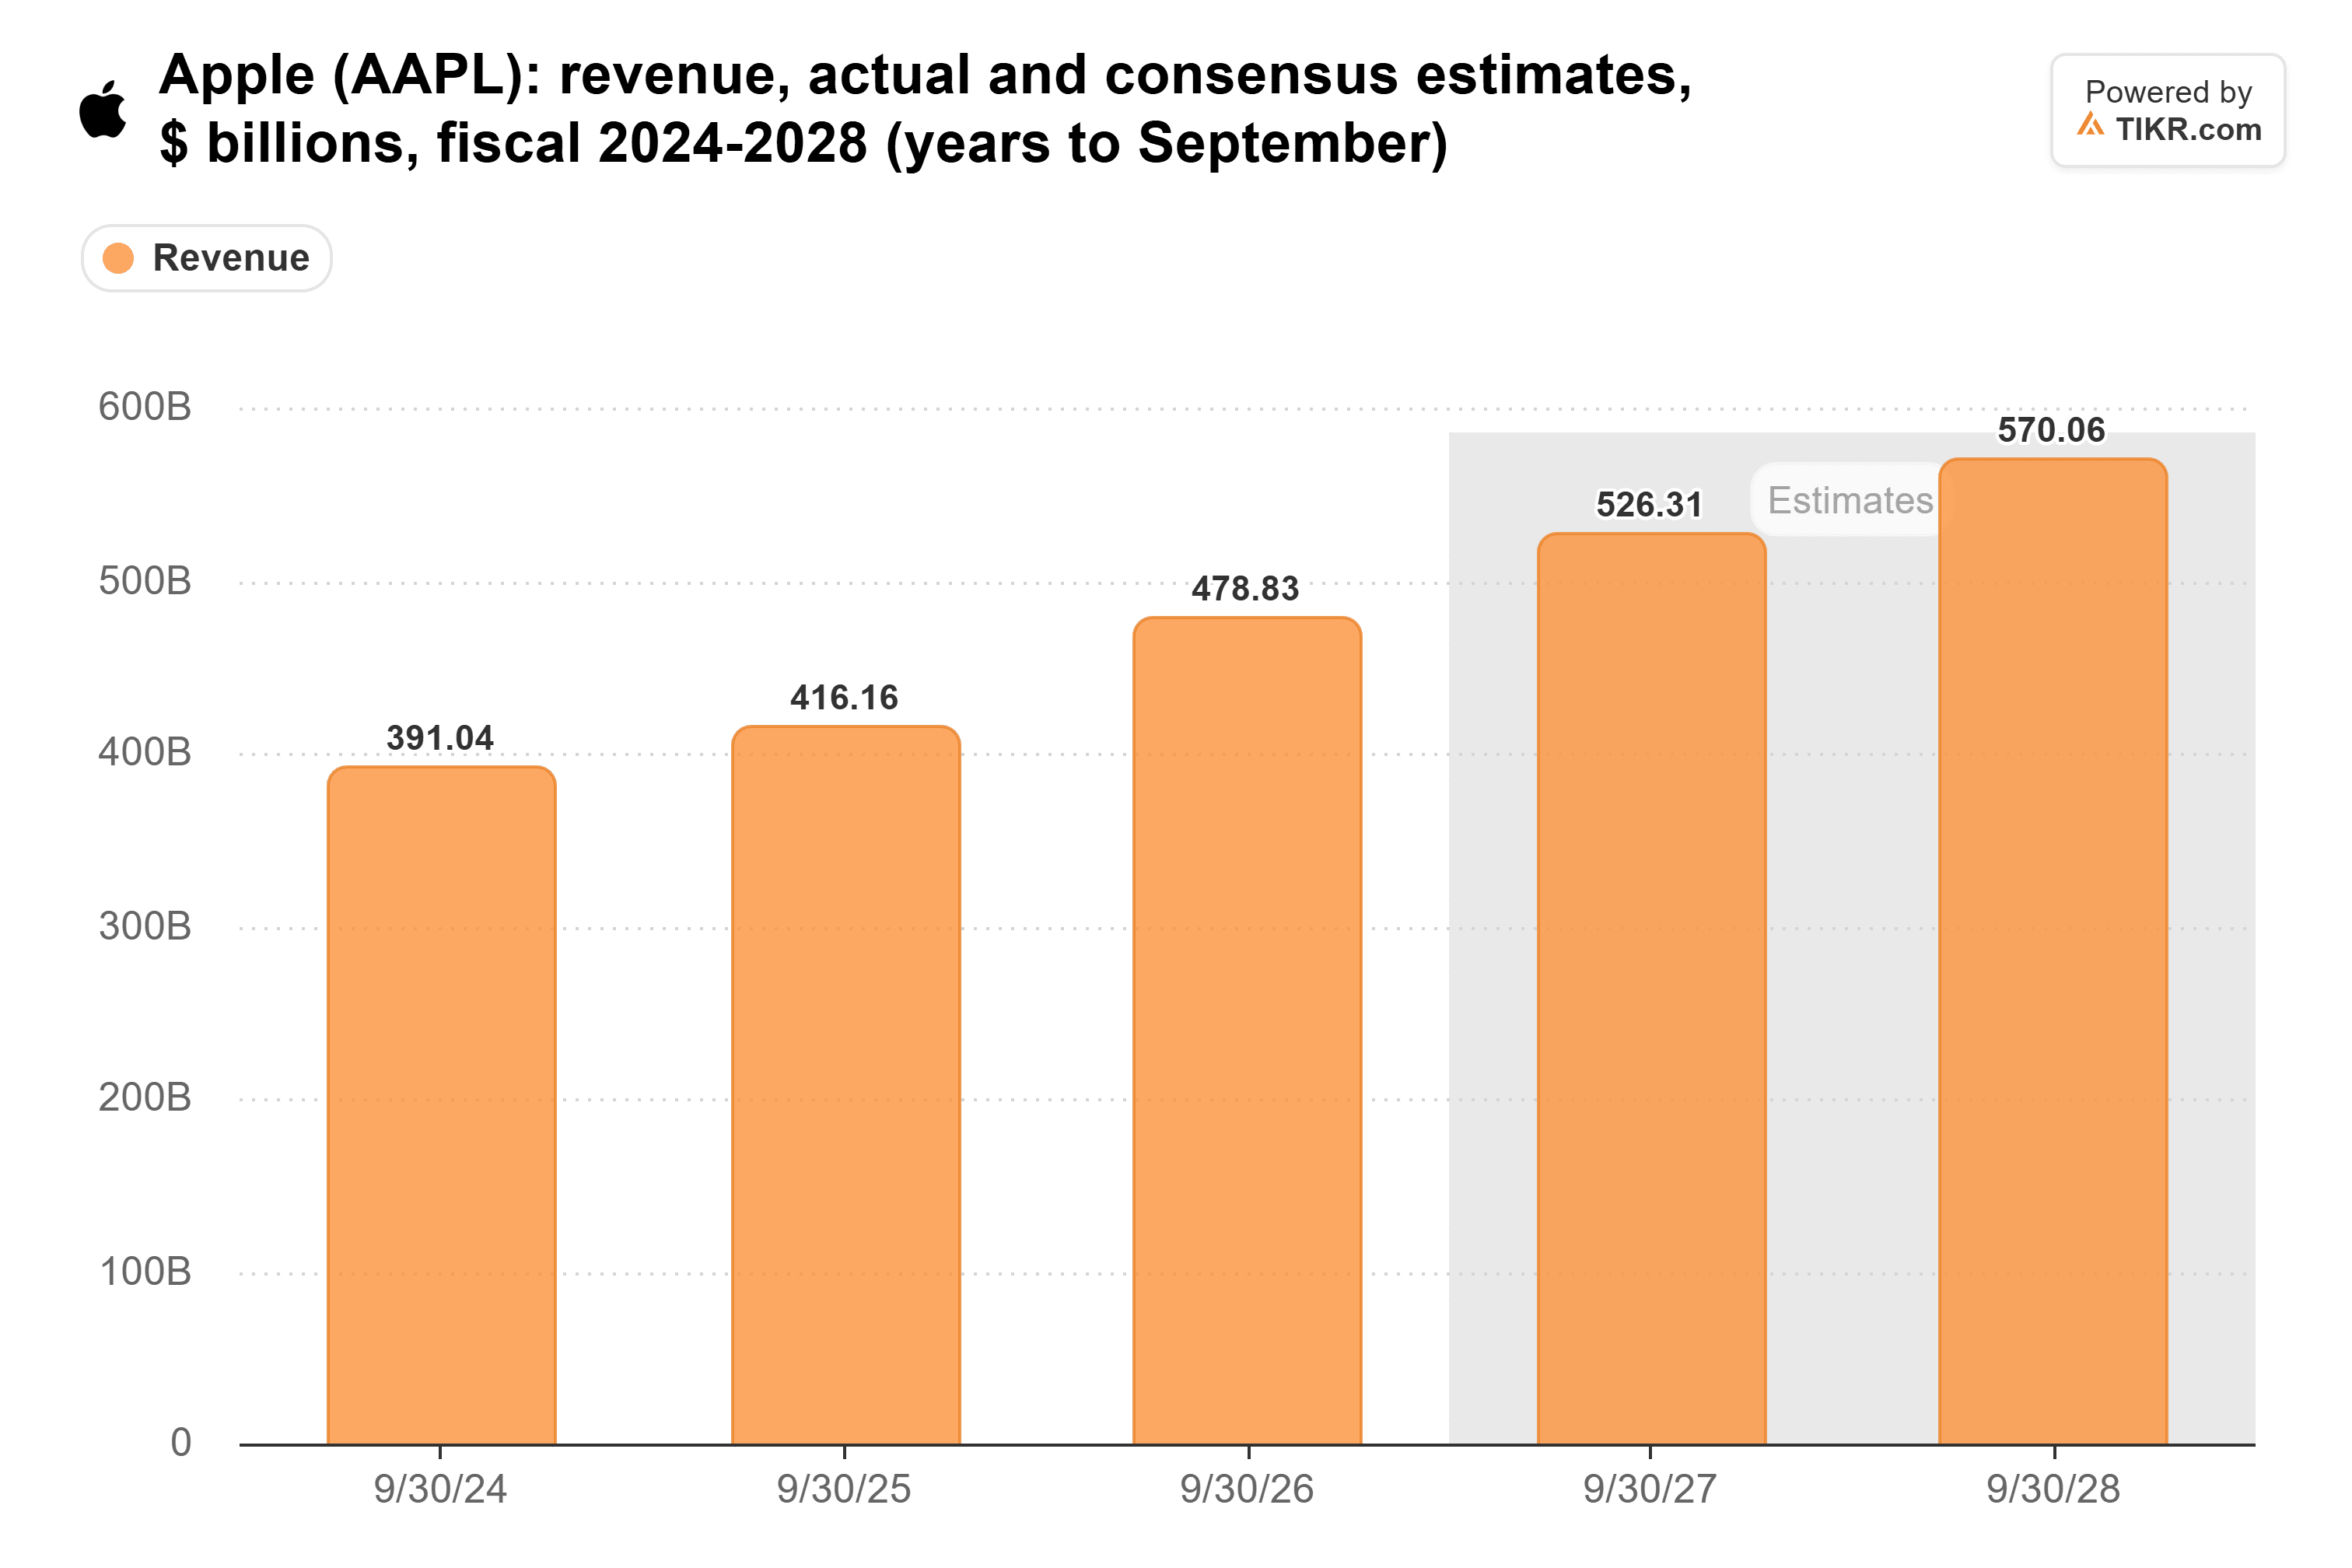
Revenue should keep growing too. CFO Kevan Parekh guided December-quarter revenue up 7% to 10% and said, “We expect this to be the best quarter for revenue in the history of the company.” Analysts expect revenue to rise from $479 billion in fiscal 2026 to $570 billion in fiscal 2028:
Services has to pick up the pace
Ives’ 15% has to come from a Services business that is slowing. Services revenue hit a record $31.6 billion in the September quarter, up 10%. But Apple guided December-quarter growth to just 8% to 9%, with headwinds “primarily driven by third-party licensing and foreign exchange.”
Third-party licensing is where Google’s search payments sit. Bloomberg’s Mark Gurman has said AI is pulling searches away from Safari, so Apple’s revenue share from Google “is going to come down.”
AI isn’t free for Apple either. Apple guided December-quarter gross margin to 45% to 46%, down from 47.9% in the September quarter. Parekh said that includes higher memory costs and “some costs related to the ramp of Siri AI.”
Investors are already paying for it
Apple’s forward P/E is 36x. That’s near its 10-year high of 38x, set in late October, and far above its 10-year average of 24x:
Ives is right about Apple’s position. It reaches billions of people with AI without spending like a hyperscaler, and the cash flow shows it.
But at 36x, I think his $75 of AI upside is already in the price, and Services, where that upside is supposed to show up, is guided to slow. I’d hold Apple as the safe place to wait out this selloff. I wouldn’t add at this multiple until Siri AI starts paying off in Services.
Apple sells heavier Siri AI use through iCloud+ plans. If those upgrades start moving the needle, Services is where it will show first. Apple’s next report, due in late January, will tell us whether December’s 8% to 9% guide was the low point.
So what is Apple stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!