Key Takeaways
- CrowdStrike rose 2% today after Cloudflare reported 39% revenue growth and raised its full-year outlook.
- Cloudflare tied its growth to escalating digital threats, a good sign for security spending.
- Palo Alto Networks and Zscaler rose too, ahead of their own reports.
- CrowdStrike still trades far above its five-year average multiple, so its Dec. 1 report probably needs another guidance raise.
CrowdStrike (CRWD) is up 2% today, winning back part of Thursday’s 9% drop, and it has another company’s quarter to thank.
After Thursday’s close, Cloudflare said third-quarter revenue rose 39% to $782.5 million, its fastest growth in nearly four years. It raised its full-year outlook to $2.96 billion, above the $2.87 billion analysts expected. That’s good news for Palo Alto Networks (PANW) and Zscaler (ZS), too.
Cloudflare puts a number on the threats
Cloudflare co-founder and CEO Matthew Prince tied the growth to the same pressure CrowdStrike sells against: “as digital threats escalate, organizations of every size continue to rely on Cloudflare for protection.” He added that Cloudflare has “found an even higher gear for this next phase of growth.”
Palo Alto and Zscaler report next
Palo Alto, up 2%, reports first, on Nov. 18. It expects next-generation security ARR of $9.54 billion to $9.56 billion for the quarter ending Oct. 31, up 63%. A beat would say Cloudflare’s demand is reaching Palo Alto too.
Zscaler, up 0.1%, competes with Cloudflare in zero-trust security: is that budget growing for both companies, or is Cloudflare taking share? Leaving out its Red Canary acquisition, Zscaler’s ARR grew 20% in the year to July 31, and it expects 16.6% to 17.4% growth for the year ahead. Its Dec. 2 report should answer that.
TIKR tracks 53 analysts on CrowdStrike. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CrowdStrike, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CrowdStrike’s Analyst Ratings
CrowdStrike is priced for another raise
CrowdStrike reports on Dec. 1. Analysts expect revenue to nearly double from the year ended January 2026 to the year ending January 2029:
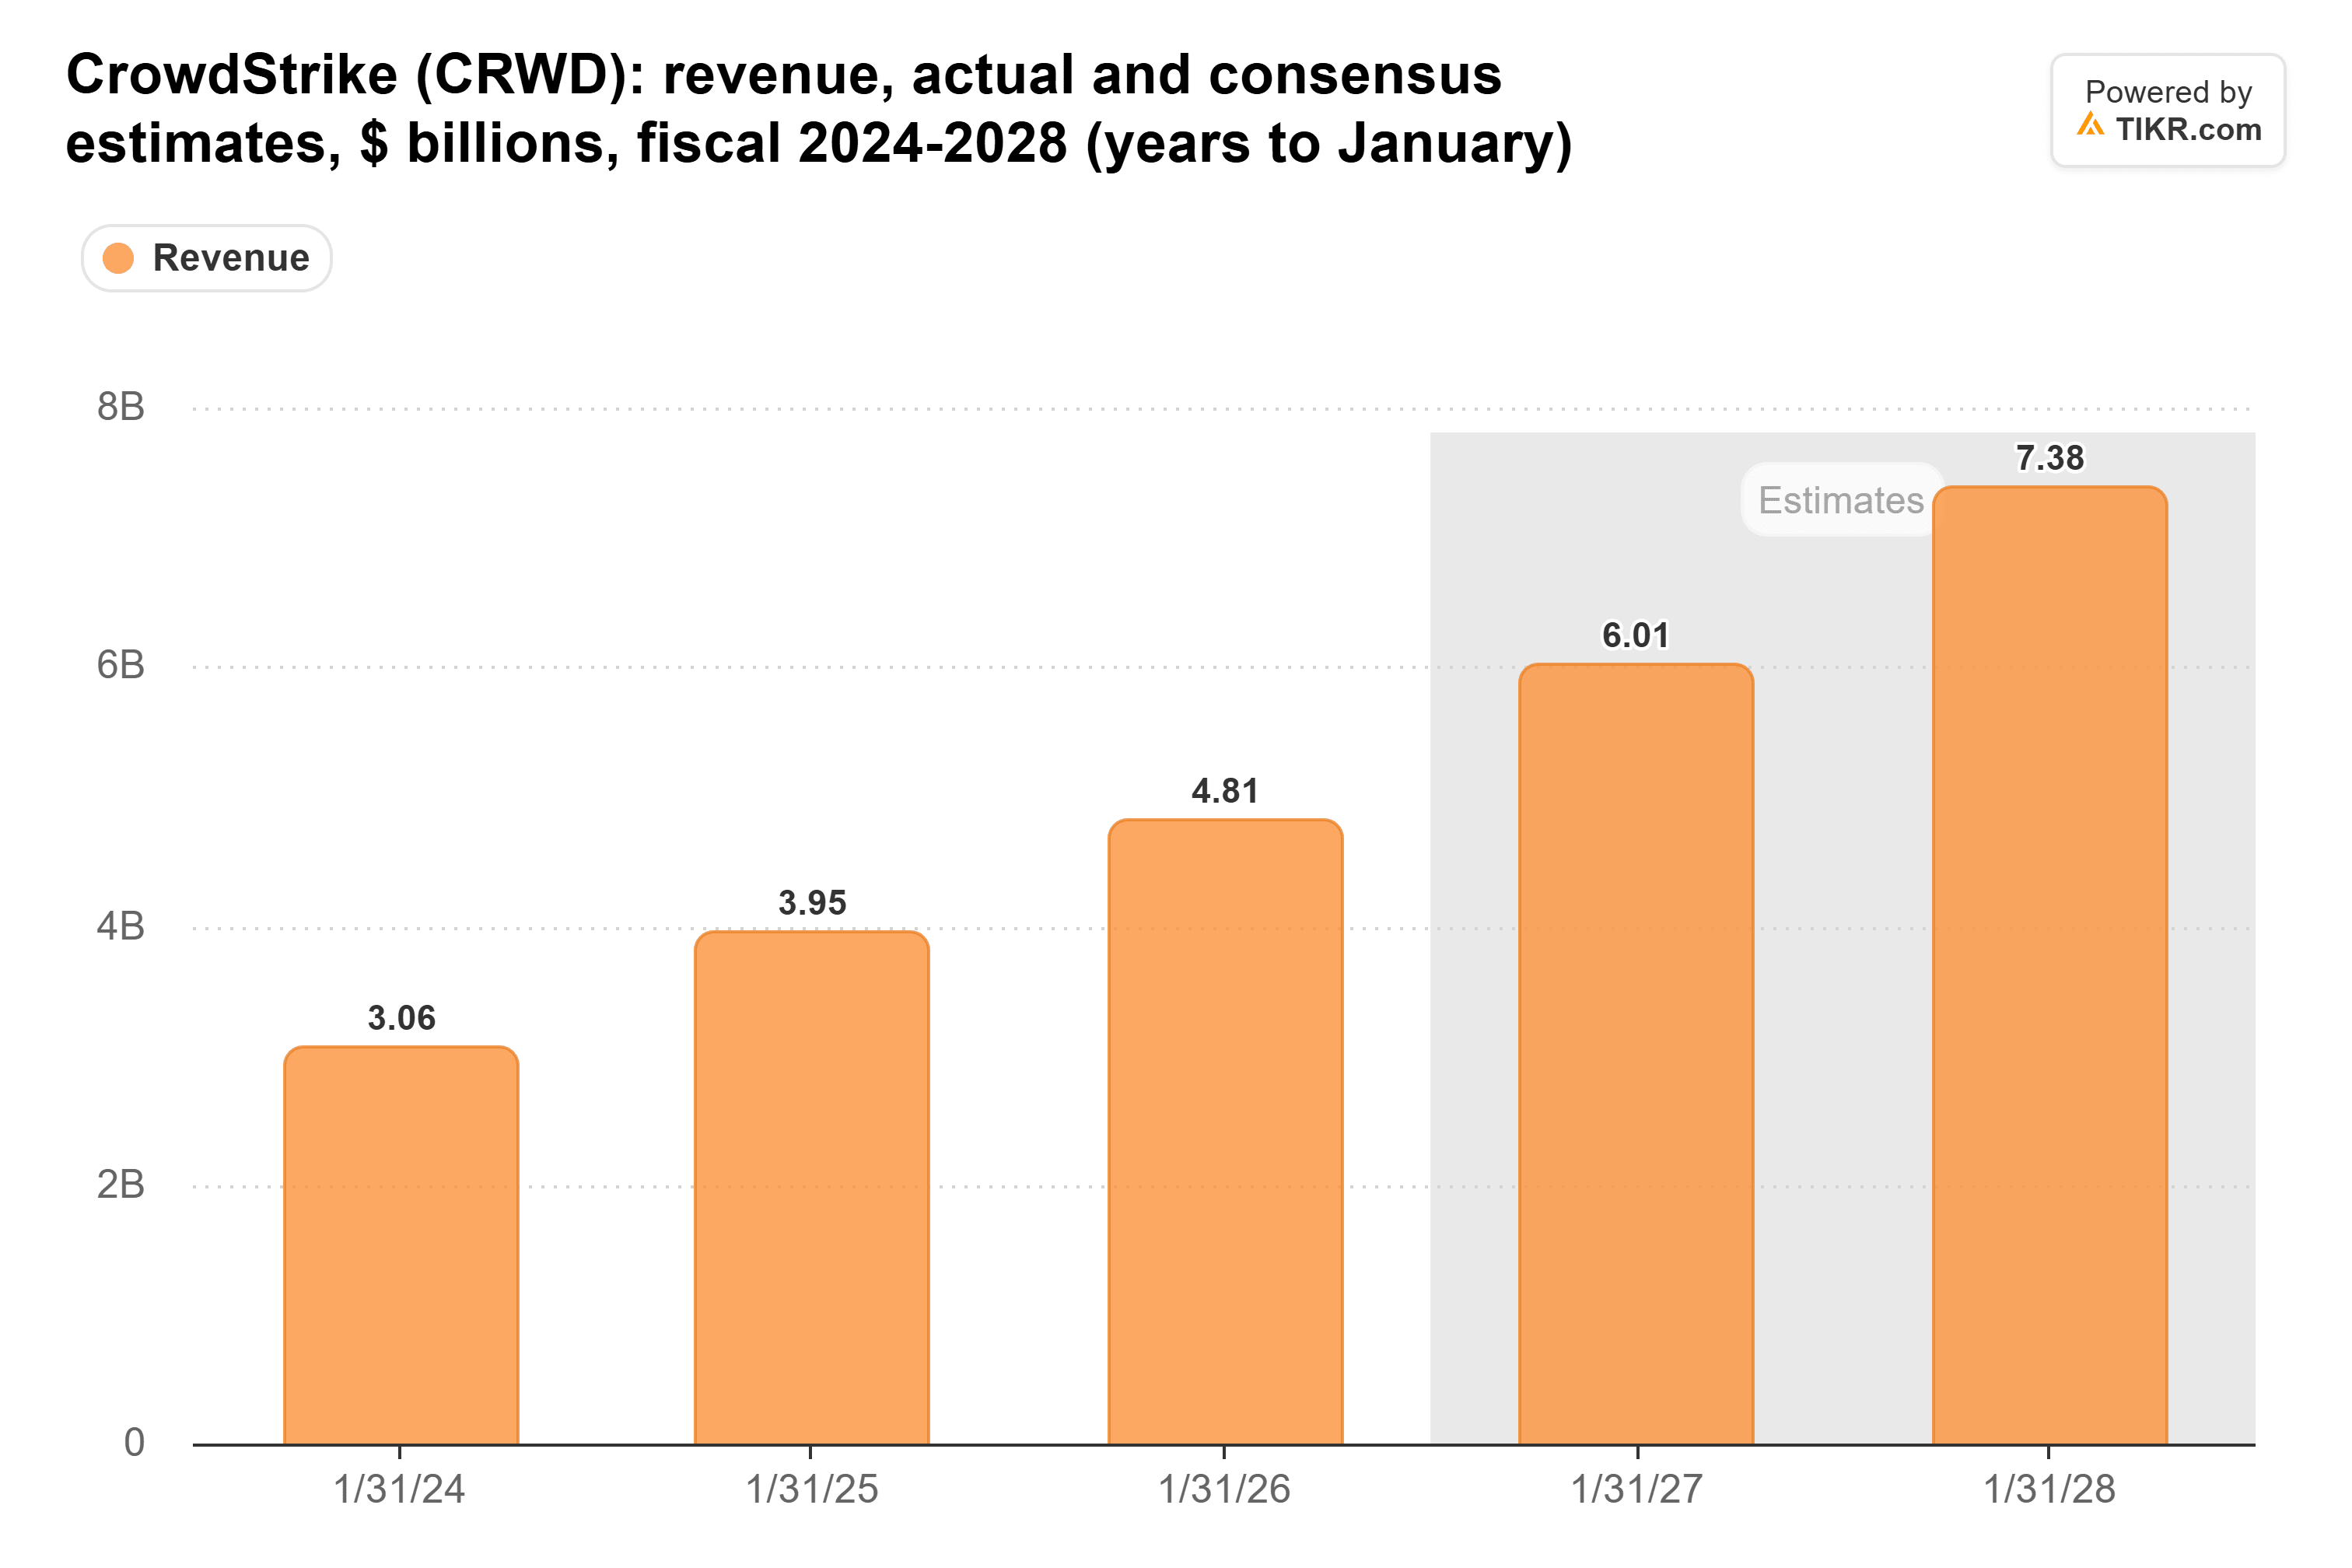
But analysts have raised those estimates by less than 5% over the past year, so most of the stock’s run came from a higher forward P/E:
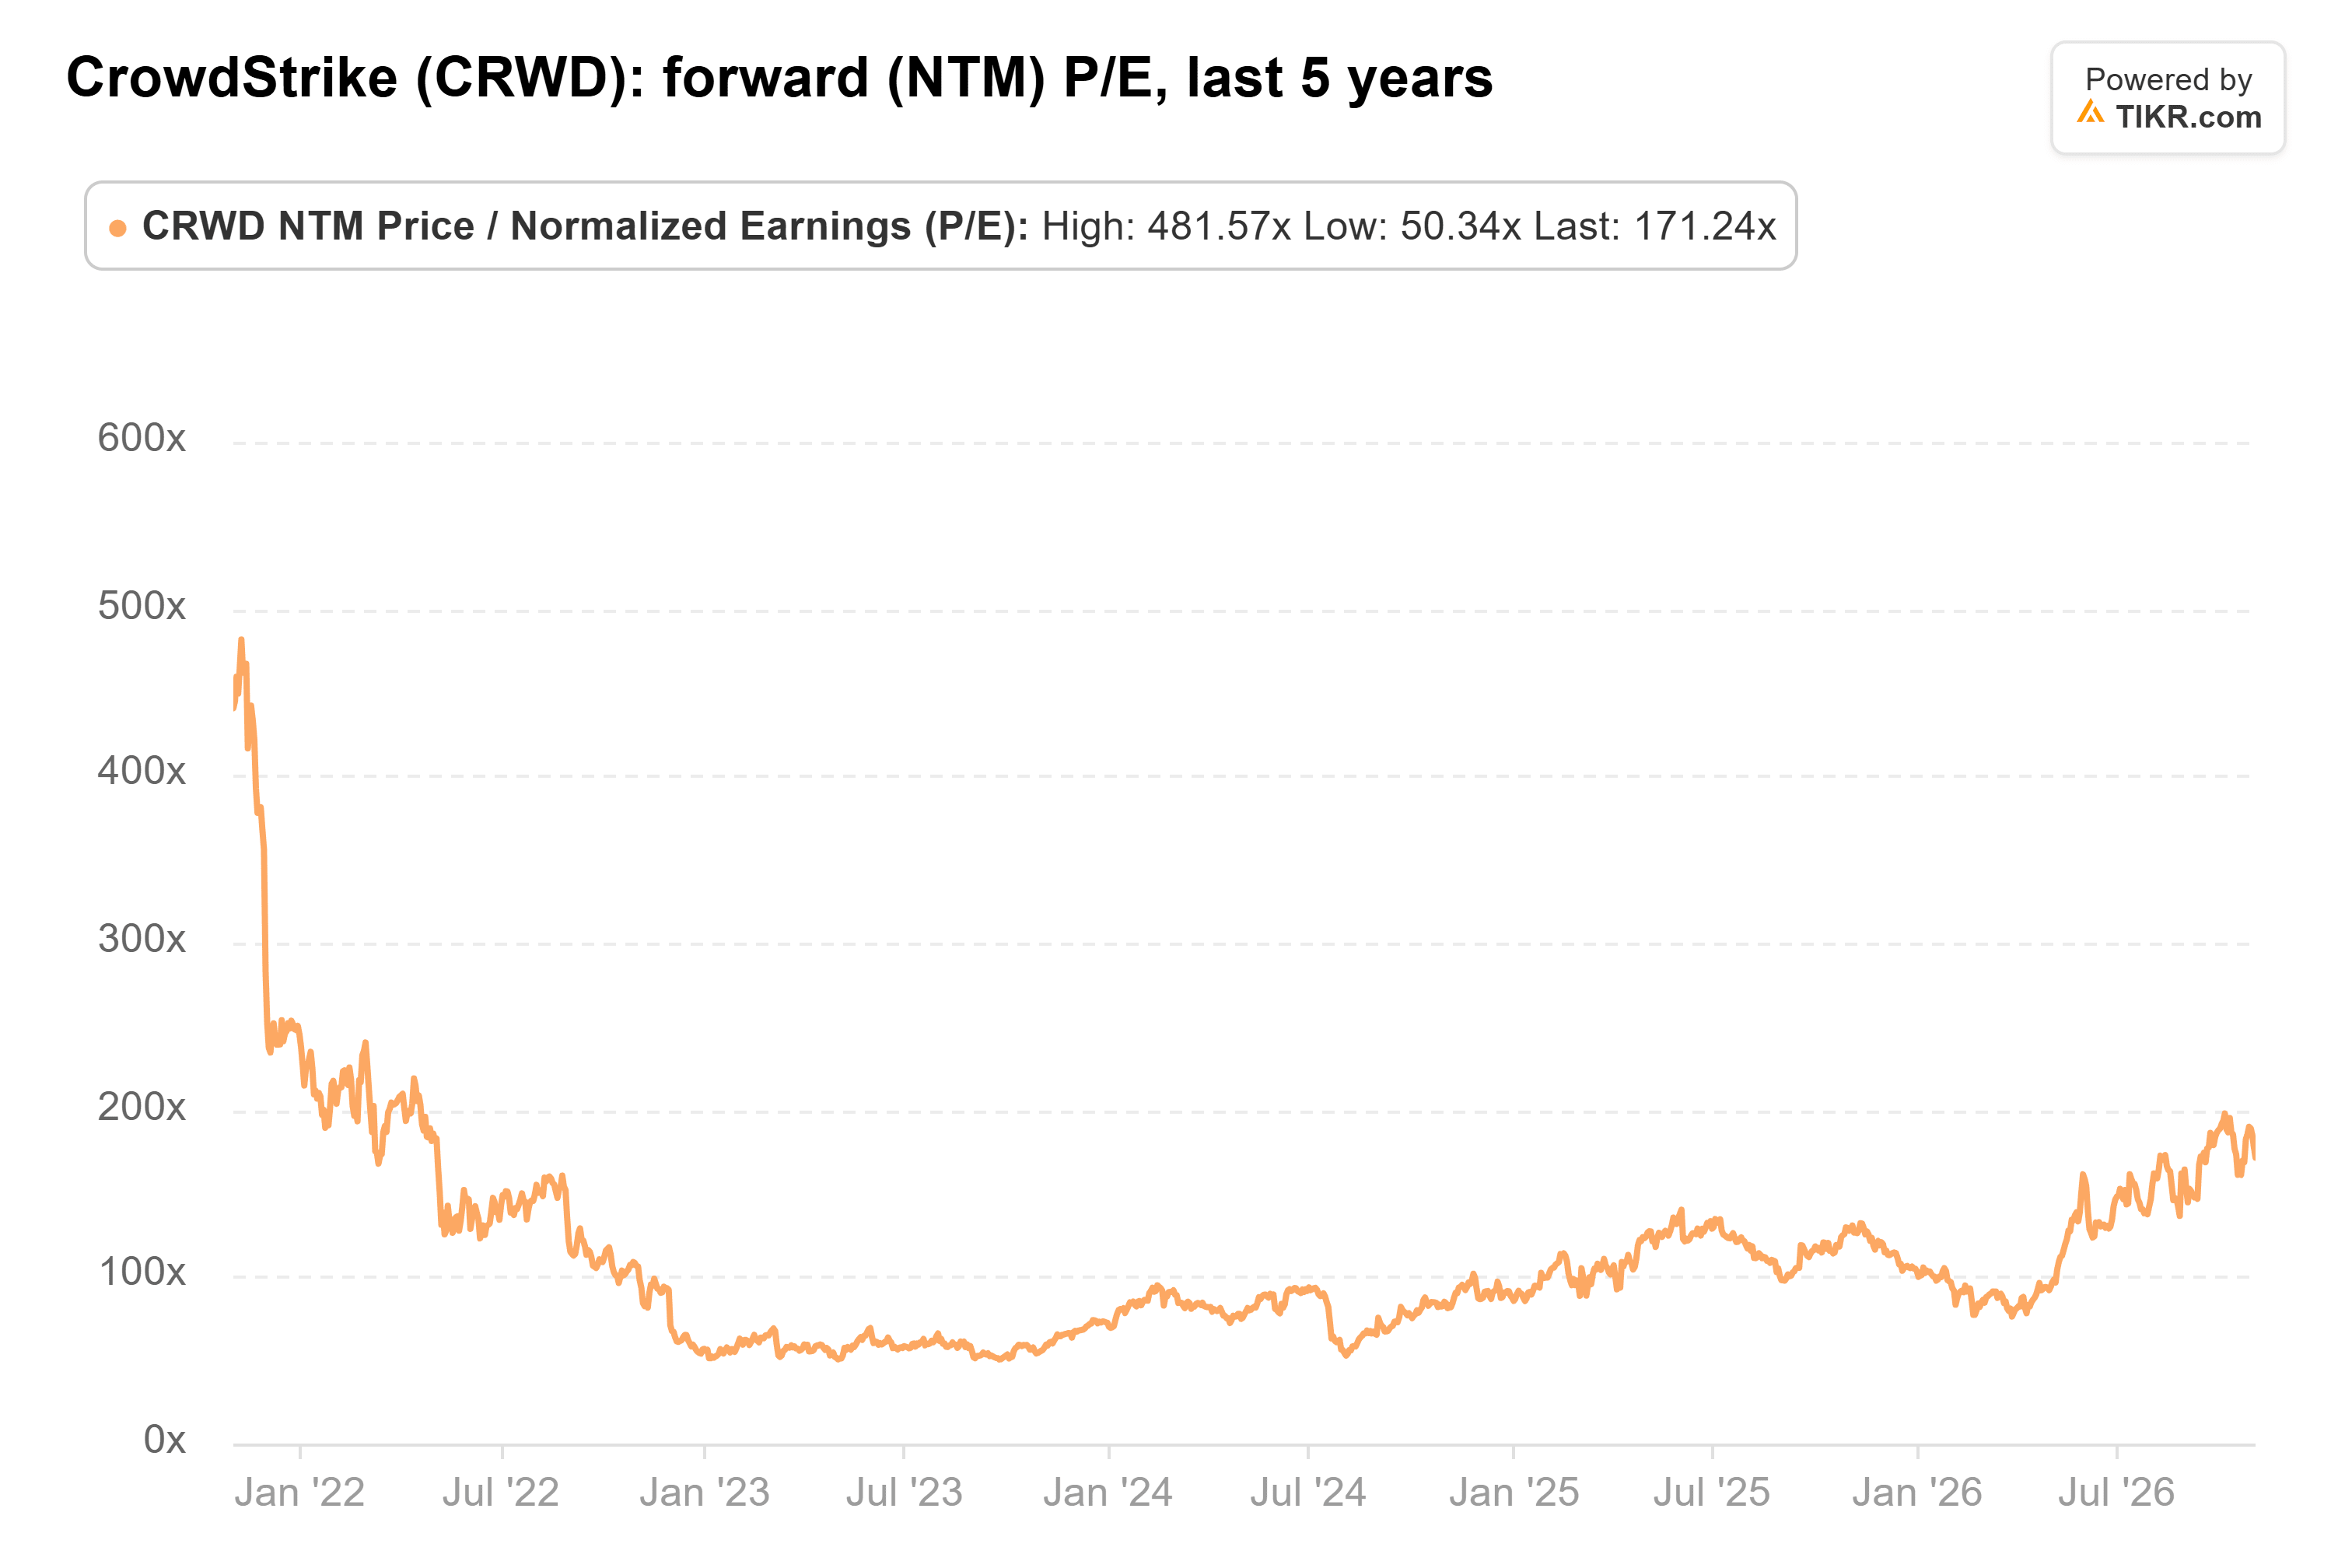
CrowdStrike traded at 171x forward earnings on Nov. 2, against a five-year average of 113x. Even after this week’s selling, it’s still well over 150x.
The way I see it, Cloudflare just made a strong CrowdStrike quarter more likely. But management has already raised its full-year net new ARR outlook twice, to 34% growth, and at this multiple the stock needs a third raise on Dec. 1.
Of course, a soft Palo Alto quarter on Nov. 18 would take some of the shine off Cloudflare’s good news.
So what is CrowdStrike stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CrowdStrike could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!