Key Takeaways
- Credo fell 17.7% to $112 on Thursday and 25.6% over two sessions, leaving it 64% below its 52-week high of $309.
- Its last quarter was a record, with revenue up 115% to $479 million and a 68% adjusted gross margin.
- Four customers produced about 84% of revenue, and the CTO has sold more than $25 million of stock since September.
- The December 2 report will show whether optical revenue is on track for the $600 million-plus target for fiscal 2027.
Credo Technology Group (CRDO) has some of the best margins in AI networking. Right now the market is pricing it like one of the riskiest names.
Shares fell 17.7% on Thursday to $112, after a 9.6% drop on Wednesday. The Nasdaq slid into a correction as AI stocks sold off, and Credo now sits 64% below its 52-week high of $309.
The whole optical group got hit. Coherent (COHR) fell 13% on Thursday and Lumentum (LITE) lost 18.7%, yet Credo now trades at a lower forward multiple than either, with gross margins well above both.
So is this a chance to buy an AI interconnect leader on sale? Or is the market right to discount a company that leans on four customers?
A record quarter, then a reset
Credo’s fiscal first quarter, reported September 1, set records almost everywhere:
- Revenue rose 115% to $479 million, above the $465 million to $475 million guide.
- Adjusted EPS of $1.20 beat the $1.17 estimate.
- Adjusted gross margin hit 68%, with operating margin at 48.2%.
AECs remain the largest business, with relationships at five hyperscalers. Retimers and optical DSPs both hit records, and Credo booked its first silicon photonics PIC revenue after buying DustPhotonics for $750 million.
The top line has gone nearly vertical, and analysts expect more…
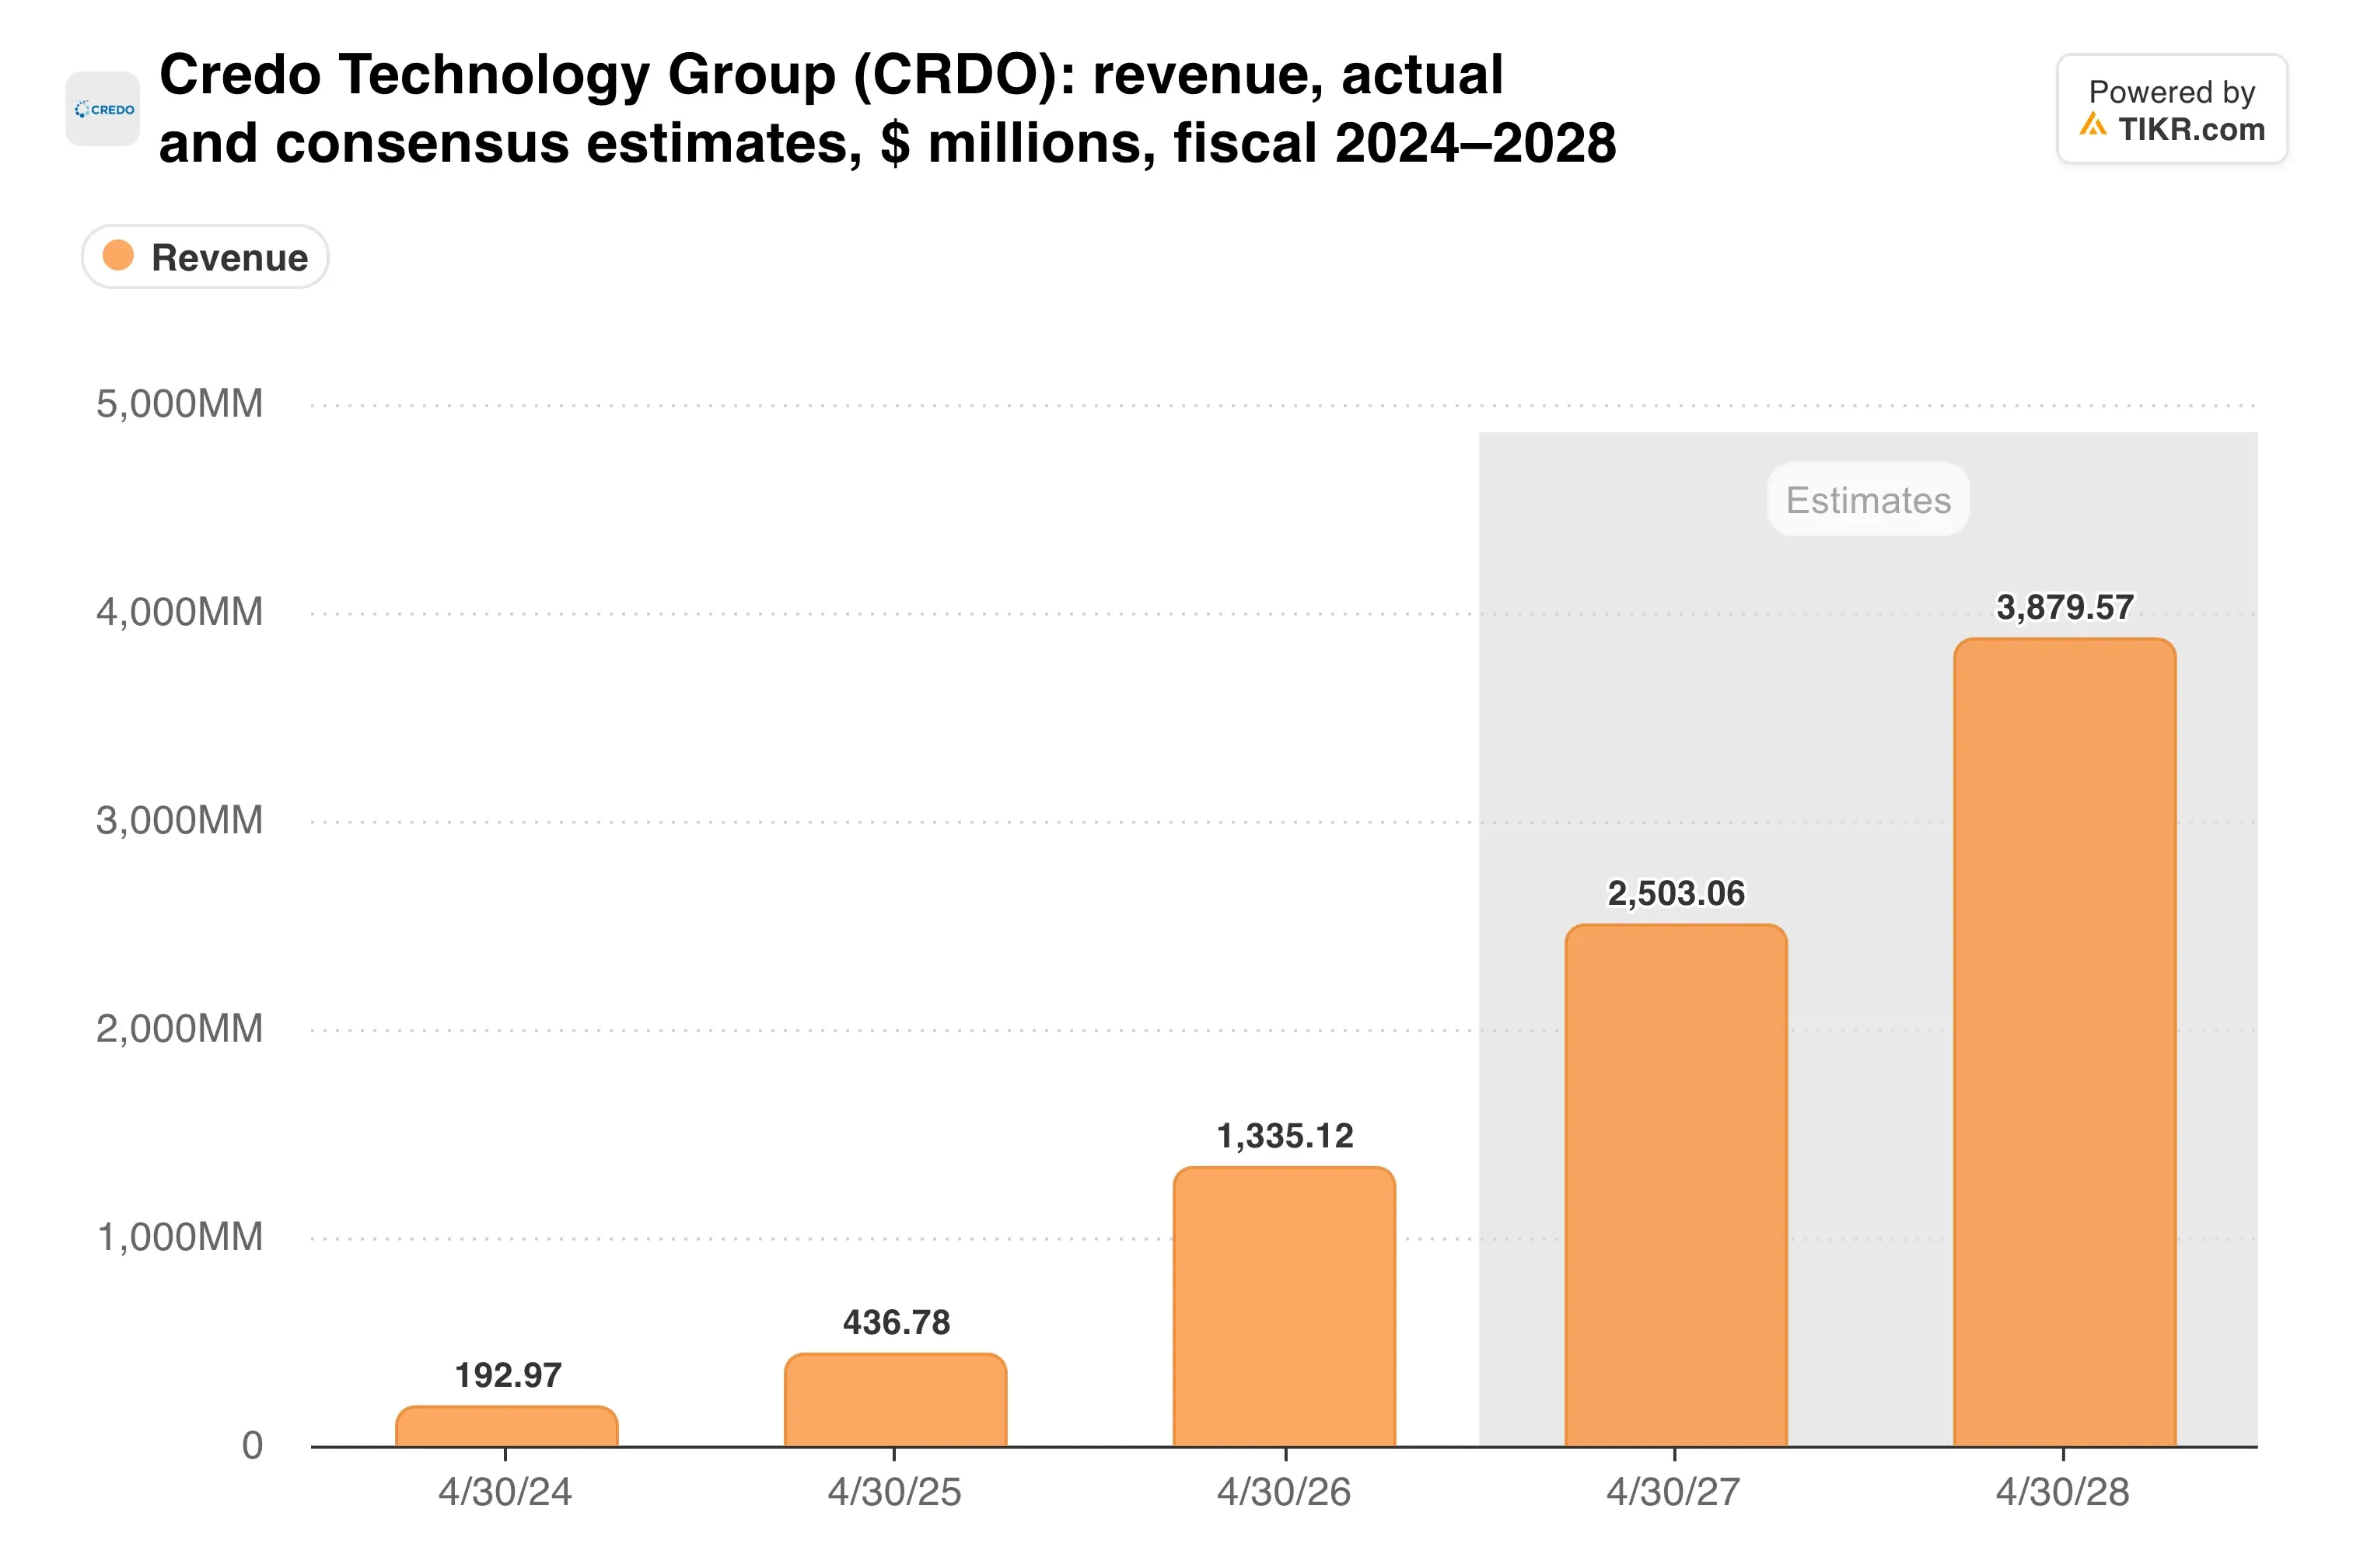
Management’s fiscal 2027 guide calls for growth above 85%, so estimates still assume a very steep year.
Margins the peers can’t match
Second-quarter guidance calls for revenue of $525 million to $535 million, or about 10.6% sequential growth, with adjusted gross margin of 67% to 69%.
Management also expects optical revenue above $600 million this fiscal year. ZeroFlap Optics, silicon photonics PICs, and optical DSPs should each pass $100 million, and that ramp drives the second-half inflection.
The optical push moves Credo deeper into Coherent’s and Lumentum’s territory. The cost structures could hardly look more different:

Credo’s trailing gross margin of 67.1% compares with 48.0% at Lumentum and 37.5% at Coherent.
TIKR tracks 20 analysts on Credo Technology. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Credo Technology, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Credo Technology’s Analyst Ratings
Concentration is the discount
Four end customers generated about 84% of first-quarter revenue. One accounted for 33% and another for 28%, so a single order change could swing a quarter.
Insider selling adds to the unease. CTO Cheng Chi Fung has reported six sales since September 10 totaling more than $25 million, and COO Lam Yat Tung sold $20.6 million in late September.
How much of that is already in the price?

At roughly 15.8x forward earnings, Credo trades below Coherent at about 18.5x and Lumentum at about 20.9x. Wall Street’s average target of $284 sits 153% above Thursday’s close.
My take: I think the selloff went too far for a company guiding to 85% growth with 68% gross margins and $738 million of net cash. Concentration is a real risk, and I’d expect the stock to stay volatile. But at under 16x forward earnings, the price already assumes something goes wrong, and the last quarter showed no sign of it.
The December 2 report is the test. Watch whether revenue lands in the $525 million to $535 million range and whether management still sees optical revenue above $600 million.
So what is Credo stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Credo could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!