Key Takeaways
- HSBC kept its Buy rating on Citigroup on Nov. 12 and cut its price target to $158 from $164, still 30% above the Nov. 16 close.
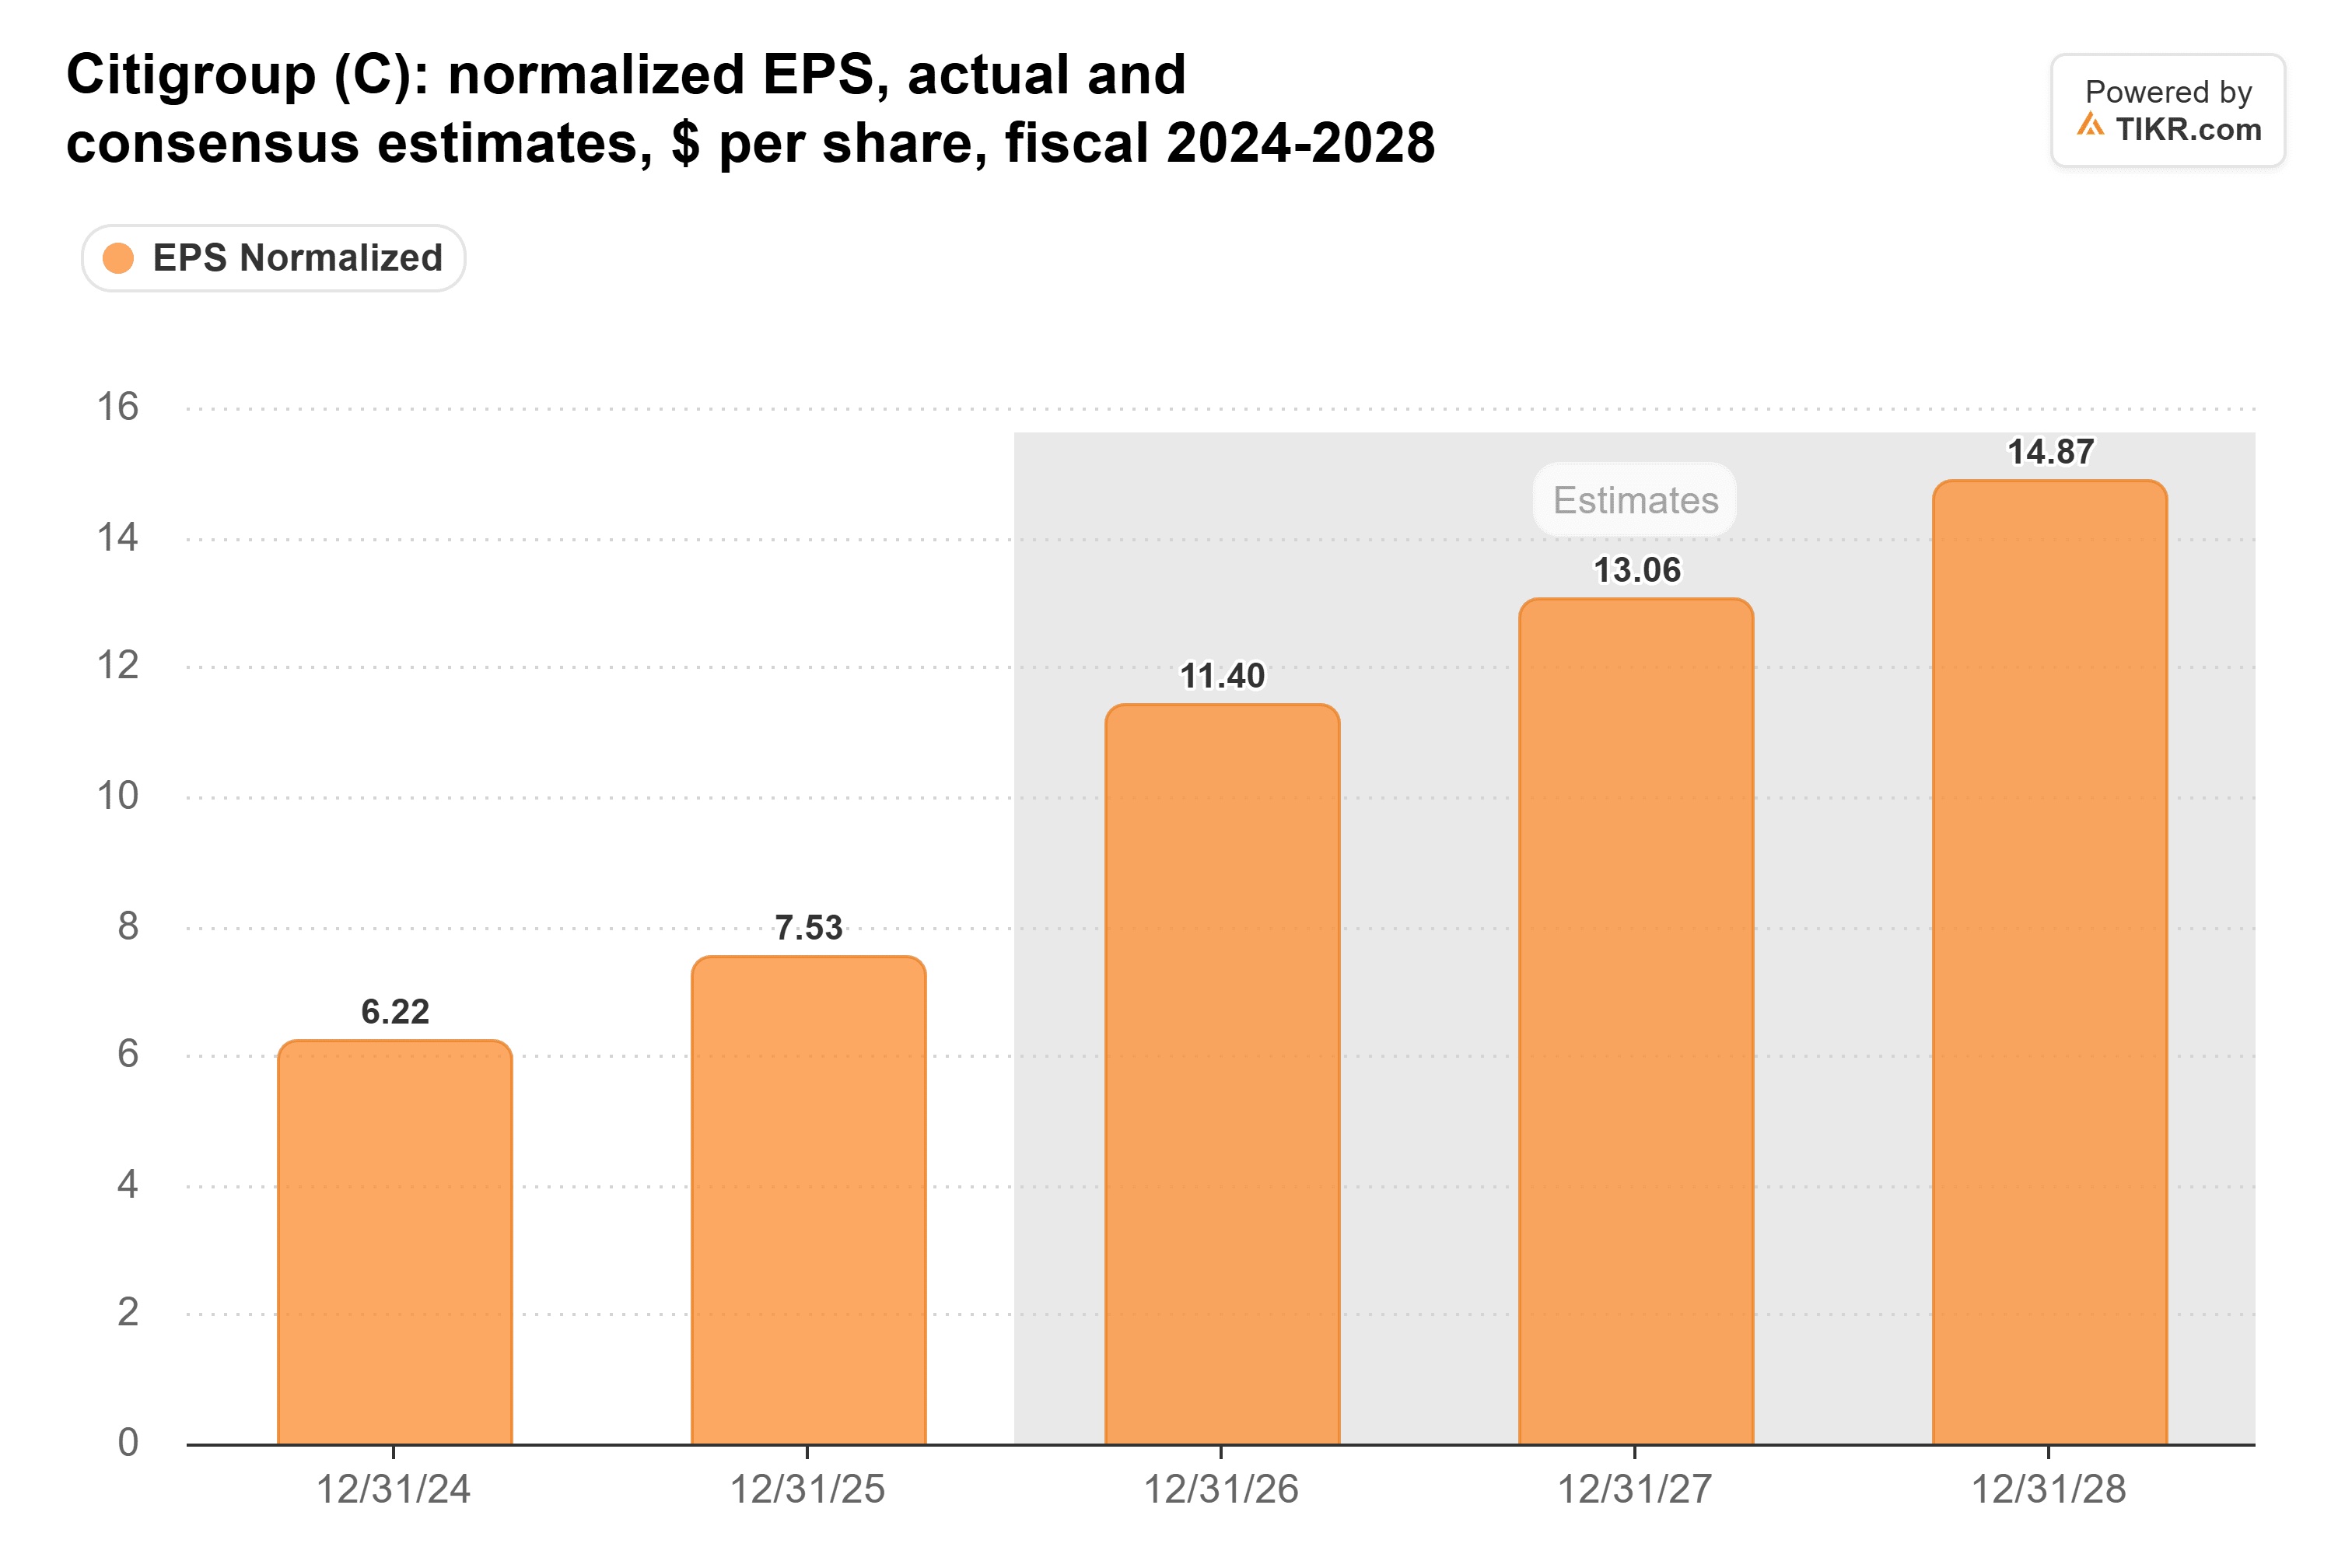
- Analysts have raised their 2026 and 2027 earnings estimates for Citigroup over the past three months, and TIKR’s consensus now sits at $11.40 a share for 2026 and $13.06 for 2027.
- HSBC’s target implies about 1.6x today’s tangible book value, above the 1.47x peak Citigroup hit in June, its highest in five years.
- Citigroup can likely earn its way to $158 as tangible book grows, but probably not within twelve months. Its fourth-quarter report and 2027 outlook on Jan. 14 are the next test.
Citigroup (C) is 17% below its June closing high, even after posting its best third-quarter revenue in a decade. On Nov. 12, HSBC kept its Buy rating on Citi and set a $158 price target, down from $164 but still 30% above the Nov. 16 close of $121.32.
A strong quarter, with a softer finish ahead
In Citi’s third quarter, reported Oct. 13, revenue rose 8% to $23.8 billion, earnings per share rose to $2.85 from $1.86, and Services grew revenue 15% at a 31.2% return on tangible common equity (RoTCE). CEO Jane Fraser said Citi expects “to exceed this year’s return target, even as we pull forward investments toward our 11-13% near-term goal.”
Returns did slip, though. Firmwide RoTCE fell to 11.5% from 13% in the second quarter. CFO Gonzalo Luchetti said fourth-quarter RoTCE should land “at a high single-digit rate,” with Markets revenue expected to fall about 20% from the third quarter, possibly a bit more.
TIKR tracks 23 analysts on Citigroup. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Citigroup, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Citigroup’s Analyst Ratings
Does 1.6x tangible book add up?
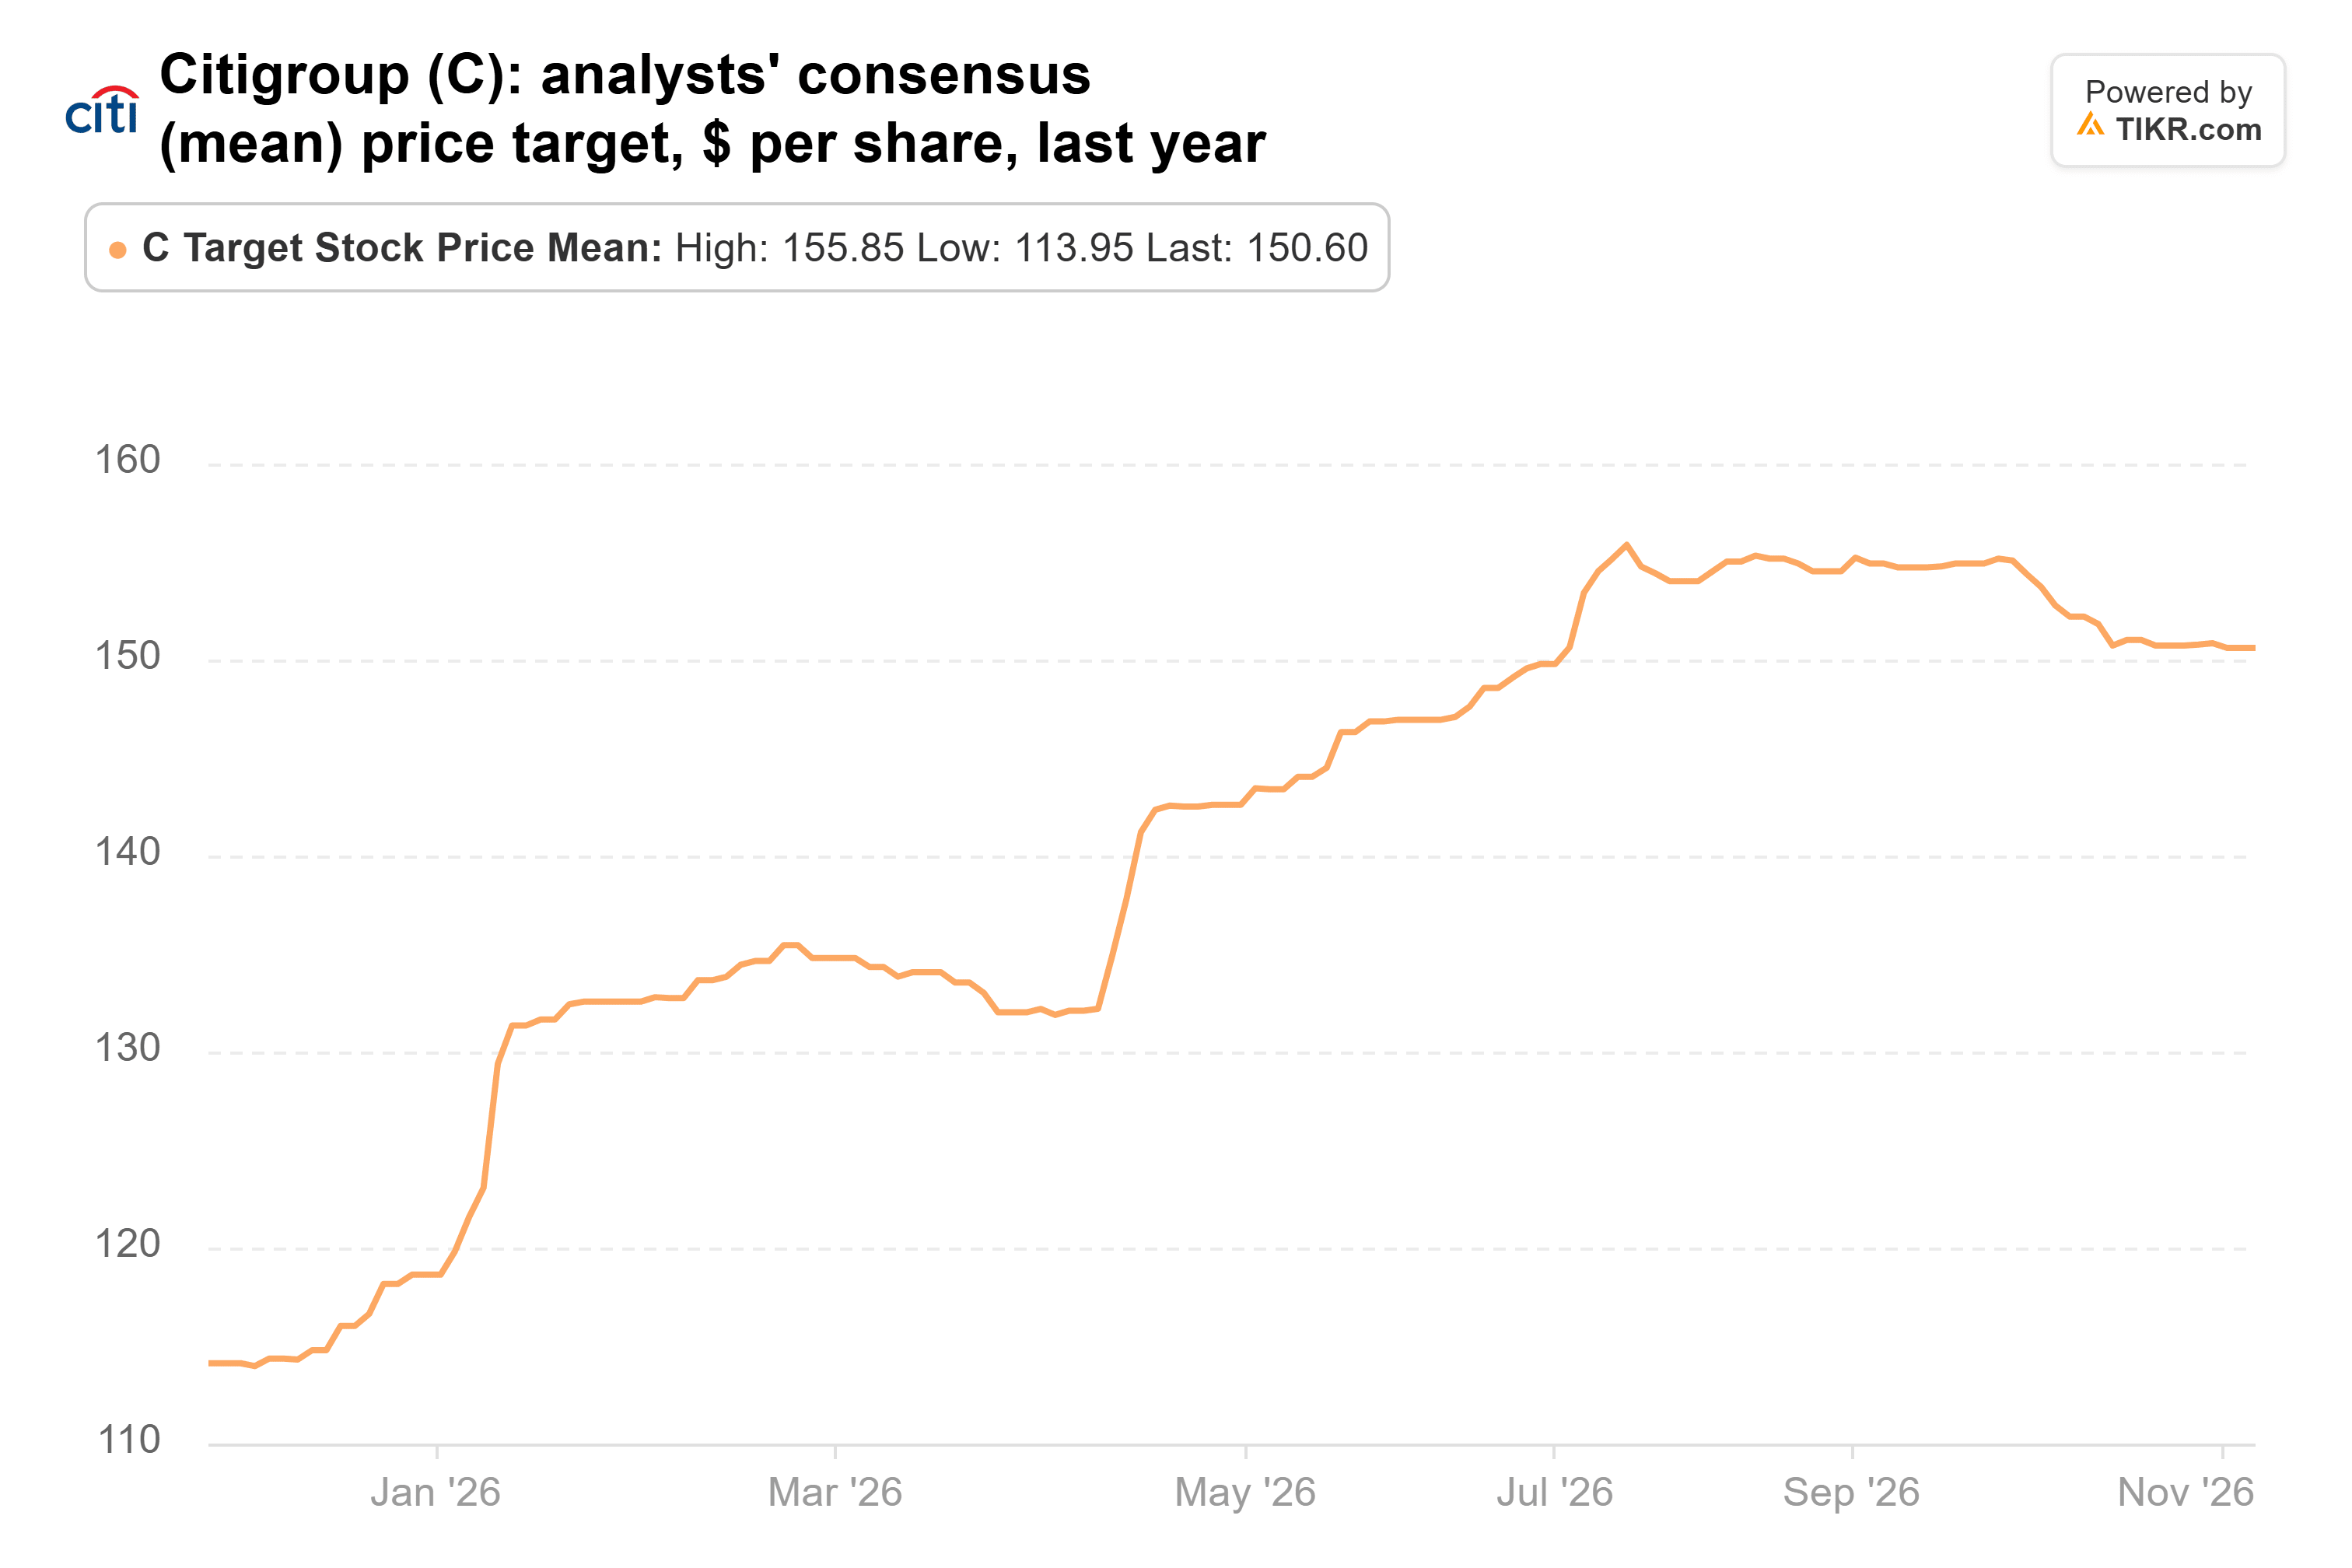
HSBC’s $158 target sits 5% above the $151 mean target of the 21 analysts with published targets, and the Street’s highest target is $170.
The consensus target rose from $114 a year ago to a peak of $156 in mid-July. It has eased to $151 since:
Earnings estimates are still rising. TIKR’s consensus calls for normalized EPS of $11.40 for 2026 and $13.06 for 2027. On Yahoo Finance’s tally, the 2026 estimate has risen to $11.19 from $10.91 three months ago, and 2027’s to $12.95 from $12.62:
The multiple is the harder part. Citi trades at 1.22x tangible book value, well above its five-year average of 0.81x:
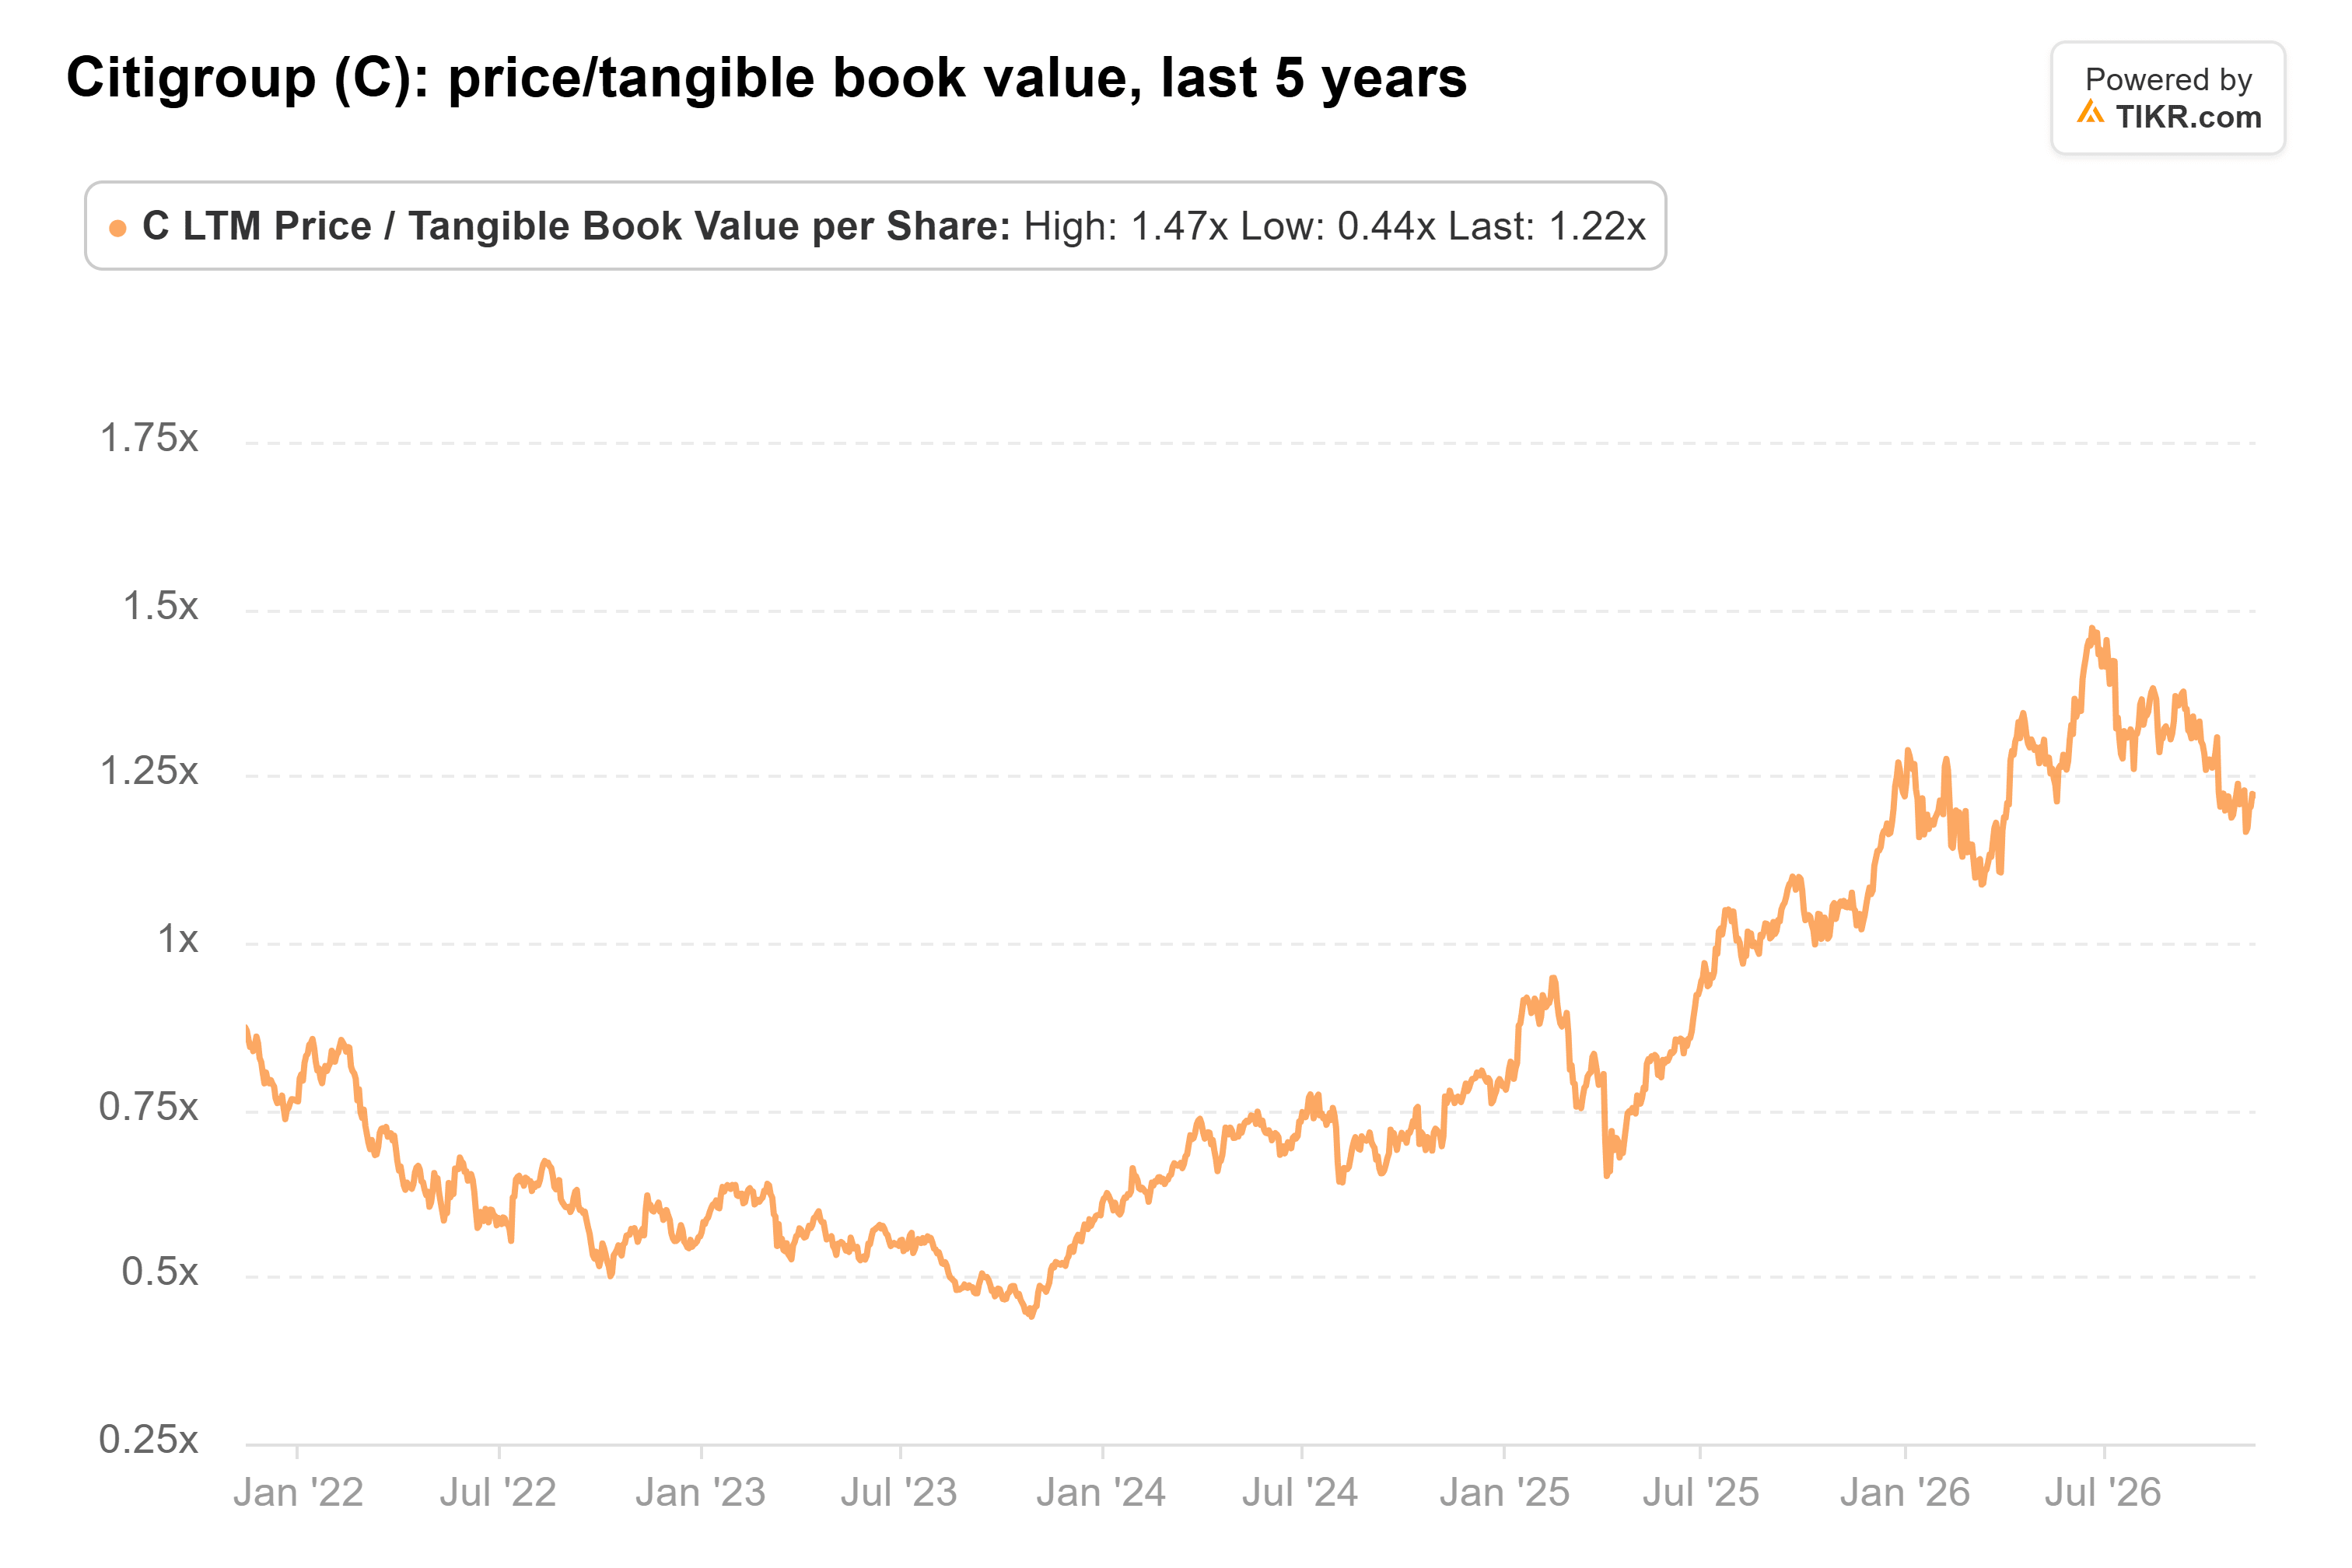
HSBC’s target works out to about 1.6x Citi’s tangible book value per share. That’s above the 1.47x peak of June 22, the highest of the last five years. Tangible book rose 6% in the year to Sept. 30, to $101.59 a share, and analysts expect $122.01 by the end of 2028. On that book, $158 would be about 1.3x, inside the range Citi has traded at this year.
Citi can get to $158, just more slowly
In early 2027, Citi expects to book an approximate $9 billion currency-translation loss when it deconsolidates Banamex. Luchetti said the deconsolidation should be slightly accretive to Citi’s CET1 capital ratio, so the charge should dent reported earnings without denting that ratio.
HSBC has the direction right: estimates are climbing. But for the stock to hit $158 within twelve months, investors would have to pay a multiple at or near June’s five-year peak, even after a year of book growth, just as returns dip. Citi more likely gets there as tangible book grows, just more slowly than HSBC’s target allows. The fourth-quarter report and 2027 outlook on Jan. 14 are the next test. If guidance keeps 11% to 13% returns in reach for 2027, the market may pay up sooner.
So what is Citigroup stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Citigroup could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!