Key Takeaways
- Constellation signed a 3,590 MW package with Google, including a 20-year PPA for 890 MW of new nuclear capacity from uprates.
- Shares closed at $253 on October 23, down 30.5% year to date and 38% below the 52-week high.
- The NRC opened a special inspection at the Dresden plant on October 14, adding a near-term operational question.
- The November 9 Q3 report should show whether 2026 adjusted operating EPS guidance of $11.50 to $12.50 holds.
Every hyperscaler seems to want nuclear power, and Constellation Energy (CEG) owns more of it than anyone in the U.S. That has not helped the stock much this year.
Shares closed at $253 on October 23, down 30.5% year to date and 38% below the $406.04 high. The slide continued even after Alphabet (GOOGL) signed a 3.6 GW power package on October 6.
Eight days later, the NRC opened a special inspection at the Dresden plant in Illinois. So investors now hold record contracts alongside an operational question.
Google commits for two decades
The Google package has two pieces, and they carry different economics:
- A 20-year PPA for 890 MW of new capacity from uprates at 11 Constellation-owned units in Illinois, Pennsylvania and New Jersey
- A 15-year supply agreement for another 2,700 MW from the existing PJM fleet
- More than $4.3 billion of Constellation investment, with the first uprate online in 2028 and all 890 MW by the end of 2032
A week earlier, Amazon (AMZN) signed a 20-year PPA for 690 MW at Calvert Cliffs, including a roughly 190 MW uprate due between 2030 and 2032.
CEO Joe Dominguez said expanding the existing fleet is “critical to meeting our nation’s growing energy needs.”
Earnings power had already turned before these deals…
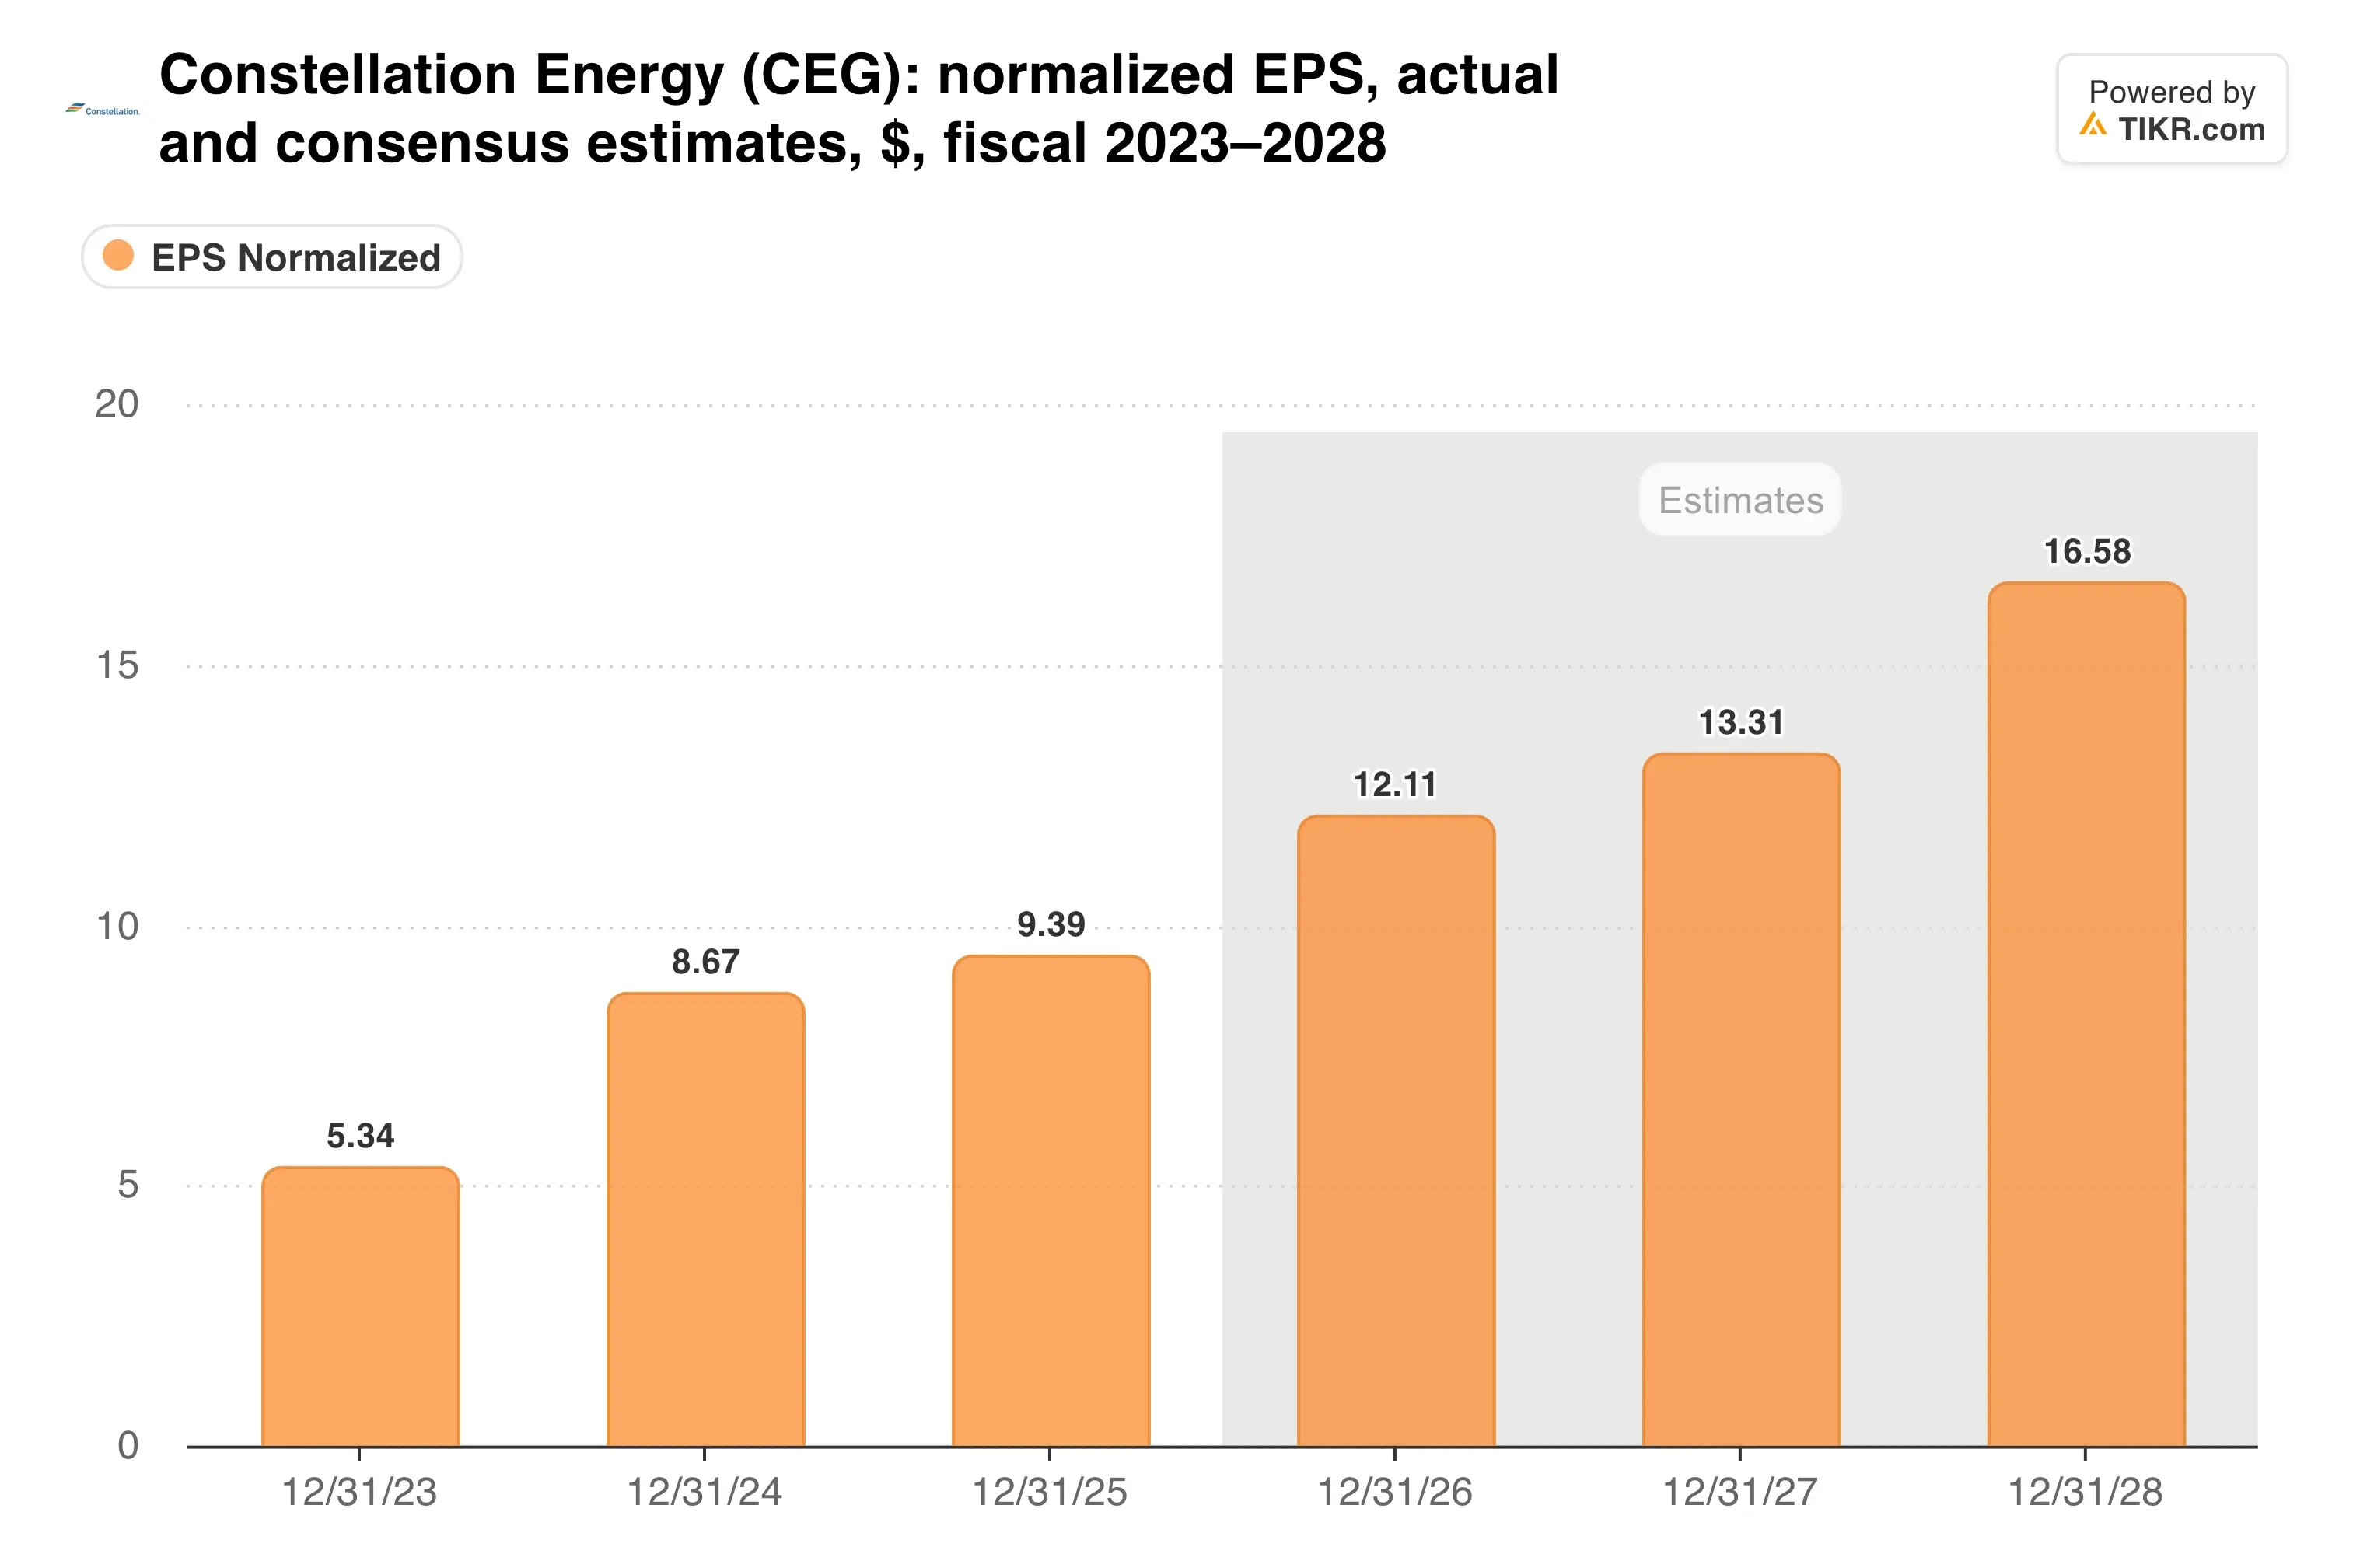
Consensus EPS keeps climbing through 2028, so analysts are layering new contracts onto an already raised base.
Uprates are the scarce asset
Uprates are the fastest path to new nuclear megawatts. They use existing sites, licenses and grid connections, so they skip the interconnection queue.
Google and Amazon together now back about 1,080 MW of planned Constellation uprates under long-term contracts. That turns capital spending into contracted returns.
The base business supports the bet. Q2 revenue rose 23% to $7.50 billion with help from Calpine, and adjusted operating EPS rose 33% to $2.55.
Management then raised 2026 adjusted operating EPS guidance to $11.50 to $12.50.
Vistra (VST) is running the same playbook with 433 MW of uprates for Meta, backed by up to $4.2 billion of conditional federal loans.
Here is what the spending side looks like…
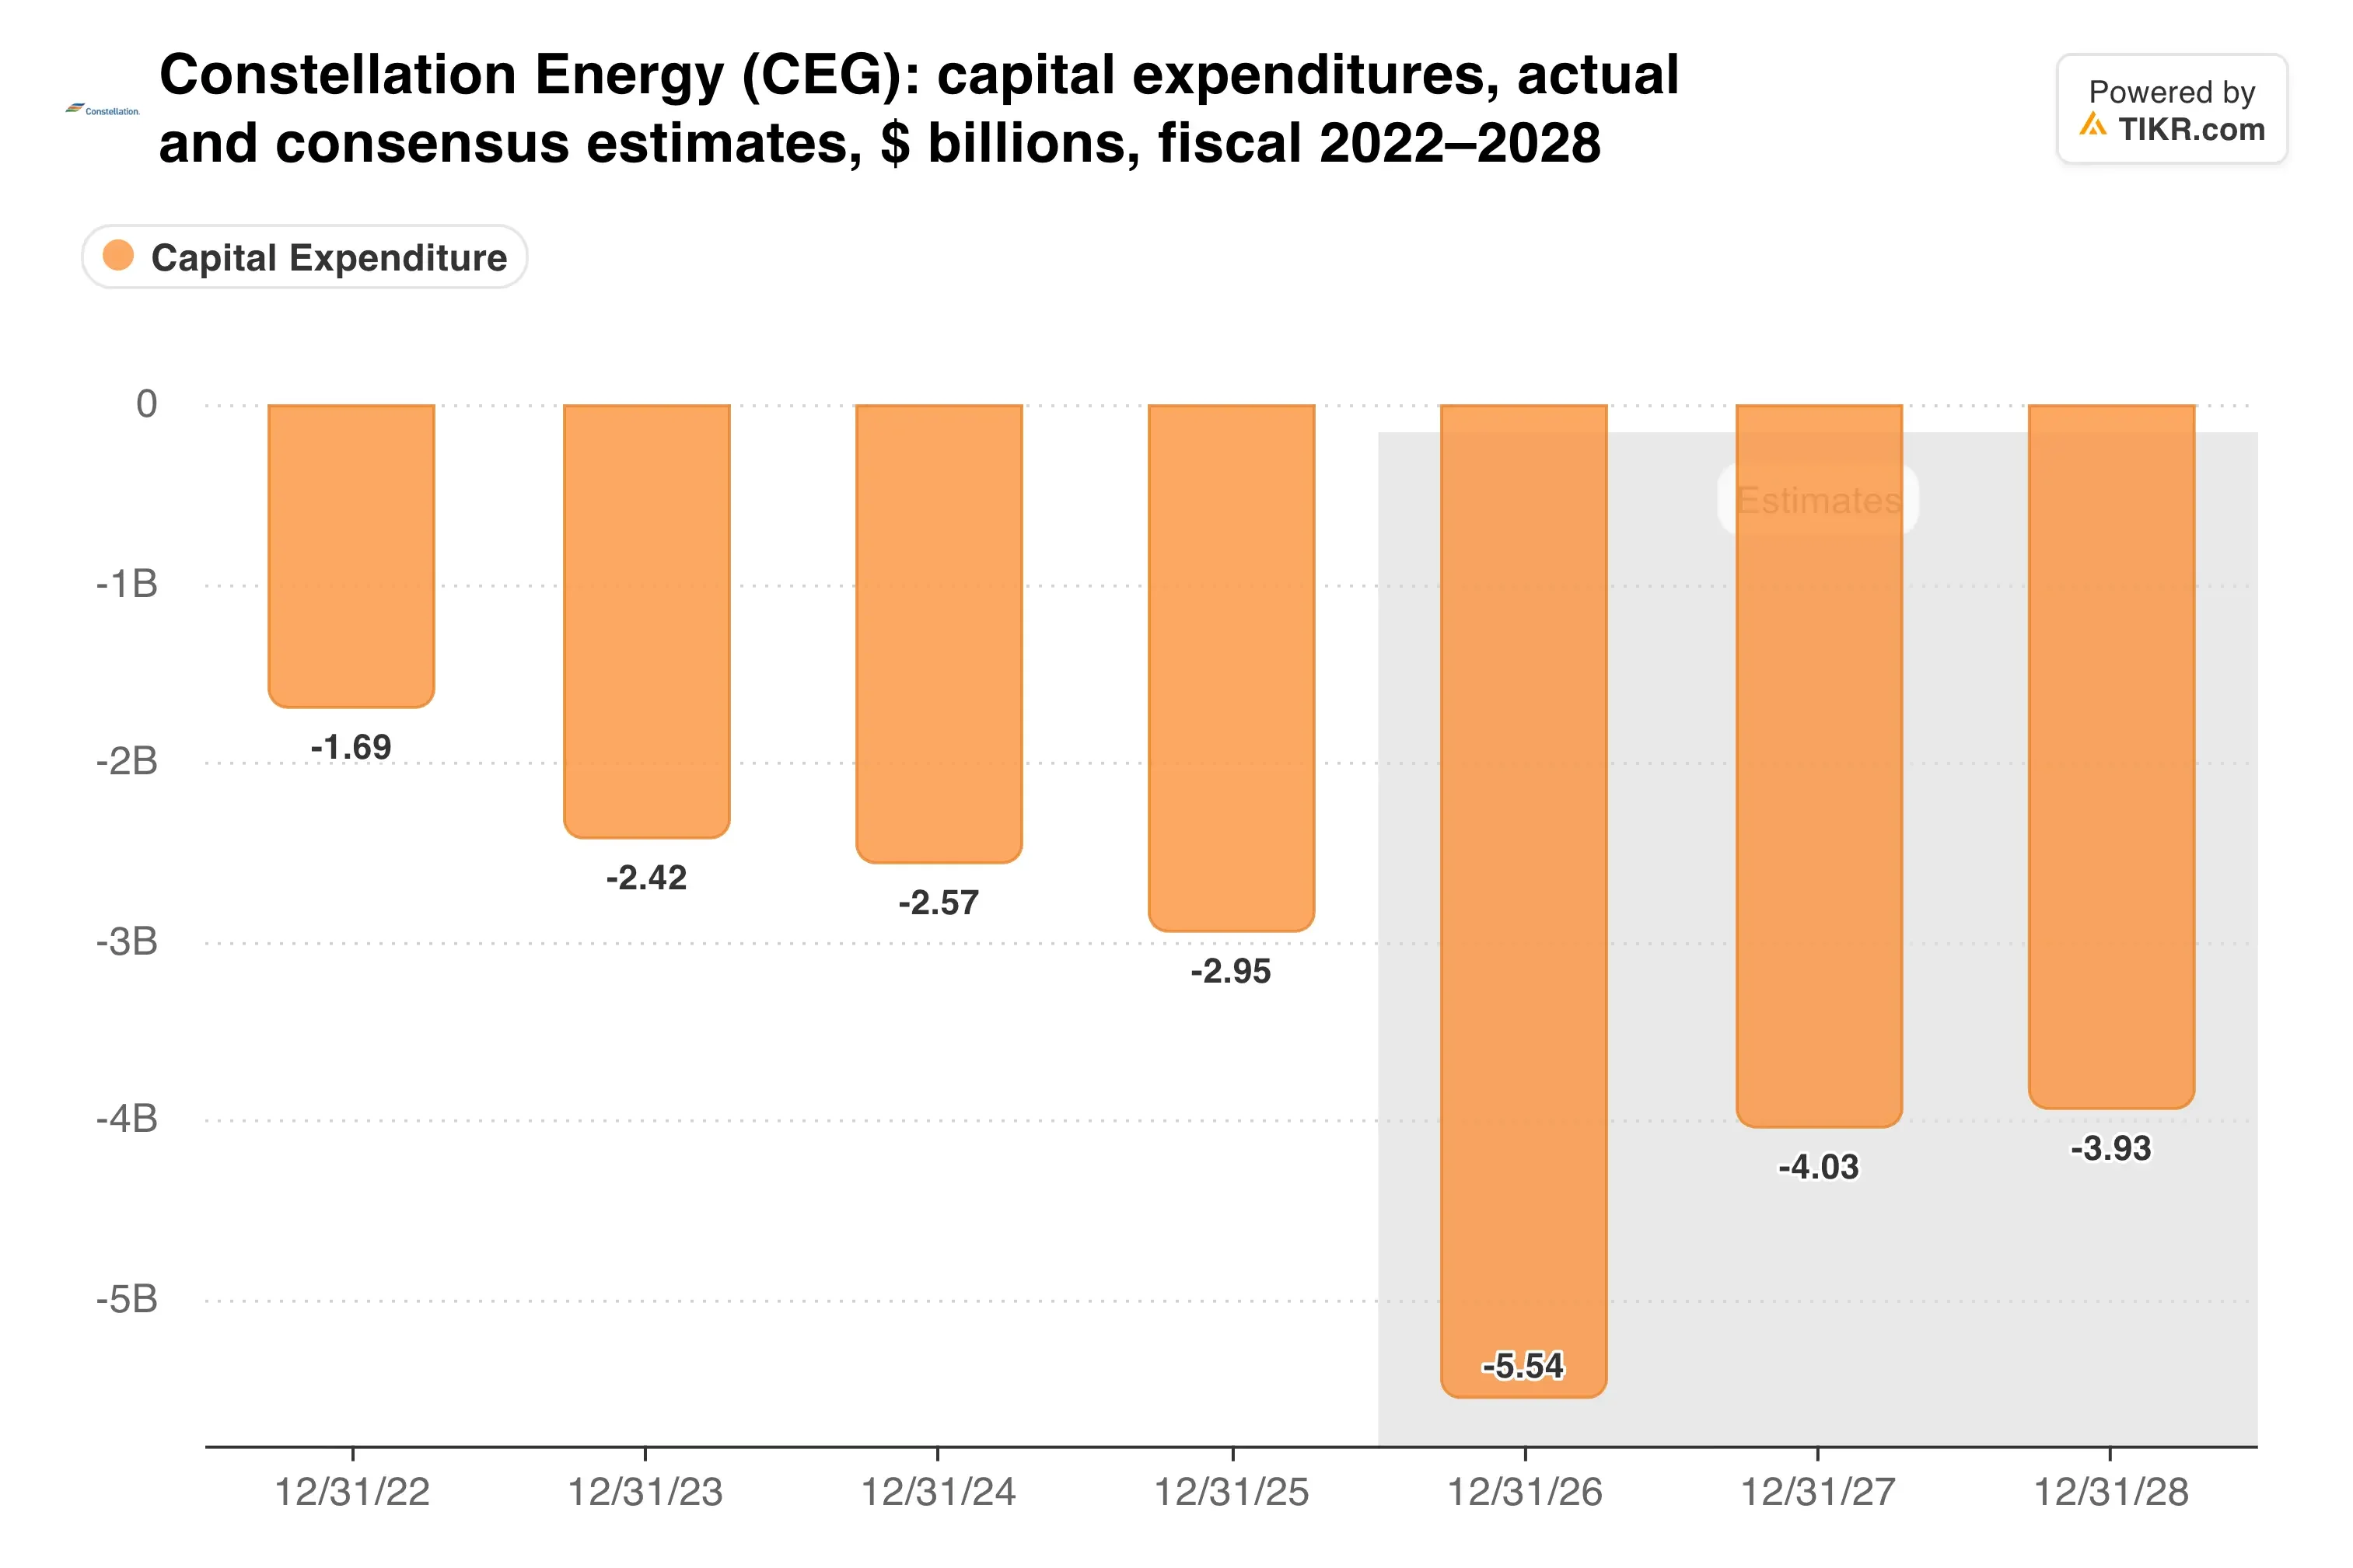
Capex is rising to match the uprate pipeline, and hyperscaler contracts now underwrite much of it.
TIKR tracks 25 analysts on Constellation Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Constellation Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Constellation Energy’s Analyst Ratings
Reliability now carries the multiple
Operations are the soft spot. Nuclear output fell 2.2% in Q2 to 44,160 GWh, and the capacity factor excluding Salem and South Texas slipped to 93.0% from 94.8% on more refueling days.
GAAP diluted EPS also dropped to $1.42 from $2.67. Now the Dresden inspection lands right before Q3.
Valuation has already absorbed a lot of that worry.
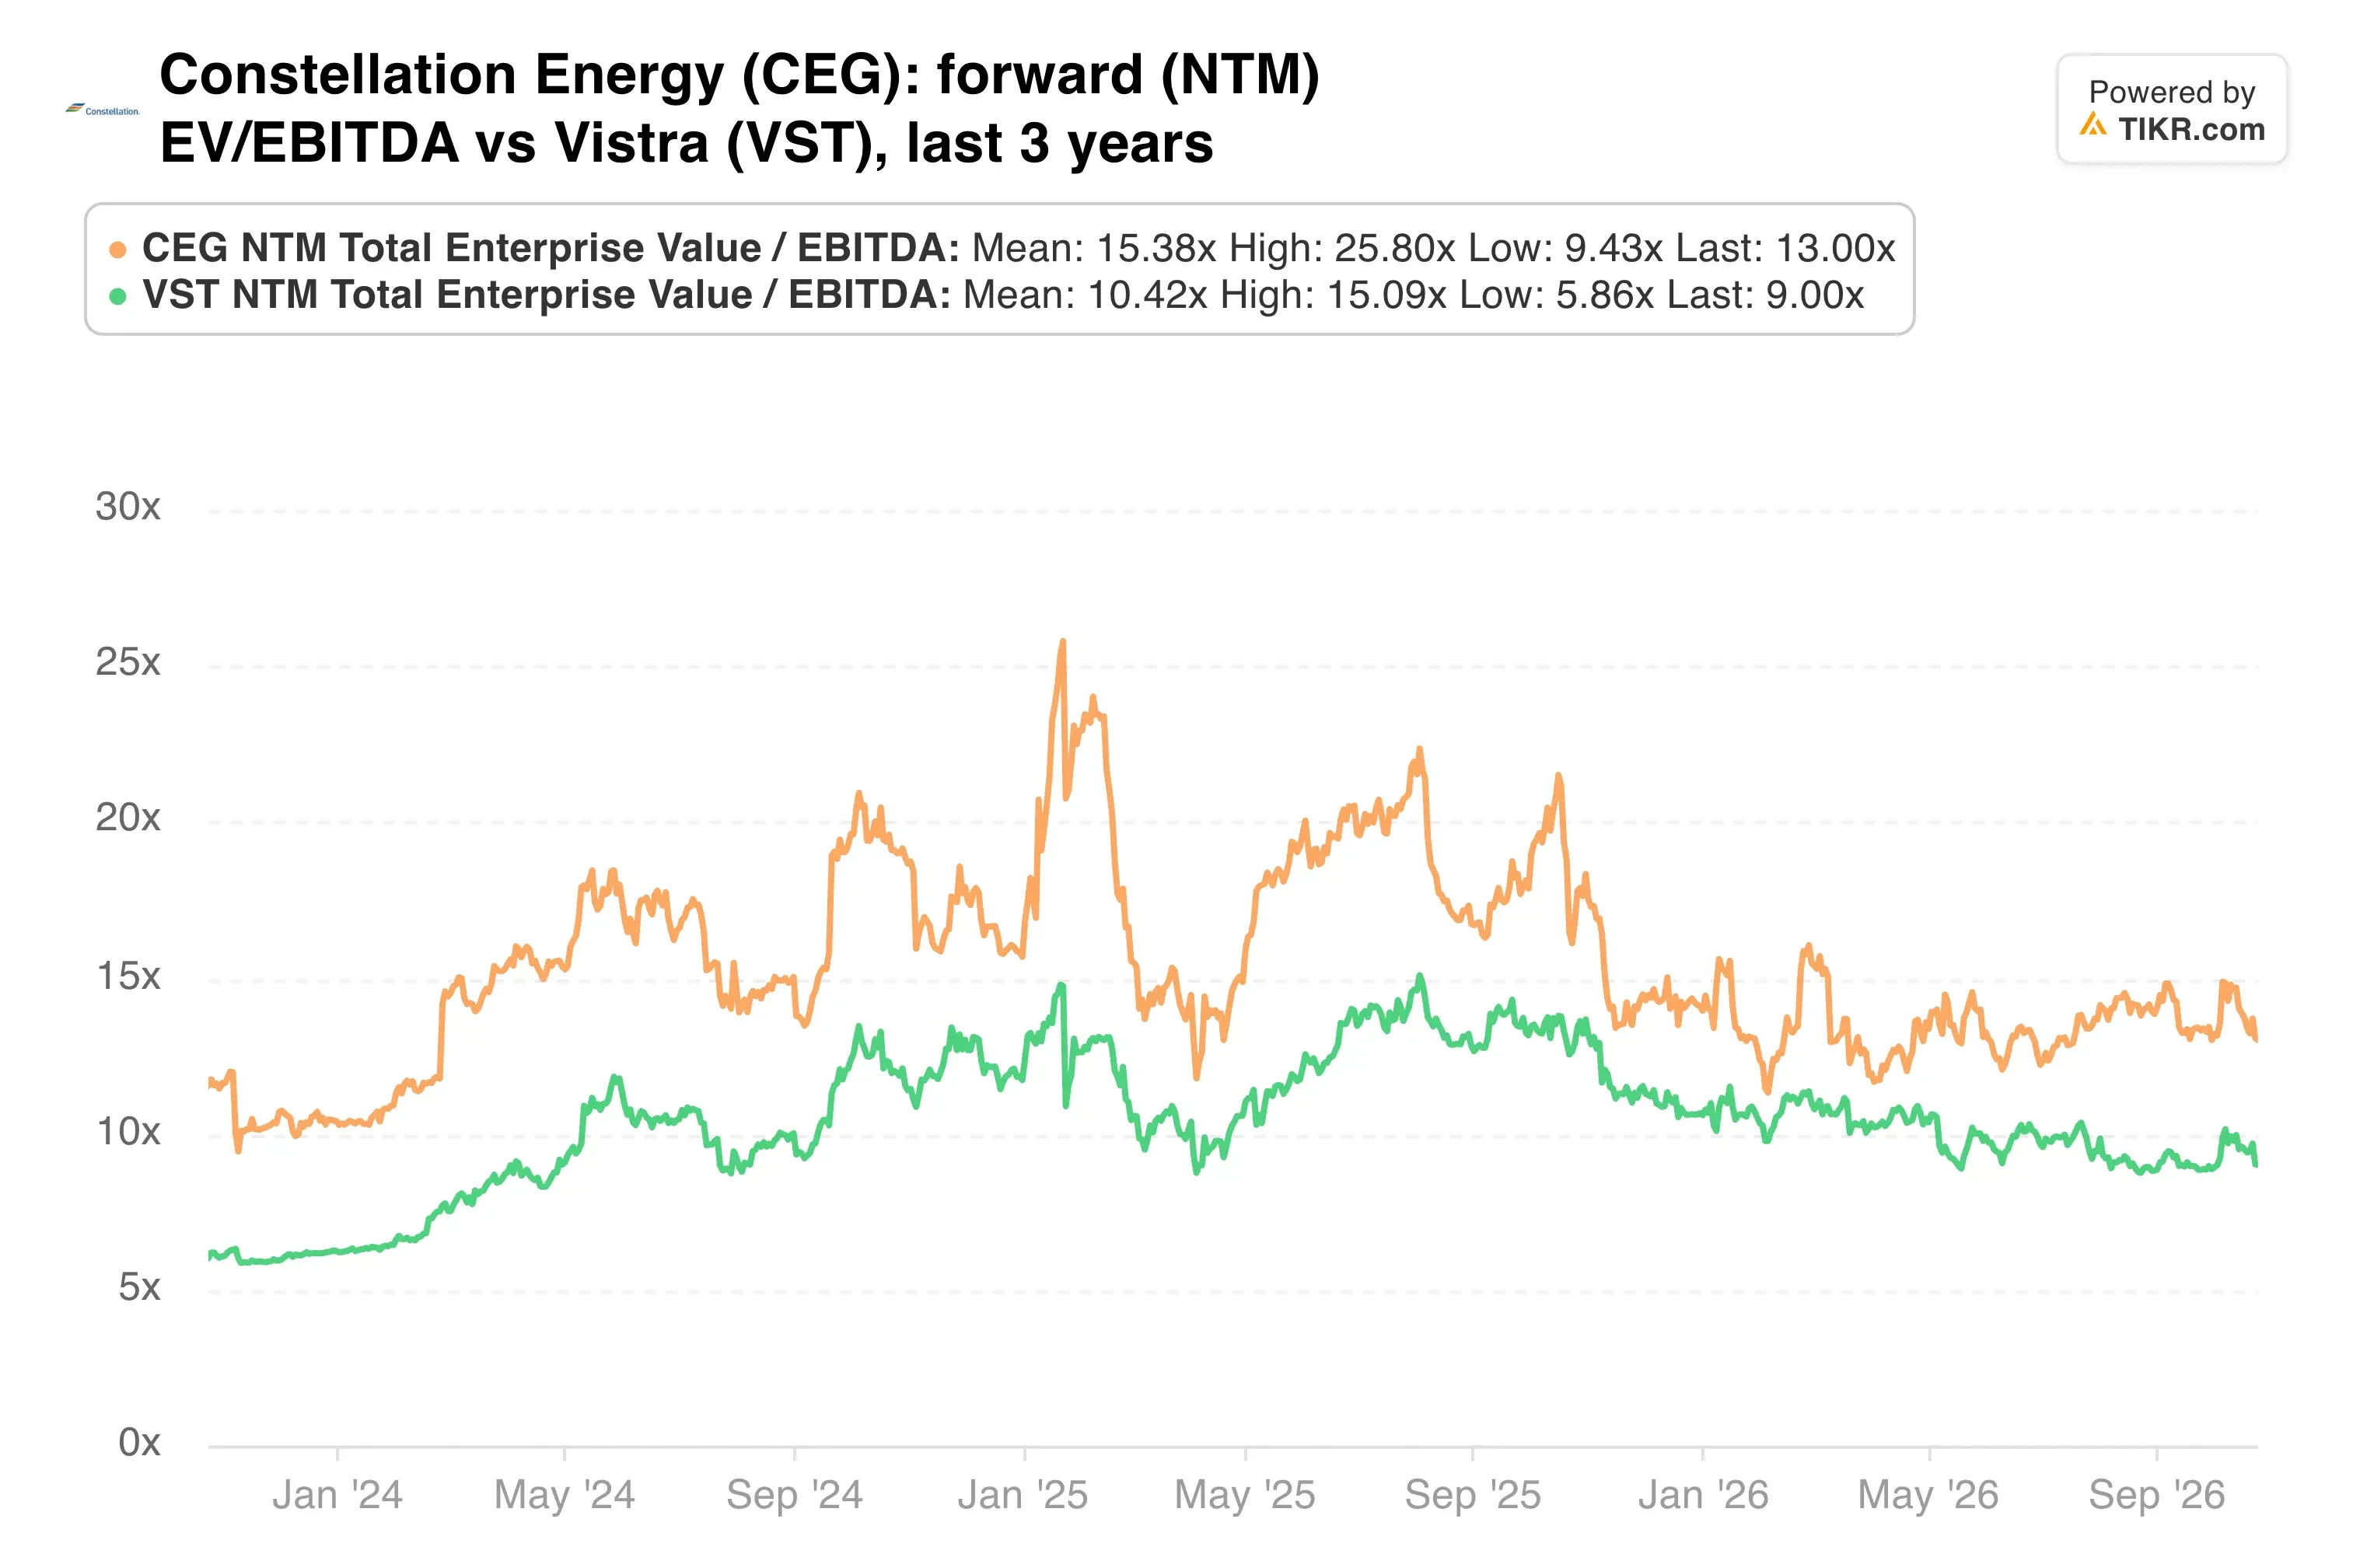
Constellation trades at 13.0x forward EV/EBITDA against 9.0x for Vistra, so it still carries a premium for fleet quality.
Leverage stays manageable at about 3.0x net debt to EBITDA, and the Brazos Valley sale to LS Power closed on October 15.
My take: Long-dated contracts with Google and Amazon make Constellation’s earnings more predictable than a 30% drawdown implies. The risk is operational, since uprates and premium pricing both depend on reactors running near 93% or better. At 20.5x forward earnings against a $338 Street target, I think the setup favors patient holders, assuming Dresden stays contained.
The November 9 Q3 report is the next checkpoint. Look for an update on Dresden, nuclear capacity factors and whether guidance moves toward the top of the range.
So what is Constellation Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Constellation Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!