Key Takeaways
- Cipher Digital (CIFR) has approximately $9.1 billion in contracted revenue at Barber Lake, representing about 55% of its $16.6 billion contracted portfolio.
- Alphabet (GOOGL) has agreed to invest approximately $10 billion in Anthropic’s planned IPO-related private placement, potentially strengthening the AI developer’s ability to fund infrastructure.
- Cipher’s total debt increased from $2.77 billion at the end of 2025 to $5.62 billion in September 2026, highlighting financing risks associated with its data center expansion.
- Cipher traded at approximately 4.7x forward sales in TIKR’s November 9 data, below its three-year average of 11.4x, while analysts projected revenue to reach $828 million in 2027.
What Happened?
Cipher Digital (CIFR) could benefit indirectly from Anthropic’s planned IPO as the AI developer prepares to raise billions of dollars to support its expanding computing infrastructure.
According to Anthropic’s November 10 amended prospectus, the proposed offering includes 825 million shares priced between $70 and $78, representing up to $64.35 billion in gross offering value.
Anthropic plans to sell approximately 801.4 million newly issued shares, while existing stockholders plan to sell another 23.6 million. The company will not receive proceeds from existing shareholders’ sales.
Alphabet (GOOGL) has also agreed to invest approximately $10 billion through a concurrent private placement, part of a broader $26 billion financing involving other major technology companies.
The connection matters because Cipher’s Barber Lake data center in Colorado City, Texas, is associated with Anthropic’s expanding AI infrastructure.
Cipher has an initial 10-year lease with Fluidstack and a separate commitment for a subsequent 10-year lease with an unnamed AI lab. Epoch AI identifies Anthropic as the campus’s computing user.
Cipher, Fluidstack, and Anthropic also jointly committed $10 million toward improvements to Colorado City’s water infrastructure, providing further evidence of their operational relationship.
According to Cipher’s third-quarter business update, the September lease expansion increased Barber Lake’s contracted revenue to approximately $9.1 billion, including $5.2 billion in additional commitments.
Cipher CEO Tyler Page highlighted growing AI infrastructure demand, stating, “Demand for compute is growing, and our relationships with leading hyperscalers and AI labs are deepening.”
However, Cipher has not publicly identified Anthropic as the counterparty to its second 10-year lease, and the planned IPO does not directly change the value or timing of Cipher’s existing contracts.
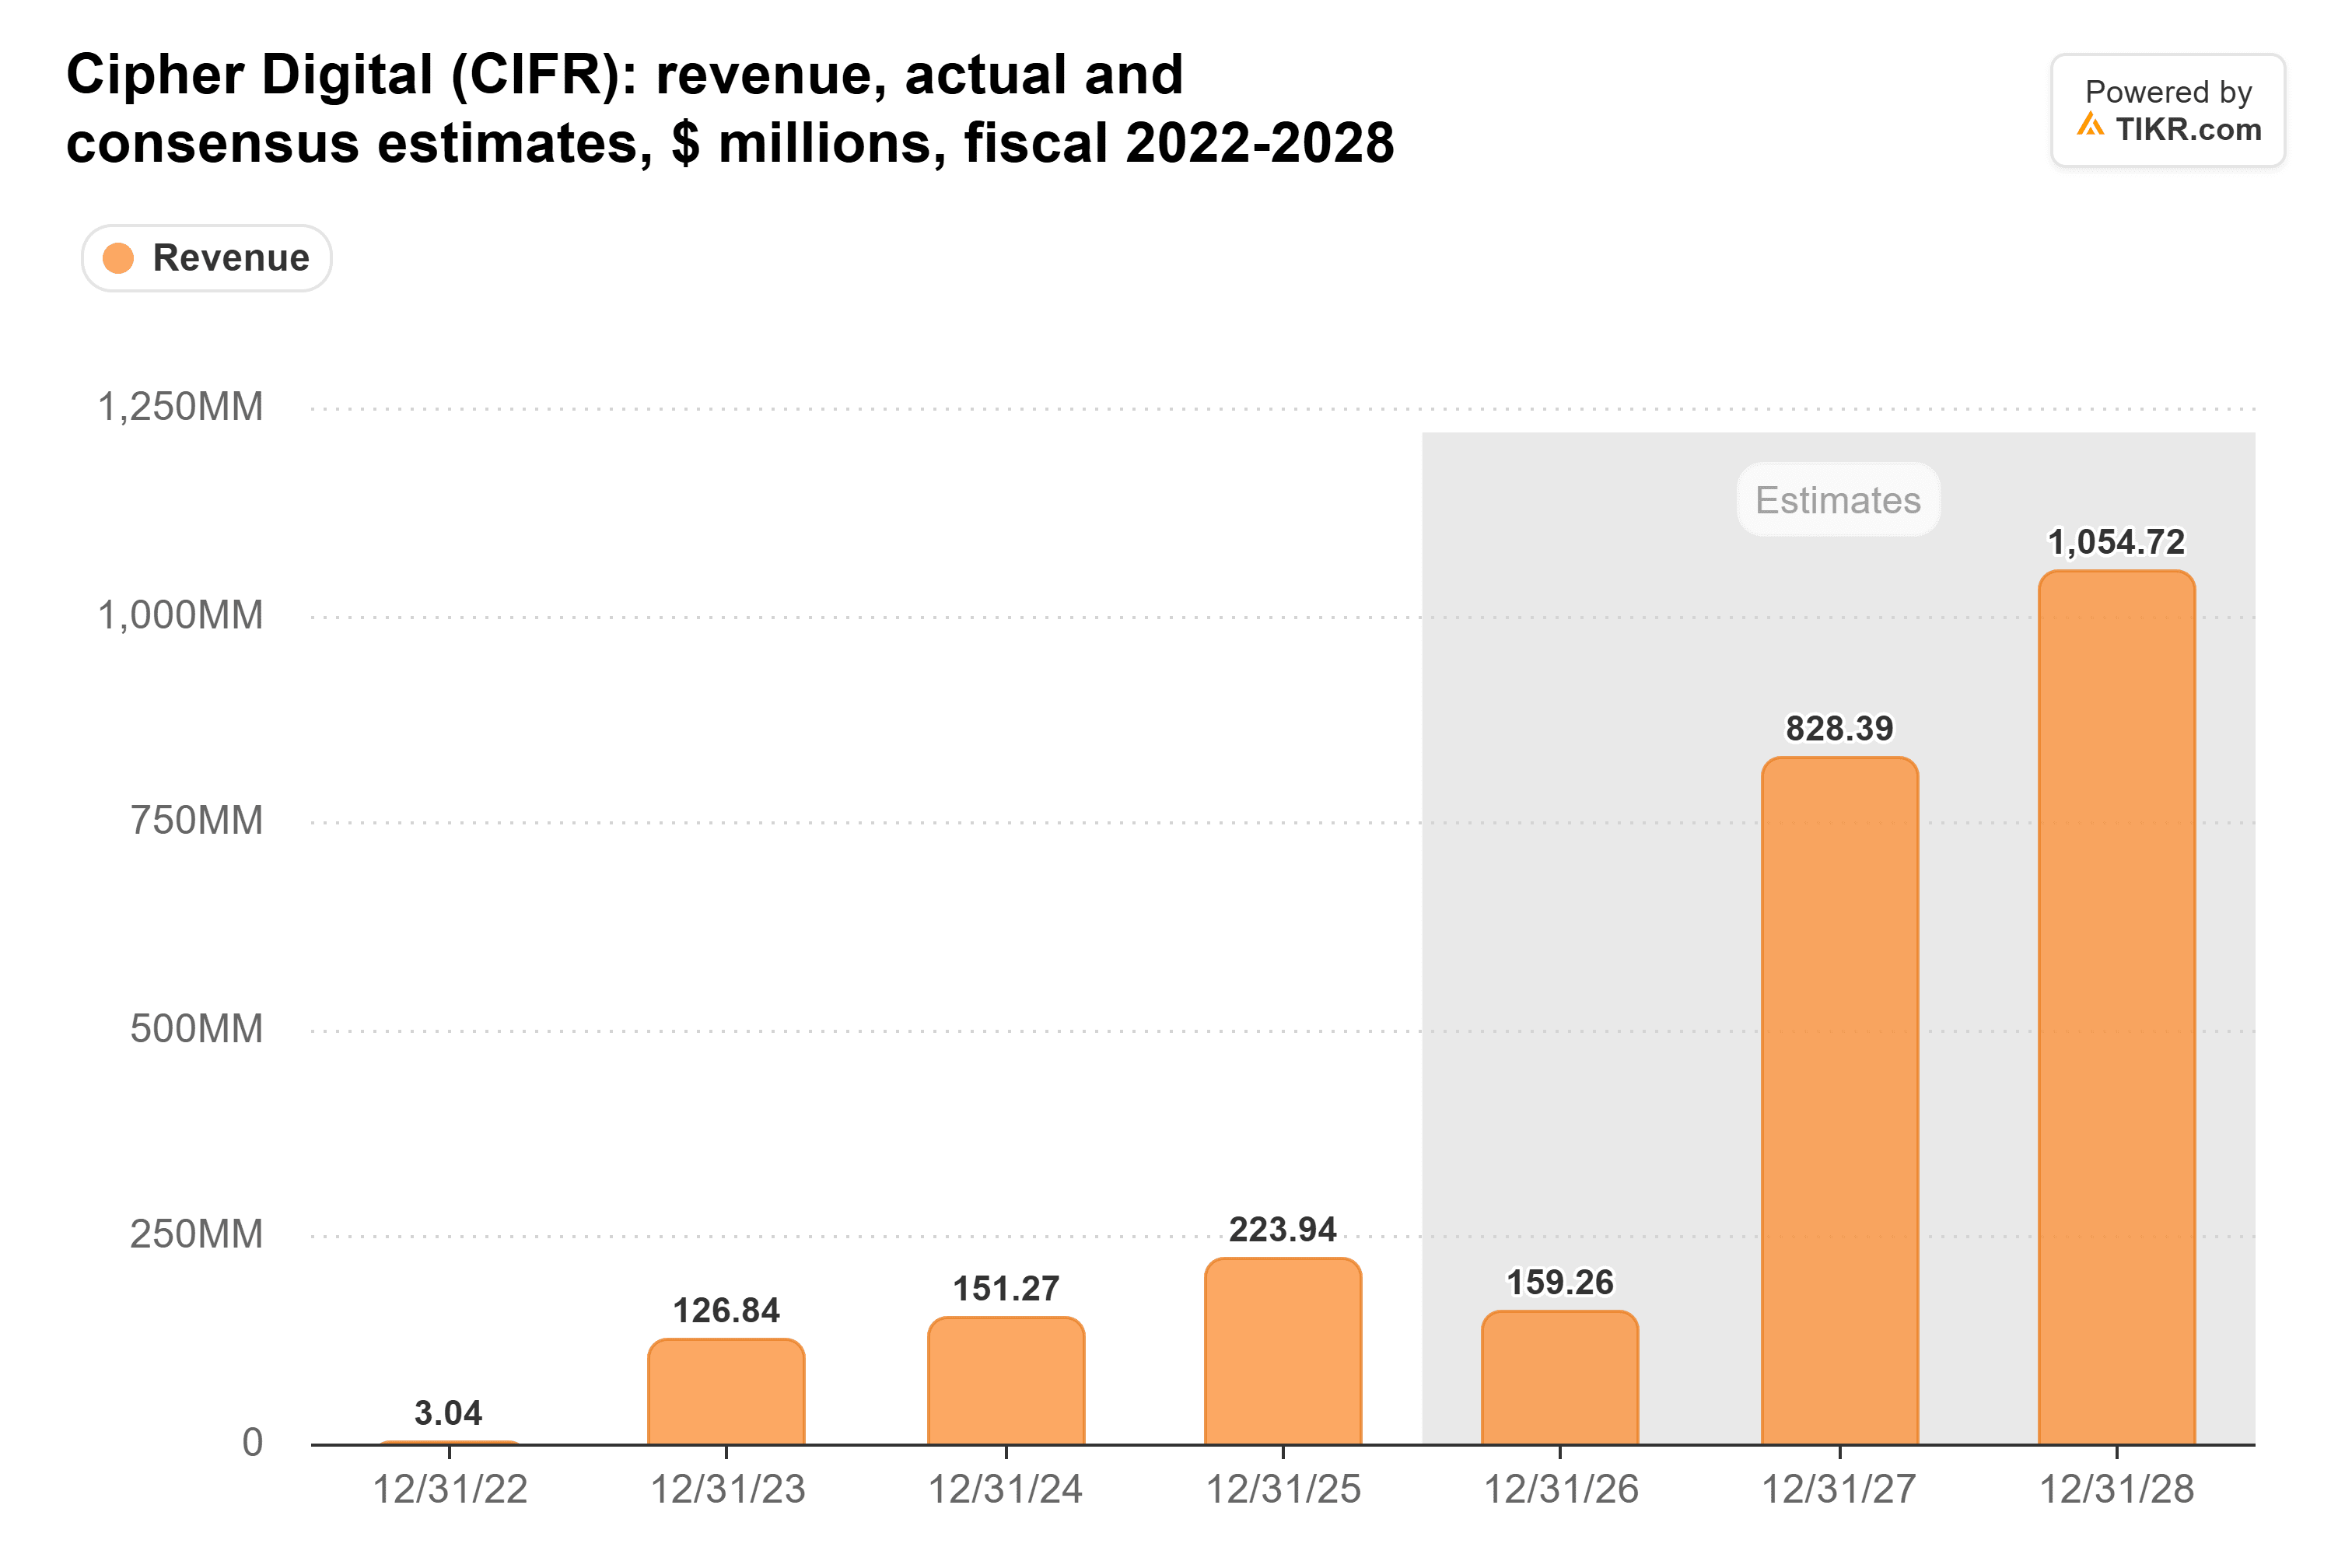
According to TIKR estimates dated November 9, Cipher’s revenue is projected to decline from approximately $224 million in 2025 to $159 million in 2026 before rising to $828 million in 2027 and $1.05 billion in 2028.
The expected recovery reflects Cipher’s transition away from bitcoin mining toward contracted AI data center infrastructure.
Cipher recognized its first high-performance computing lease revenue at Black Pearl during the third quarter, while Barber Lake’s data halls are scheduled for phased delivery from the fourth quarter of 2026 through the first quarter of 2027.
Importantly, Barber Lake’s $9.1 billion represents revenue contracted over future lease periods, not revenue already collected.
Is Cipher Digital Stock Undervalued or Overvalued?
Cipher appears potentially undervalued relative to its historical forward sales multiple, although substantial financing requirements and execution risks could justify part of its valuation discount.
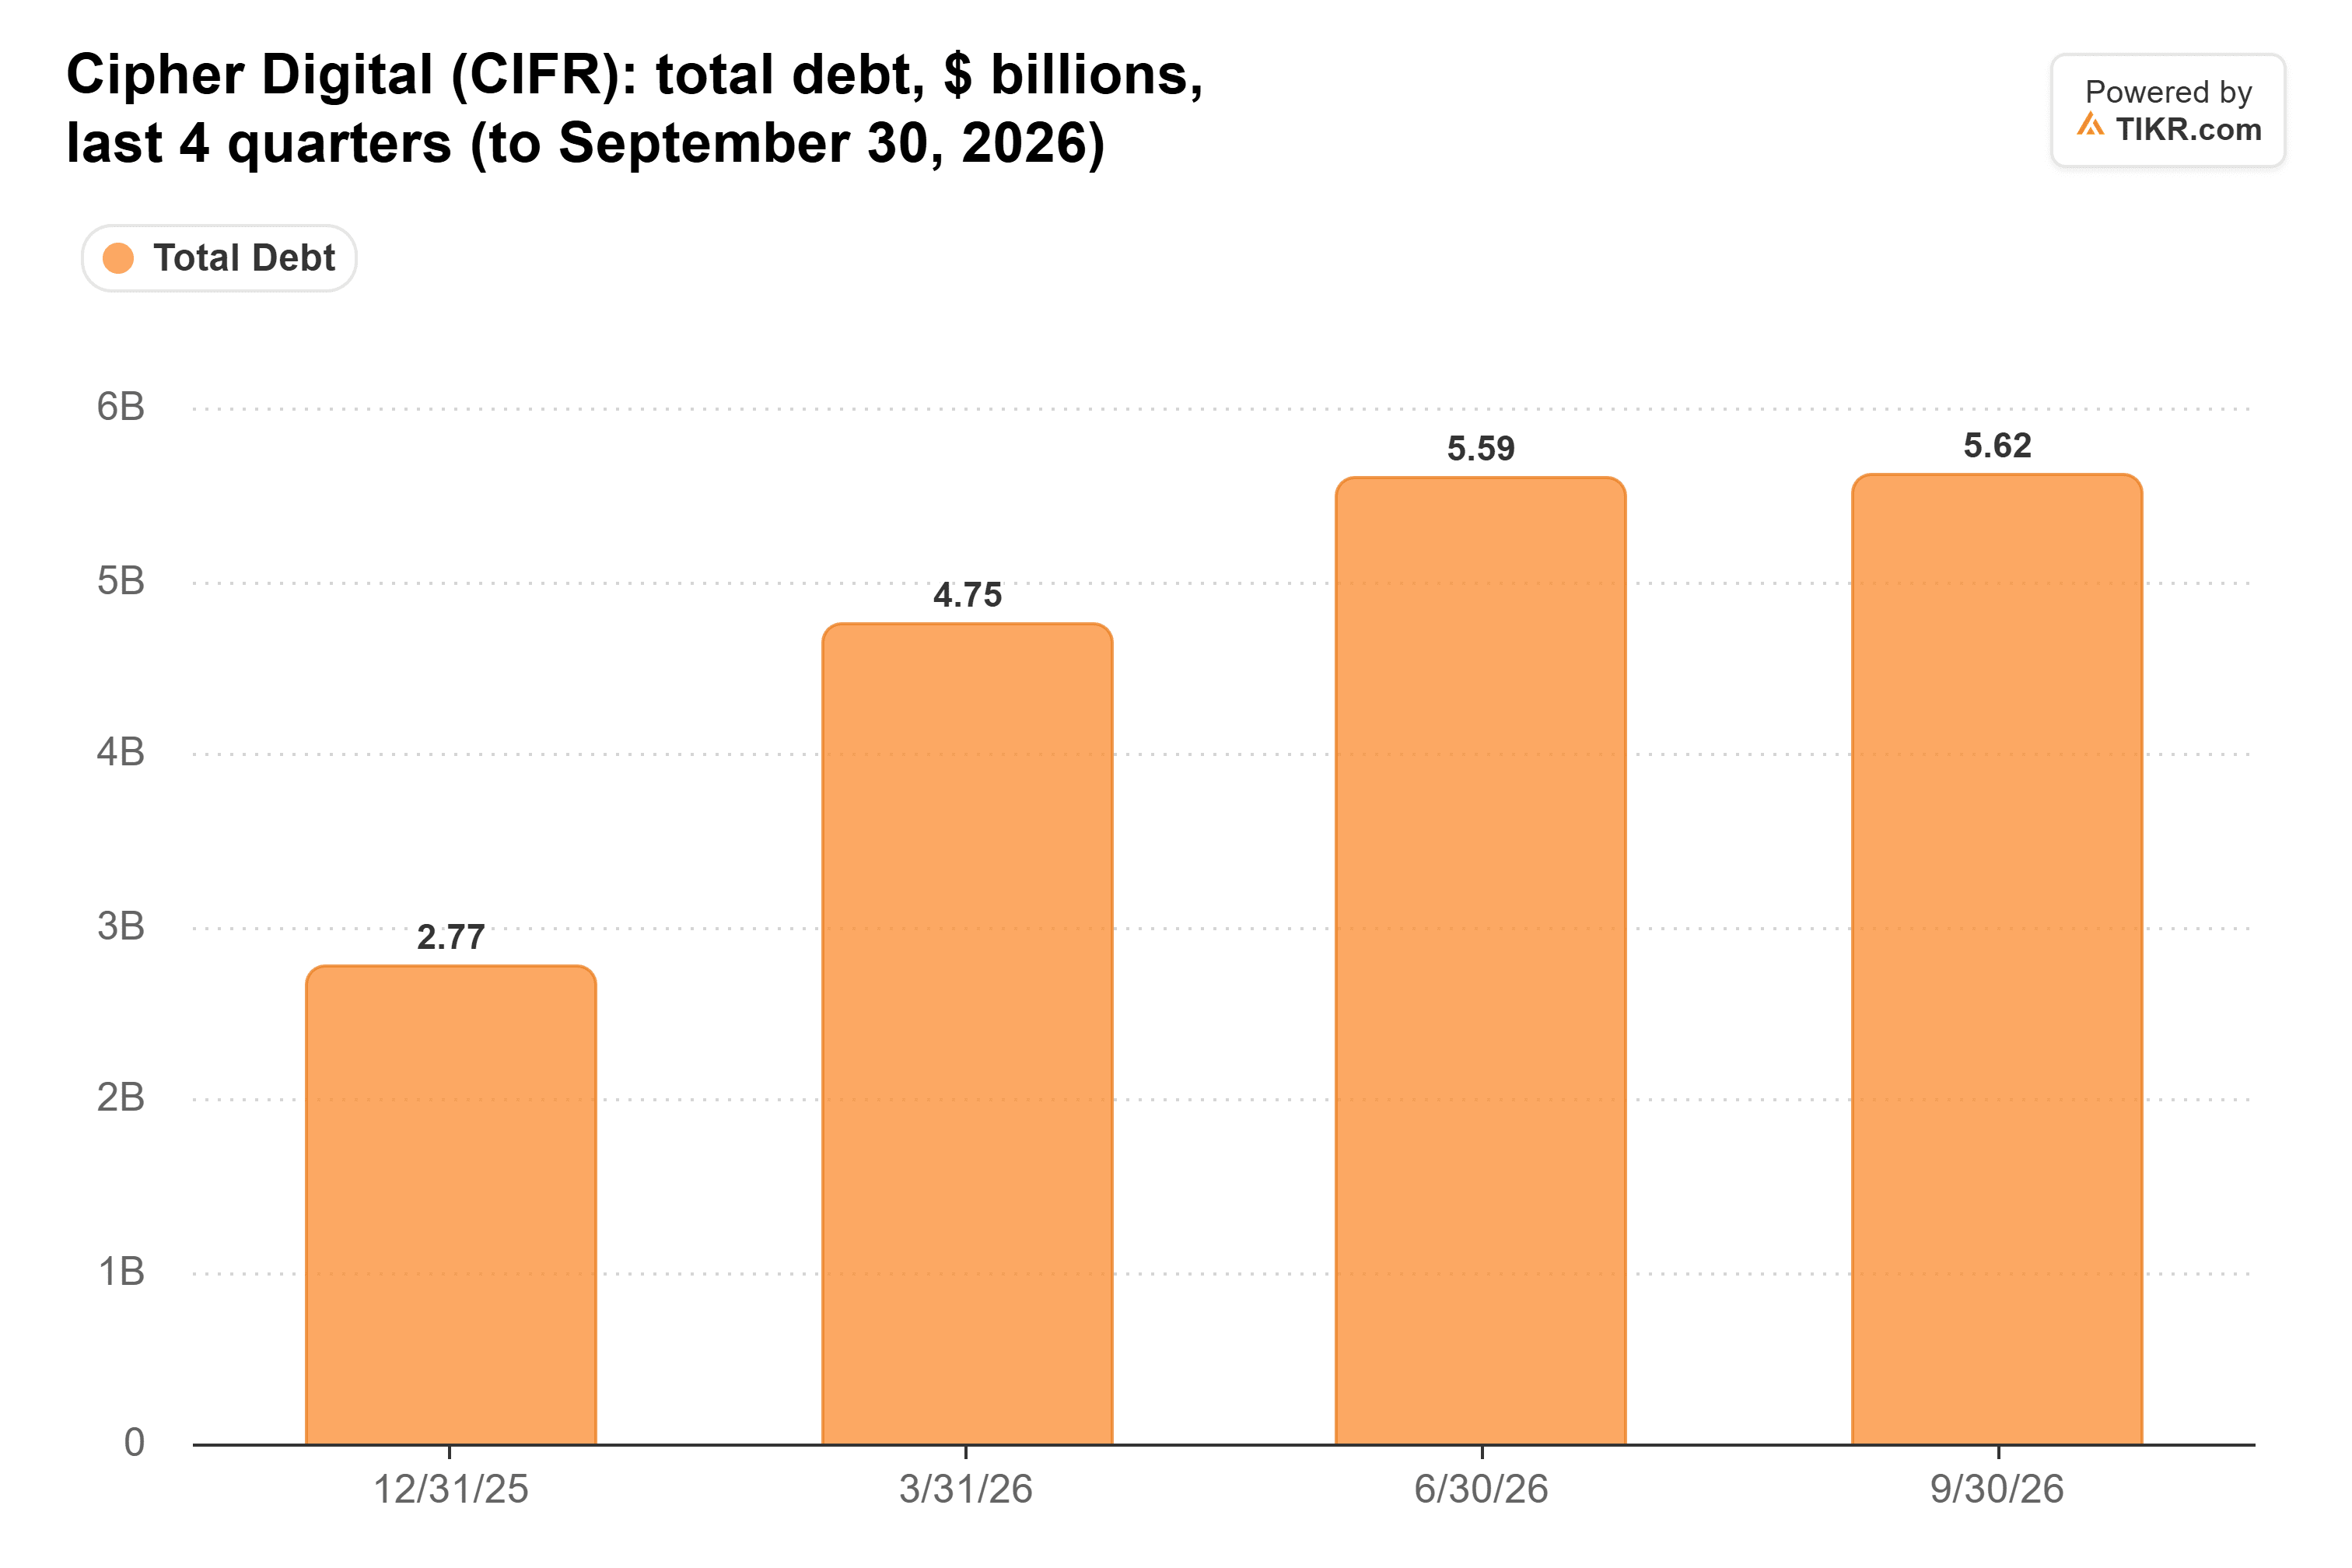
According to TIKR financials, total debt increased from $2.77 billion in December 2025 to $5.62 billion in September 2026, while Cipher held approximately $660 million in cash and short-term investments.
The company also completed an $850 million offering of 0% convertible notes in October, partly funding additional investment in Barber Lake while introducing potential future shareholder dilution.
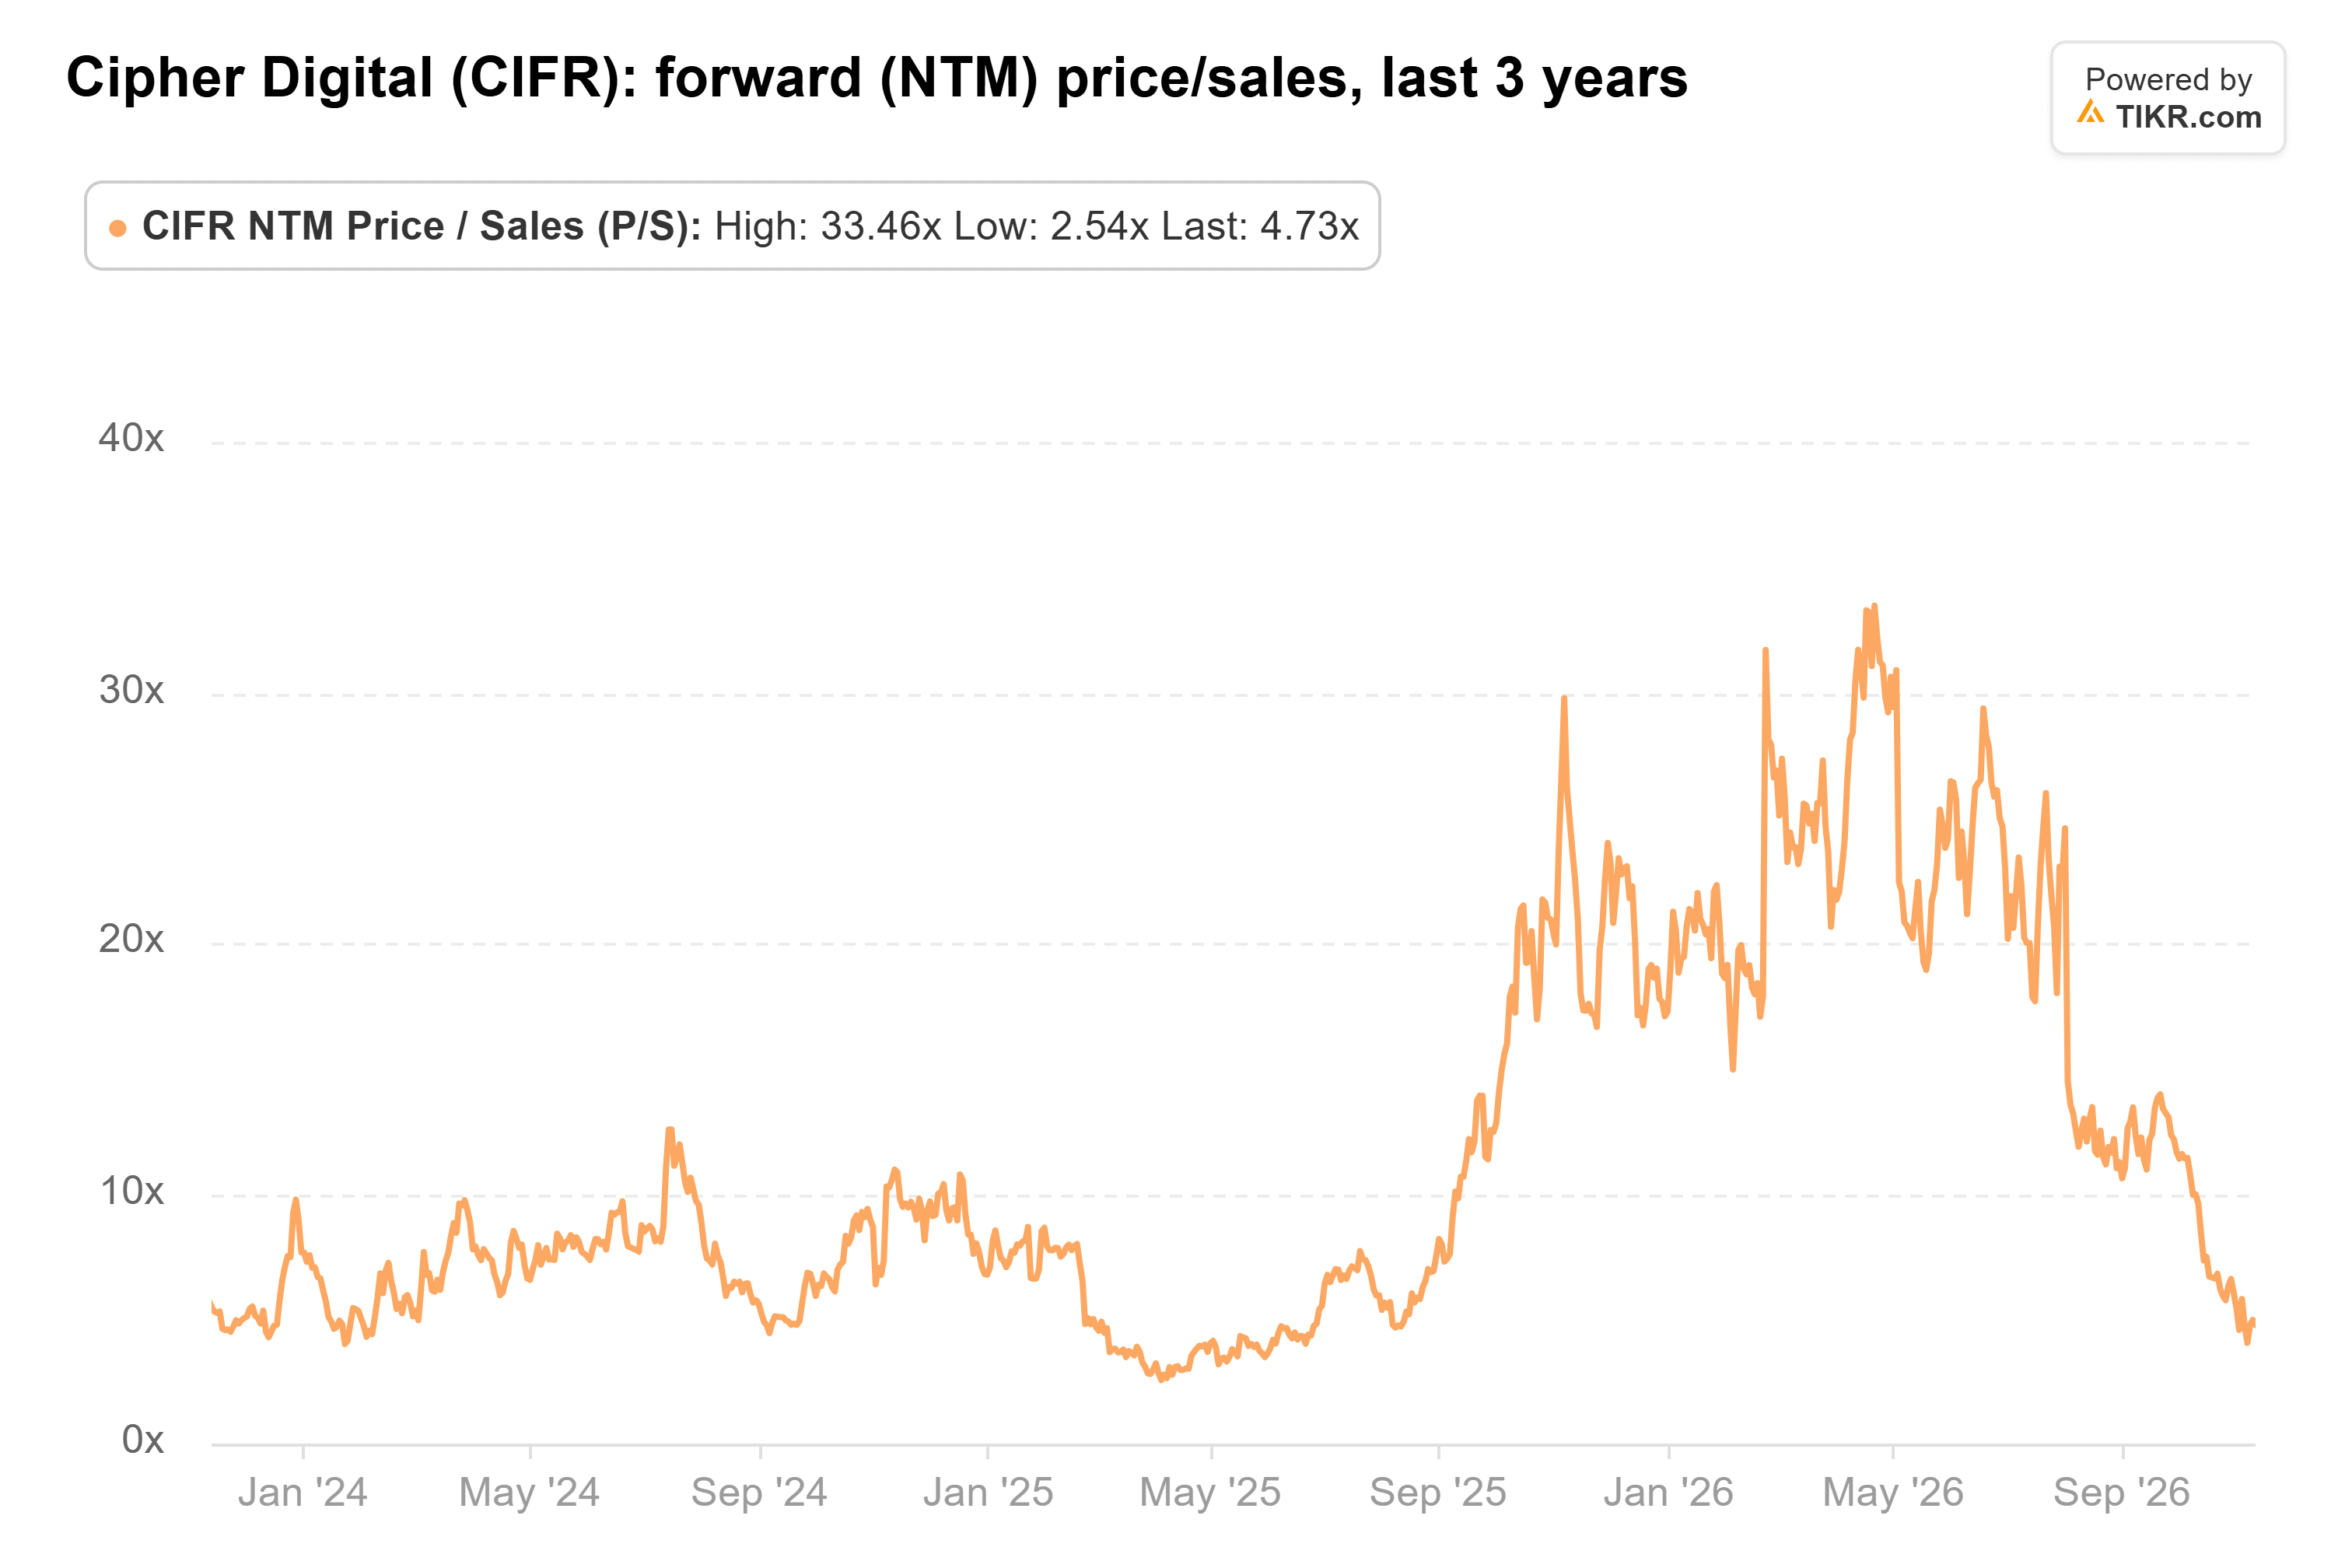
At approximately 4.7x forward sales in TIKR’s November 9 data, compared with its three-year average of 11.4x, Cipher traded at a substantial historical discount. However, the lower multiple also reflects the company’s significant construction costs, rising debt, and uncertainty around when contracted rental revenue will be recognized.
However, that comparison is imperfect because Cipher is transitioning from bitcoin mining toward long-term AI infrastructure leasing, making historical valuation multiples less directly comparable.
Over the next 12 months, successful data center deliveries, growing rental revenue, and improved financing access could support a higher valuation.
Anthropic’s IPO could strengthen confidence in the longer-term demand supporting Barber Lake, but Cipher’s initial lease remains with Fluidstack, while the separate AI lab commitment covers the subsequent decade.
Consequently, Cipher offers meaningful growth potential if its infrastructure transition succeeds, but elevated debt, potential dilution, and execution risks mean its lower valuation does not automatically make the stock cheap.
So what is Cipher Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cipher Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!