Key Takeaways
- Cimpress shares fell 19% after fiscal first-quarter results missed management’s own expectations, with 2% organic growth and adjusted EBITDA down 9%.
- Management kept its full-year targets, which now lean on faster cost cuts, acquisitions and a stronger second half.
- Cimpress needs at least $430 million of adjusted EBITDA over the next three quarters, against $89.8 million in the first.
Cimpress (CMPR) stock is down 19% today after its fiscal first-quarter results fell short of management’s own expectations.
Revenue rose 8% to $934 million in the quarter to Sept. 30, but only 2% on an organic, constant-currency basis. Adjusted EBITDA fell 9% to $89.8 million.
Management kept its full-year guidance anyway, and CEO Robert Keane said on Thursday’s call:
“We are accelerating cost reduction measures as an insurance plan for meeting our financial goals.”
The rest of the year has a lot to carry
Cimpress still expects at least $520 million of adjusted EBITDA in fiscal 2027 (the year to June), about $200 million of adjusted free cash flow, and at least 3% organic growth.
That leaves at least $430 million of adjusted EBITDA for the last three quarters. In last year’s fiscal fourth quarter it made $120.4 million.
Analysts already expected EBITDA to jump this year:
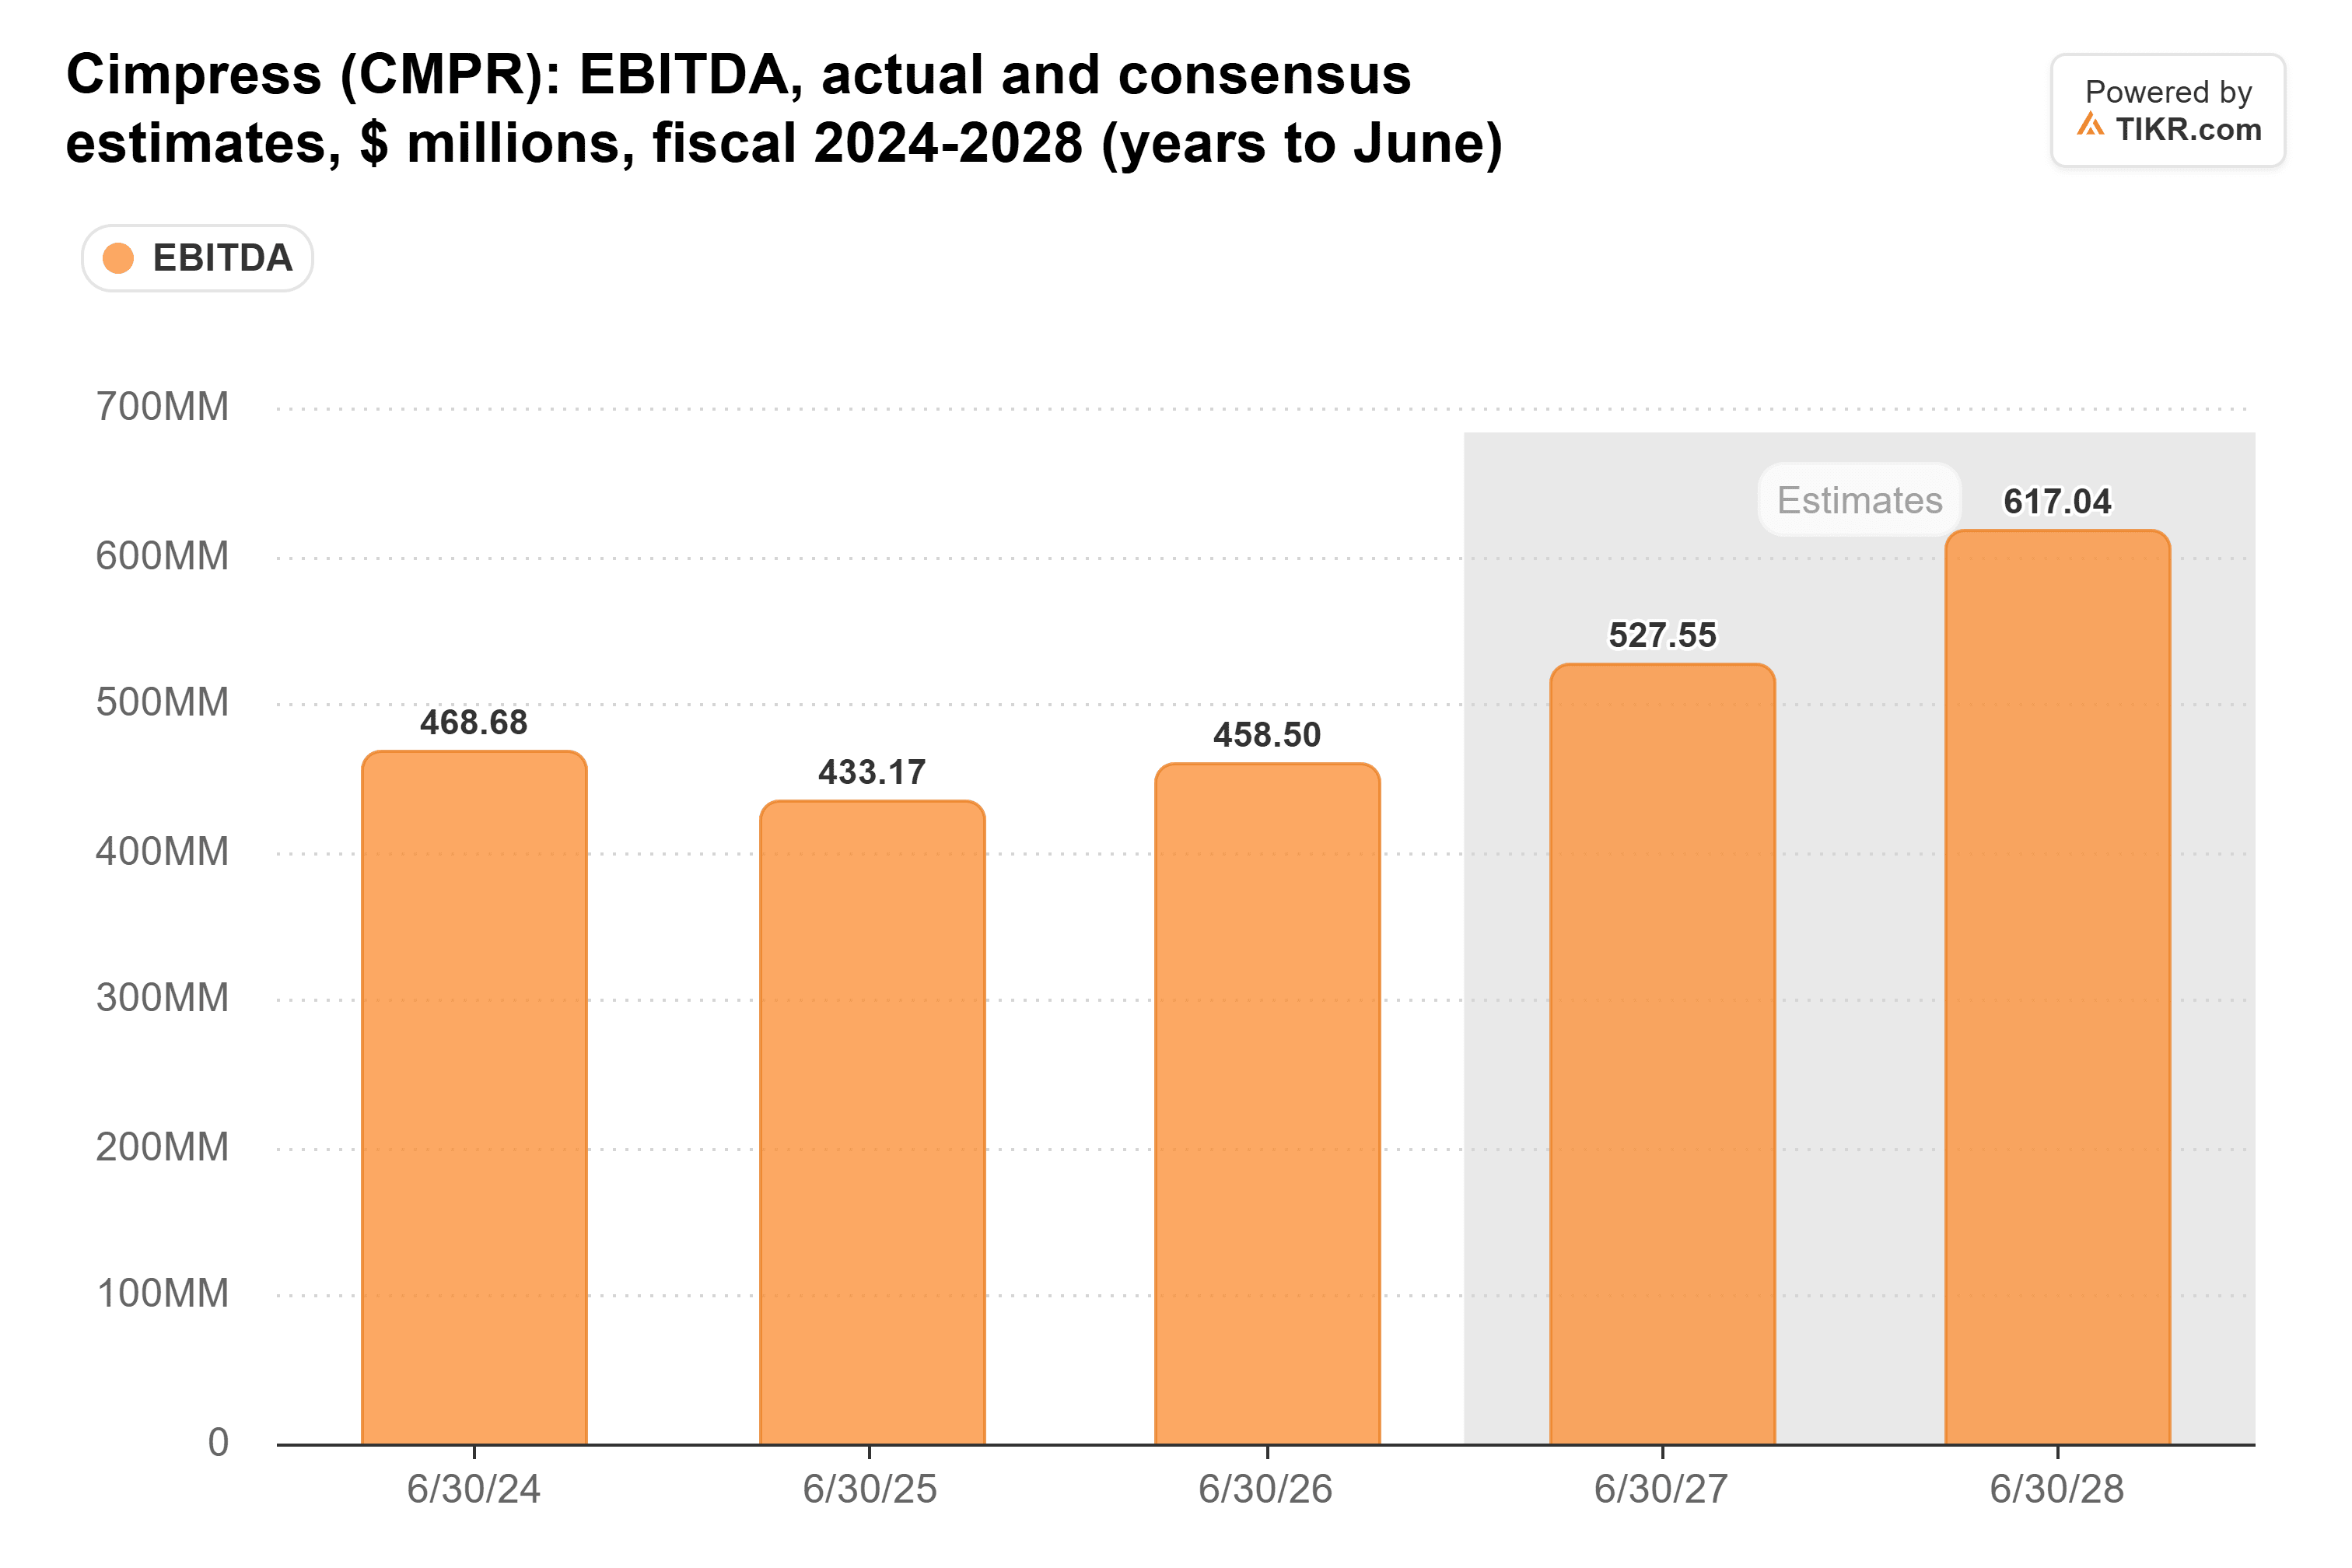
Both estimates behind that $528 million figure were made before this quarter’s results. After a 9% drop, I’d expect them to come down.
Acquisitions should add $18 million to $21 million of EBITDA this year, so they won’t close the gap alone.
Free cash flow has shrunk two years in a row:
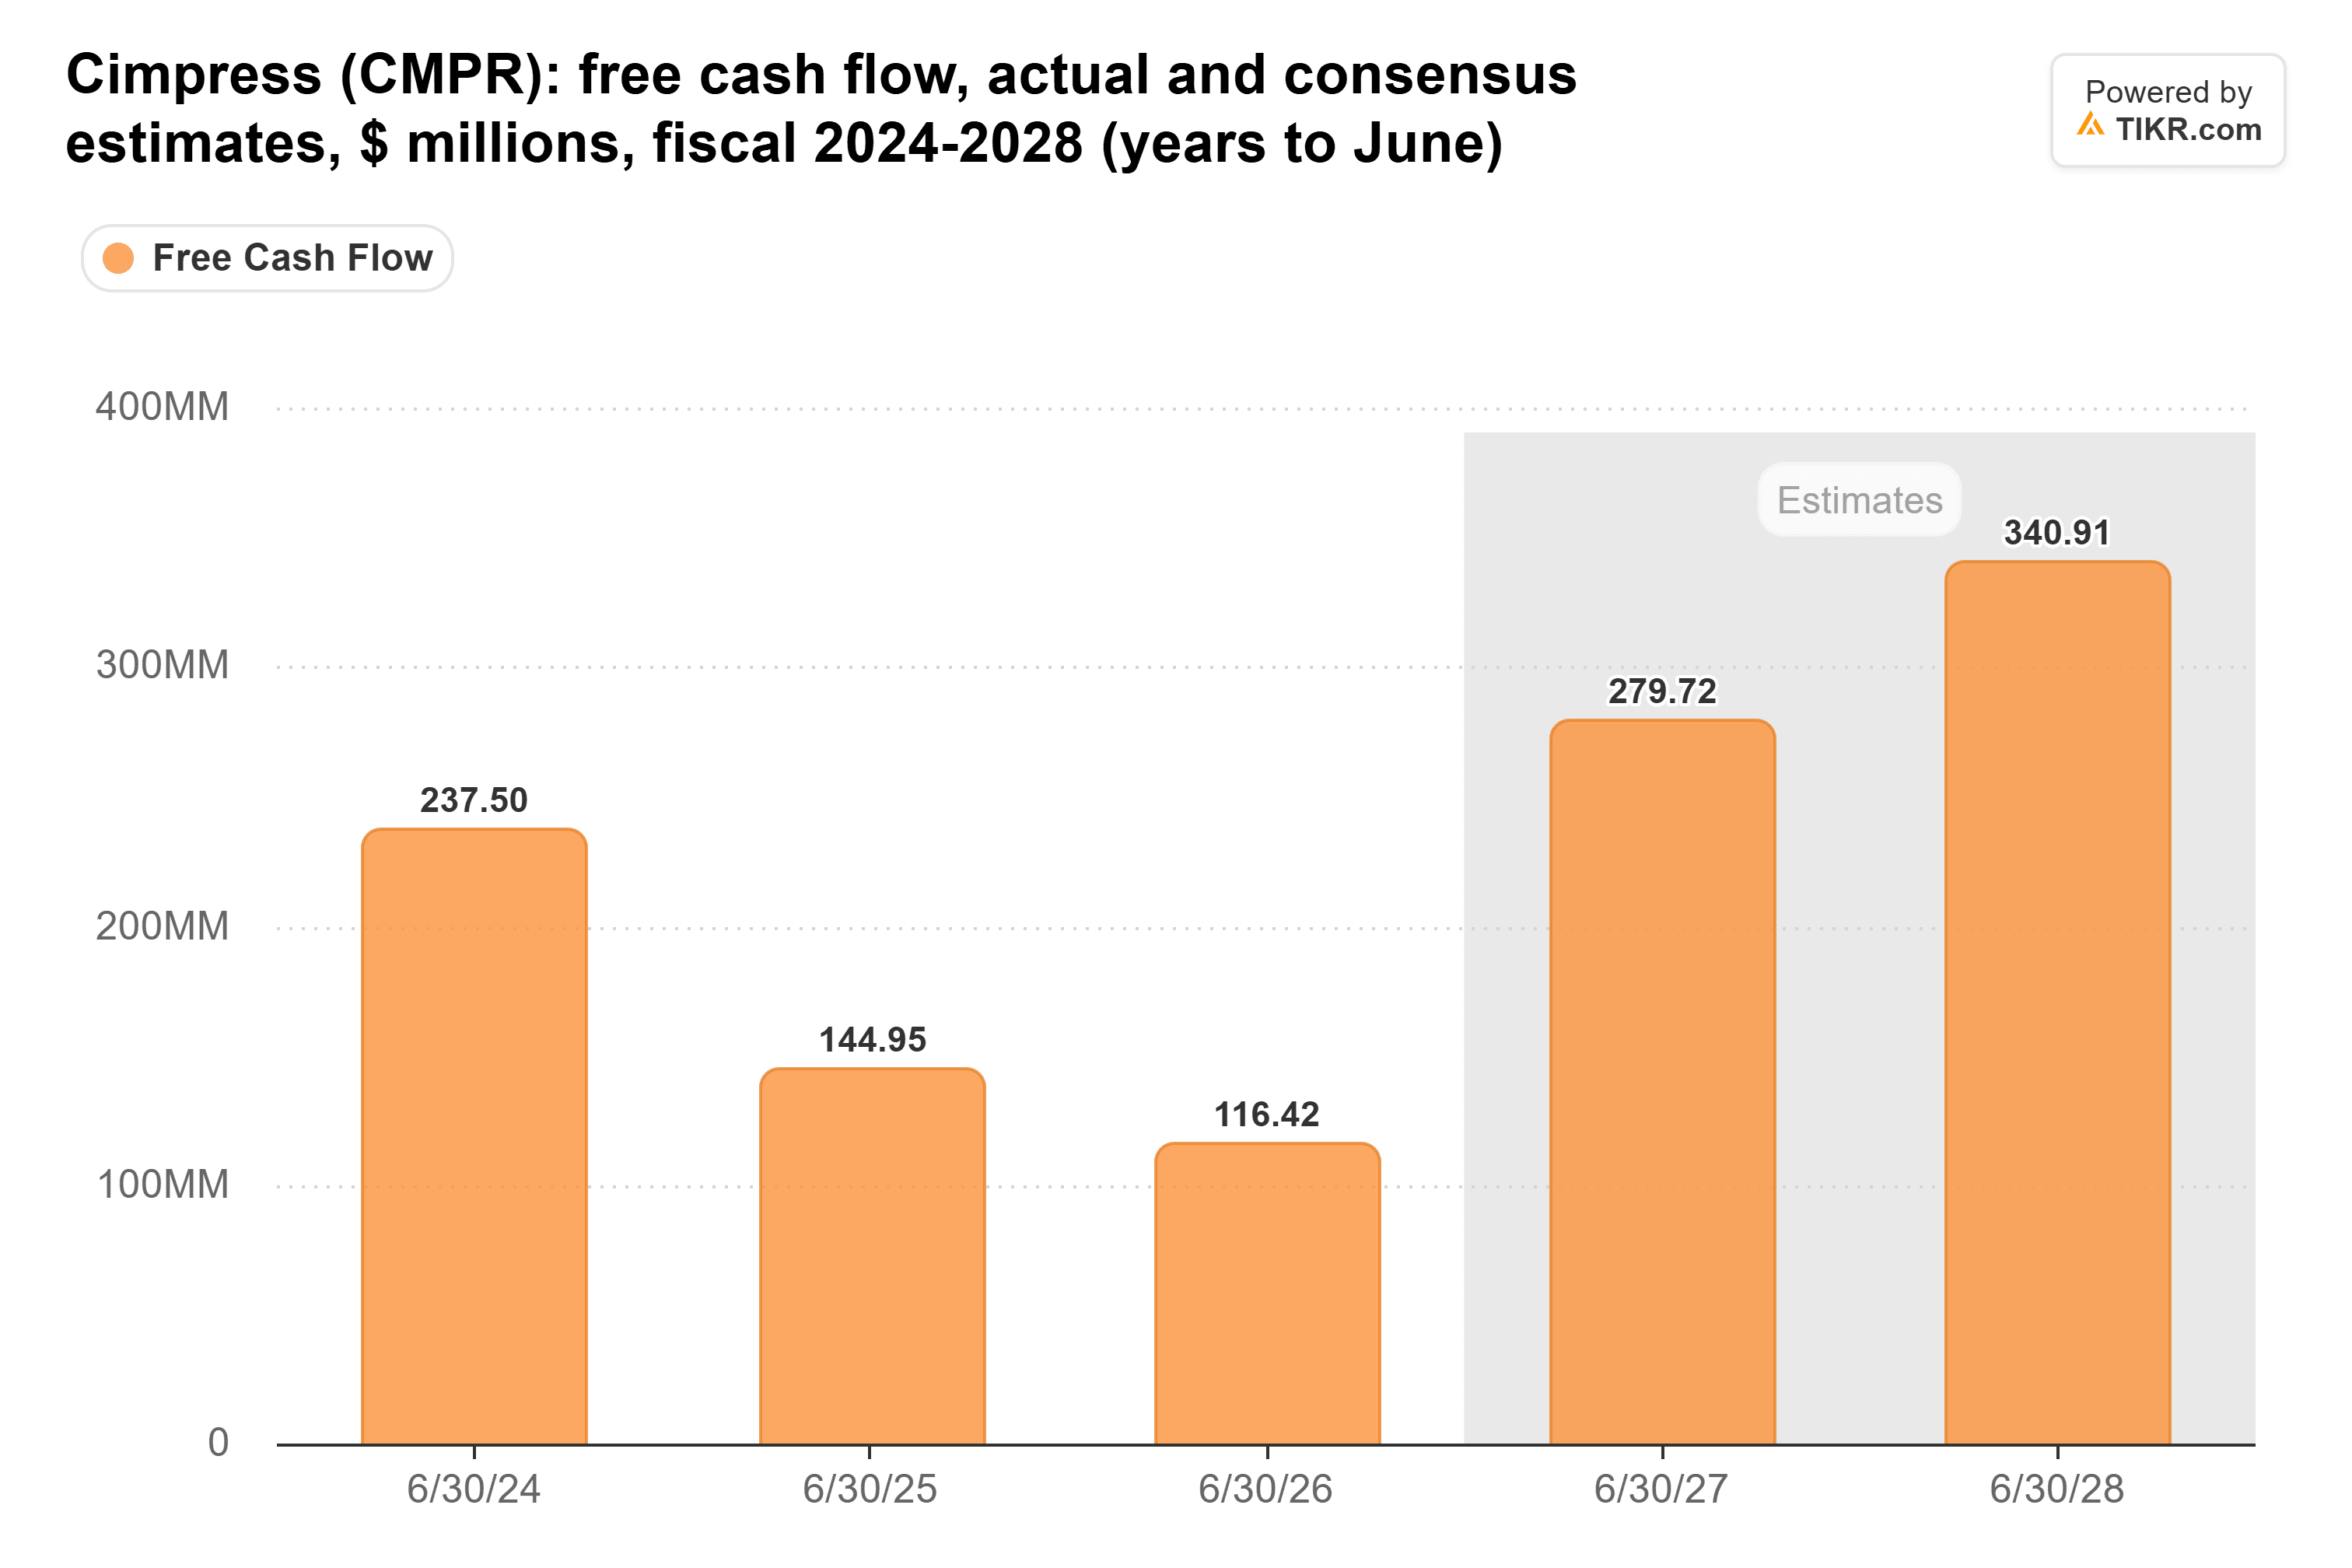
Adjusted free cash flow in the first quarter was a $9.3 million outflow, so the next three quarters have to bring in more than $200 million.
Growth is the harder fix
Acquisitions added $60 million of revenue in the quarter, which explains most of the gap between 8% and 2% growth. And Keane said VistaPrint’s legacy products and small customers “are currently offsetting tailwinds from high-value customers.”
See analyst ratings on Cimpress (it’s free):
See the full breakdown of Buy, Hold, and Sell ratings on Cimpress, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cimpress’ Analyst Ratings
Priced for the plan
Before today, Cimpress traded at 15x forward earnings. That’s down from 21x in July but above its five-year average of 13x:
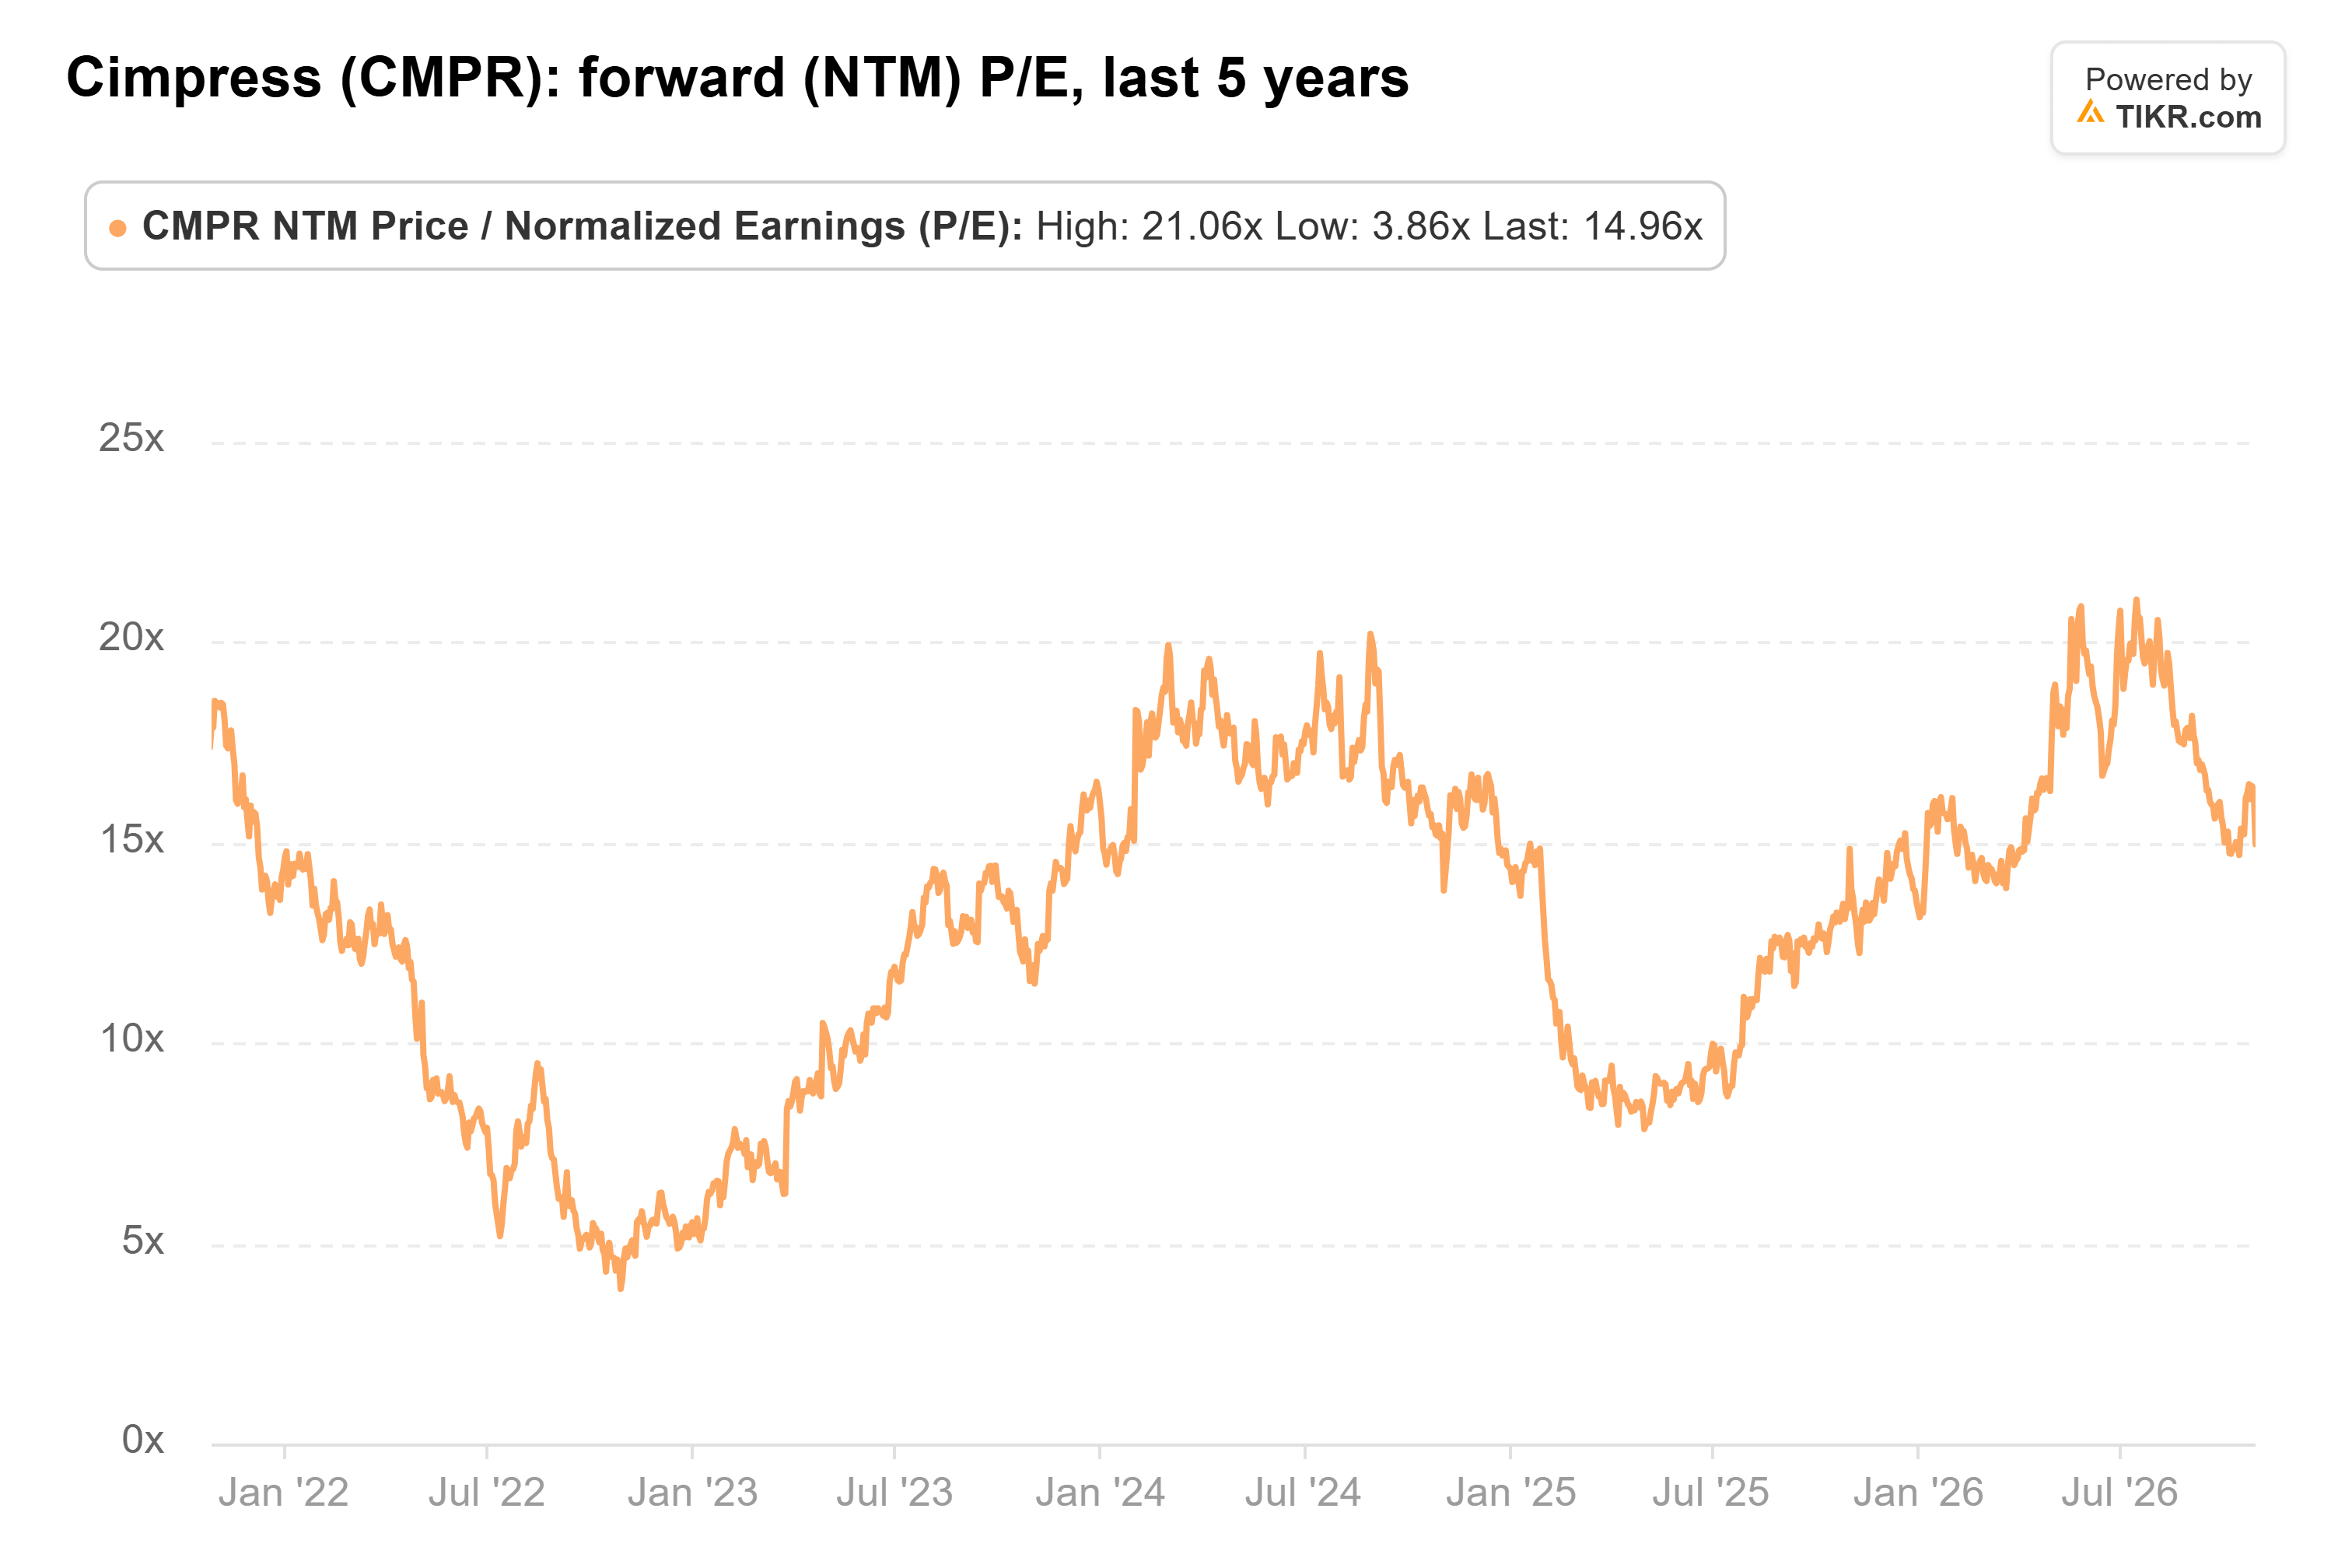
Today’s drop takes it to about 13x, and the earnings estimates behind that multiple look likely to fall.
My take: At that price, the market still assumes the guidance holds. After a quarter this far below plan, I’d want to see the December quarter before buying. Of course, a strong second quarter, reported in late January, would go a long way.
So what is Cimpress stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cimpress could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!