Key Takeaways
- Cathie Wood’s ARK Invest sold 37,002 shares of Amazon from its ARK Innovation ETF on Friday, worth about $9 million at the day’s close.
- The sale is small next to the 1.70 million Amazon shares ARK held at the end of September.
- Analysts expect Amazon’s earnings to nearly double from 2025 to 2028, and the stock trades at 24x forward earnings, half its five-year average.
- Amazon’s AI spending and its Anthropic stake, which now has a public price, are the risks, but at this multiple the numbers favor buying over selling.
Cathie Wood’s ARK Invest sold 37,002 shares of Amazon (AMZN) on Friday, according to ARK’s daily trade email. At Friday’s close of $246.82, that comes to about $9 million. That figure is the shares times the close, since ARK doesn’t say what it got for them.
It was a rough day to trade anything in tech. The Nasdaq 100 fell 6% on Friday, the day after Anthropic (ANT) went public. Anthropic’s latest amended S-1 puts Amazon’s stake at 14.7% after the offering.
A small trim from ARK’s flagship fund
All 37,002 shares came out of the ARK Innovation ETF (ARKK), where they made up 0.06% of the fund. That’s a small move, and it’s also small next to what ARK owned going in.
ARK manages $17 billion. Its 13F for the quarter ended Sept. 30, filed Nov. 13, showed 1.70 million Amazon shares worth $423 million. That’s 2.4% of its 13F stocks and its 13th-largest holding. ARK also held 7% more Amazon shares on Sept. 30 than it did three months earlier, so Friday’s sale trims a stake that grew last quarter.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Amazon’s earnings are still heading up
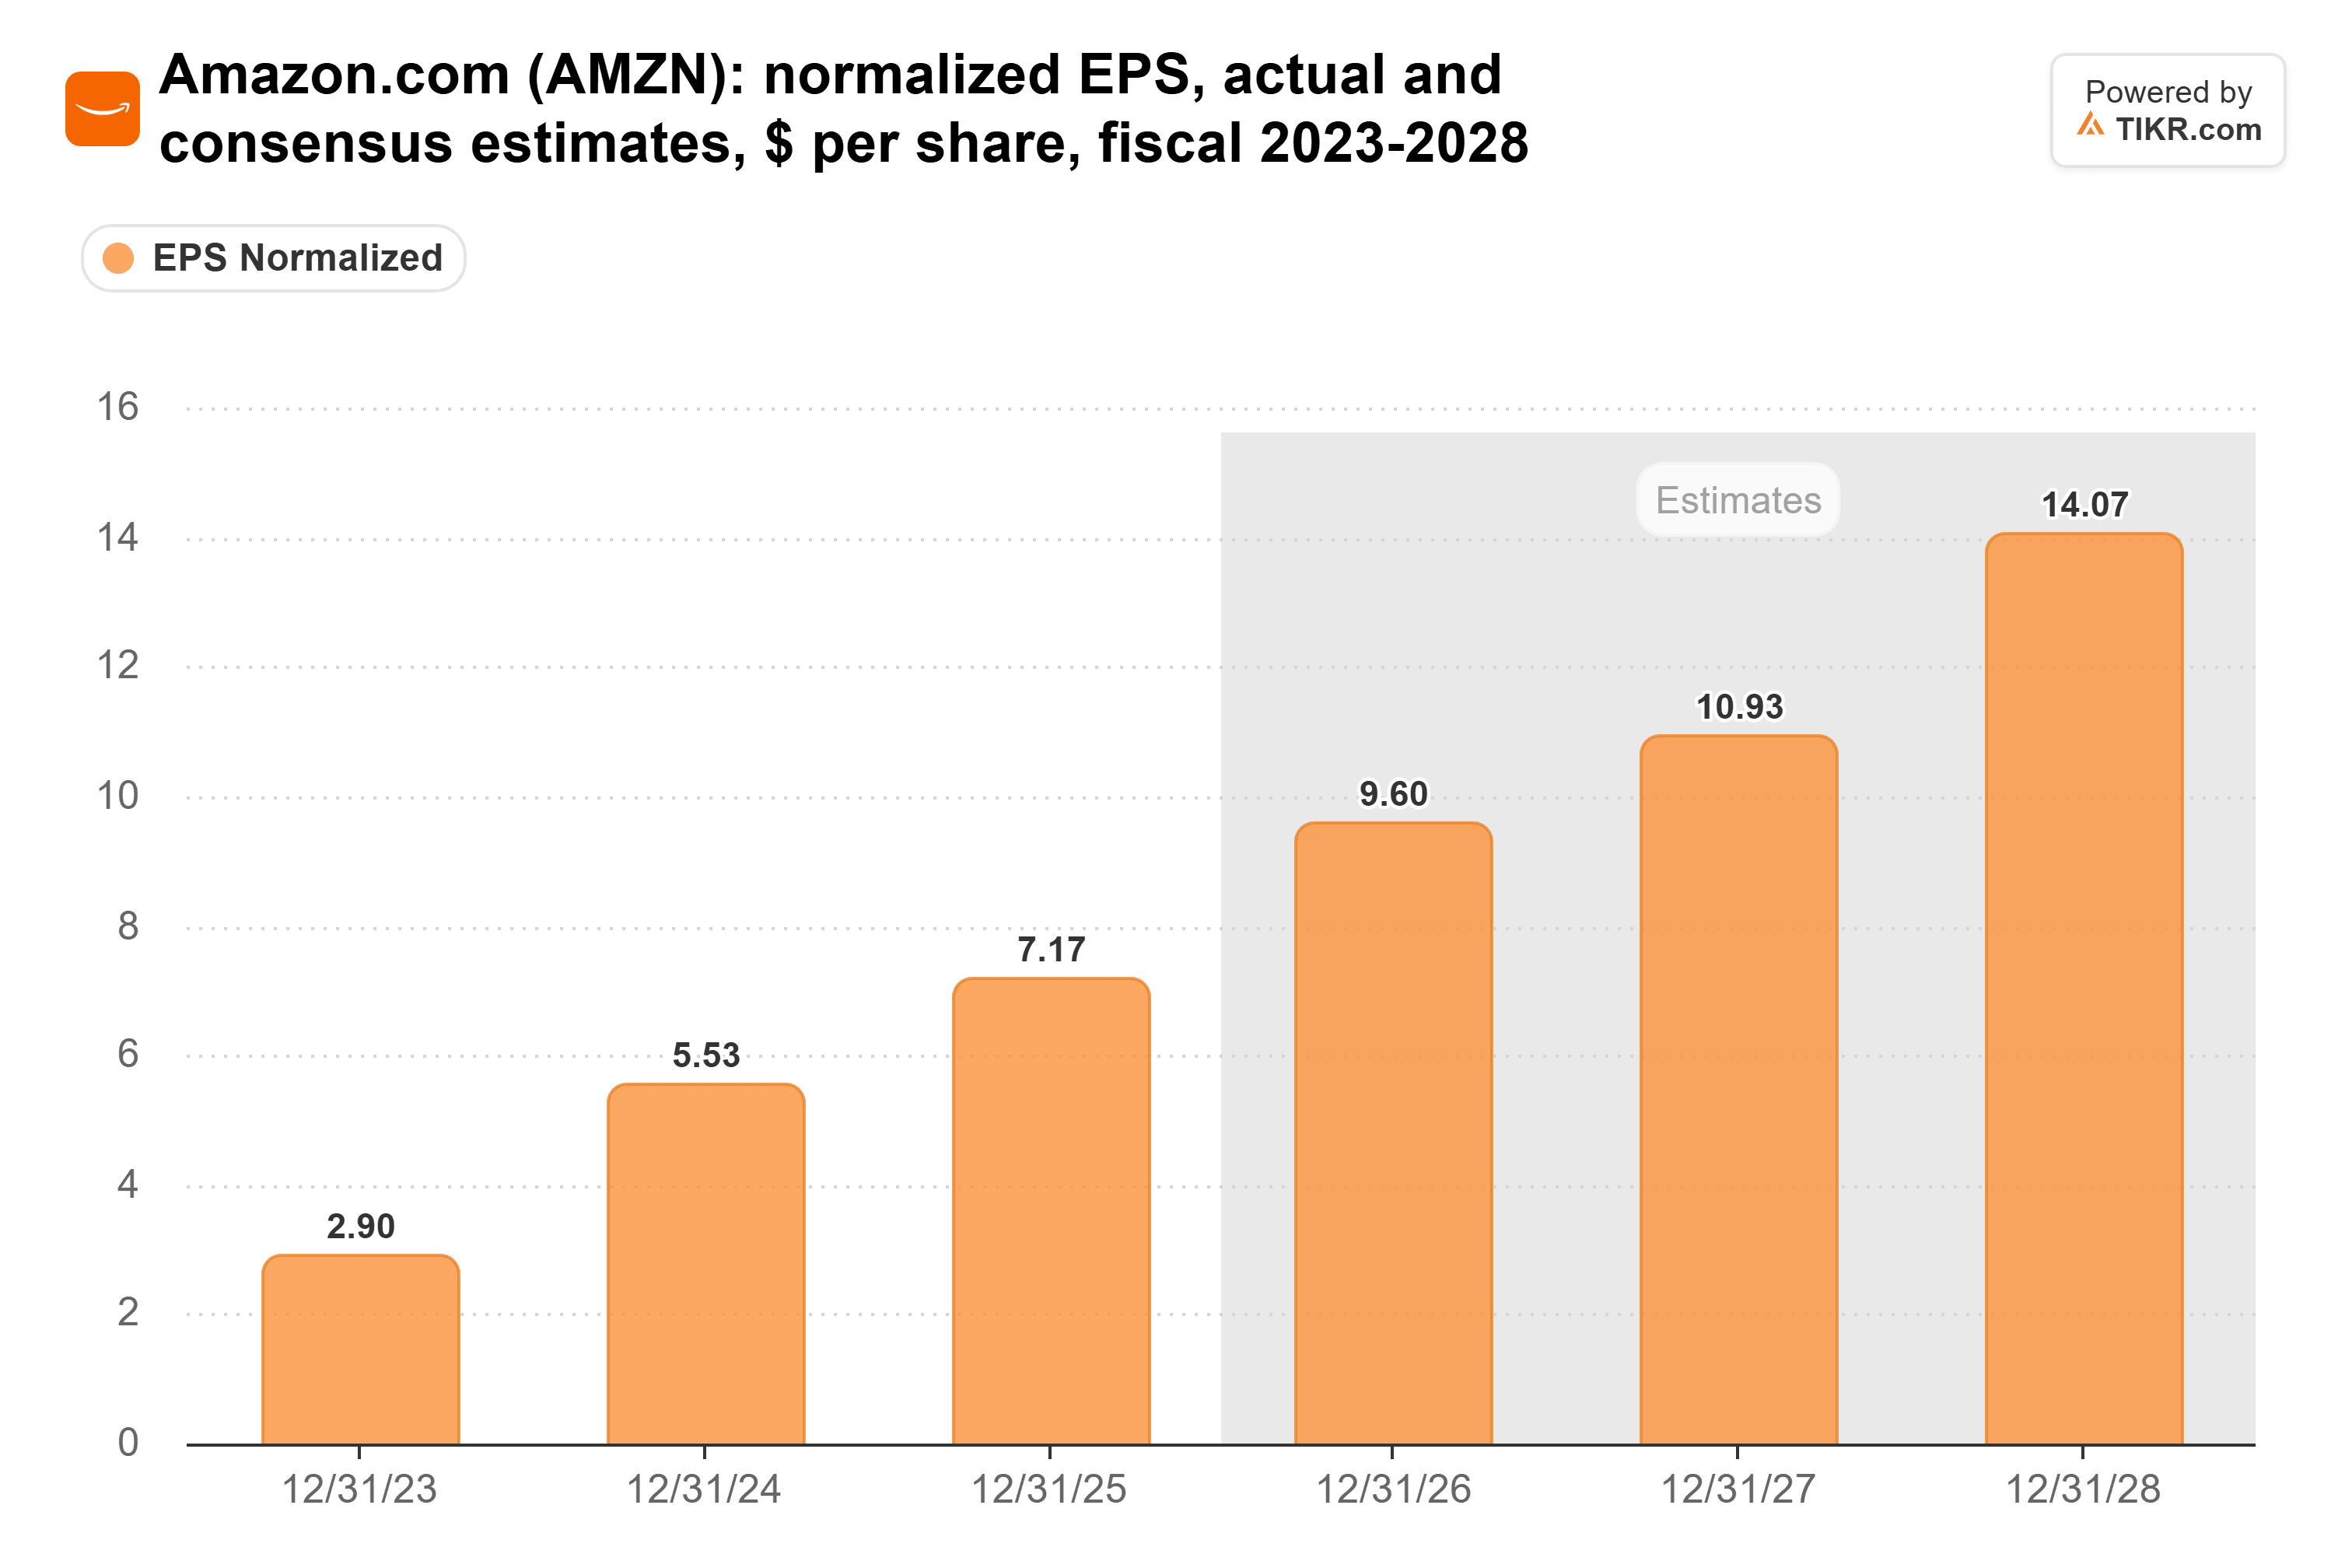
The case for holding starts with earnings. Analysts expect Amazon’s normalized EPS to rise from $7.17 in 2025 to $9.60 this year and $14.07 in 2028, nearly double in three years:
AWS carries much of that, and the demand is there. CEO Andy Jassy said on CNBC’s Halftime Report this week that Amazon’s compute is largely reserved for 2027, along with “a good chunk” of 2028 and “a fair bit” of 2029. Amazon’s own chips are also growing into a real business. Management put their run rate above $25 billion in the second quarter, and earlier said it would be a $50 billion business at third-party prices.
Priced near its five-year low
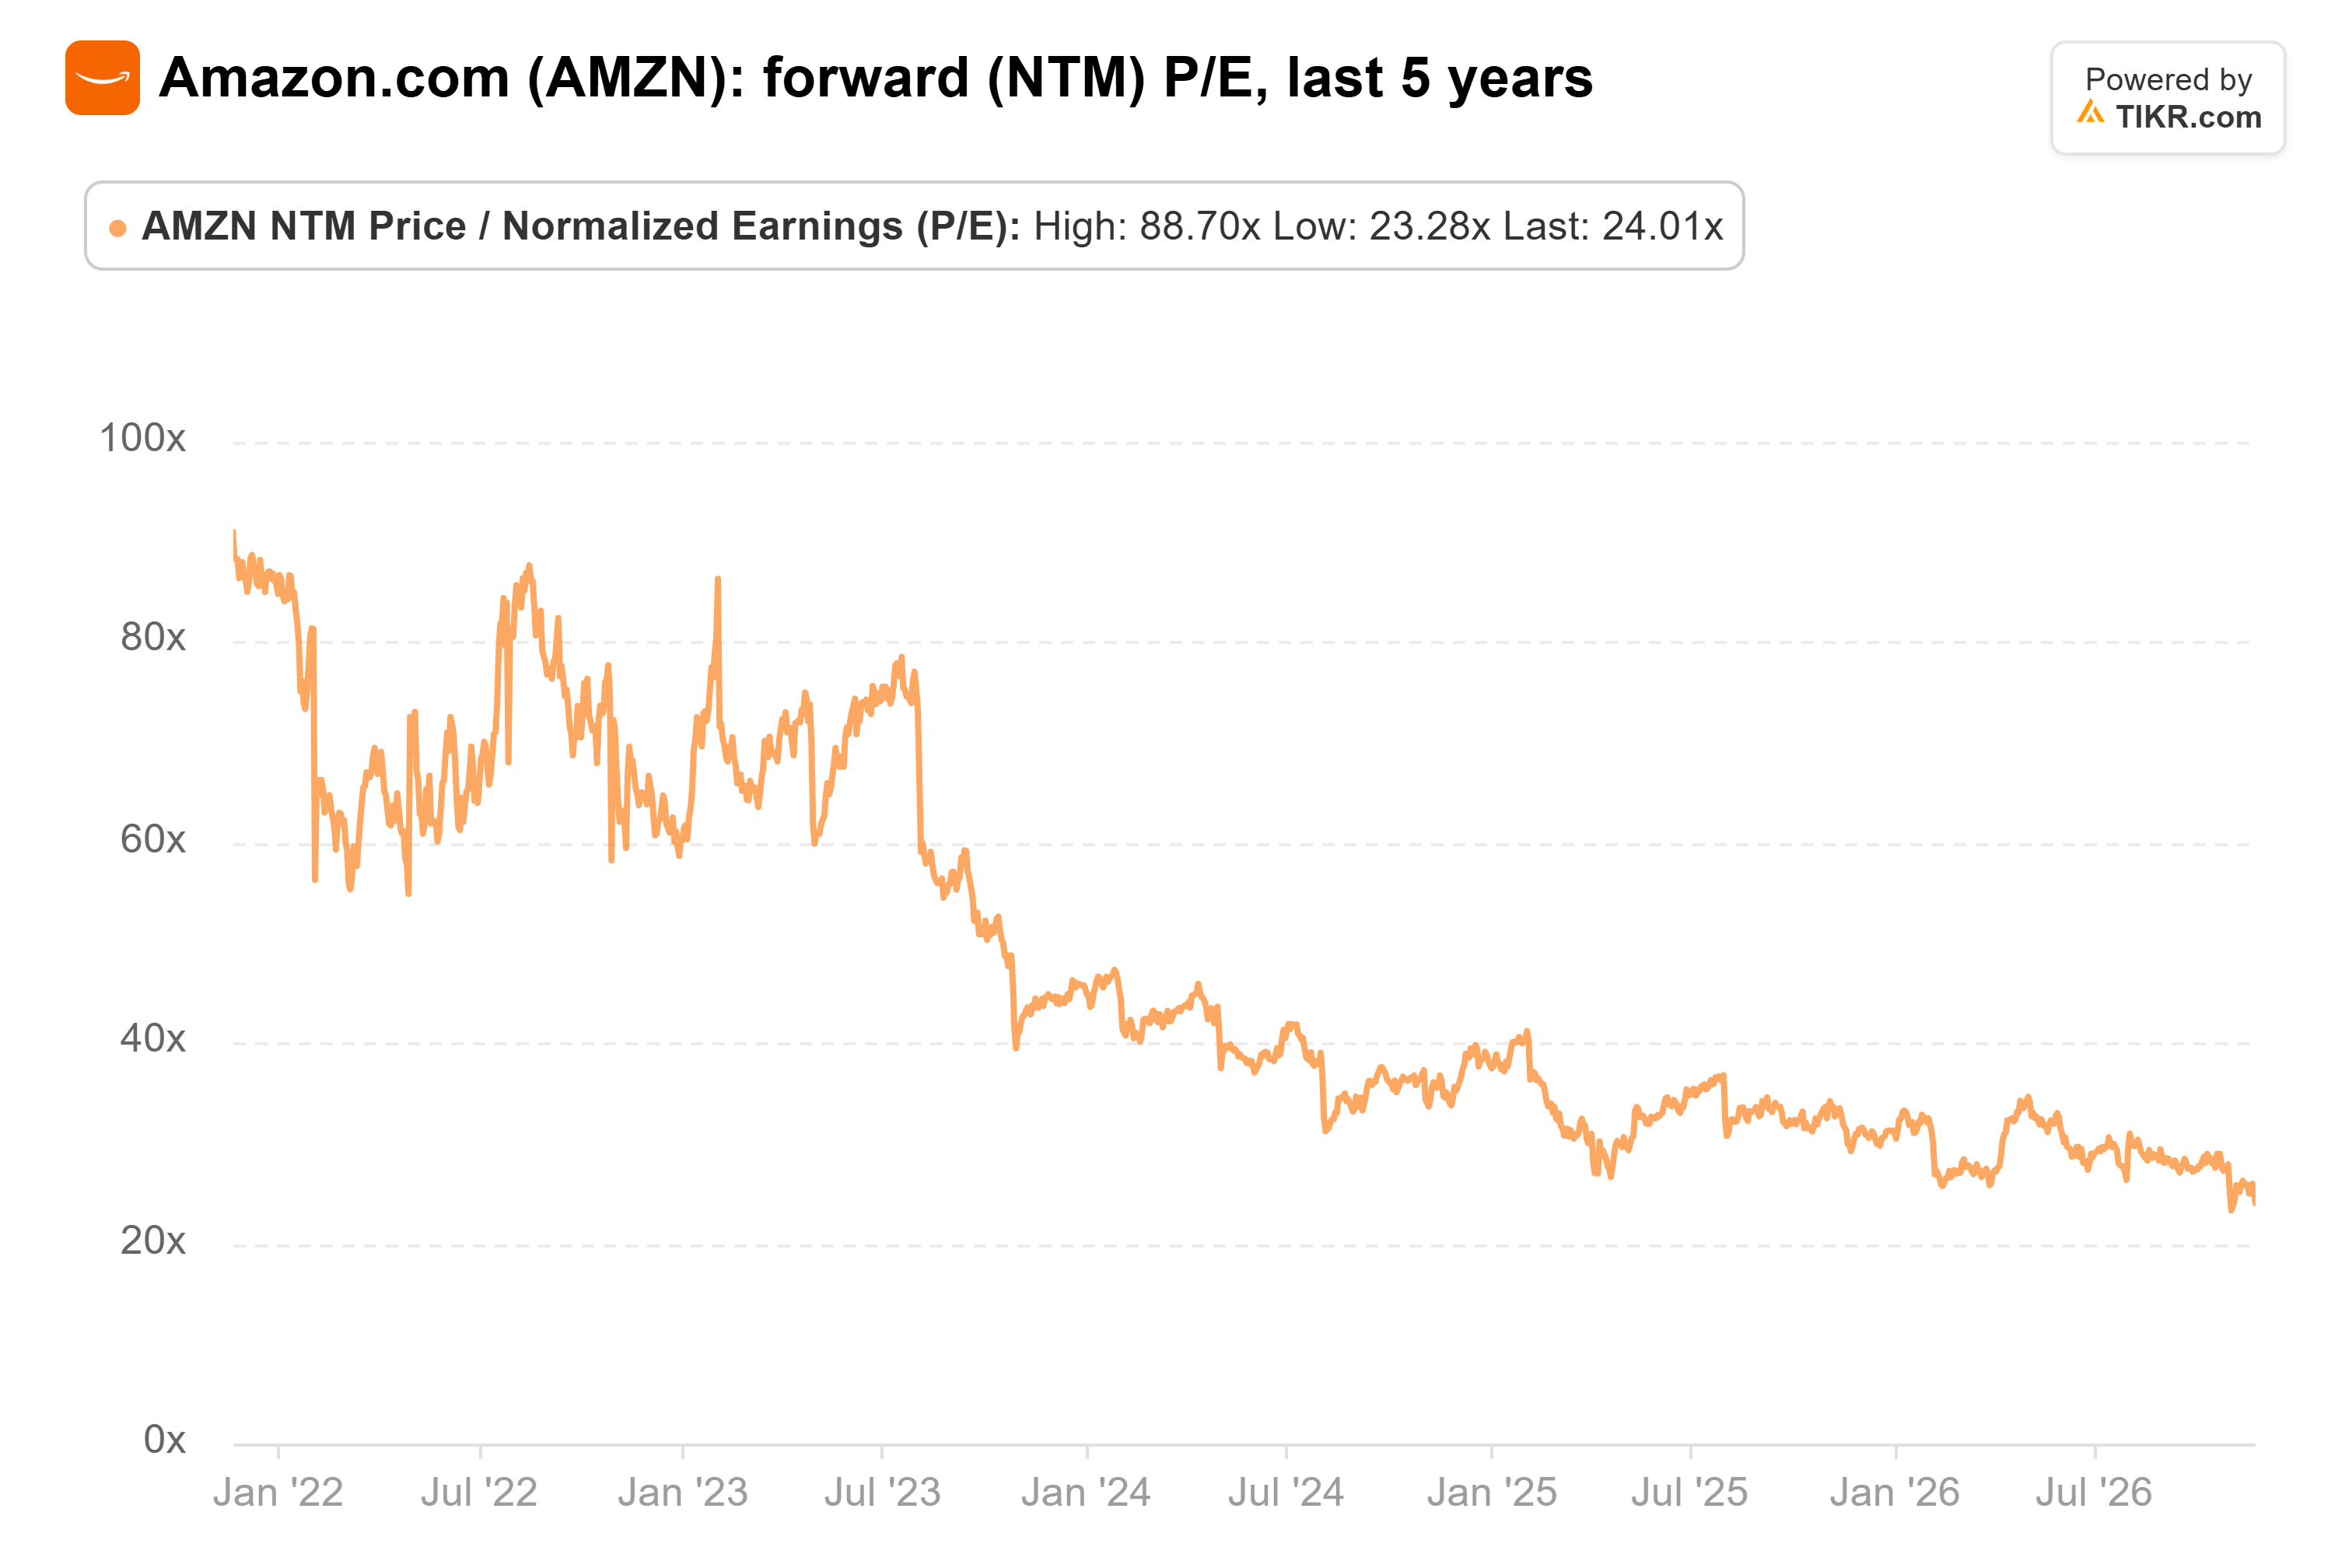
The stock has gone the other way. Amazon trades at 24x forward earnings, just above the 23x low it hit on Oct. 30 and half its five-year average of 48x:
The Street hasn’t followed the stock down. Analysts’ consensus price target has risen to $327 from $294 a year ago, and it sits 32% above Friday’s close:
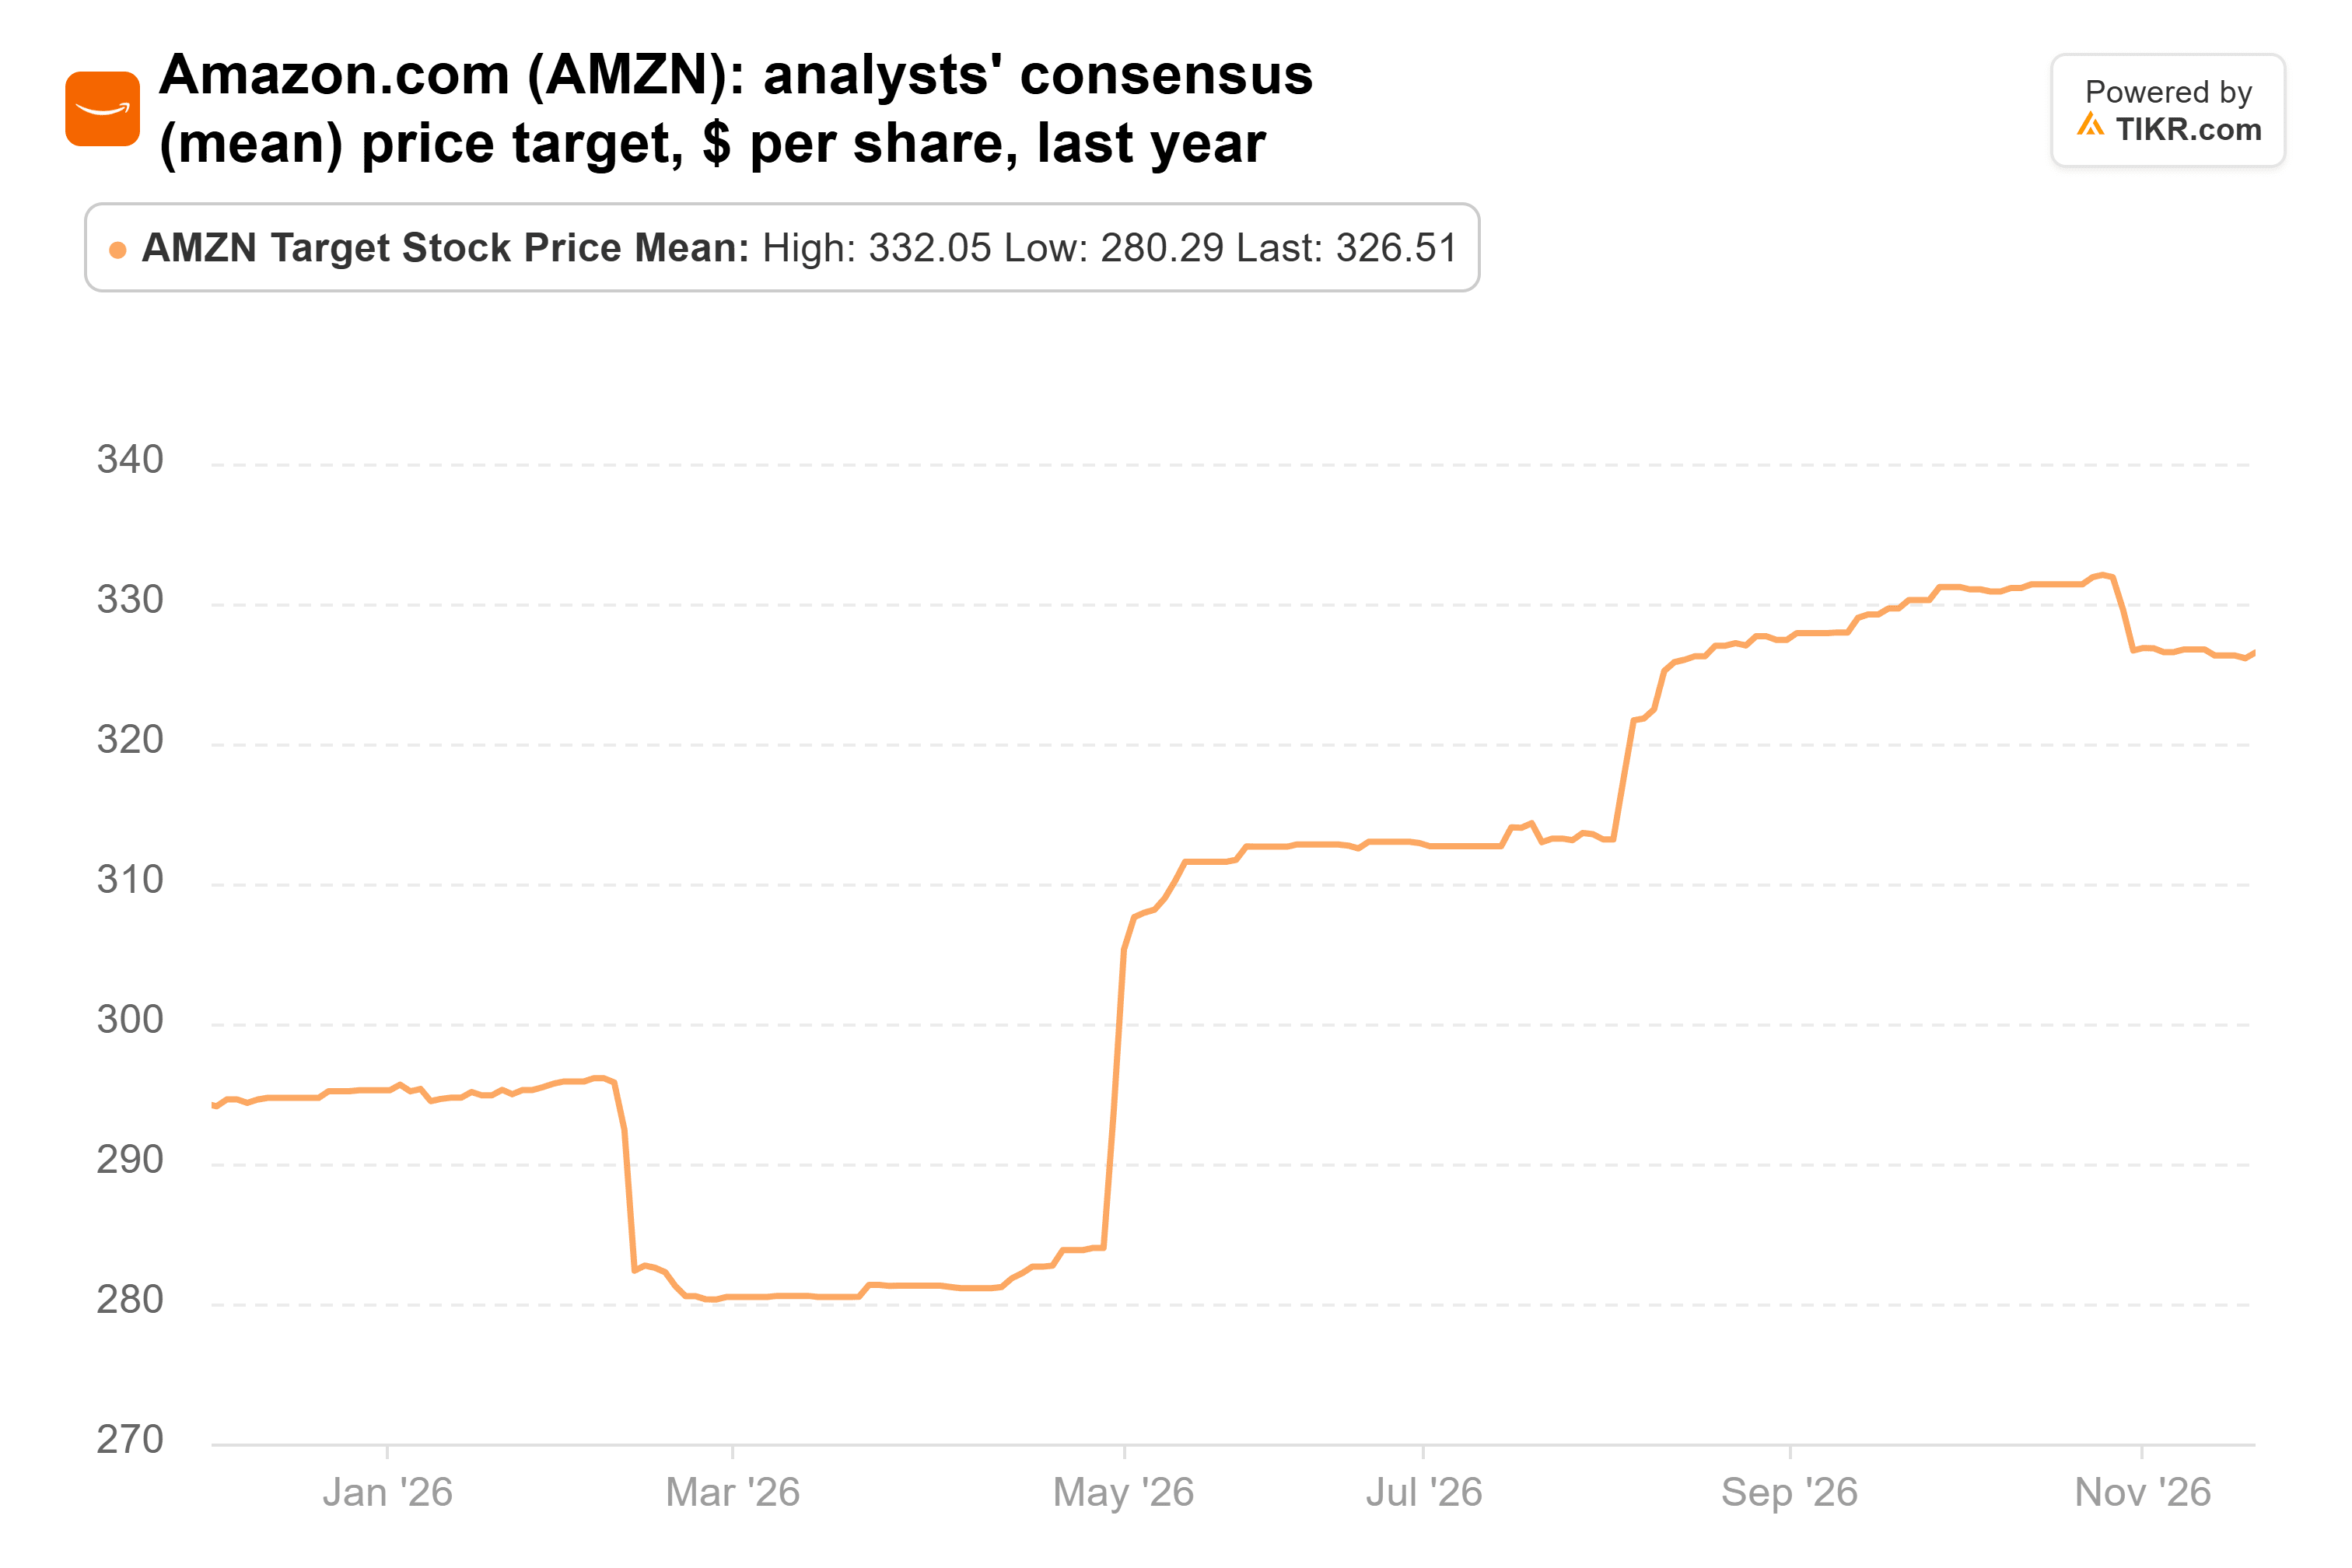
By my math, $327 is about 23x Amazon’s 2028 estimates. So the target doesn’t need investors to pay a higher multiple than today’s. It only needs the estimates to hold.
I’d be on the other side of this trade
Amazon’s spending is what could go wrong. Jassy said Amazon will spend “meaningfully more” in 2027 than the roughly $220 billion of capex it expects this year. Analysts now expect free cash flow of minus $41.2 billion in 2026, turning positive again in 2028.
Anthropic is the other risk. Amazon carried its stake at about $239 billion on Sept. 30. Now that Anthropic trades, the stake gets a market price every quarter, so Amazon’s GAAP earnings will rise and fall with Anthropic’s stock. The debut was bumpy: the shares slid on their second day, at one point to just 5 cents above the IPO price. Nearly 40% of the deal was also free to trade from day one.
Still, analysts expect earnings to nearly double by 2028, the multiple is close to its low, and the Street’s target only needs those estimates to hold. At 24x, Amazon looks like a stock to add to.
The next check is Amazon’s fourth-quarter report in early February, when it’s expected to give its 2027 spending plan. A capex figure well above the $278.2 billion analysts expect would push the cash turn further out. ARK’s next 13F, due in mid-February, will show how much Amazon it still held at year-end.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!