Key Takeaways
- Cathie Wood’s ARK Invest bought 49,745 shares of Advanced Micro Devices across two ETFs on Nov. 20, worth about $21 million at that day’s close.
- AMD is down 31% since Sept. 30, and its forward P/E of 28x is below its five-year average of 34x.
- Analysts expect AMD’s earnings to more than double in 2027. Getting there means winning AI business from Nvidia with chips Taiwan Semiconductor Manufacturing makes.
- The numbers support the buy as long as AMD’s Helios racks ship on schedule.
Cathie Wood’s ARK Invest bought 49,745 shares of Advanced Micro Devices (AMD) on Friday, Nov. 20, according to ARK’s own daily trade email. At that day’s close of $424.39, that’s about $21 million.
The stock is 36% below its 52-week high. Much of AMD’s case rests on winning a bigger share of an AI build-out that Nvidia (NVDA) still leads, using chips made by Taiwan Semiconductor Manufacturing (TSM).
A small add after a big cut
The buy went into two funds: 39,157 shares for the ARK Innovation ETF (ARKK) and 10,588 for the ARK Next Generation Internet ETF (ARKW). That’s 0.13% of each fund. The $21 million is the shares times Friday’s close, since the email lists the portfolio changes ARK’s team made but doesn’t give a price.
It’s a small trade next to what ARK already owned. The $17 billion firm’s 13F for the quarter ended Sept. 30, filed Nov. 13, showed 675,668 AMD shares worth $413 million. That was 2.4% of its 13F stocks and its 14th-biggest position. It also came after ARK cut its AMD share count by 52% during the quarter. Since Sept. 30, AMD has fallen 31%.
TIKR tracks 54 analysts on AMD. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AMD, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AMD’s Analyst Ratings
Two November headaches
AMD had news of its own this month. On Nov. 16, the Commerce Department’s Bureau of Industry and Security put out an interim rule that requires licenses for advanced US AI chips shipped to Indonesia, Malaysia, Singapore, Thailand and Brazil, and AMD’s Instinct GPUs are covered. Then on Nov. 19, AMD fell 8% after Hunterbrook Media reported that IEIT Systems, a company on the Commerce Department’s Entity List, had put newer AMD firmware into its BIOS updates. Hunterbrook’s affiliate is short AMD. Hunterbrook says its findings don’t show an export-law violation, and AMD said on Nov. 20 that the claims “misrepresent AMD’s business practices and relationships.” ARK’s buy came on the same day the Nasdaq 100 fell 6%.
The estimates keep climbing
None of that has dented what analysts expect AMD to earn. The consensus has normalized EPS nearly doubling from $4.17 in 2025 to $8.08 this year, then more than doubling again to $17.64 in 2027:
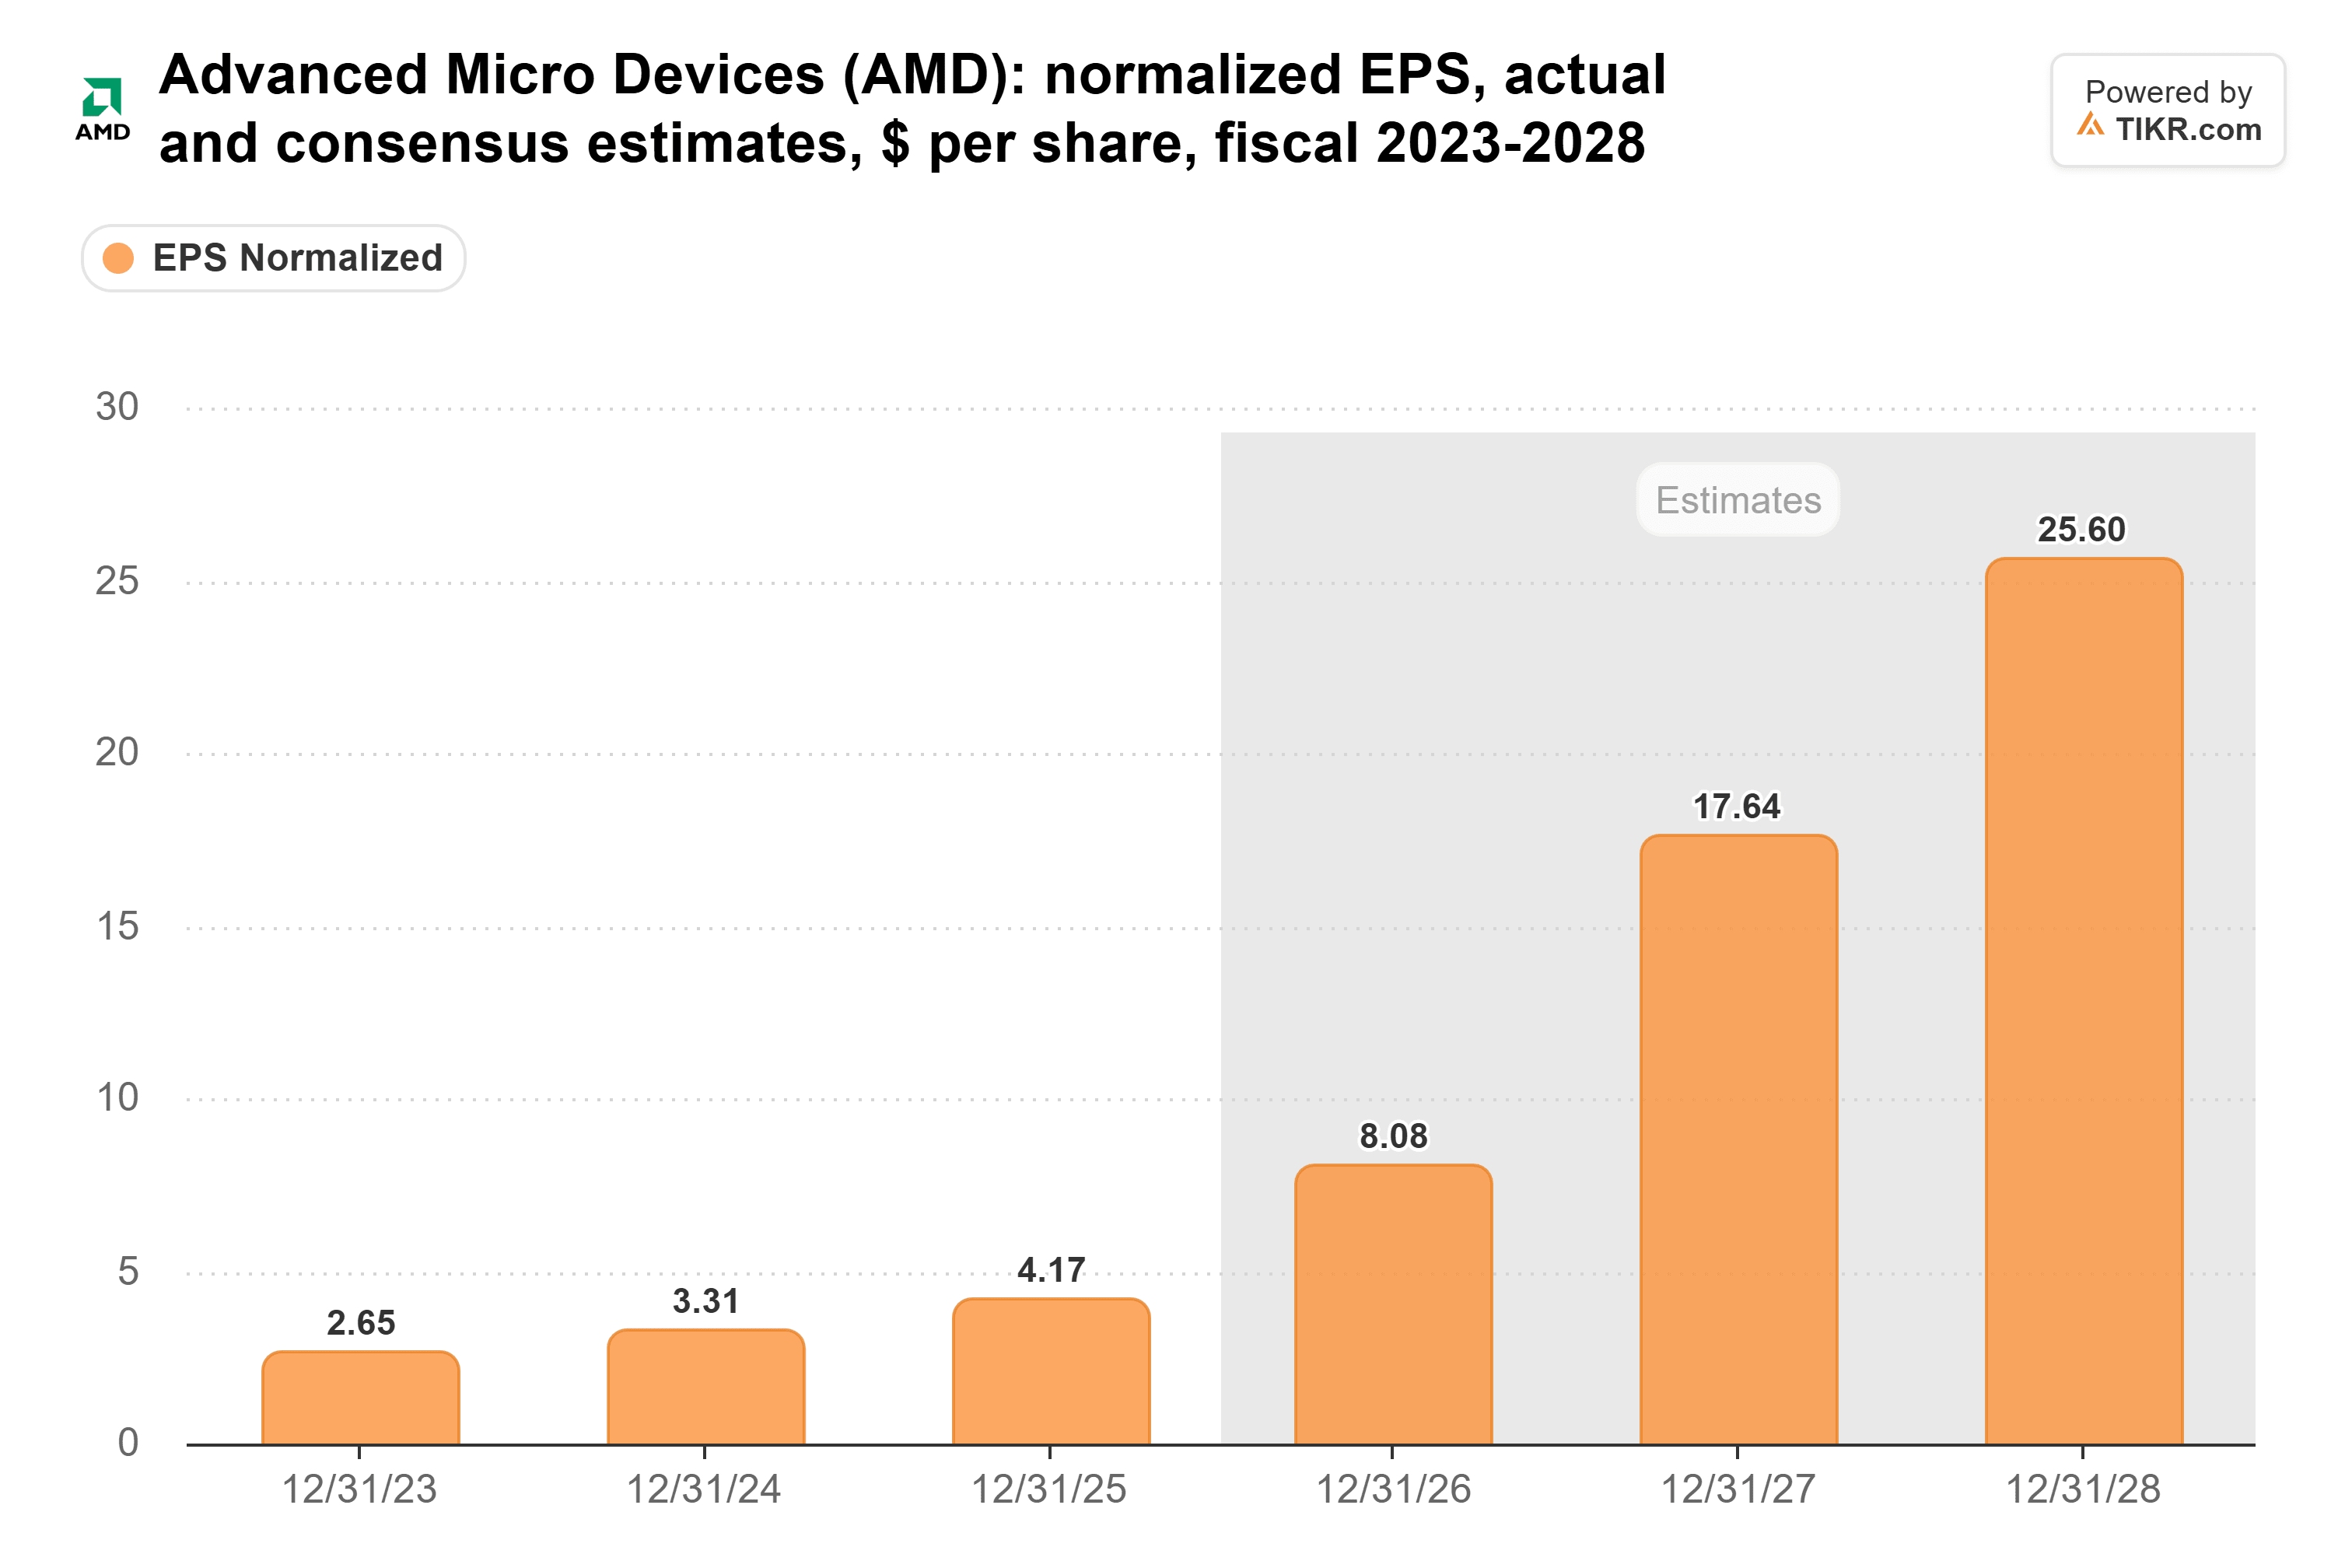
Those estimates have only gone up. The 2027 figure was $13.18 in late July.
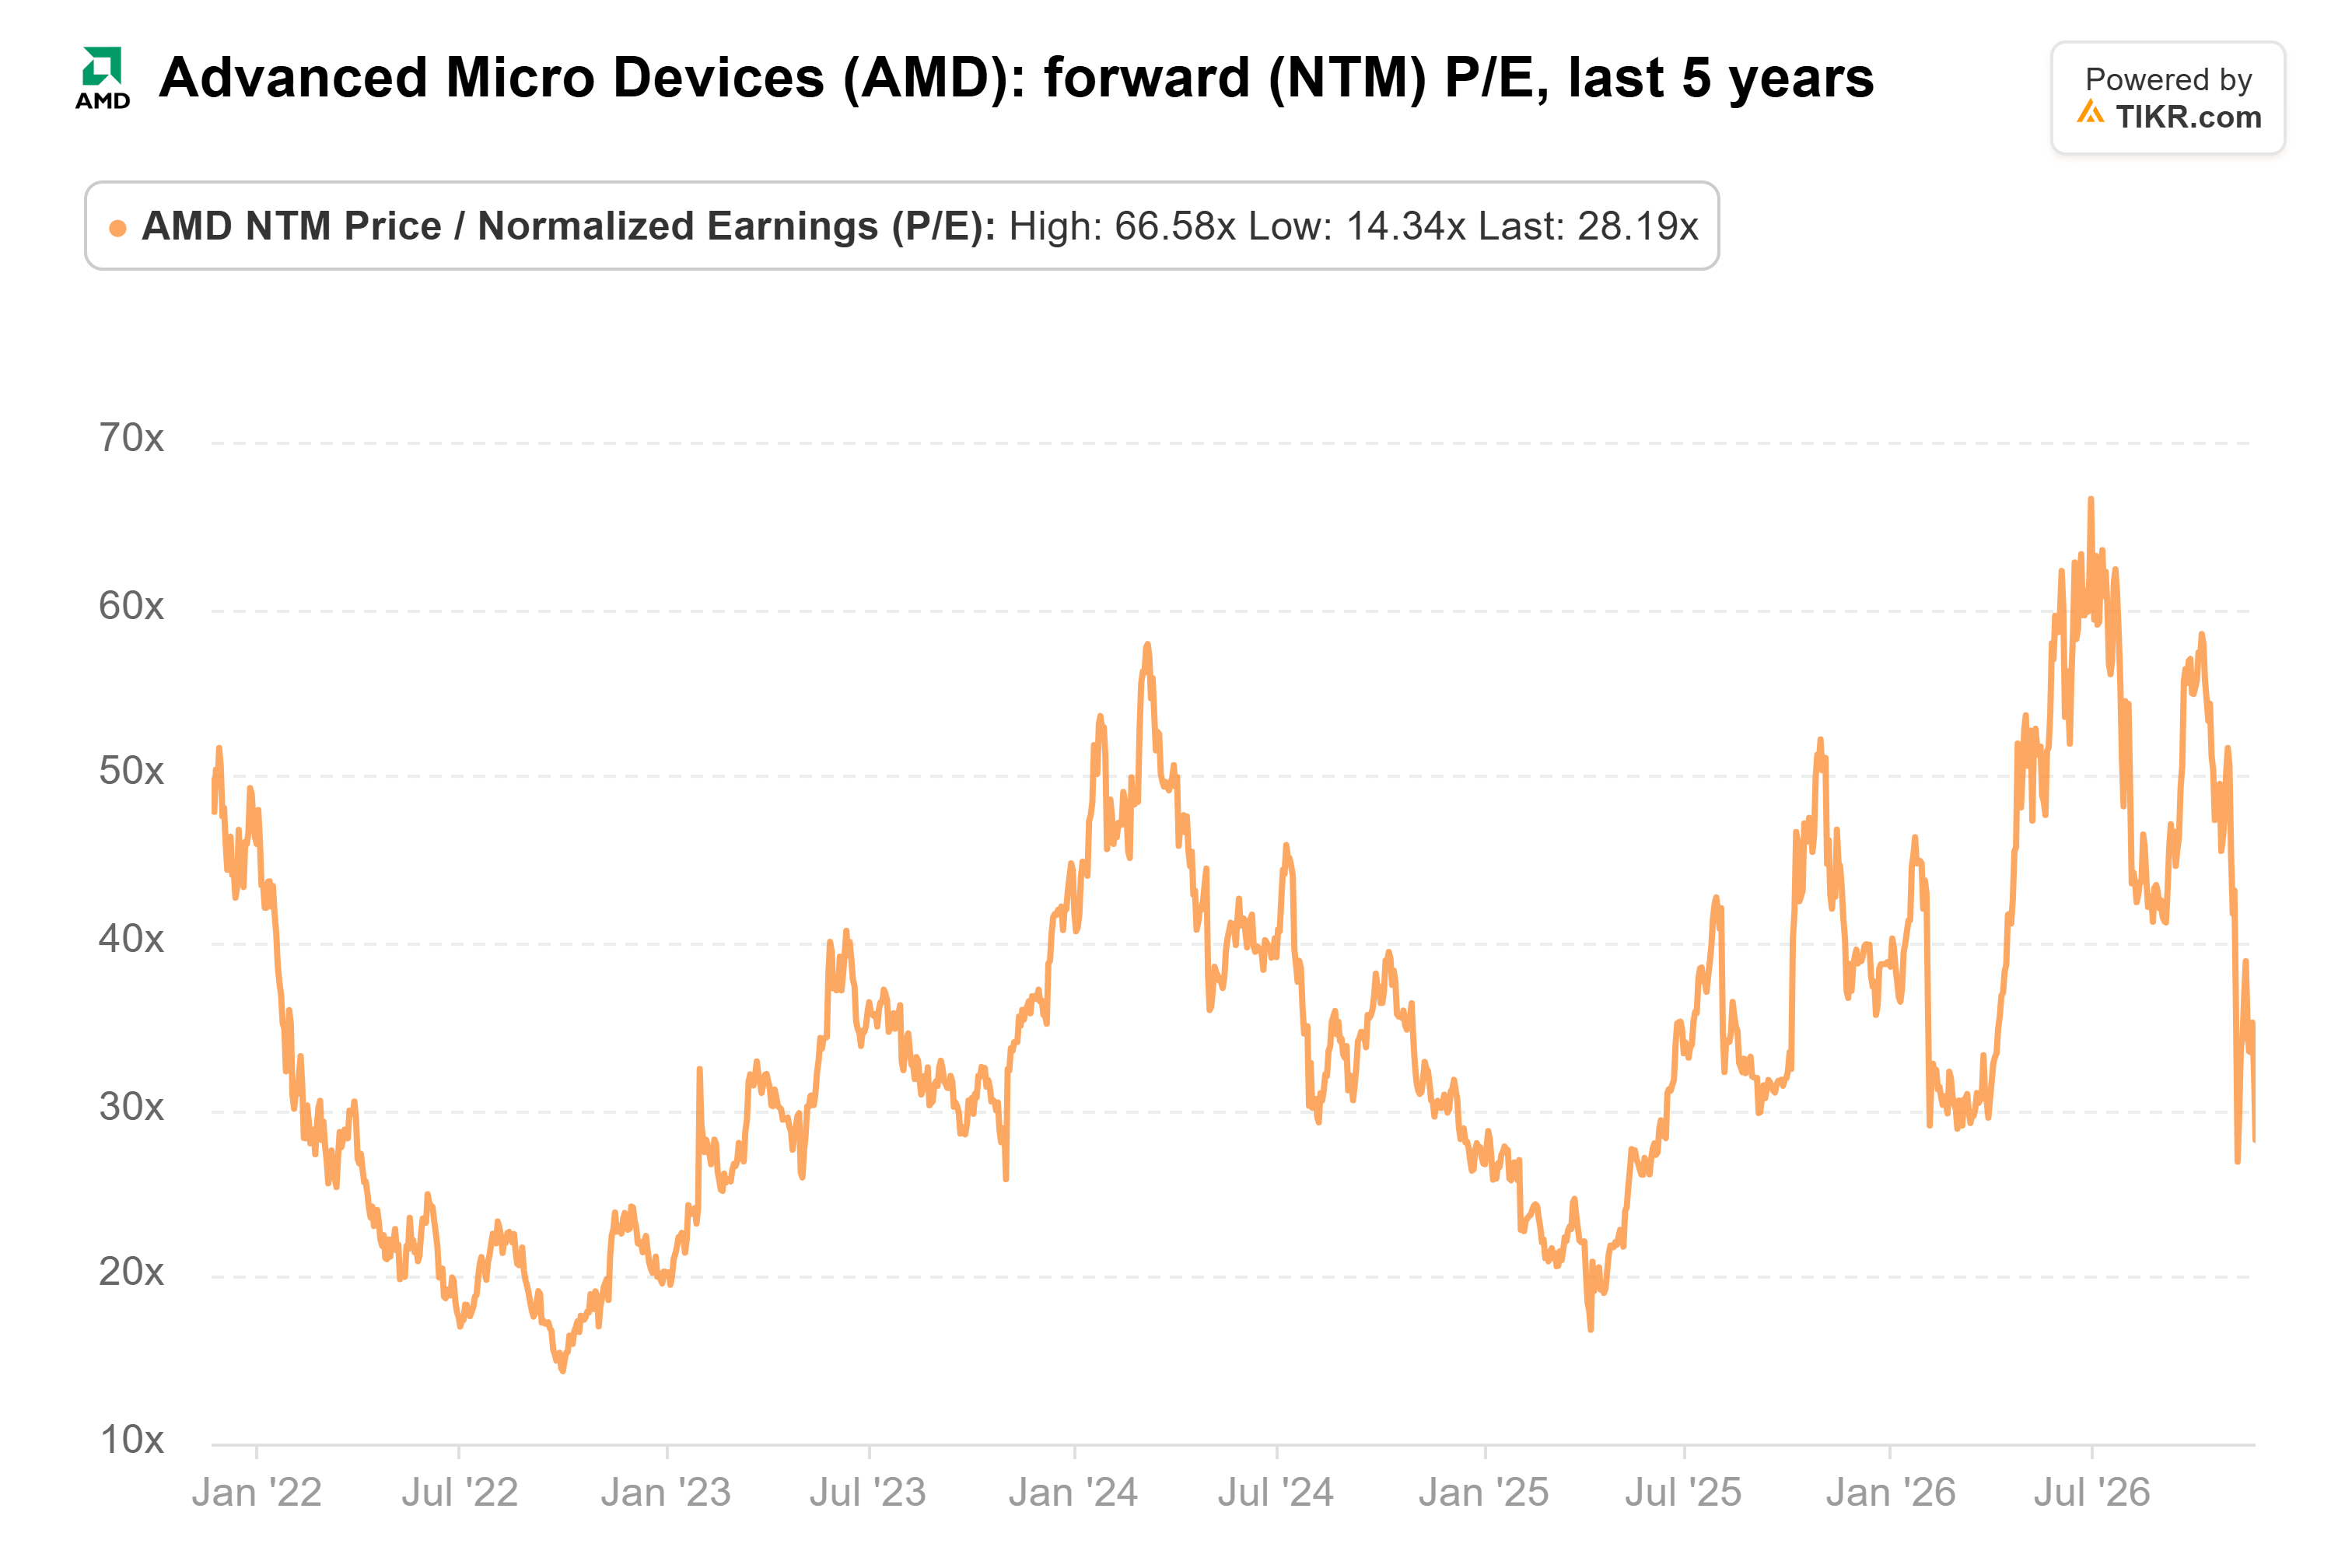
And investors are paying less for those earnings than usual. AMD trades at 28x forward earnings, below its five-year average of 34x and well under the 67x it hit at the end of June:
Price targets have gone up too. The average target is $658, up from $283 a year ago and 55% above Friday’s close:
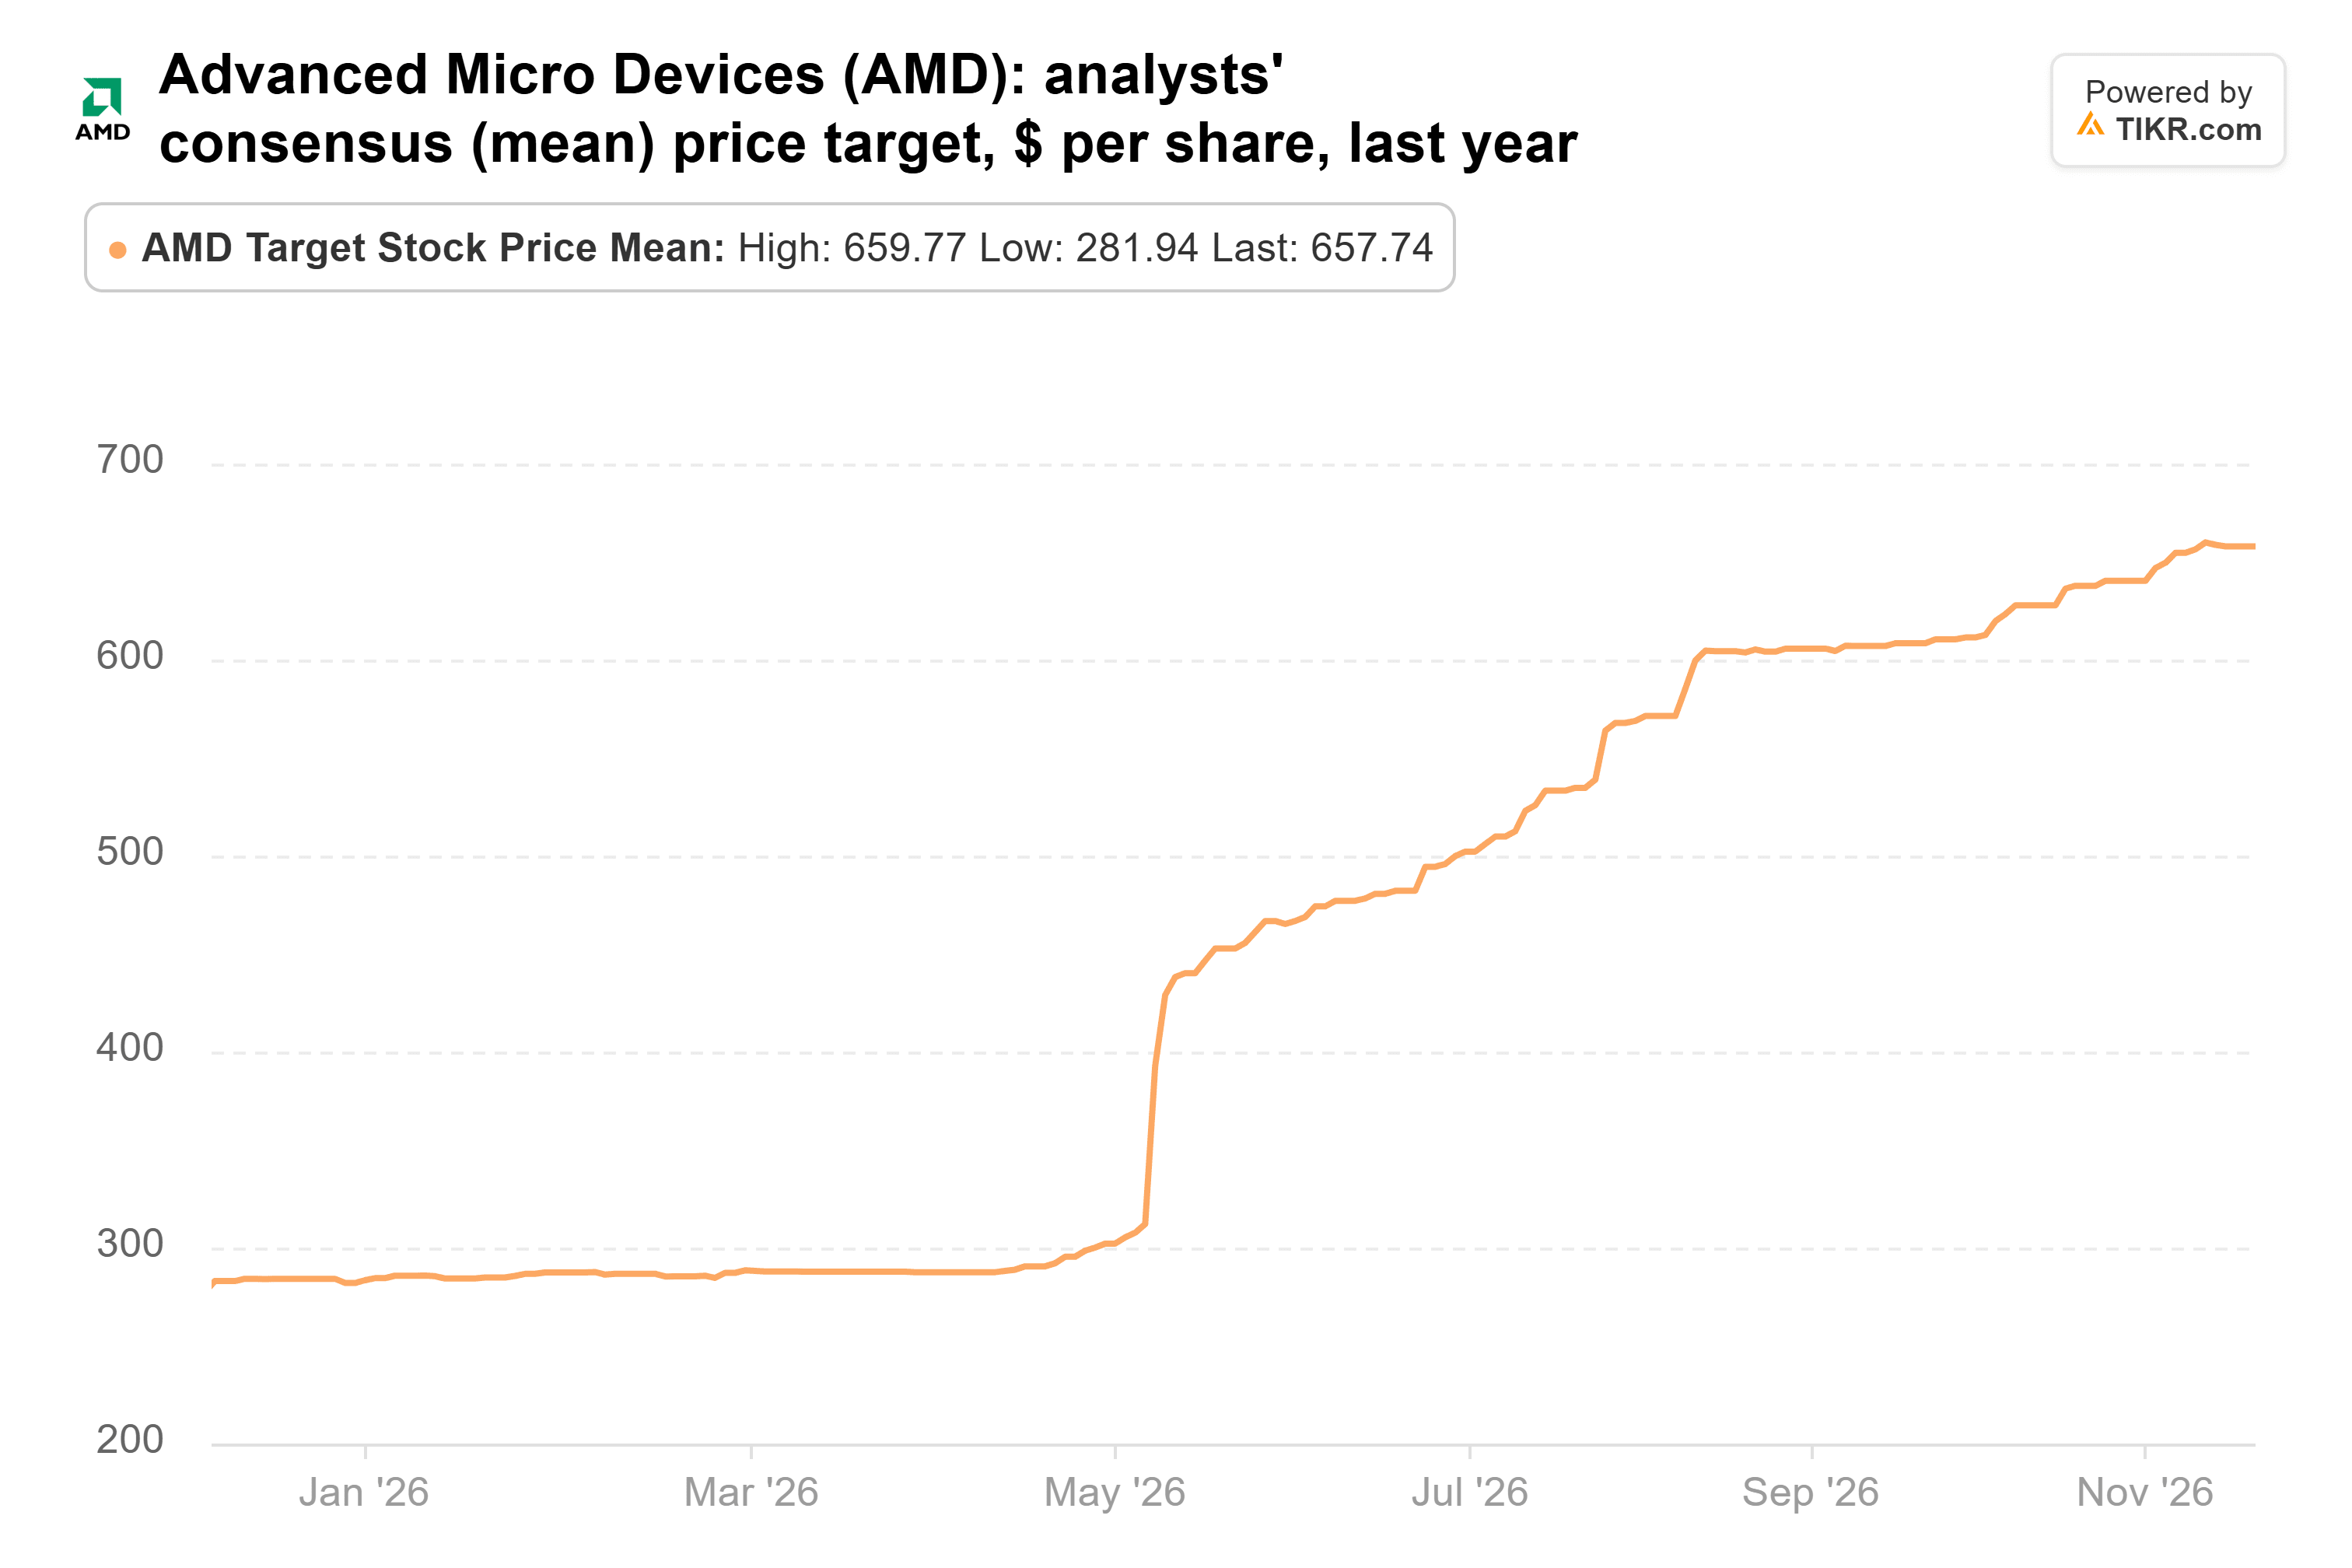
Even the lowest target on TIKR, $525, is above Friday’s close.
Helios has to deliver
The 2027 jump depends on AMD’s Helios racks, which management said would start shipping late in the third quarter. OpenAI and Meta plan up to 6 gigawatts each, and Anthropic up to 2. That puts AMD up against Nvidia, whose data center revenue rose 110% to $107.6 billion in the quarter ended Oct. 25. Nvidia expects total revenue of $130.0 billion next quarter. For AMD, the job is delivering the gigawatts it has already signed, on time.
Supply looks like the smaller worry. AMD says it has enough to more than meet its guidance. And on Nov. 10, the board of TSMC, which makes AMD’s advanced CPU and GPU wafers, approved about $40.9 billion of capital spending, including advanced chip and packaging capacity.
The bigger risks are the export questions above and the warrants AMD gave OpenAI and Meta. Those cover up to 320 million shares, 19.6% of AMD’s share count, and they vest as the two customers deploy Helios.
Still, at 28x earnings that analysts keep raising, the numbers support ARK’s buy, and the stock has room to climb if Helios delivers. The test is AMD’s fourth-quarter report, expected in early February. Helios volume with a gross margin at or above 55%, the bottom of AMD’s long-term range, would confirm the case. ARK’s next 13F, due by mid-February, will show what it held at Dec. 31.
So what is AMD stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AMD could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!