Key Takeaways
- Broadcom fell 9% today on fears that Democrats’ midterm wins will slow US data center building.
- Analysts expect Broadcom’s normalized EPS to nearly triple from fiscal 2025 to fiscal 2027.
- The selloff prices in a policy risk that hasn’t touched Broadcom’s results, and the stock went in below its usual multiple.
- The test is Broadcom’s Dec. 9 report and its fiscal 2027 AI outlook.
Broadcom (AVGO) is down 9% today with no news of its own, in a chip rout across the AI supply chain.
Democrats won both chambers of Congress in the Nov. 3 midterms, and traders fear tighter AI rules and slower data center construction. A big phone chipmaker’s guidance after Wednesday’s close added to the selling.
The rest of the AI supply chain fell harder
Suppliers deeper in the AI build-out had a worse day than Broadcom, though both had just reported strong quarters. Chip packager ASE Technology Holding Co. (ASX) is off 19%, a week after a strong report: on Oct. 29, it said third-quarter revenue rose 45% from a year earlier. Storage company Everpure (P) has lost 16% and is in the same boat: revenue grew 38% in its fiscal second quarter, which ended Aug. 2, and it raised its full-year guidance on momentum in AI and hyperscale products.
Ciena (CIEN) had no news either, but fell 15% with optical stocks on worries that hyperscalers will slow their networking orders too.
Applied Digital (APLD) dropped 17% on data center permit fears after Democratic wins in Texas. Yet Applied Digital’s leased campuses, worth about $36 billion of revenue over their base terms, are in North Dakota, Louisiana and Alabama. That looks like guilt by association.
TIKR tracks 51 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
Analysts are counting on the buildout
Broadcom guided on Sept. 2 to $21.7 billion of AI chip revenue for its fiscal fourth quarter, and analysts expect normalized EPS to climb from $6.82 in fiscal 2025 to $30.37 in fiscal 2028.
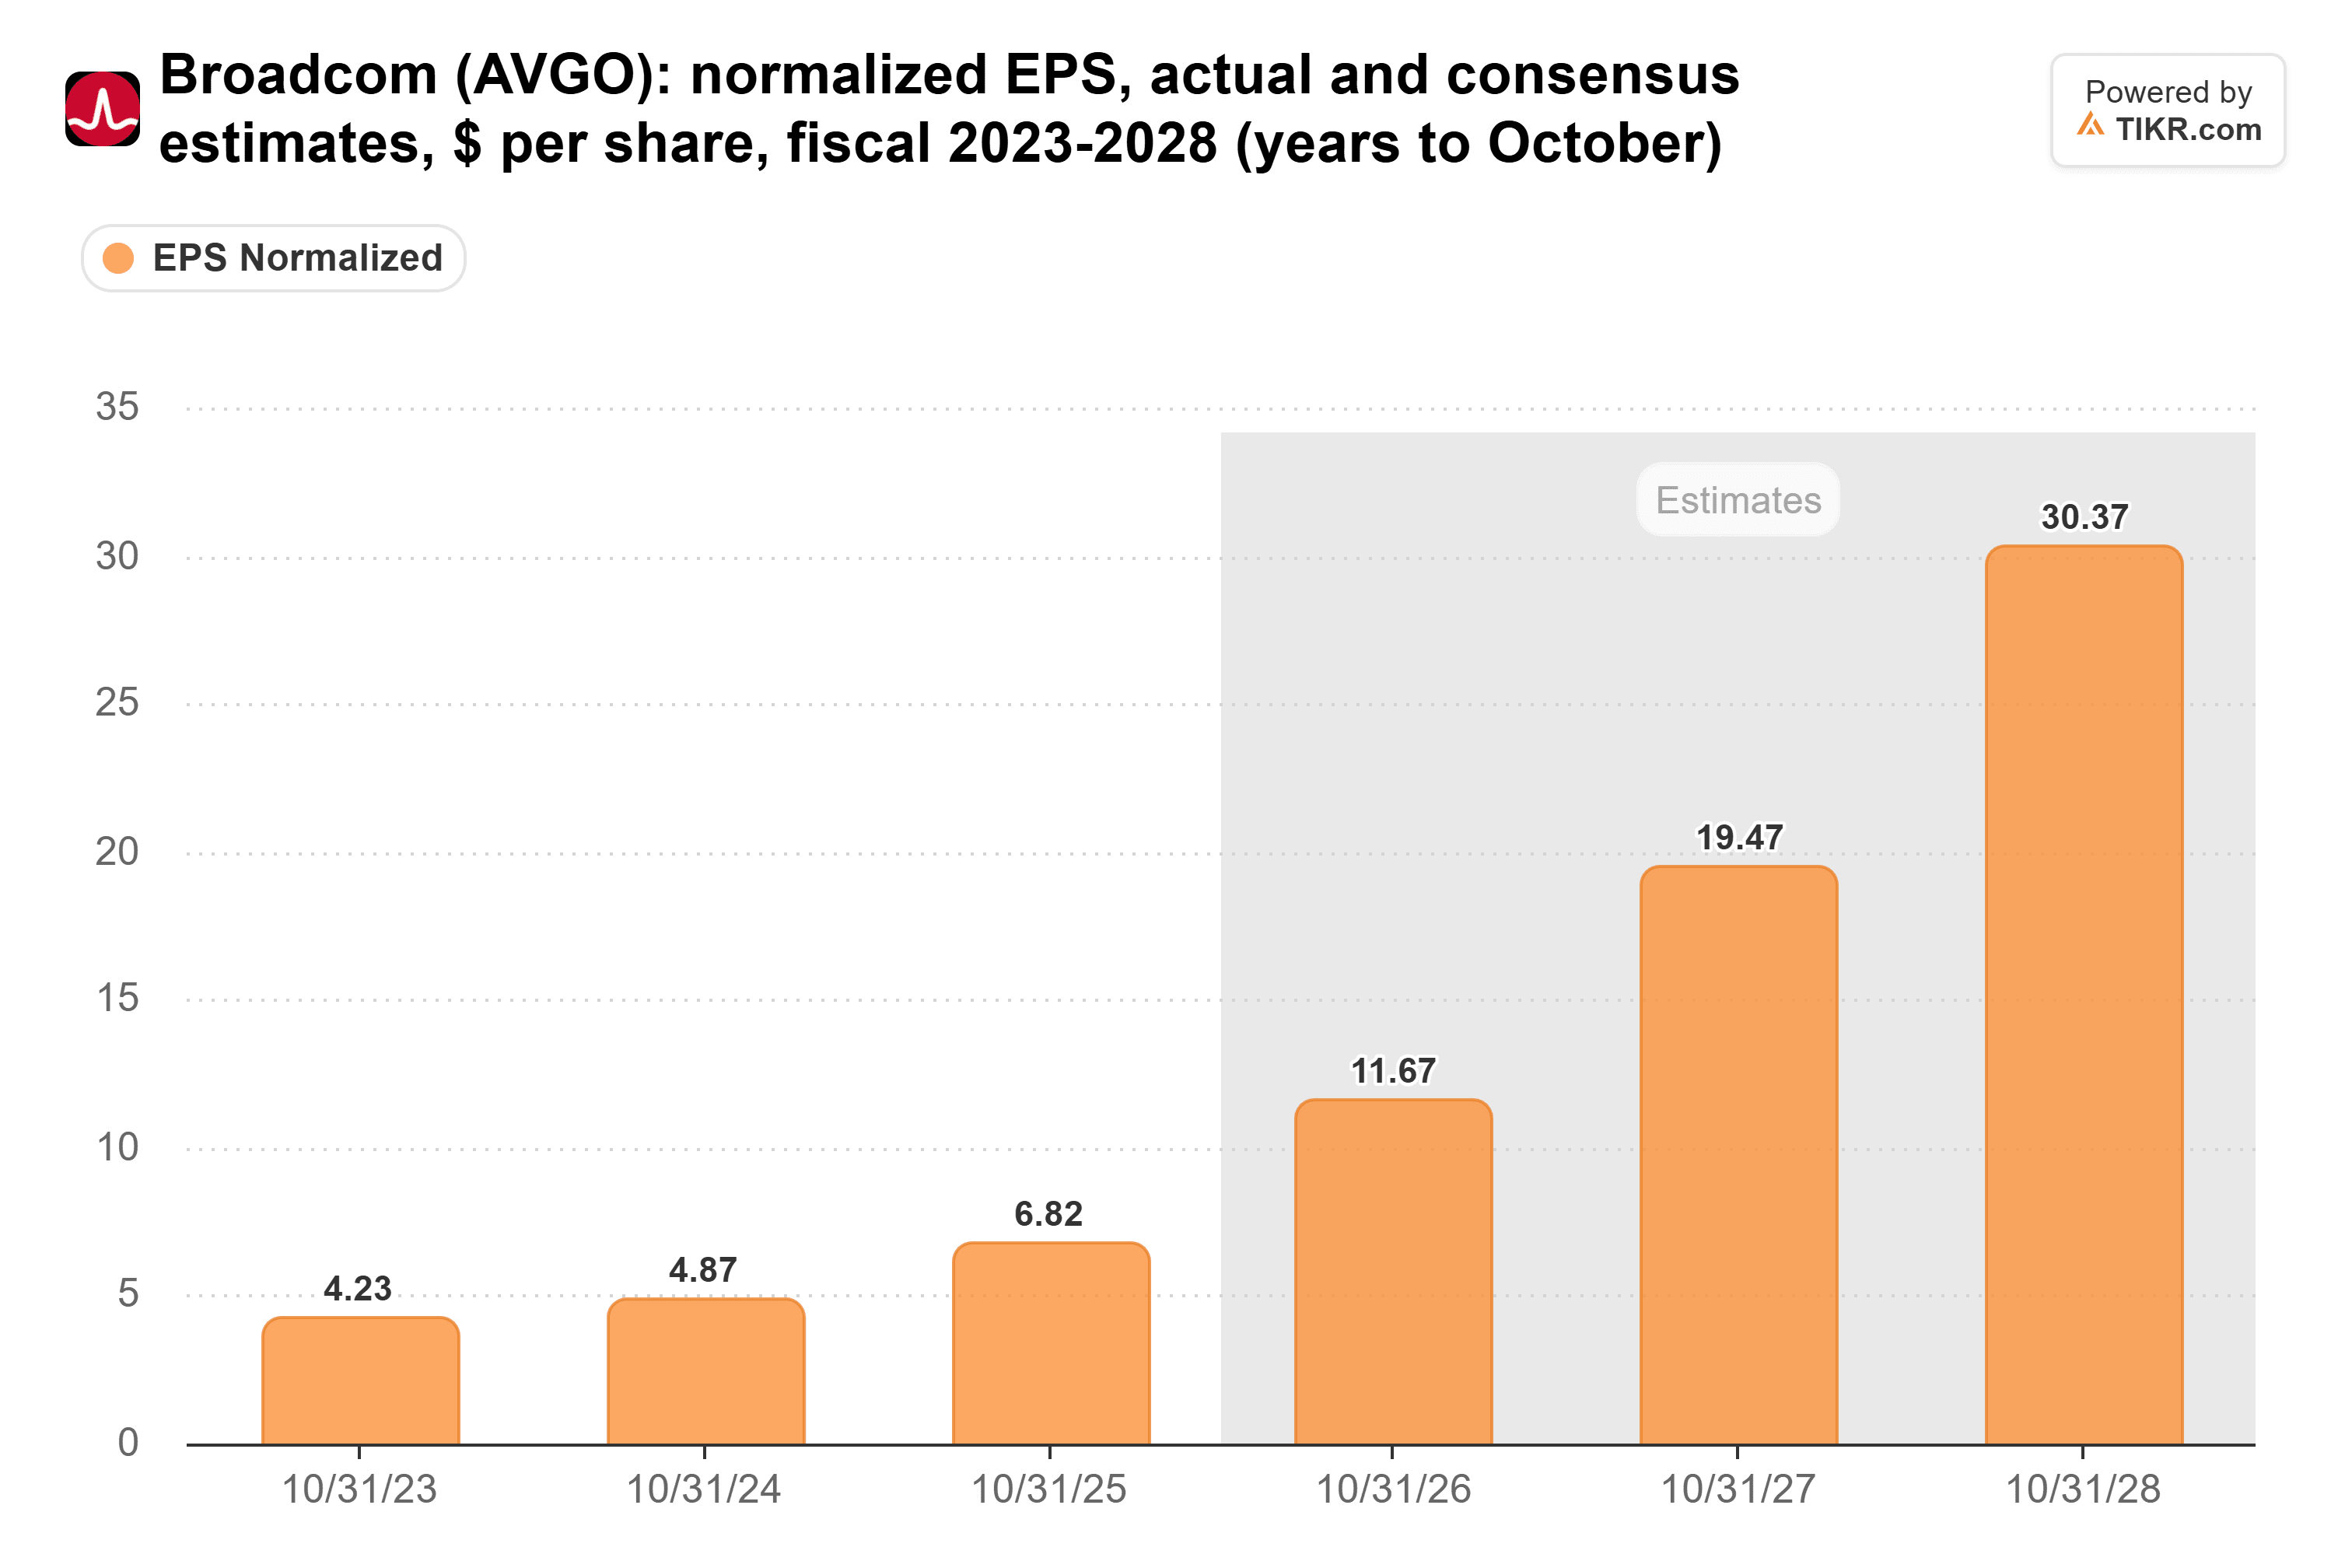
None of today’s news came from Broadcom, so I don’t see those estimates moving before Dec. 9.
Washington could still matter: on Broadcom’s third-quarter call, CEO Hock Tan called land, power and the building shell “more than a big concern.”
But Broadcom had $179.2 billion of committed contract value at Aug. 2, up from $33.3 billion nine months earlier.
Cheaper than usual going in
Broadcom went into today at under 19x forward earnings, well below its five-year average of 24x.
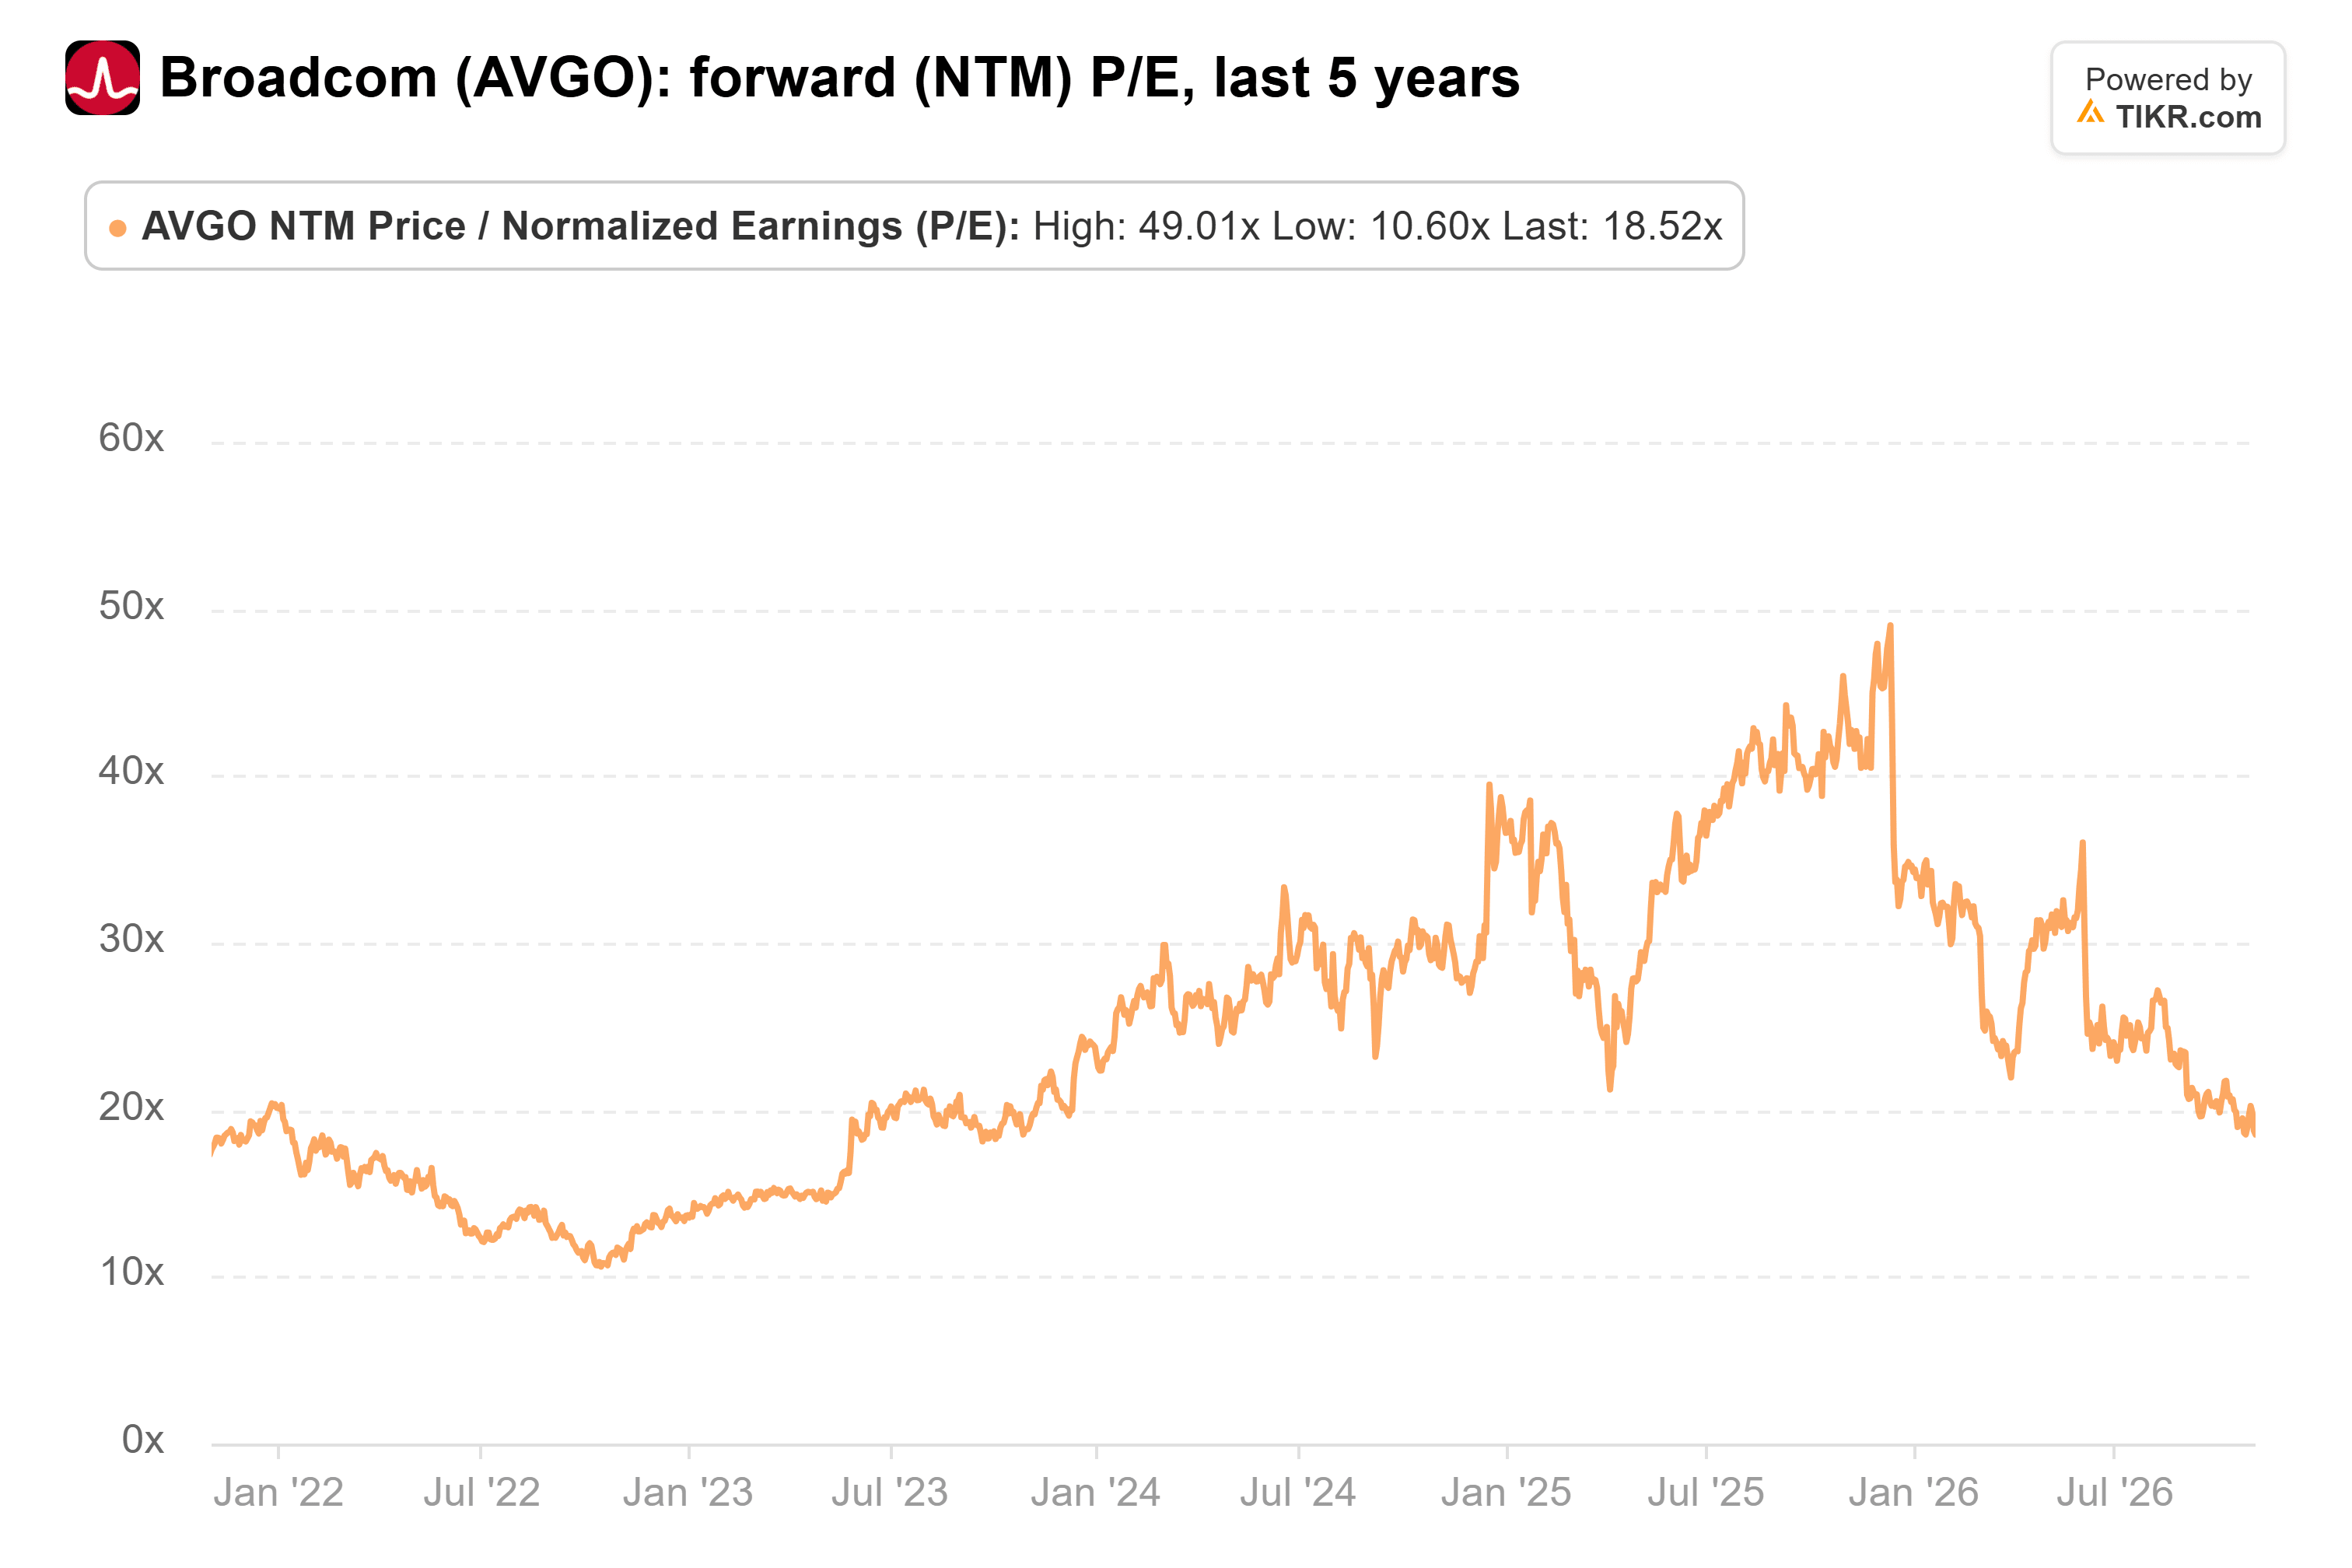
At today’s price, it’s lower still.
The bigger risk is the financing: Broadcom backstops up to about $29 billion of leases for Anthropic’s chips, plus up to about $43 billion more on a second package.
Frankly, this looks like a policy scare priced in before any policy exists, and Broadcom is cheaper for it.
If management still sees about $115 billion of AI revenue for fiscal 2027 on Dec. 9, today’s drop will look like a gift. If not, the market had it right.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!