Key Takeaways
- Broadcom shares fell 11% today as Anthropic gave back much of its IPO pop. Broadcom expects Anthropic to be its largest custom AI chip customer in 2027.
- Broadcom guarantees up to about $29 billion of Anthropic-linked leases, more than its $24.0 billion of cash, but Anthropic just raised $81.3 billion in its IPO.
- Revenue ties the two together more tightly than the guarantee does, and TSMC and Amazon have their own money on Anthropic.
- Broadcom trades below its five-year average multiple, and its Dec. 9 report is the real test.
Broadcom (AVGO) sank 11% today, and the company at the center of its growth plan is a big reason why. Anthropic (ANT) fell 10% on its second day of trading and gave back much of Thursday’s record debut.
Anthropic priced its IPO at $83 a share and opened Thursday at $111.50, so it still trades above the IPO price. Taiwan Semiconductor (TSM) fell 7%, just after its board approved buying up to $500 million of Anthropic stock at the IPO price. Amazon (AMZN), which owns a stake in Anthropic, barely moved, up 0.4%.
Anthropic sits at the center of Broadcom’s growth plan
On its Sept. 2 call, Broadcom said Anthropic is on track to be its largest custom AI chip customer in 2027. Anthropic is set to take 5 gigawatts of capacity that year and 10 more in 2028, about half of the roughly 30 gigawatts management sees across fiscal 2027 and 2028, if the data center sites are ready. Analysts expect Broadcom’s revenue to more than quadruple between fiscal 2025 and fiscal 2028:
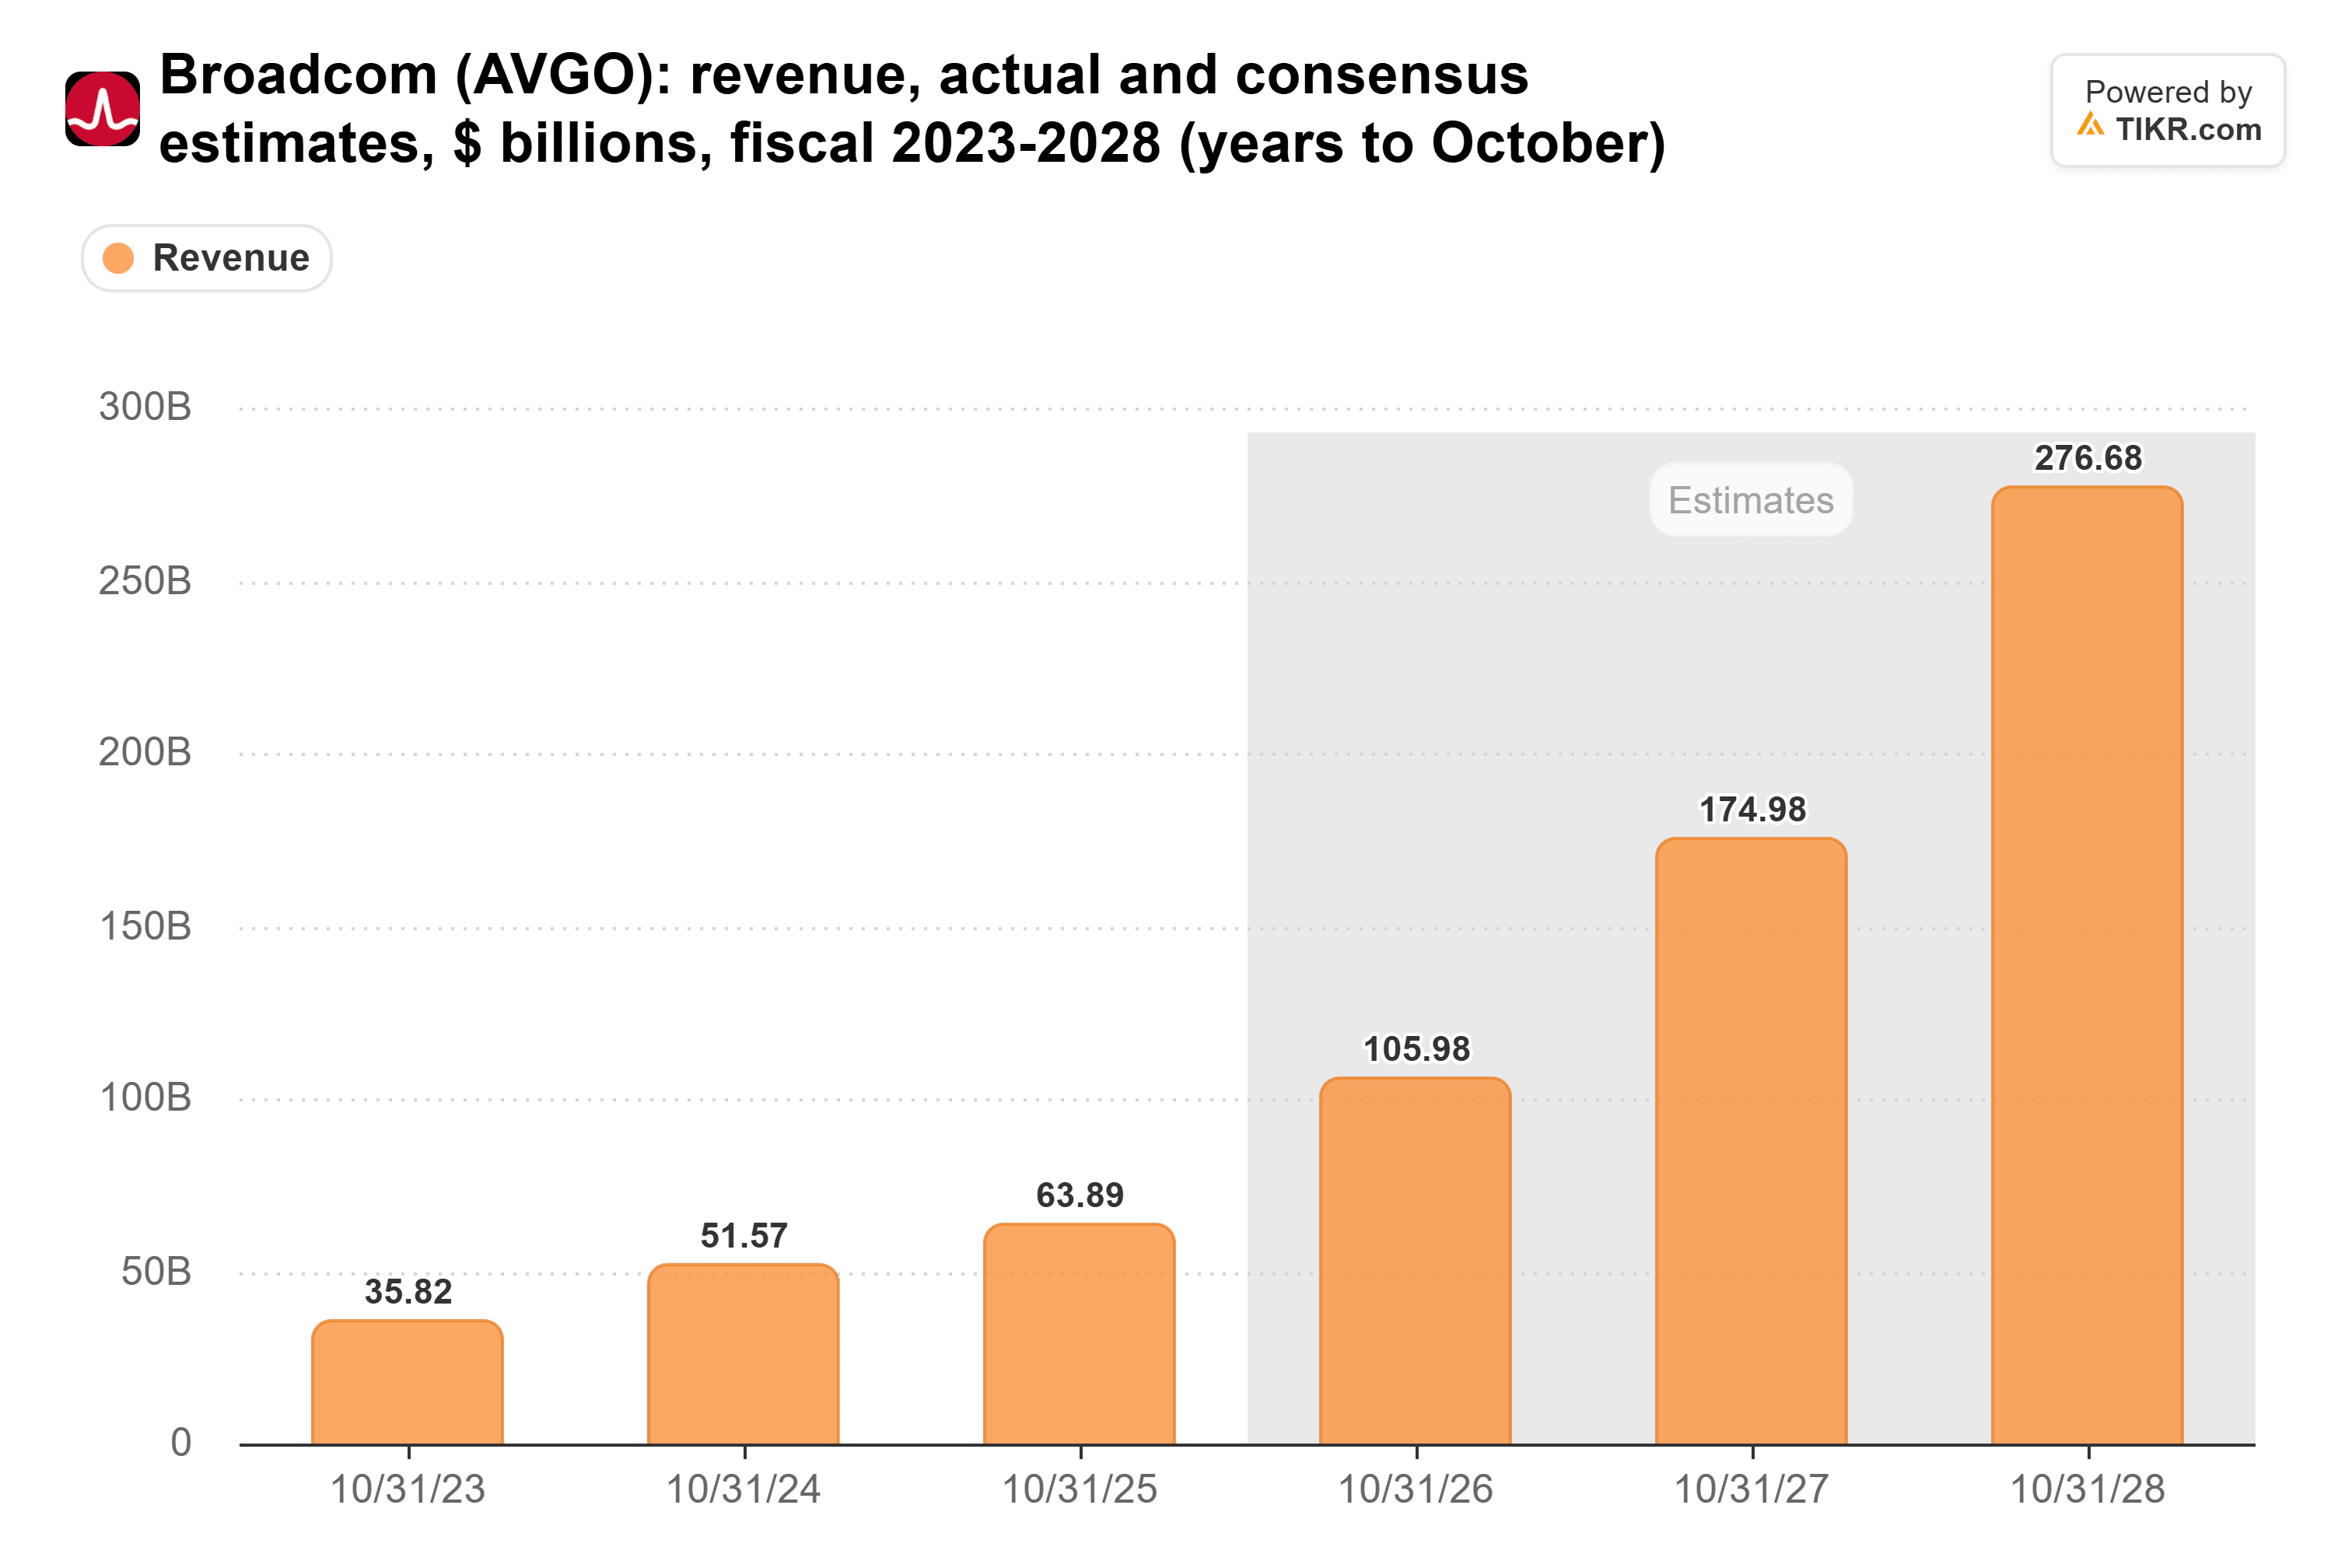
Analysts set those estimates before today’s drop, and they assume Anthropic builds on schedule.
TIKR tracks 51 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
A $29 billion promise, with plenty of Anthropic cash behind it
Broadcom also stands behind Anthropic’s bills. Its latest 10-Q says it backstops up to about $29 billion of leases tied to Anthropic’s computing capacity, and it may lend Anthropic up to $42 billion through convertible notes, though none had been issued as of Aug. 2. Before the IPO, Ed Zitron called the guarantee foolish. The backstop alone is bigger than the cash Broadcom held on Aug. 2:
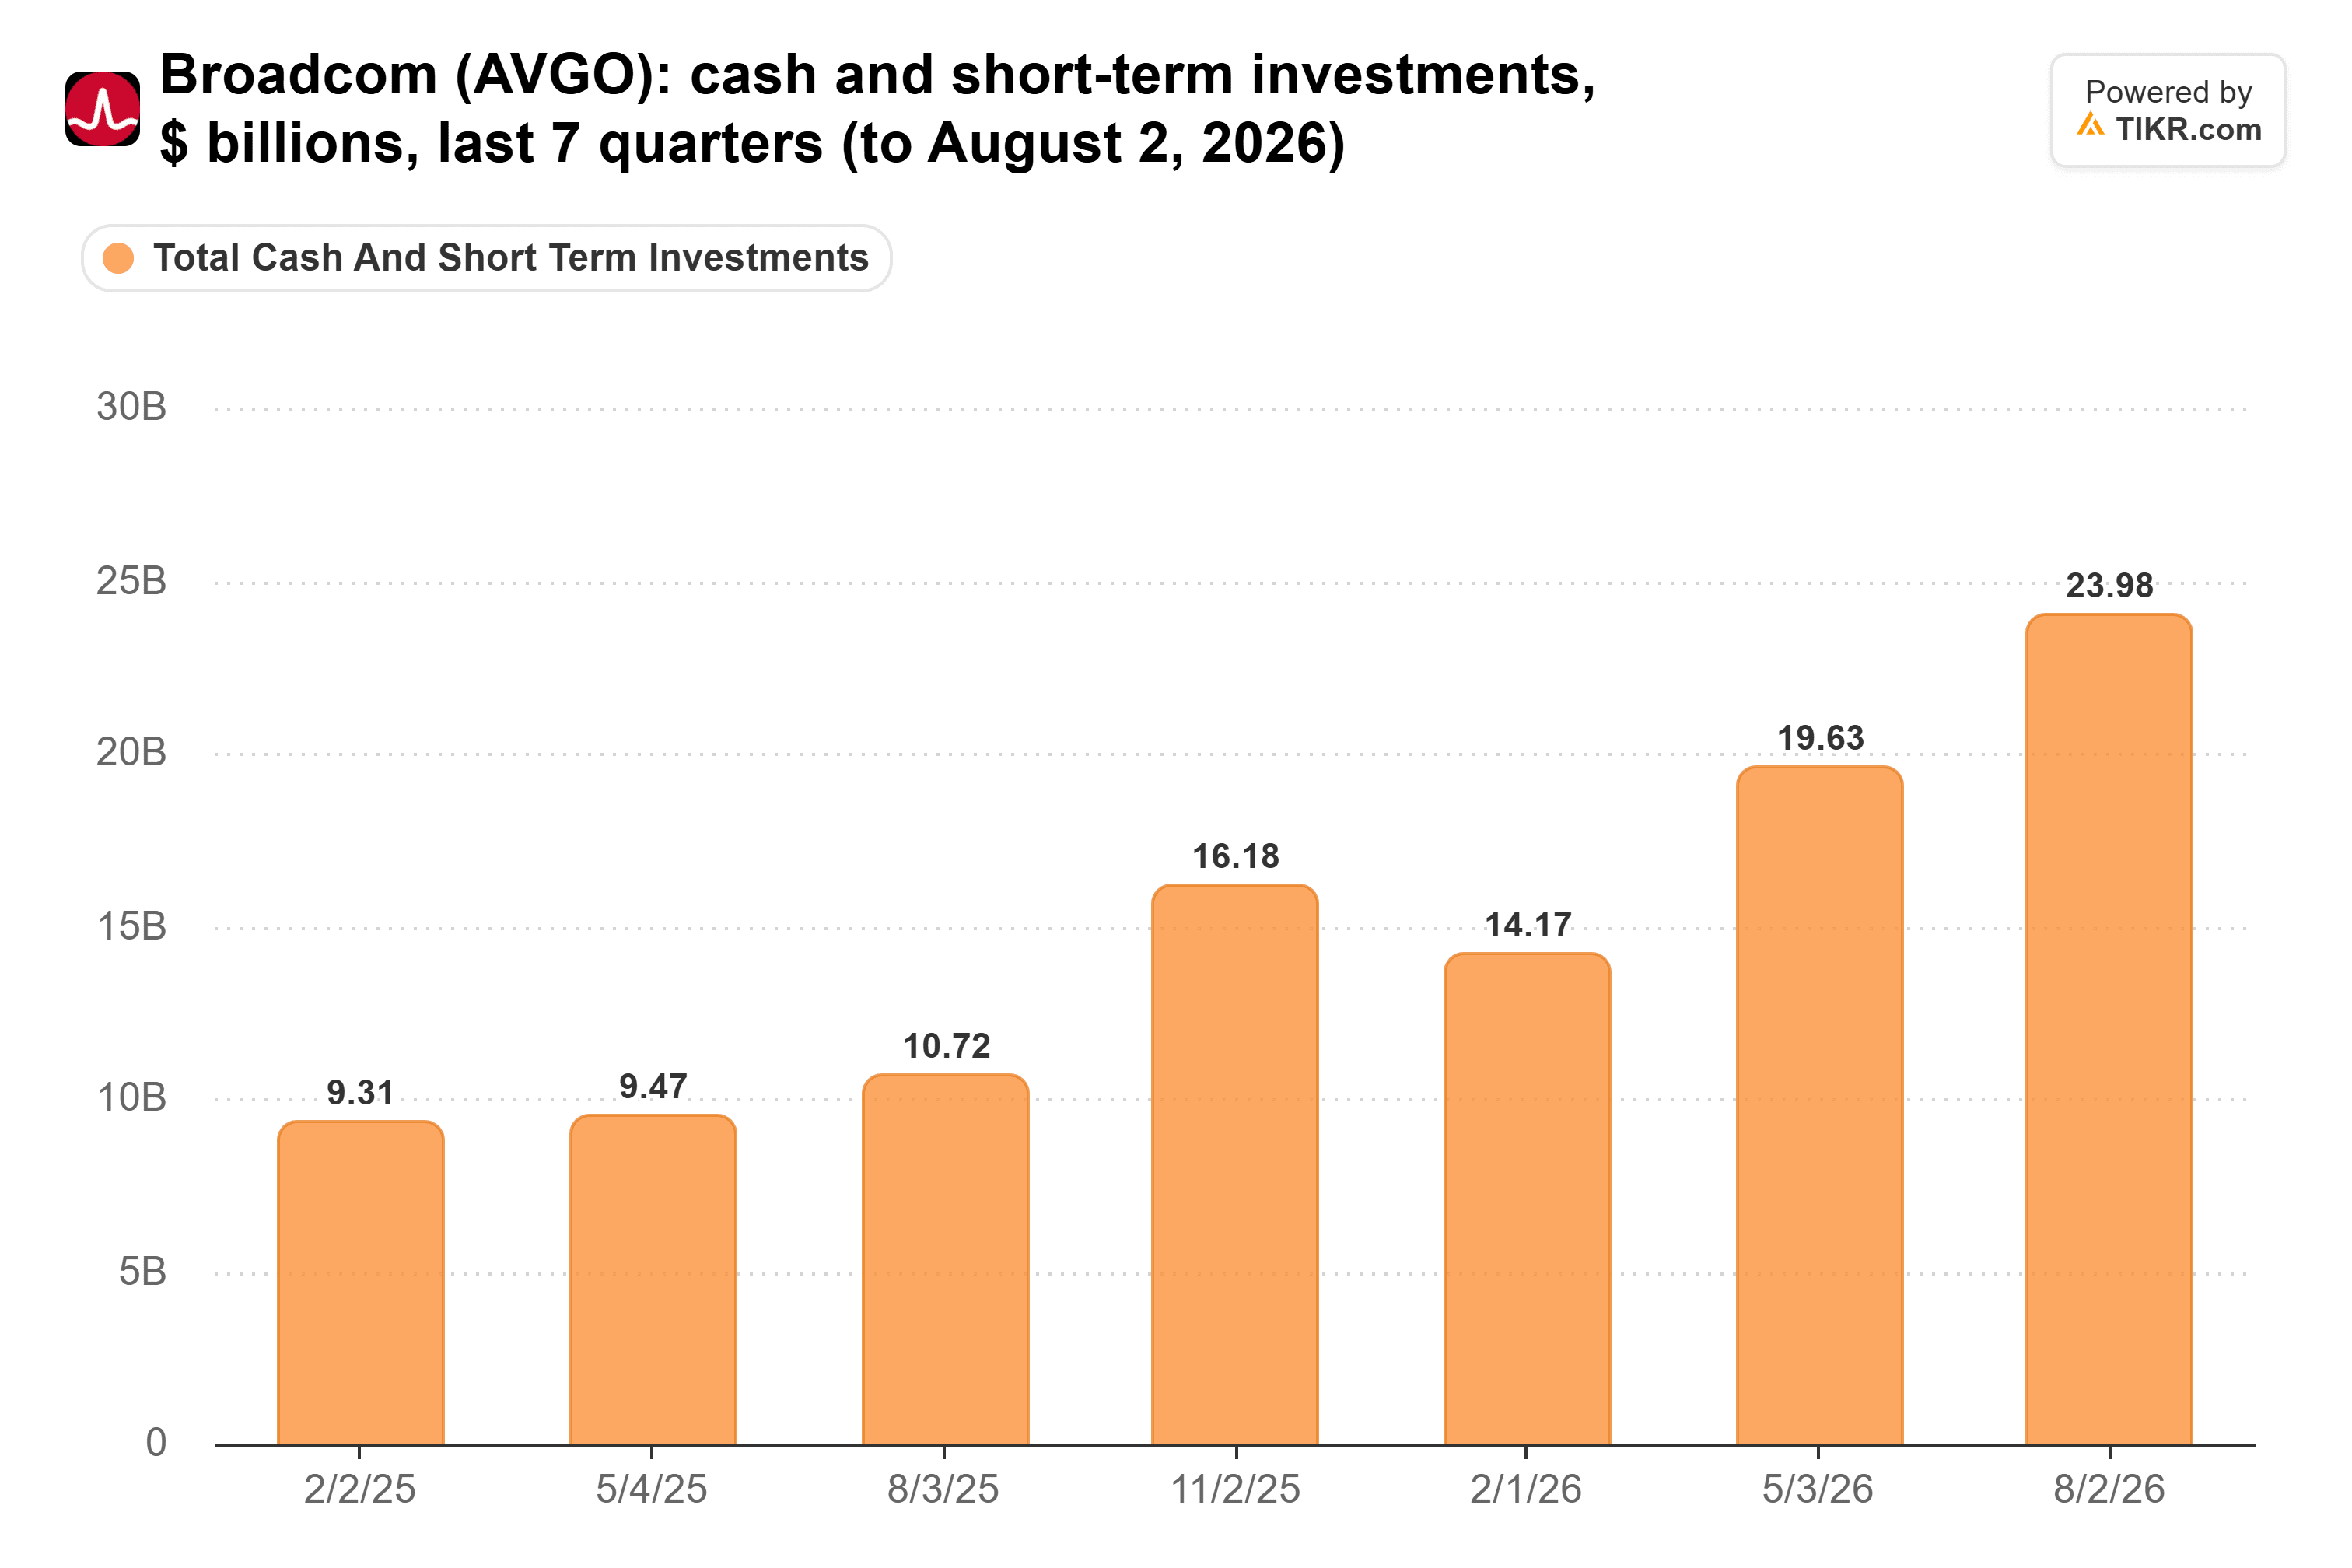
But Anthropic pays its leases out of its own cash, and the IPO brought in $81.3 billion. That comes on top of a $26 billion private placement and the $132 billion of cash and short-term investments Anthropic held at Sept. 30. Broadcom hasn’t paid anything under the guarantee, and Anthropic can cover this year’s leases whatever its stock does.
Bloomberg reported that Goldman Sachs, a lead bank on the IPO, doesn’t expect Anthropic’s free cash flow to turn positive until 2030. My read: Anthropic will need to raise money again before then, and a lower share price makes that raise more expensive. That’s when Broadcom’s notes could come into play.
Amazon has an owner’s upside, and Broadcom has a guarantor’s risk
TSMC and Amazon also have money riding on Anthropic, but their positions look very different from Broadcom’s. TSMC makes the custom chips Broadcom designs, so it would build much of the hardware behind Anthropic’s 15 gigawatts. Next to that, its stock purchase is small.
Amazon owns equity in Anthropic and offers its Claude models on AWS’s Bedrock service. Its third-quarter GAAP net income fell to $20.7 billion from $21.2 billion a year earlier, which Amazon blamed mainly on the $9.5 billion of pre-tax Anthropic gains it booked in the year-ago quarter. Amazon gets an owner’s upside from Anthropic. Broadcom gets a supplier’s revenue and a guarantor’s risk, and today’s moves show which of those the market prefers.
Broadcom’s real test is Dec. 9
Even before today’s drop, investors were paying less for Broadcom’s earnings than their five-year average:
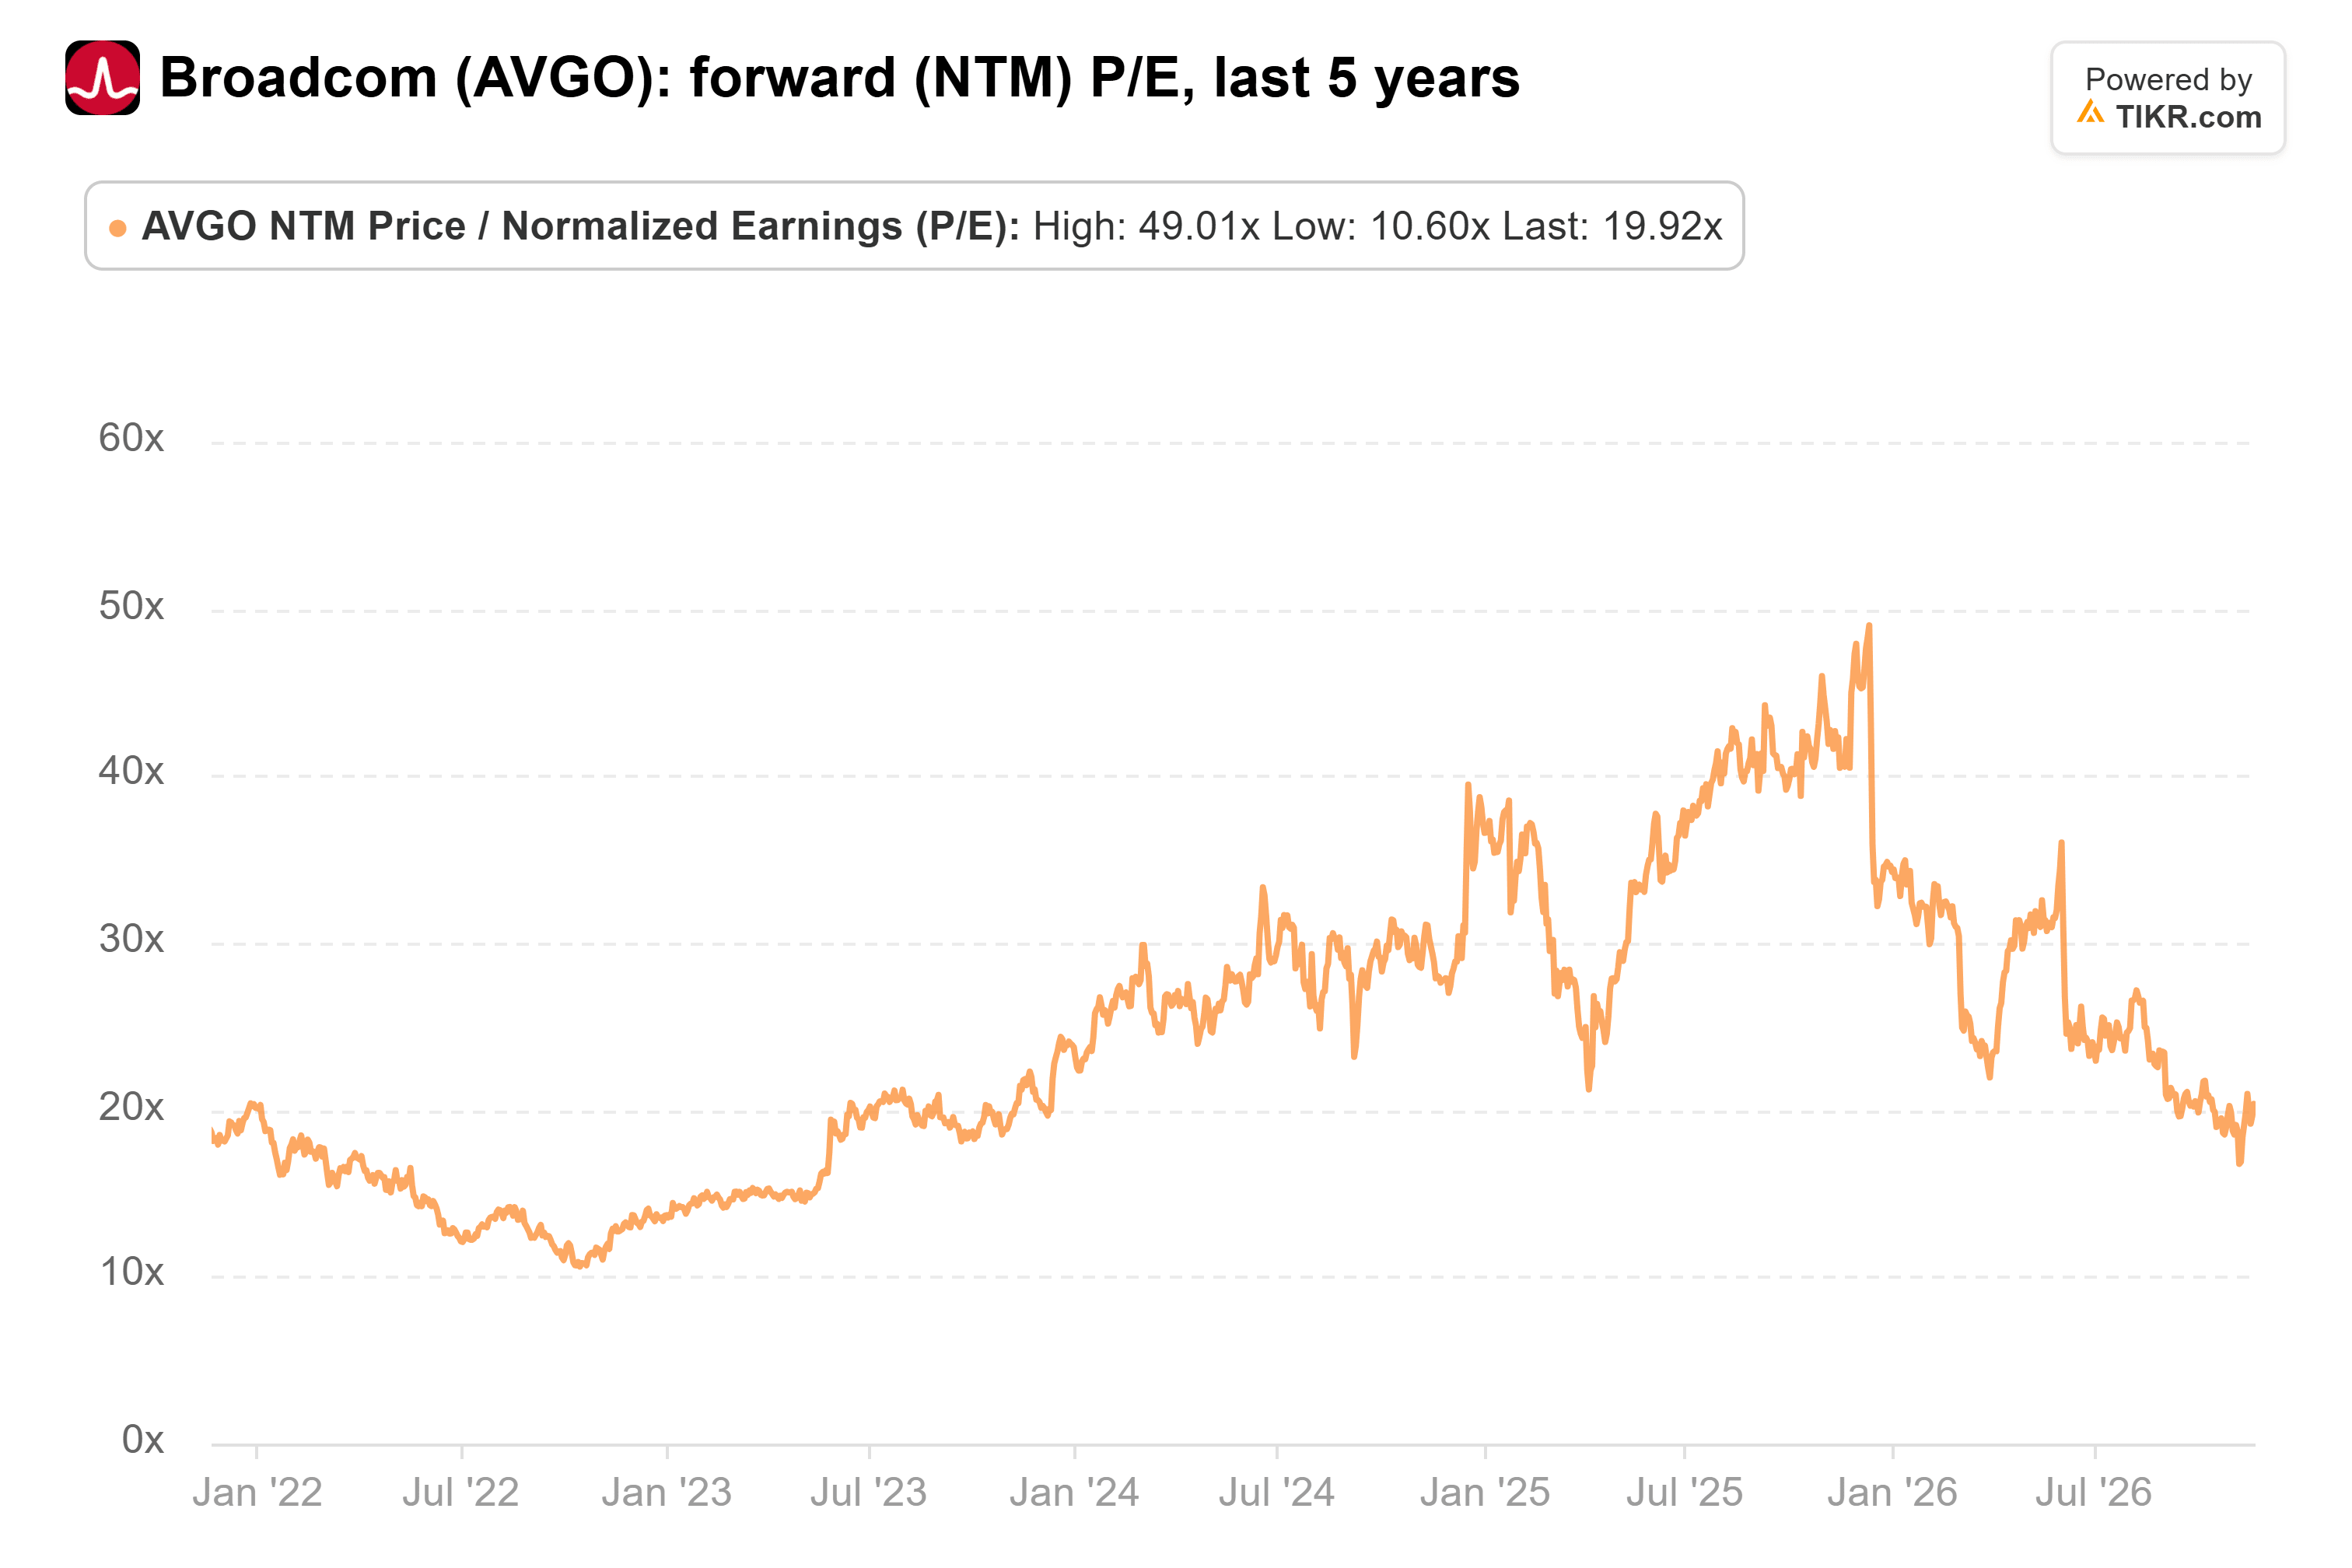
Broadcom traded at 20x forward earnings at the last close, compared with a five-year average of 24x and a peak of 49x in December 2025.
The way I see it, the market is treating Anthropic’s stock swings as Broadcom’s credit risk, even though the IPO cash made that risk smaller this week. What’s left is the revenue question. On Dec. 9, Broadcom reports its fiscal fourth quarter. If quarterly AI revenue lands at or above the $21.7 billion it guided and management holds the roughly $115 billion of AI revenue it expects for fiscal 2027, today looks like an overreaction. If the outlook slips, or Anthropic turns to Broadcom’s notes instead of the stock market for its next raise, the bears will have the better argument.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!