Key Takeaways
- Bloom Energy shares rose 6% after BMO Capital Markets upgraded the stock to Outperform on the day of Anthropic’s IPO.
- BMO, once a skeptic, now likes Bloom’s contract protections and milestone payments, though it cut its target to $230 from $260.
- Nebius’s projects support BMO’s case, and Oracle’s 2.8-gigawatt order will test Bloom’s contracts at scale.
- BMO’s target is about 28x analysts’ 2028 earnings estimate, and Bloom’s 2027 guidance early next year is the next test.
Bloom Energy (BE) stock jumped 6% this morning after BMO Capital Markets, which had long been a skeptic, upgraded it to Outperform from Market Perform.
Two customers sit behind the call. One is Nebius Group (NBIS), whose deployments BMO calls fresh evidence that Bloom can execute. The other is Oracle (ORCL), whose 2.8-gigawatt order will test Bloom’s contract terms at scale.
TIKR tracks 29 analysts on Bloom Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
What changed BMO’s mind
BMO had doubted that Bloom could execute at scale and hold its own as grid and turbine supply improves. Analyst Ameet Thakkar now points to recent execution, a cheaper stock and large projects like Nebius’s. Meetings with management also left BMO more comfortable with Bloom’s contract protections and its milestone-based customer payments.
Milestone billing is also why contract assets jumped to $858.6 million at Sept. 30 from $241.2 million at the end of 2025. It’s a big reason its record third quarter burned $181 million.
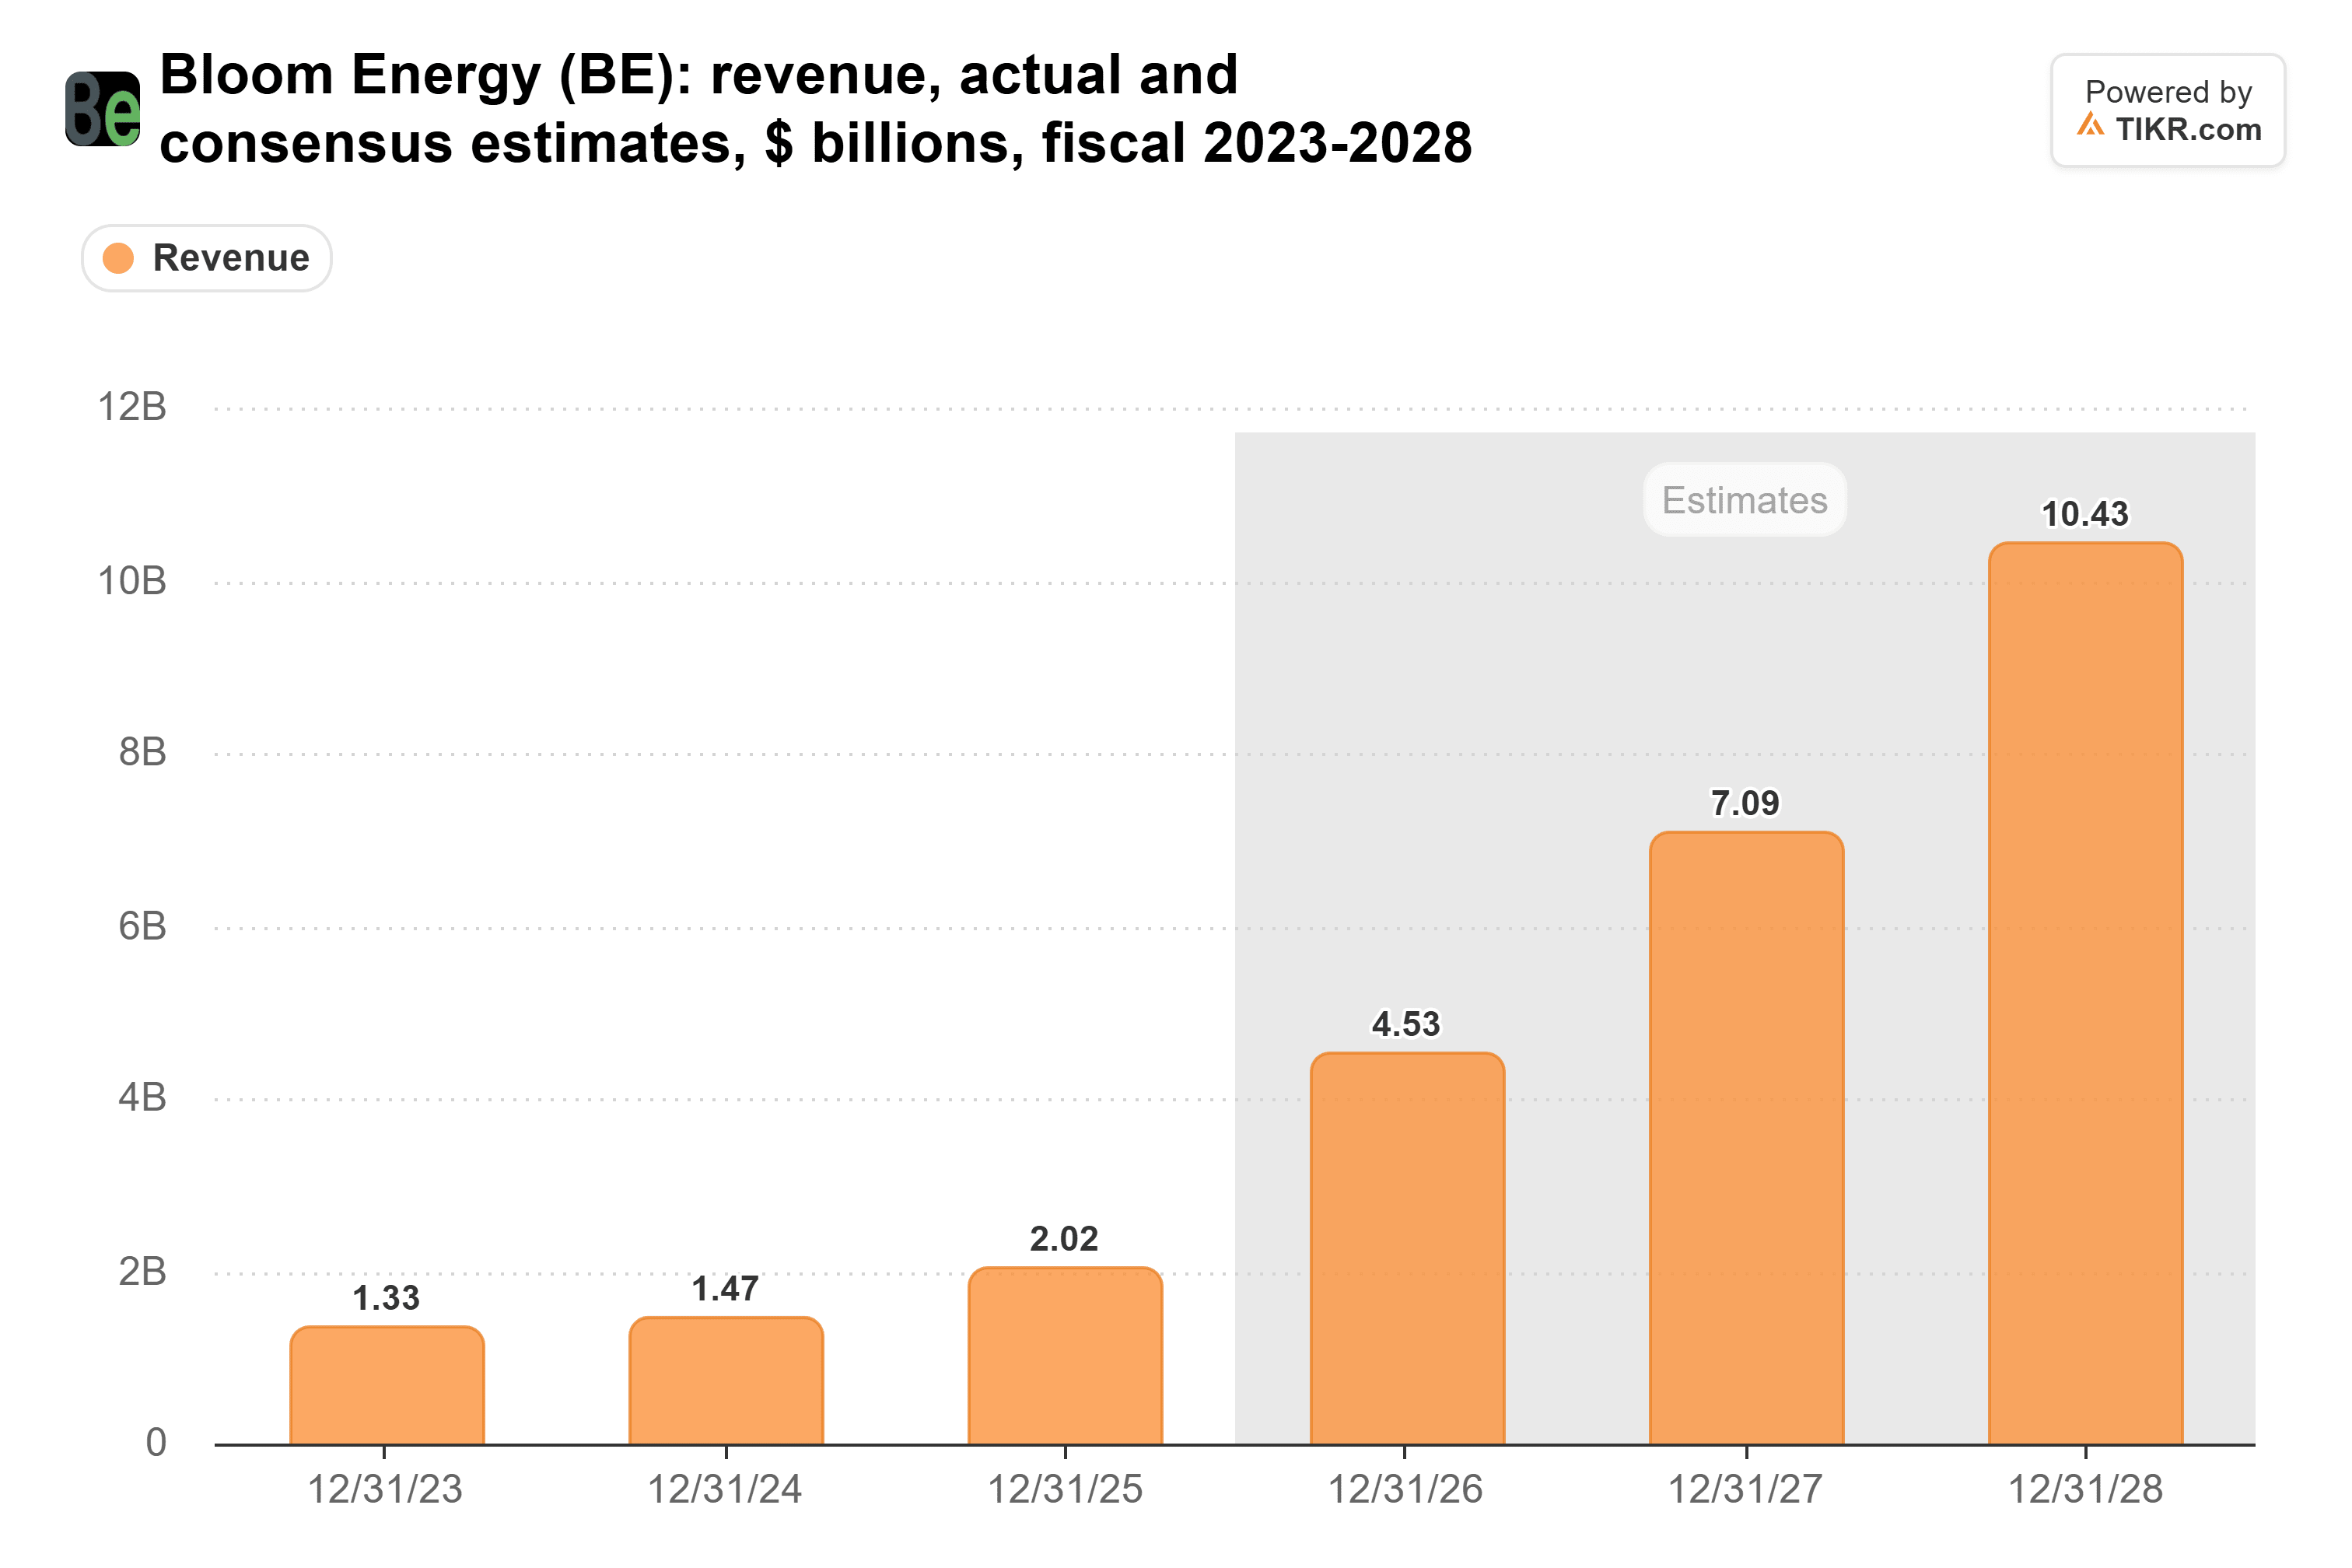
Even with the lower target, BMO expects $7.88 billion of revenue in 2027, about 11% more than the consensus estimate:
Nebius and Oracle have to deliver
Nebius’s third-quarter revenue rose to $980.8 million from $146.1 million a year earlier. It needs power quickly to turn its GPUs into revenue, and fast power is what Bloom sells. Its next report, likely in mid-February, will show whether that buildout is still on pace.
Oracle is the bigger question. Its free cash flow was negative $5 billion in the quarter ended Aug. 31, and it sold $20 billion of stock to help pay for its data centers. Its Dec. 10 report will show whether it keeps spending at the pace Bloom’s deal depends on.
BMO’s $230 looks conservative
Even after the cut, BMO’s target is below analysts’ $284 average:
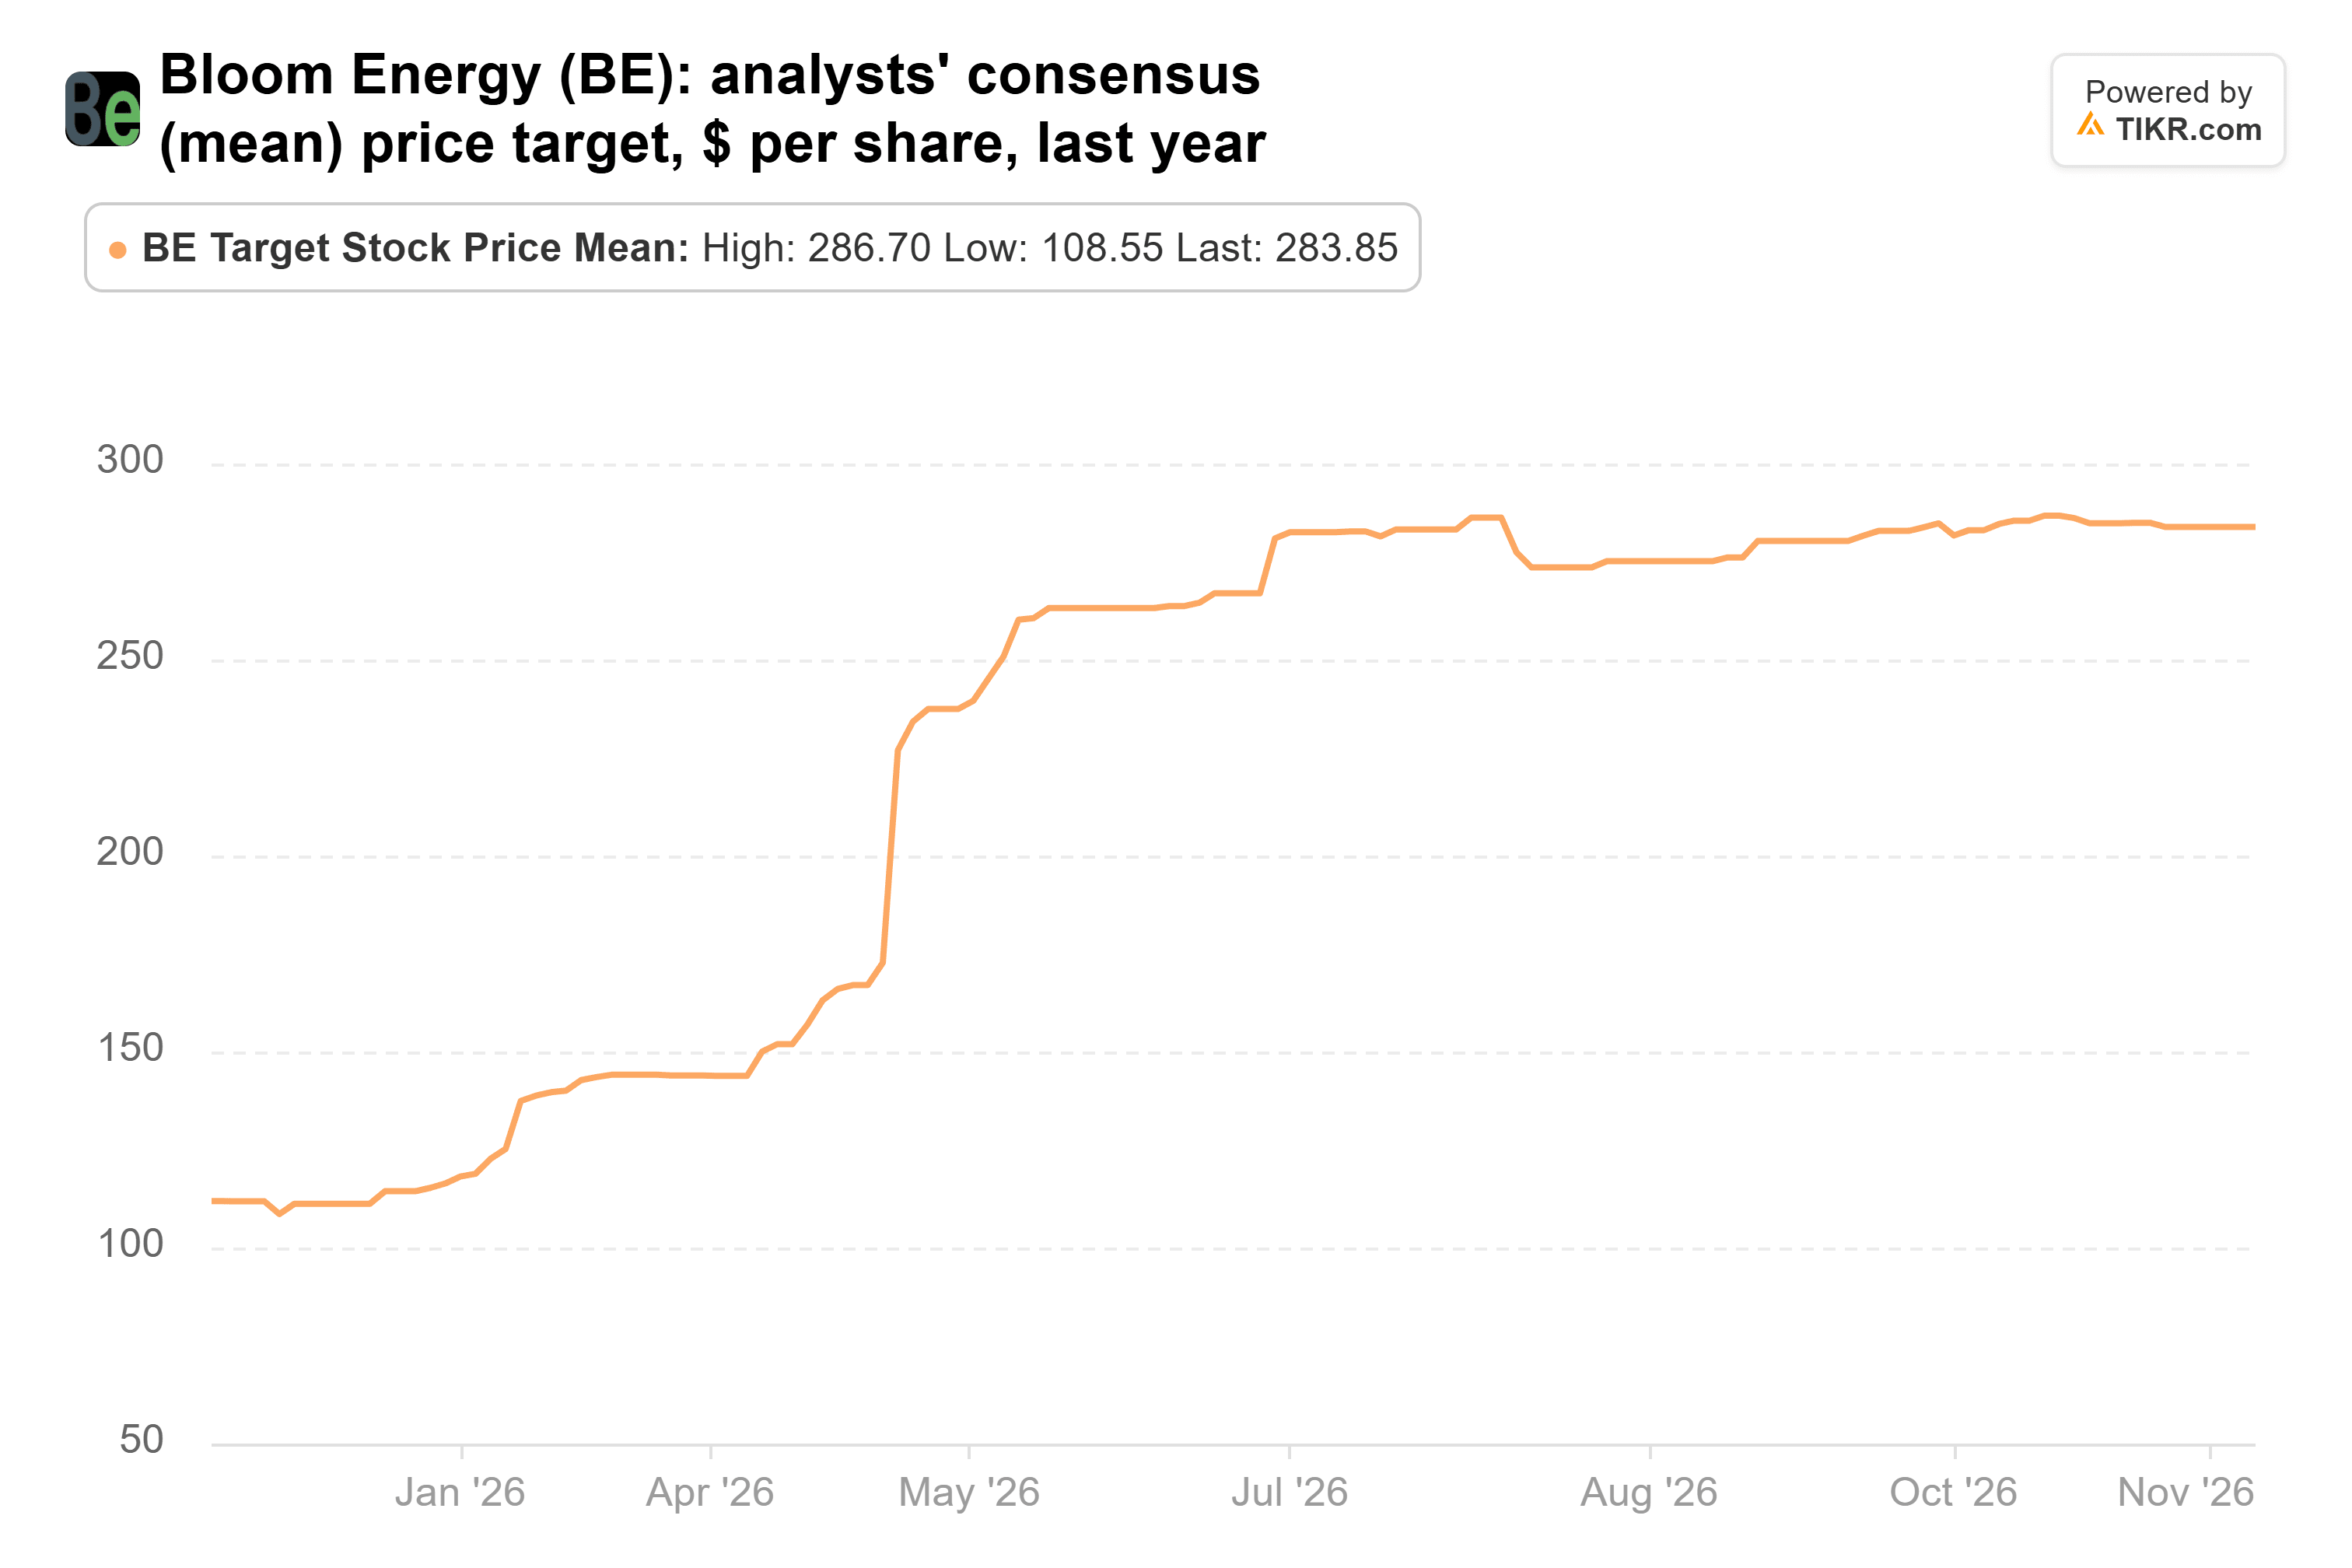
By our math, $230 is about 28x the $8.24 a share analysts expect Bloom to earn in 2028. That’s below 29x, the lowest forward P/E Bloom has had at any quarter-end since September 2023. So BMO’s call needs no higher multiple, only for the estimates to hold.
The main risk is concentration. Two customers made up 69% of Bloom’s third-quarter revenue, so one delayed project would show up quickly.
The way I see it, BMO is right to come around, and its target is conservative. Bloom’s fourth-quarter report is due early next year. Its 2027 guidance should come with it, and guidance near the $7.09 billion consensus would support the upgrade.
So what is Bloom Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!