Key Takeaways
- Bloom Energy shares are 44% below their June high after a third quarter of negative free cash flow and a selloff in data-center stocks after the midterms.
- RBC Capital kept its Outperform rating and $335 target on Monday, 68% above today’s price. It argues that local pushback against data centers favors Bloom’s on-site power.
- Analysts have raised their 2026 and 2027 earnings estimates over the past month. RBC’s target works out to 69x forward earnings, below the stock’s average since late 2023.
- RBC’s call holds up. Positive free cash flow in Bloom’s fourth-quarter report in early 2027 would back it.
Bloom Energy (BE) is 44% below its June high, even after today’s bounce.
RBC Capital isn’t backing off. On Monday, analyst Chris Dendrinos reiterated his Outperform rating and $335 price target, 68% above today’s price.
A record quarter, then the midterms
In Bloom’s third quarter, reported Oct. 22, revenue rose 138% to a record $1.24 billion. Management raised its 2026 revenue guidance for the third time this year, to $4.4 billion-$4.6 billion. But free cash flow was negative $181 million, as revenue Bloom had booked but not yet billed jumped $430 million. CFO Simon Edwards said on the call that the operating cash use is “not the beginning of a trend,” and shares dropped the next day anyway.
Then came the midterms. On Nov. 5, Bloom sank with tech stocks on fears that the data-center buildout could stall. Texas’s incoming governor, Gina Hinojosa, has also promised a moratorium on new data-center approvals. The stock fell the same day NTT DATA announced a 900-megawatt deal with Bloom.
TIKR tracks 29 analysts on Bloom Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
RBC thinks the backlash plays to Bloom’s strengths
Dendrinos’s case is that the election slows data centers down without stopping them. “We do not think datacenters are dead,” he wrote. He expects more community input and more careful site selection, which slows construction and adds near-term uncertainty for Bloom.
But he argues that Bloom’s fast delivery, cleaner exhaust, low noise and zero water use count for more when developers need local support. He also thinks slower grid hookups in Texas could push developers toward making their own power on site. RBC left its estimates unchanged, and $335 is the target it has held since late April.
Does $335 add up?
The 30 analysts covering Bloom have an average target of $284, up from $112 a year ago, even as the stock fell by half from its June high to Friday’s close:
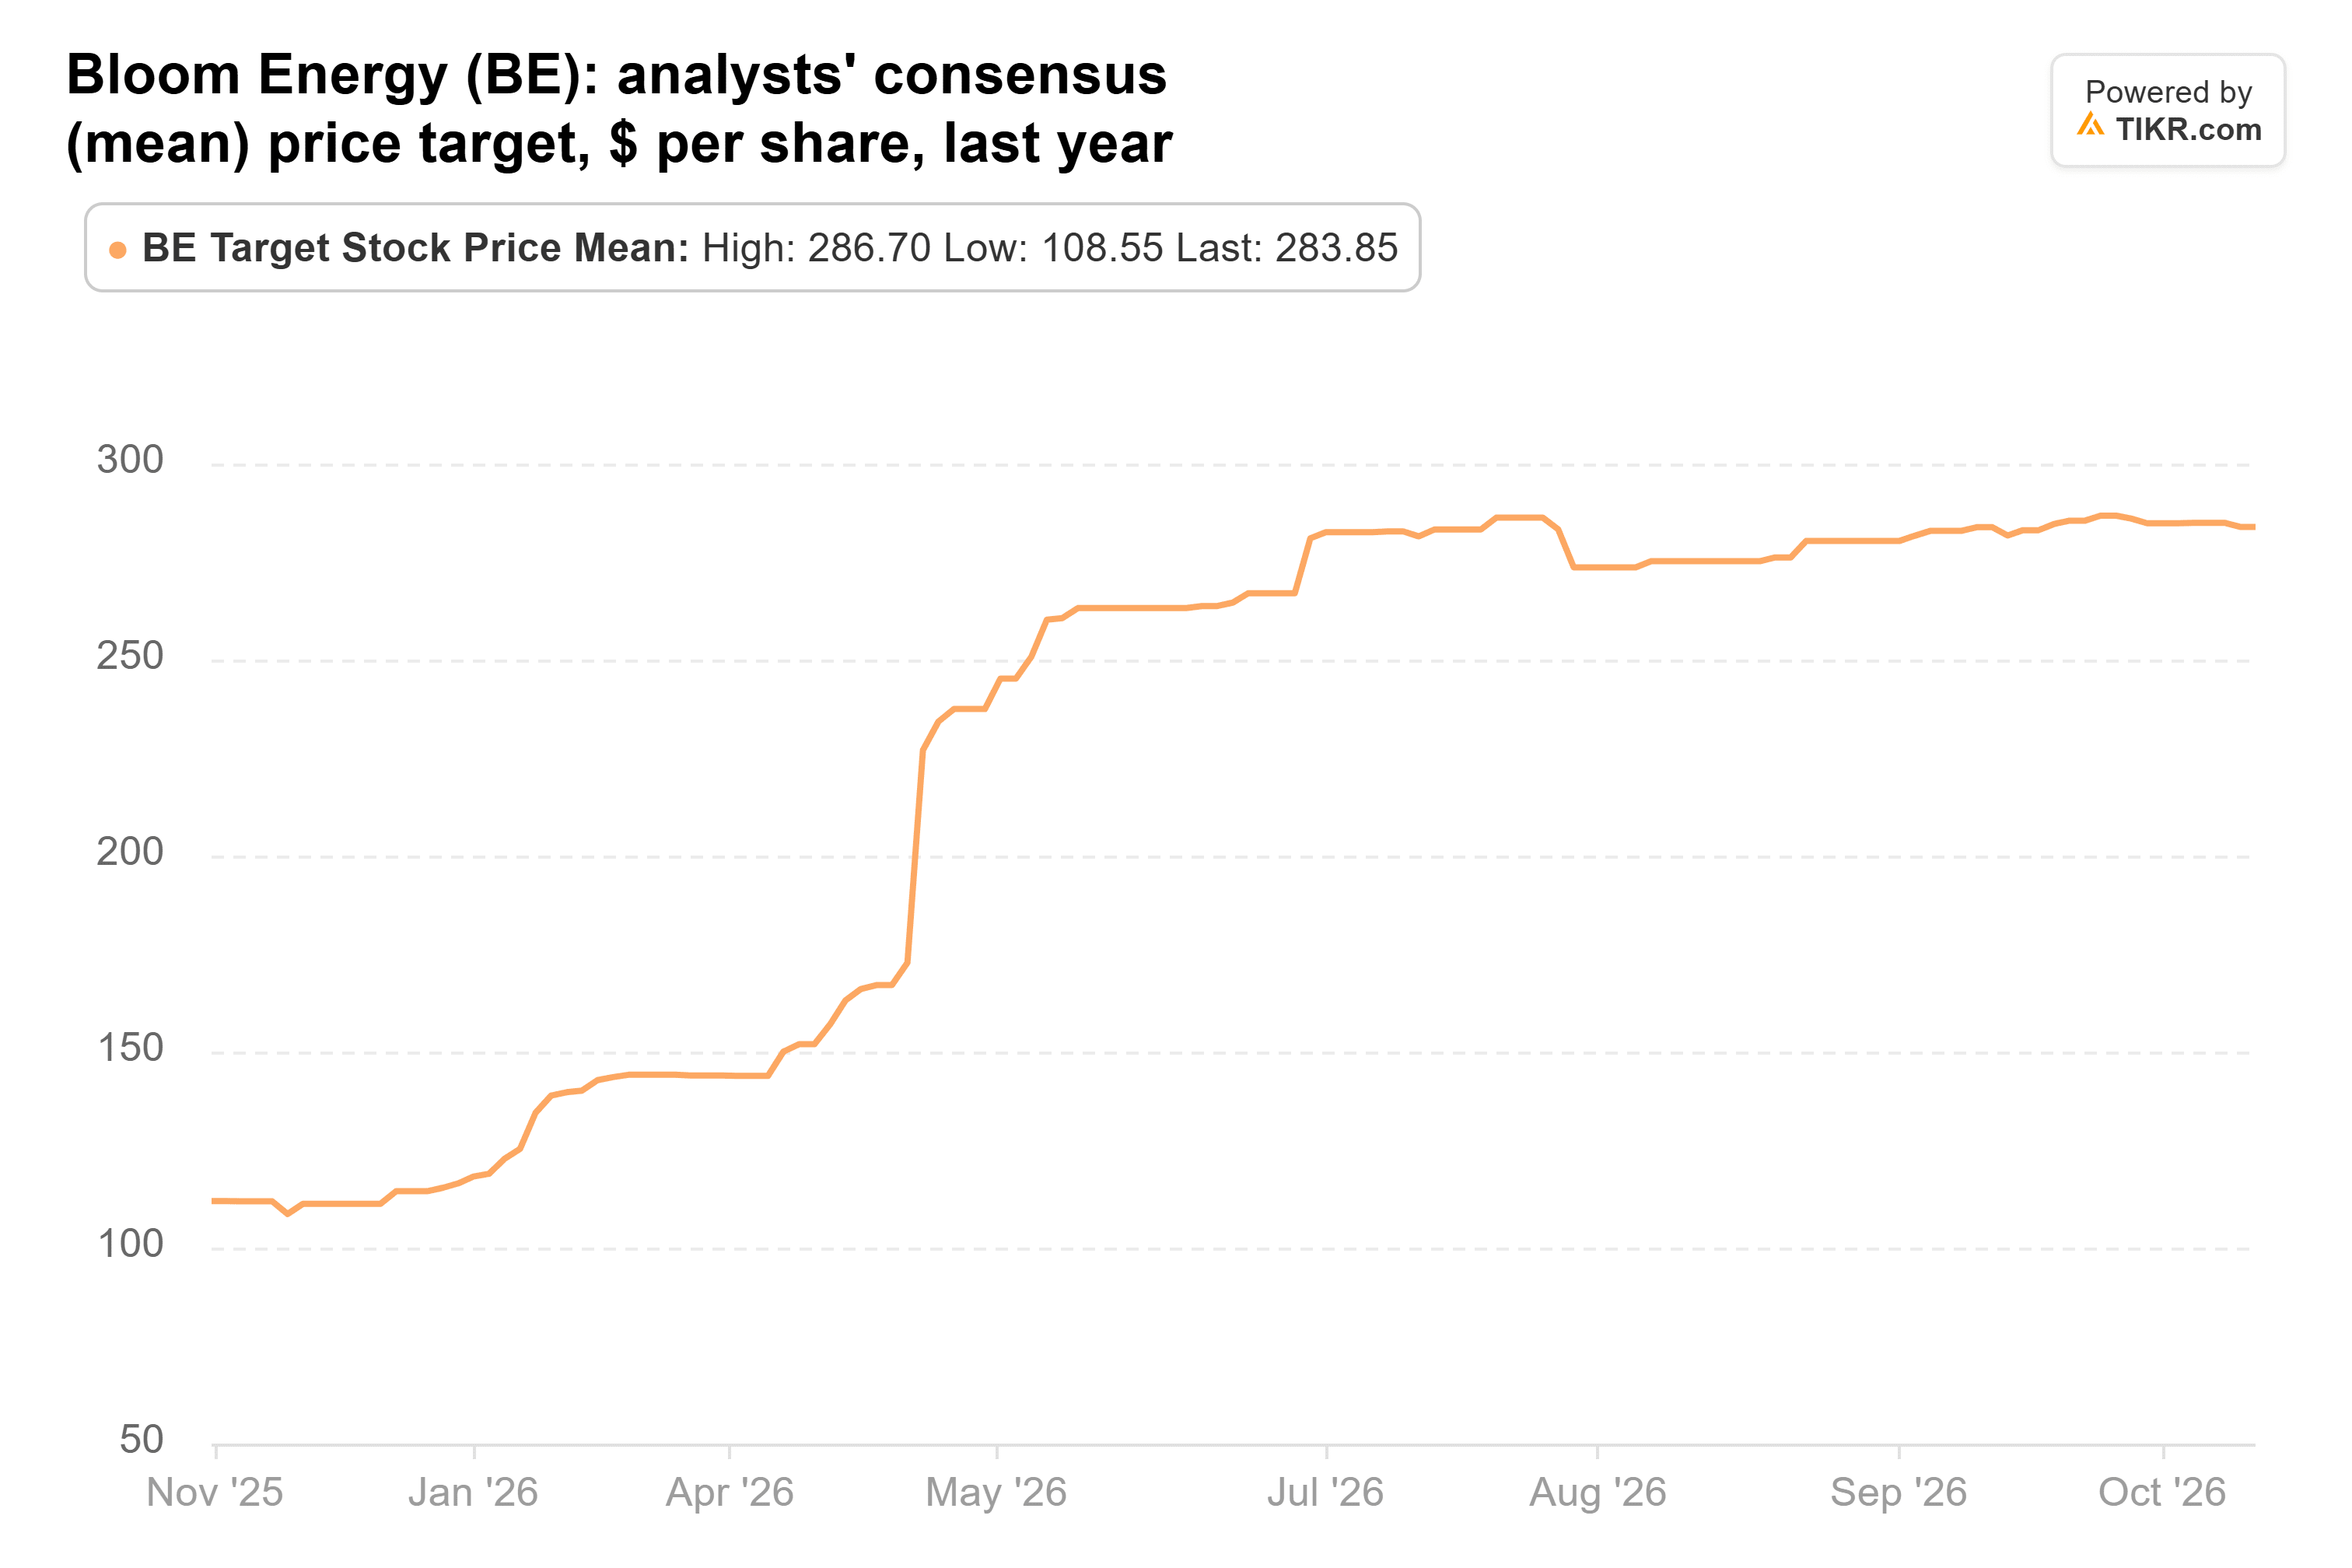
RBC’s $335 is 18% above that average. Analysts expect normalized EPS to climb from $0.76 in 2025 to $3.27 in 2026 and $8.24 by 2028:
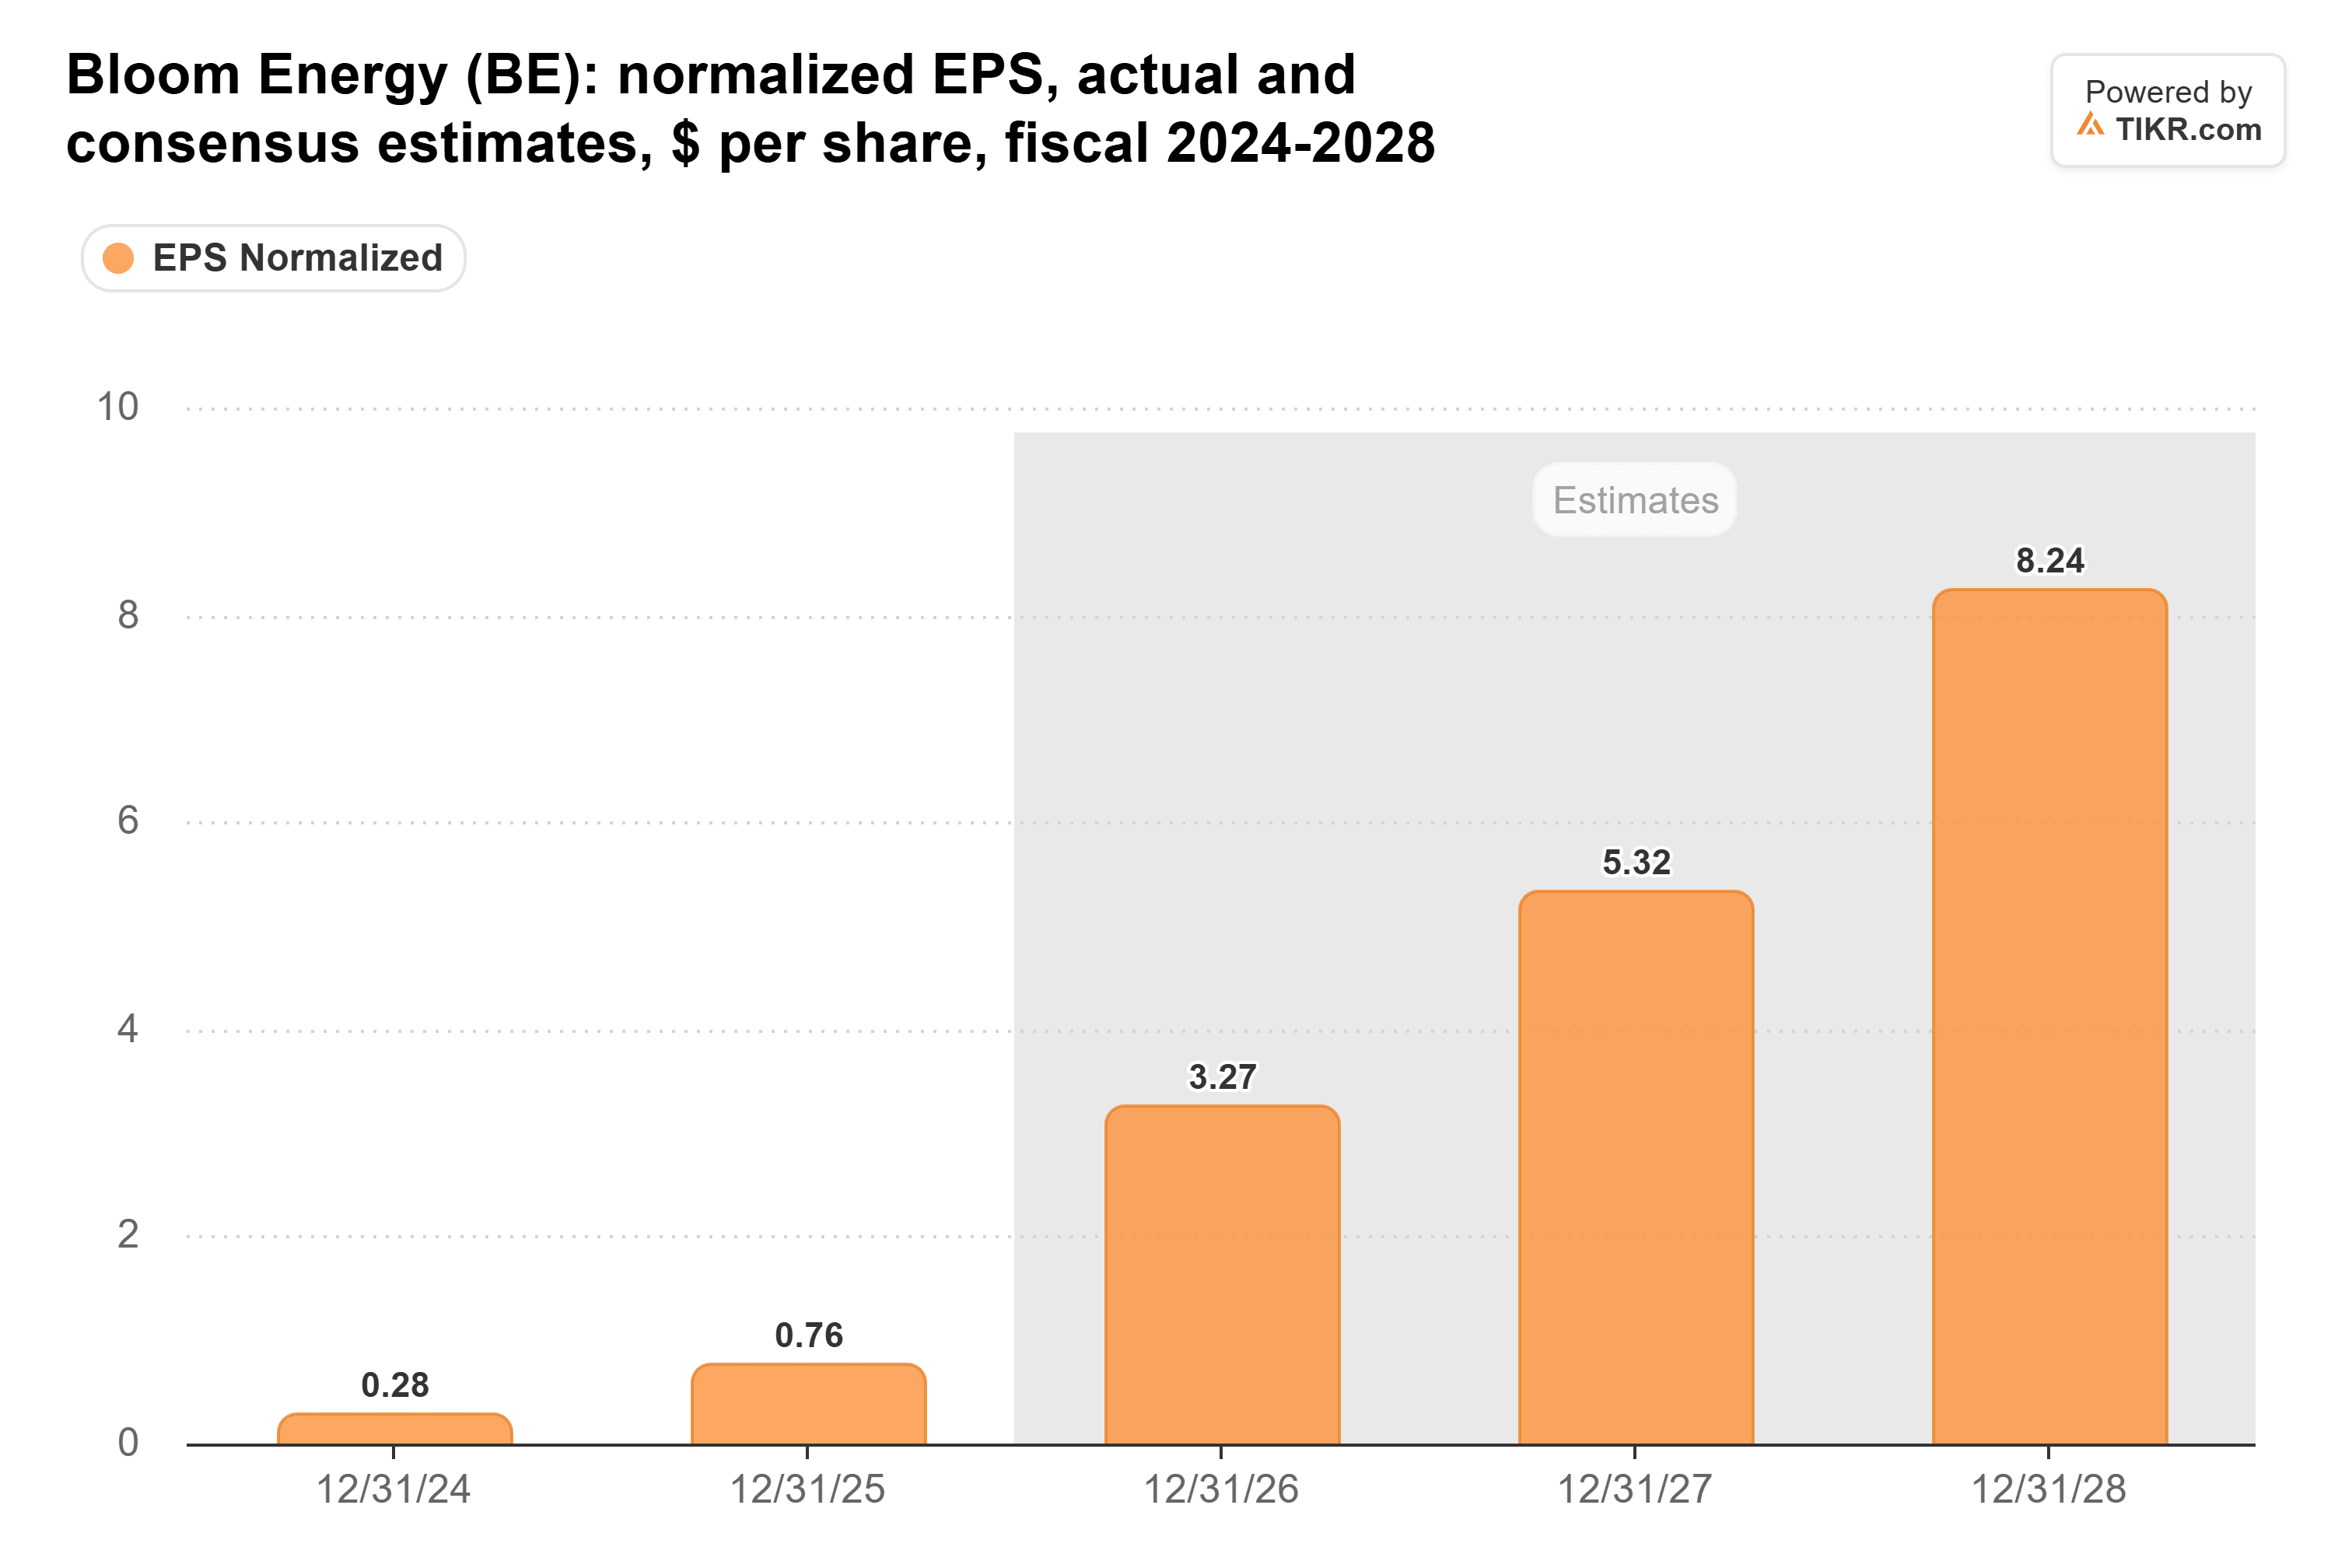
Those estimates are still rising. Thirty days ago, the 2026 estimate was $2.70, and 2027’s was $4.88, against $5.32 now.
At Friday’s close, Bloom traded at 35x forward earnings, near the bottom of its quarter-end range since late 2023 (29x to 145x, averaging 76x). RBC’s target works out to 69x, still below that average.
Cash is the catch
The risk is that Bloom keeps delivering faster than it collects. Revenue it had booked but not yet billed reached $858.6 million at Sept. 30, up from $241.2 million at the end of 2025. And 97% of third-quarter revenue came from the U.S., where UBS estimates construction pauses could put about 30% of the data-center capacity expected in 2028 at risk.
Still, I think RBC has this one right. Its target asks investors to pay less for Bloom’s earnings than they have on average since late 2023, and those earnings estimates keep going up. I’ll be watching for positive free cash flow in Bloom’s fourth-quarter report, due in early 2027.
So what is Bloom Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!