Key Takeaways
- Block shares are up 16% in a week to a new 52-week high on a third-quarter beat.
- Its first 2027 outlook calls for a 32% adjusted operating margin, which should lift analysts’ estimates.
- Block still trades a little below its usual multiple, and Cash App’s loan losses are the main risk.
Block (XYZ) stock is up 16% in the past week, to a new 52-week high, on its third-quarter report.
A beat, and a 32% margin for 2027
Block beat its own third-quarter guidance on every line:
- Gross profit grew 22%, to $3.24 billion.
- Adjusted operating income nearly doubled, up 92% to $923 million.
- Adjusted EPS of $1.13 topped the $1.03 analysts expected.
Its first look at 2027 calls for $14.52 billion of gross profit, up at least 15%, and $4.58 billion of adjusted operating income. That’s a 32% margin, four points above the 28% it guides to for 2026.
Analysts expected steep earnings growth going into the report:

Block’s raised 2026 guide of $4.15 tops the $4.05 Wall Street had. And if adjusted operating income grows 30% next year, as Block expects, 2027’s $5.21 looks low.
Lending is still the catch
Growth in consumer lending originations slowed to 40% in the third quarter, from 59% in the second. Block’s losses on loans, receivables and transactions rose 66% to $602 million, slower than the second quarter’s 99% but still 19% of gross profit, against 14% a year before.
Block also set aside $764 million for a preliminary Justice Department settlement, and says it could cost more.
TIKR tracks 47 analysts on Block. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Block, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Block’s Analyst Ratings
Room to run, if lending holds
Block traded at 17x forward earnings before the report:

At Wednesday’s close, it was about 19x, still just under its roughly 20x three-year average. Rising estimates would pull that back down, just as they left Block cheaper in October than at the end of 2025.
Analysts’ consensus price target has climbed from $89 to $98 over the past year:
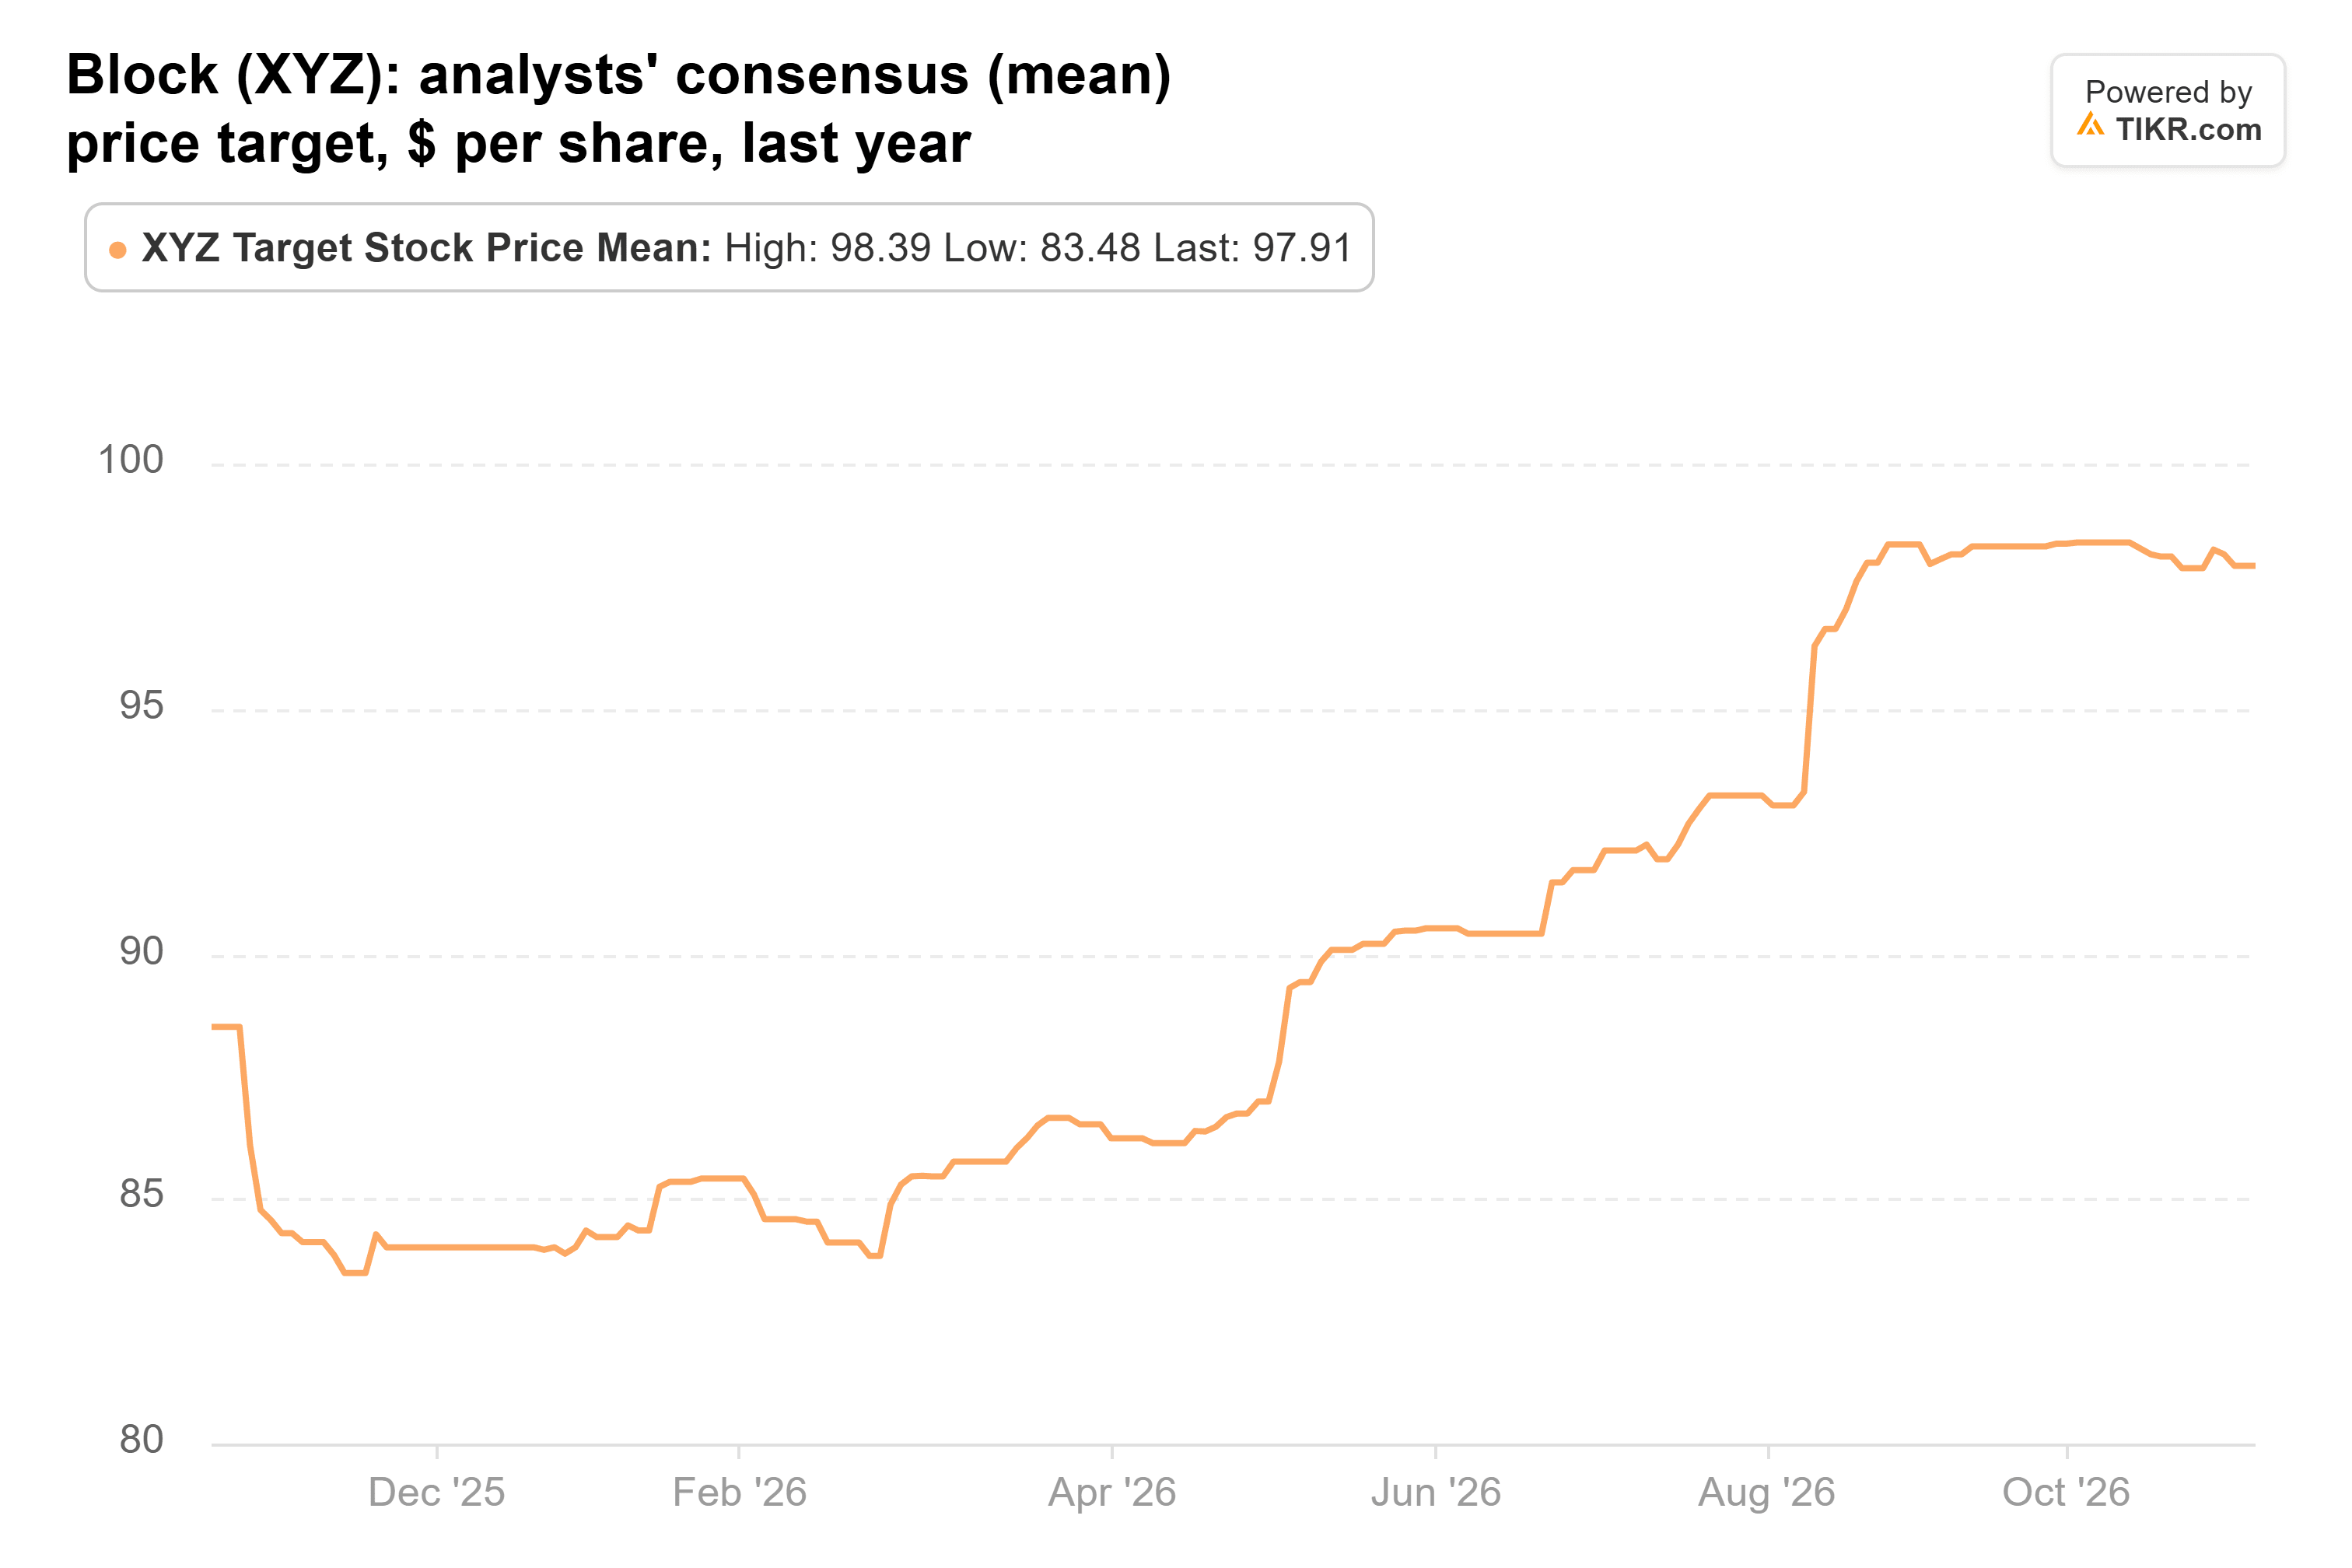
That’s 12% above Wednesday’s close.
Next up is the Nov. 10 launch of Builderlab, which sells Block’s in-house AI tools to outside companies. CEO Jack Dorsey wrote to shareholders that “we expect to generate our first machine intelligence revenue in the fourth quarter.”
The way I see it, Block still has room to run: estimates should rise, and the multiple is below its recent norm. Of course, I’d want loss growth to keep slowing in its fourth-quarter report early next year.
So what is Block stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Block could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!