

Key Takeaways
- Bill Ackman’s Pershing Square opened a new position in Intercontinental Exchange in the third quarter, worth $1.01 billion at Sept. 30, according to its 13F filed Nov. 16.
- The stock is up 17% since the quarter ended, and Intercontinental Exchange has since reported third-quarter adjusted EPS up 18% on 15% revenue growth.
- At 21x forward earnings, the stock trades just under its five-year average of 22x, and analysts expect EPS to rise every year through 2028.
- The numbers back the buy. With the multiple near its usual level, the return from here depends on those earnings estimates holding.
Bill Ackman’s Pershing Square has a new stock in its portfolio. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows 6.64 million shares of Intercontinental Exchange (ICE), worth $1.01 billion at quarter’s end.
Since then, ICE stock has climbed 17%, and it now sits 2% below its 52-week high. So for anyone reading the filing today, the question is whether there’s still room to follow him.
A smaller bet in a concentrated fund
Pershing Square, a $30.8 billion firm, held just 16 stocks at Sept. 30, and ICE was its No. 13 position, with 3.3% of its 13F stocks. A 13F only shows what a fund held on the last day of the quarter, so it can’t tell us when Pershing bought or what it paid. (So the 17% is the stock’s move from its Sept. 30 price. It isn’t the fund’s return.) We do know that ICE hit a 52-week low of $122.91 on June 29, and the stock stayed above that level for the whole third quarter.
TIKR tracks 16 analysts on Intercontinental Exchange. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Intercontinental Exchange, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Intercontinental Exchange’s Analyst Ratings
ICE’s exchanges are on a tear
ICE has given Ackman plenty to like since the quarter closed. On Oct. 29, it reported third-quarter net revenue of $2.8 billion, up 15% from a year earlier, and adjusted EPS of $2.02, up 18%. The company called it the best third quarter in its history.
The exchanges did the heavy lifting. Their net revenue rose 22% to $1.5 billion at a 75% operating margin. Energy revenue rose 25%, and NYSE cash equities and equity options revenue rose 25% to $132 million.
The cash is pouring in, too. Adjusted free cash flow reached $3.7 billion through the first nine months of the year, and ICE spent $1.6 billion on buybacks and $884 million on dividends. The weak spot is mortgage technology: its $549 million of third-quarter revenue came with a GAAP operating margin of just 2%.
The numbers back him up
Analysts expect ICE’s normalized EPS to rise from $6.95 in 2025 to $8.19 this year, $8.94 in 2027 and $10.00 in 2028:
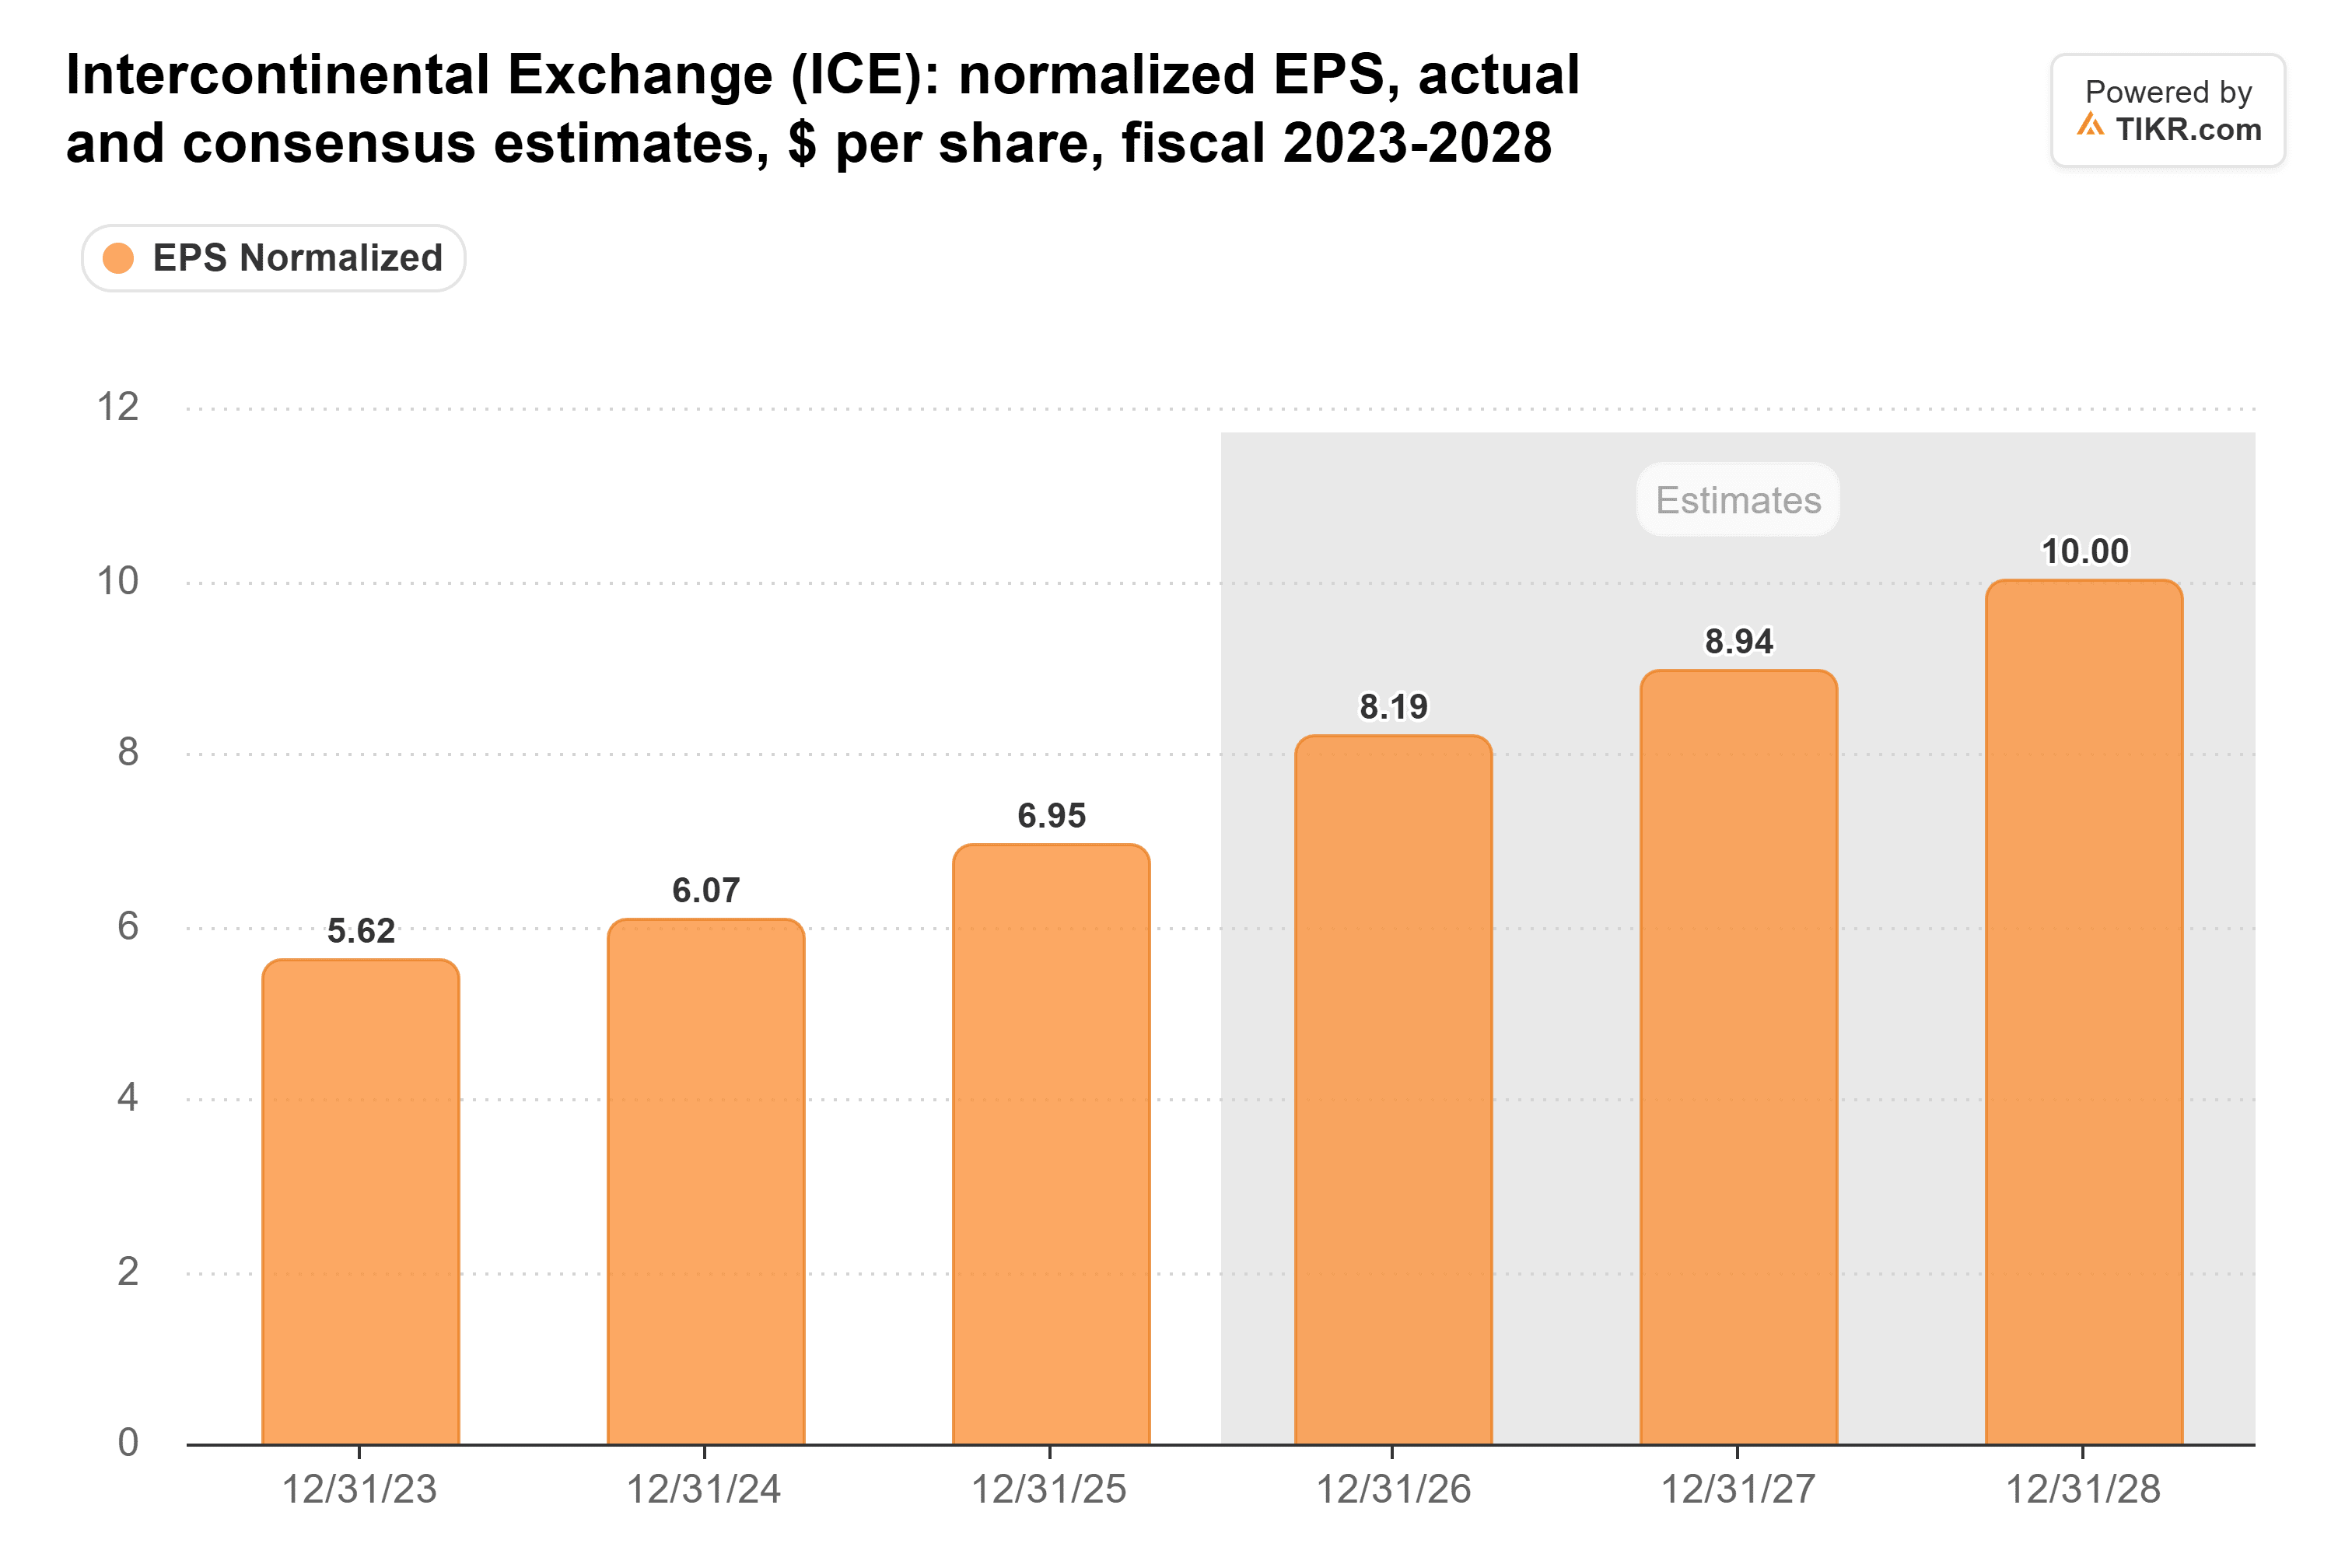
That’s growth every year, and the market isn’t paying extra for it. ICE trades at 21x forward earnings, just under its five-year average of 22x and well below its peak of 26x in March 2025:
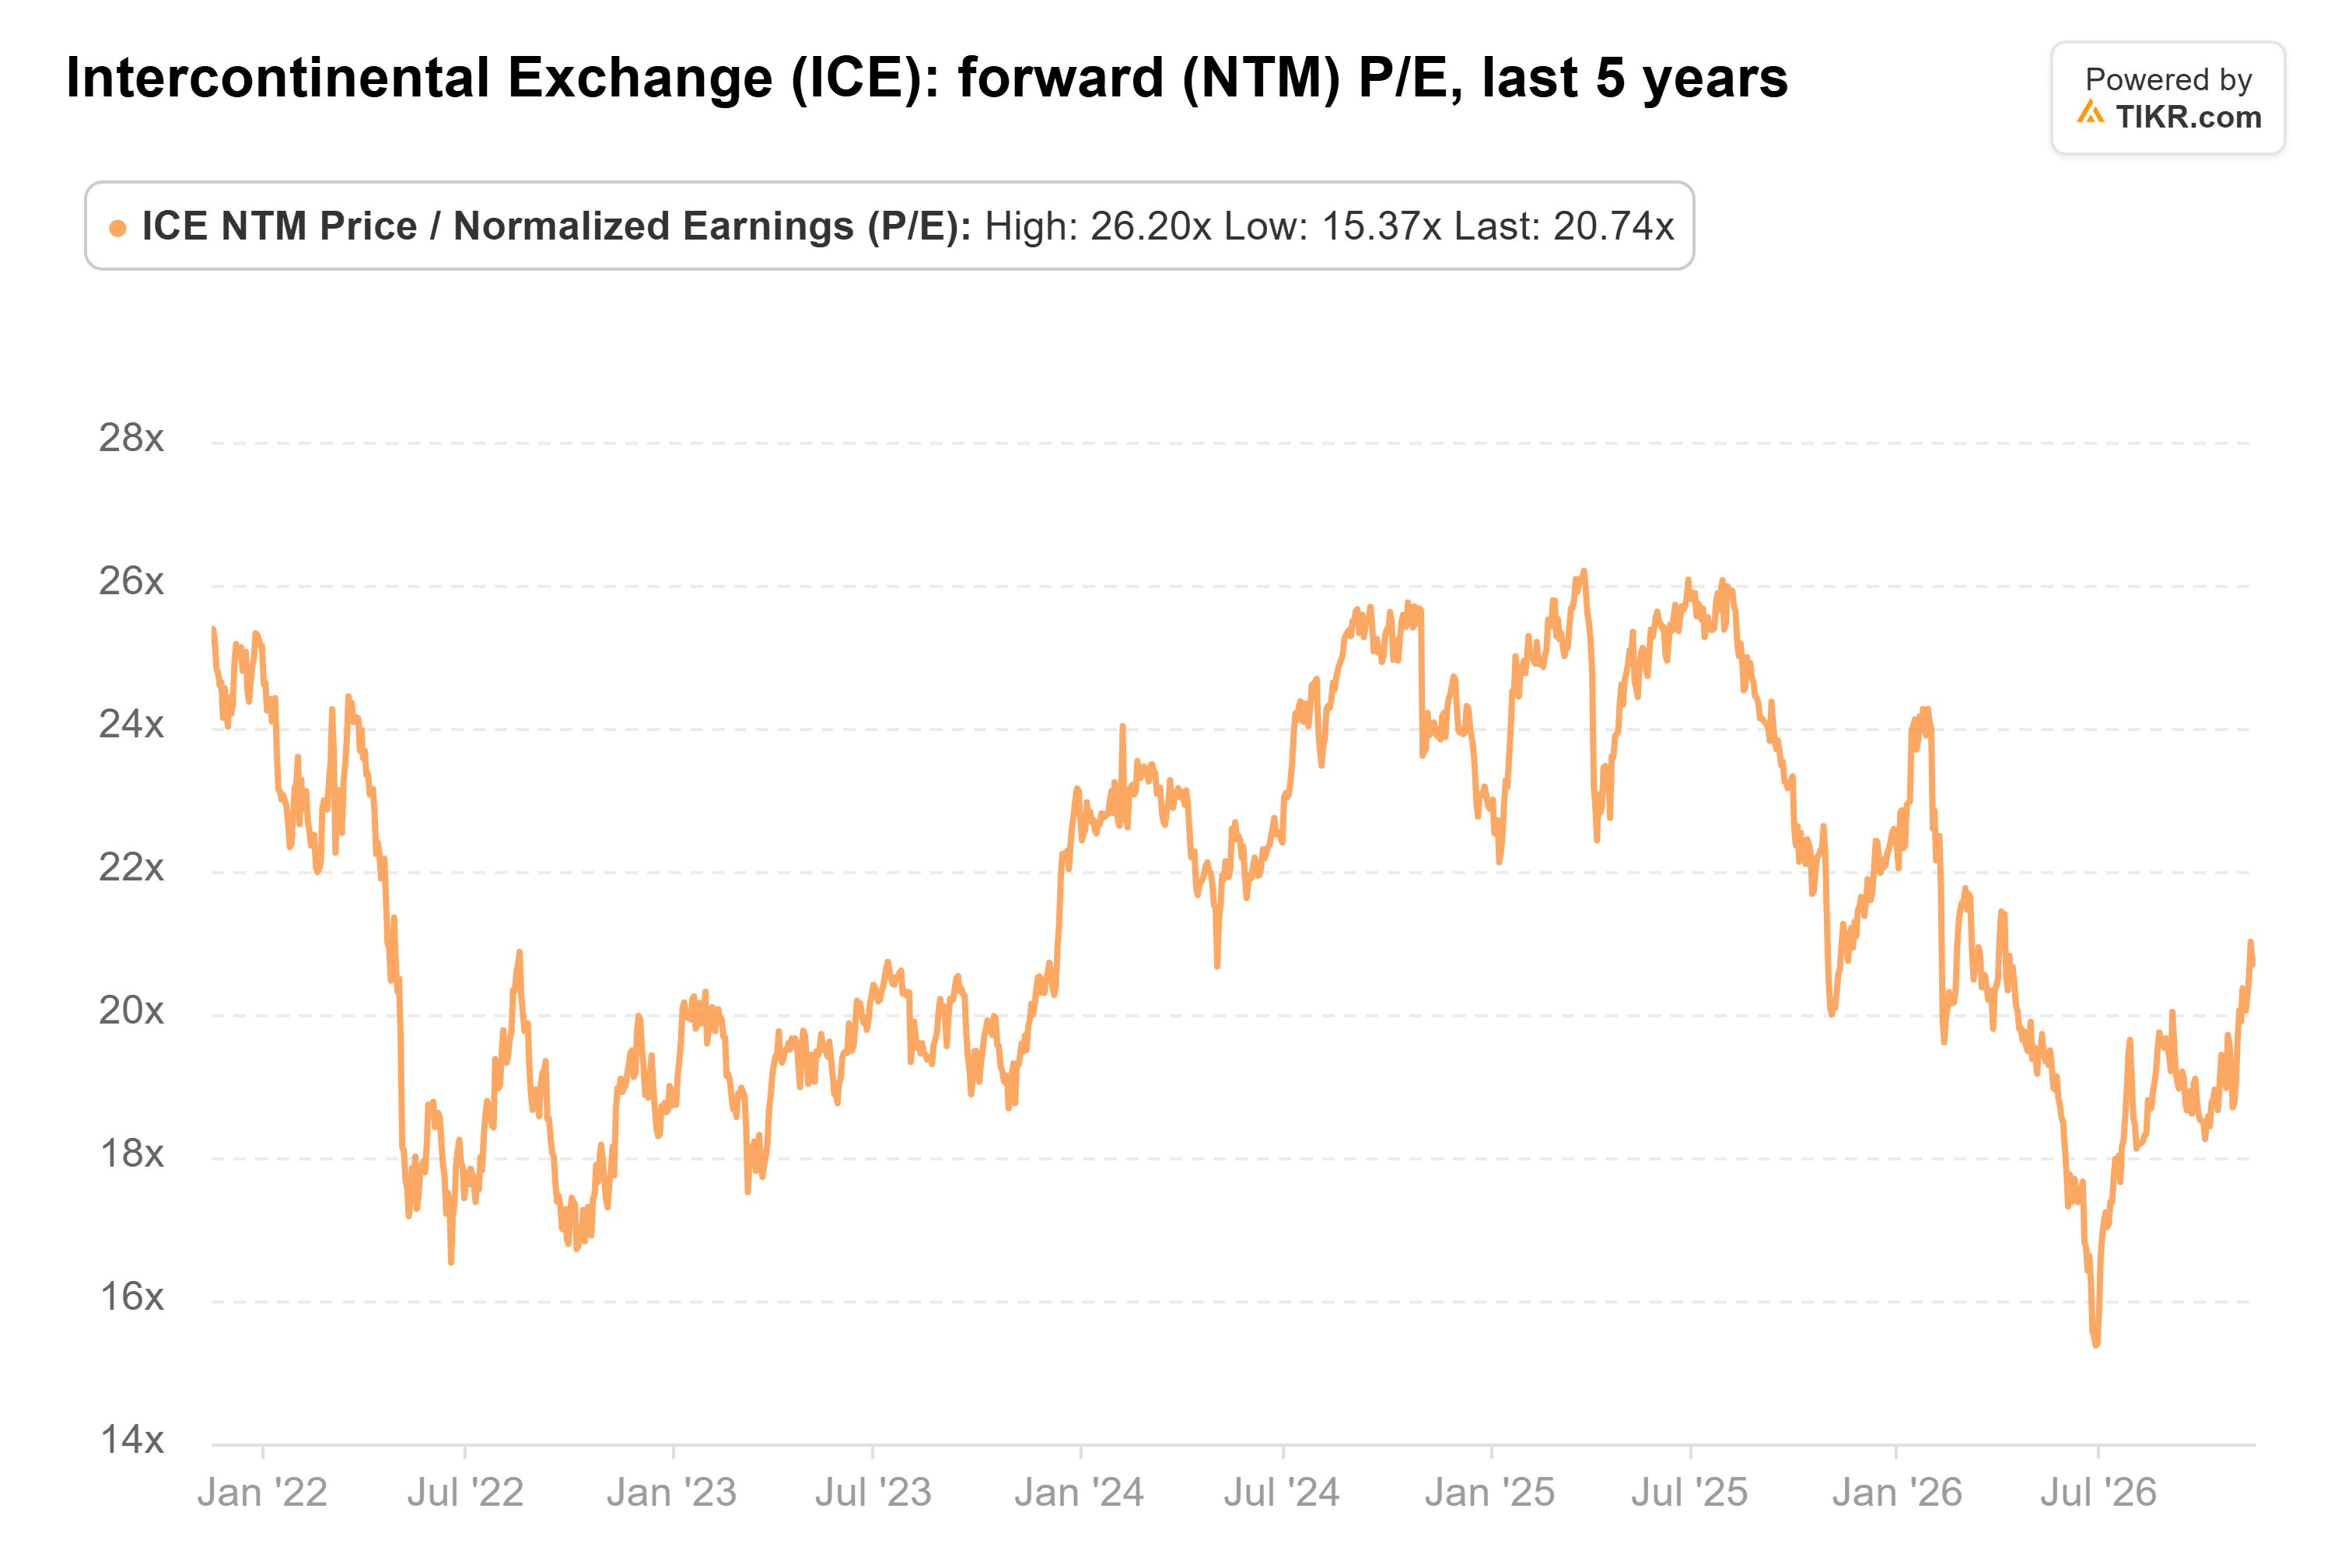
That’s still a long way above the 15x it hit at the June low.
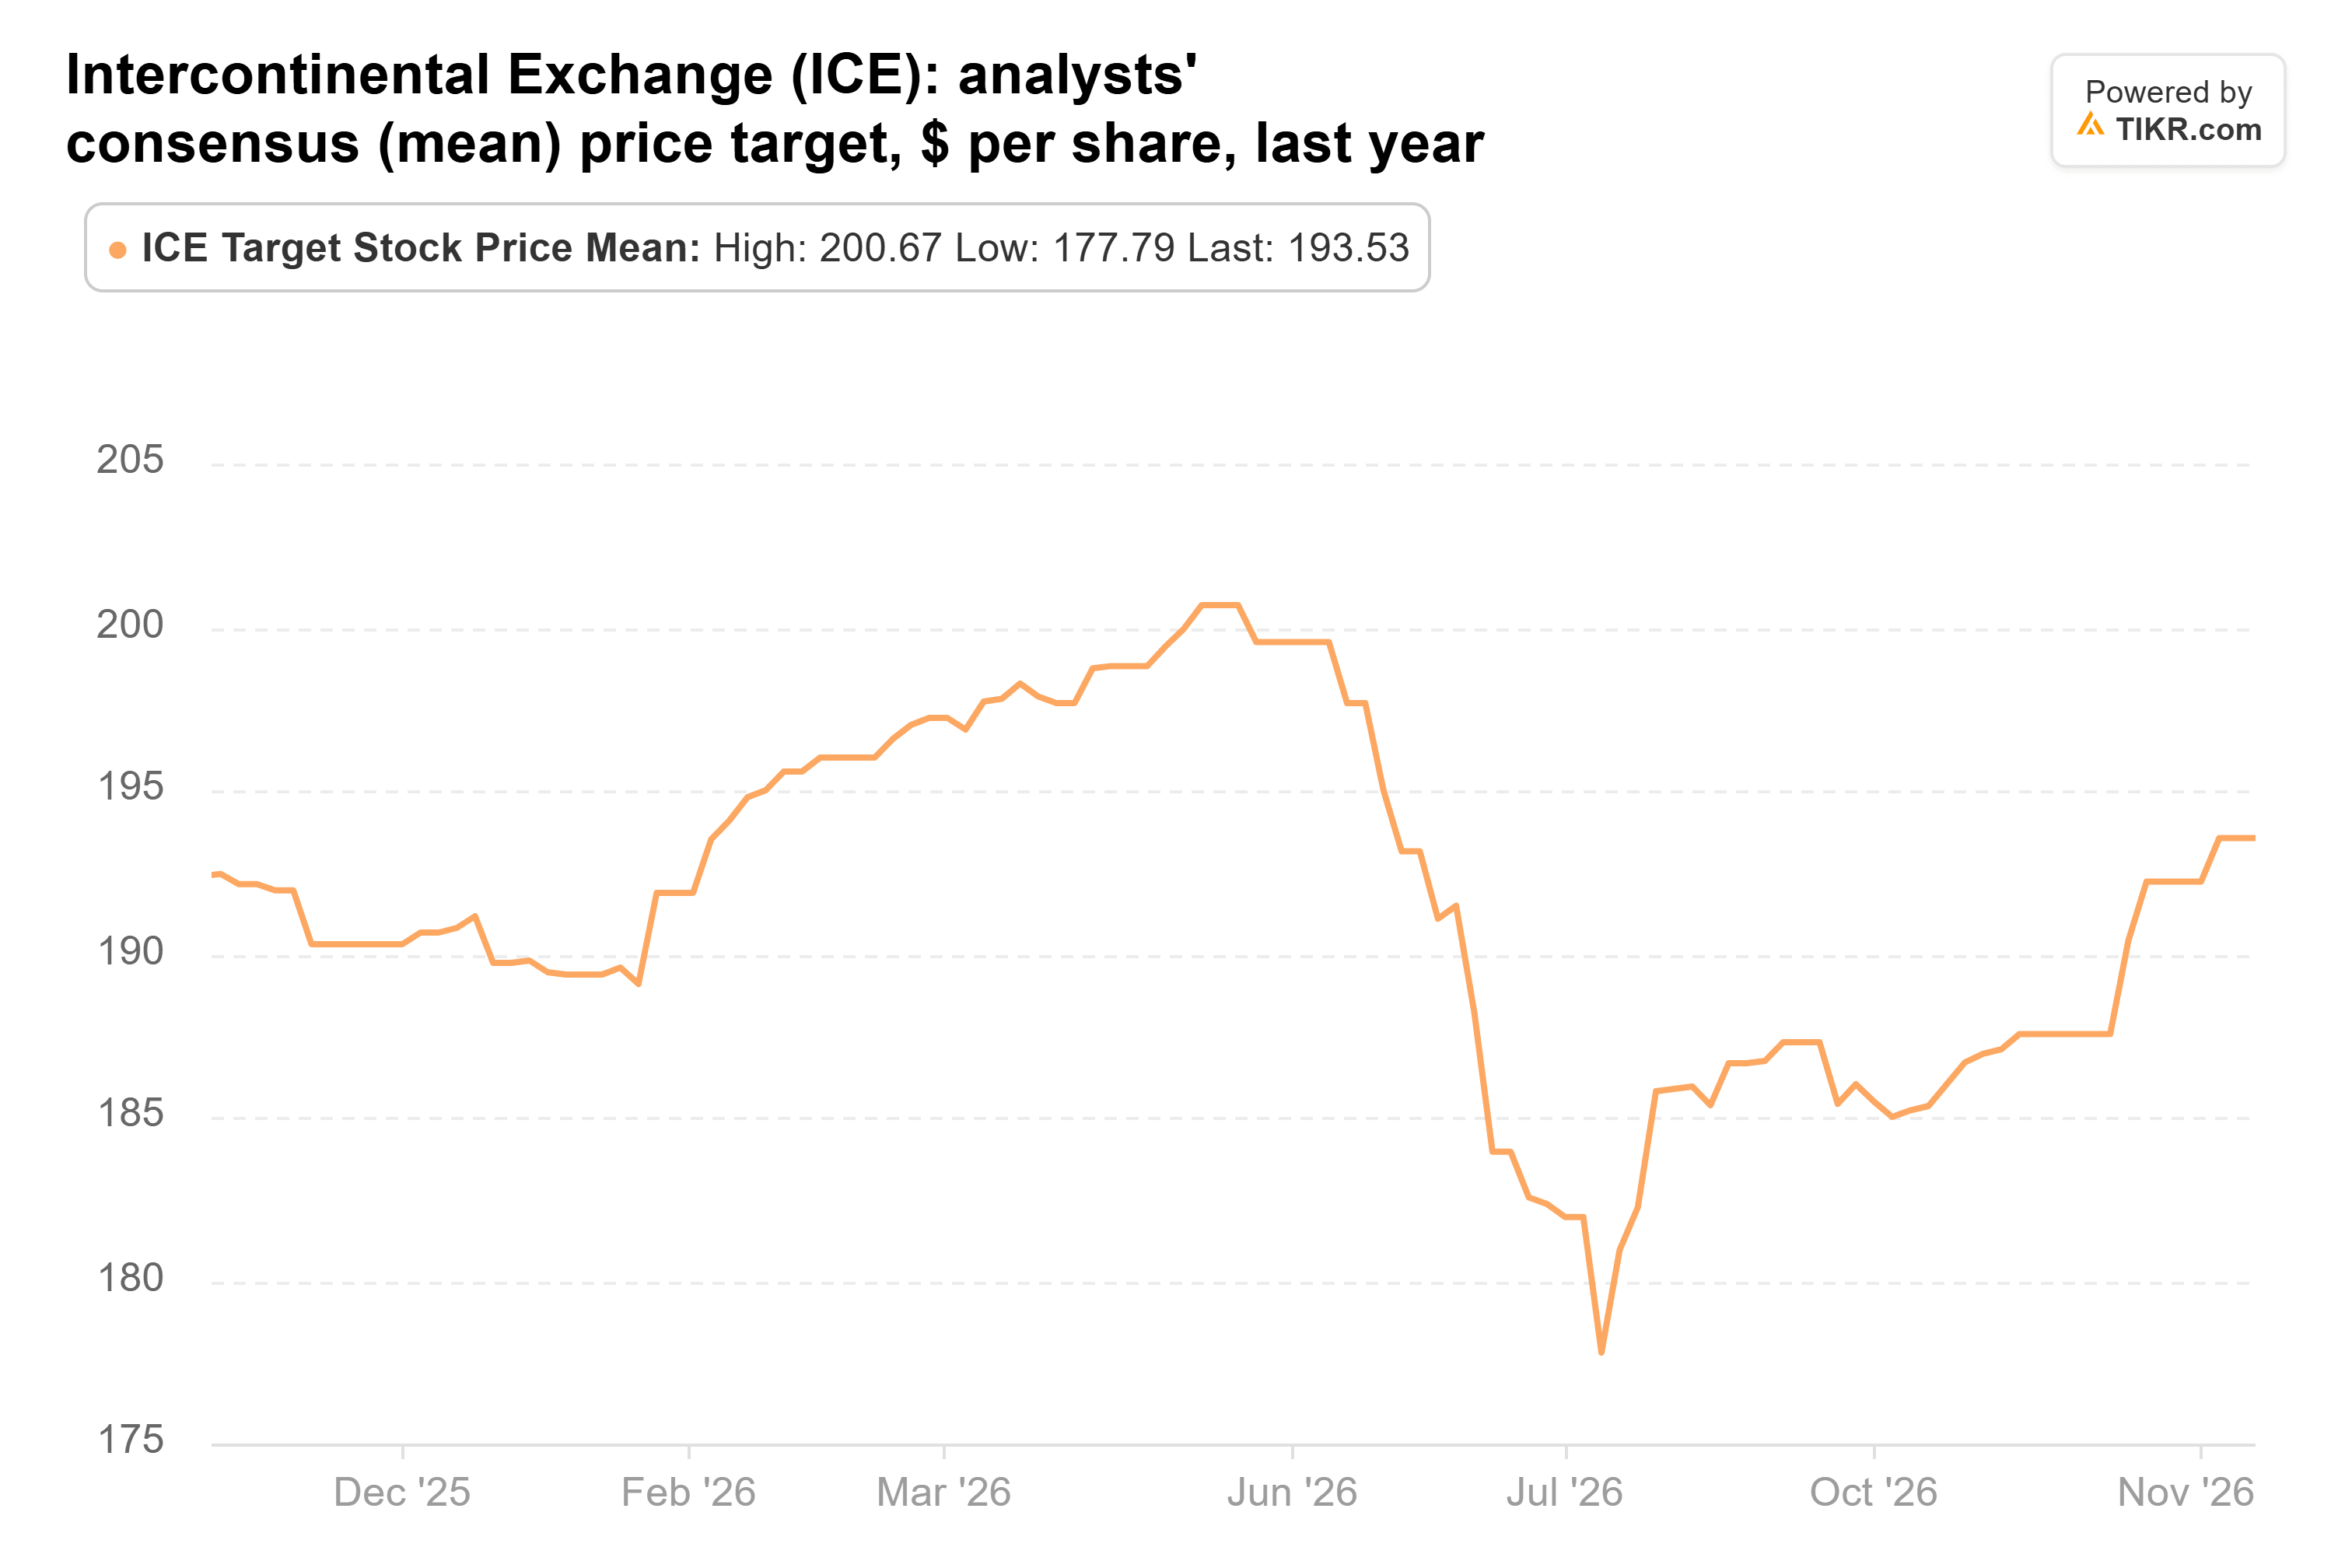
The 16 analysts covering ICE see a bit more upside. Their average price target is $194, 9% above the latest close, with targets ranging from $167 to $245. That average has barely moved in a year, from $192 last November, even as the stock climbed from $150:
A fair price for a record year
The main risk is that a record year driven by trading volumes can fade when markets calm down. The mortgage business also still isn’t carrying its weight.
Still, I think Ackman picked well. At 21x, ICE costs about what it usually does, analysts expect its earnings to rise every year through 2028, and it turns enough of those earnings into cash to keep buying back stock. Anyone following him today pays the stock’s usual multiple, though, so the return from here depends on those estimates holding.
ICE should report its fourth quarter in early February, and Pershing’s next 13F is due by mid-February. Together, they’ll show whether the exchanges kept up the pace and whether Ackman added to his stake.
So what is Intercontinental Exchange stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Intercontinental Exchange could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Intercontinental Exchange for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!







