Key Takeaways
- Altria Group yields 5.9% and Enbridge yields 6.0%, and both reported third-quarter results in the past two weeks.
- Altria paid out 78% of its free cash flow over the 12 months to Sept. 30, 2026, and Enbridge’s distributable cash flow covered its dividend 1.5x in fiscal 2025.
- Enbridge’s net debt runs at 6.3x EBITDA, against 1.7x at Altria.
- Altria’s dividend grew 4.1% a year from fiscal 2020 to fiscal 2025, against 3.1% at Enbridge, so at those rates Altria’s income passes Enbridge’s by 2028.
Income investors hunting for a 6% yield keep landing on Altria Group (MO) and Enbridge (ENB), and both just reported. On Oct. 29, Altria raised its 2026 adjusted EPS guidance to $5.66-$5.74, up from $5.56-$5.72, and its shares jumped 7% before the open.
Enbridge reported on Nov. 6. It reaffirmed its 2026 guidance, including C$5.70-C$6.10 of distributable cash flow per share. With the yields this close, which one is the better high-yield dividend stock?
| Metric | Altria Group (MO) | Enbridge (ENB) |
|---|---|---|
| Dividend yield | 5.9% | 6.0% |
| Dividend growth, fiscal 2020-2025 | 4.1% a year | 3.1% a year (in C$) |
| Record | 61 increases in 57 years | 31 straight yearly increases |
| Dividend coverage, last reported | 78% cash dividend payout ratio (TTM to Sept. 30, 2026) | 1.51x distributable cash flow coverage (fiscal 2025) |
| Net debt / EBITDA (LTM) | 1.7x | 6.3x |
| Interest coverage (LTM) | 10.9x | 2.4x |
Source: TIKR, Nov. 9, 2026. Records are each company’s own count.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Altria’s profits keep growing as cigarettes shrink
Altria’s domestic cigarette shipments keep falling, but the company is still earning more. In the third quarter of 2026, net revenue rose 1.0% to $6.1 billion and adjusted EPS rose 4.8% to $1.52, both against the same quarter a year before. Shipments of its on! nicotine pouches grew 13.3%.
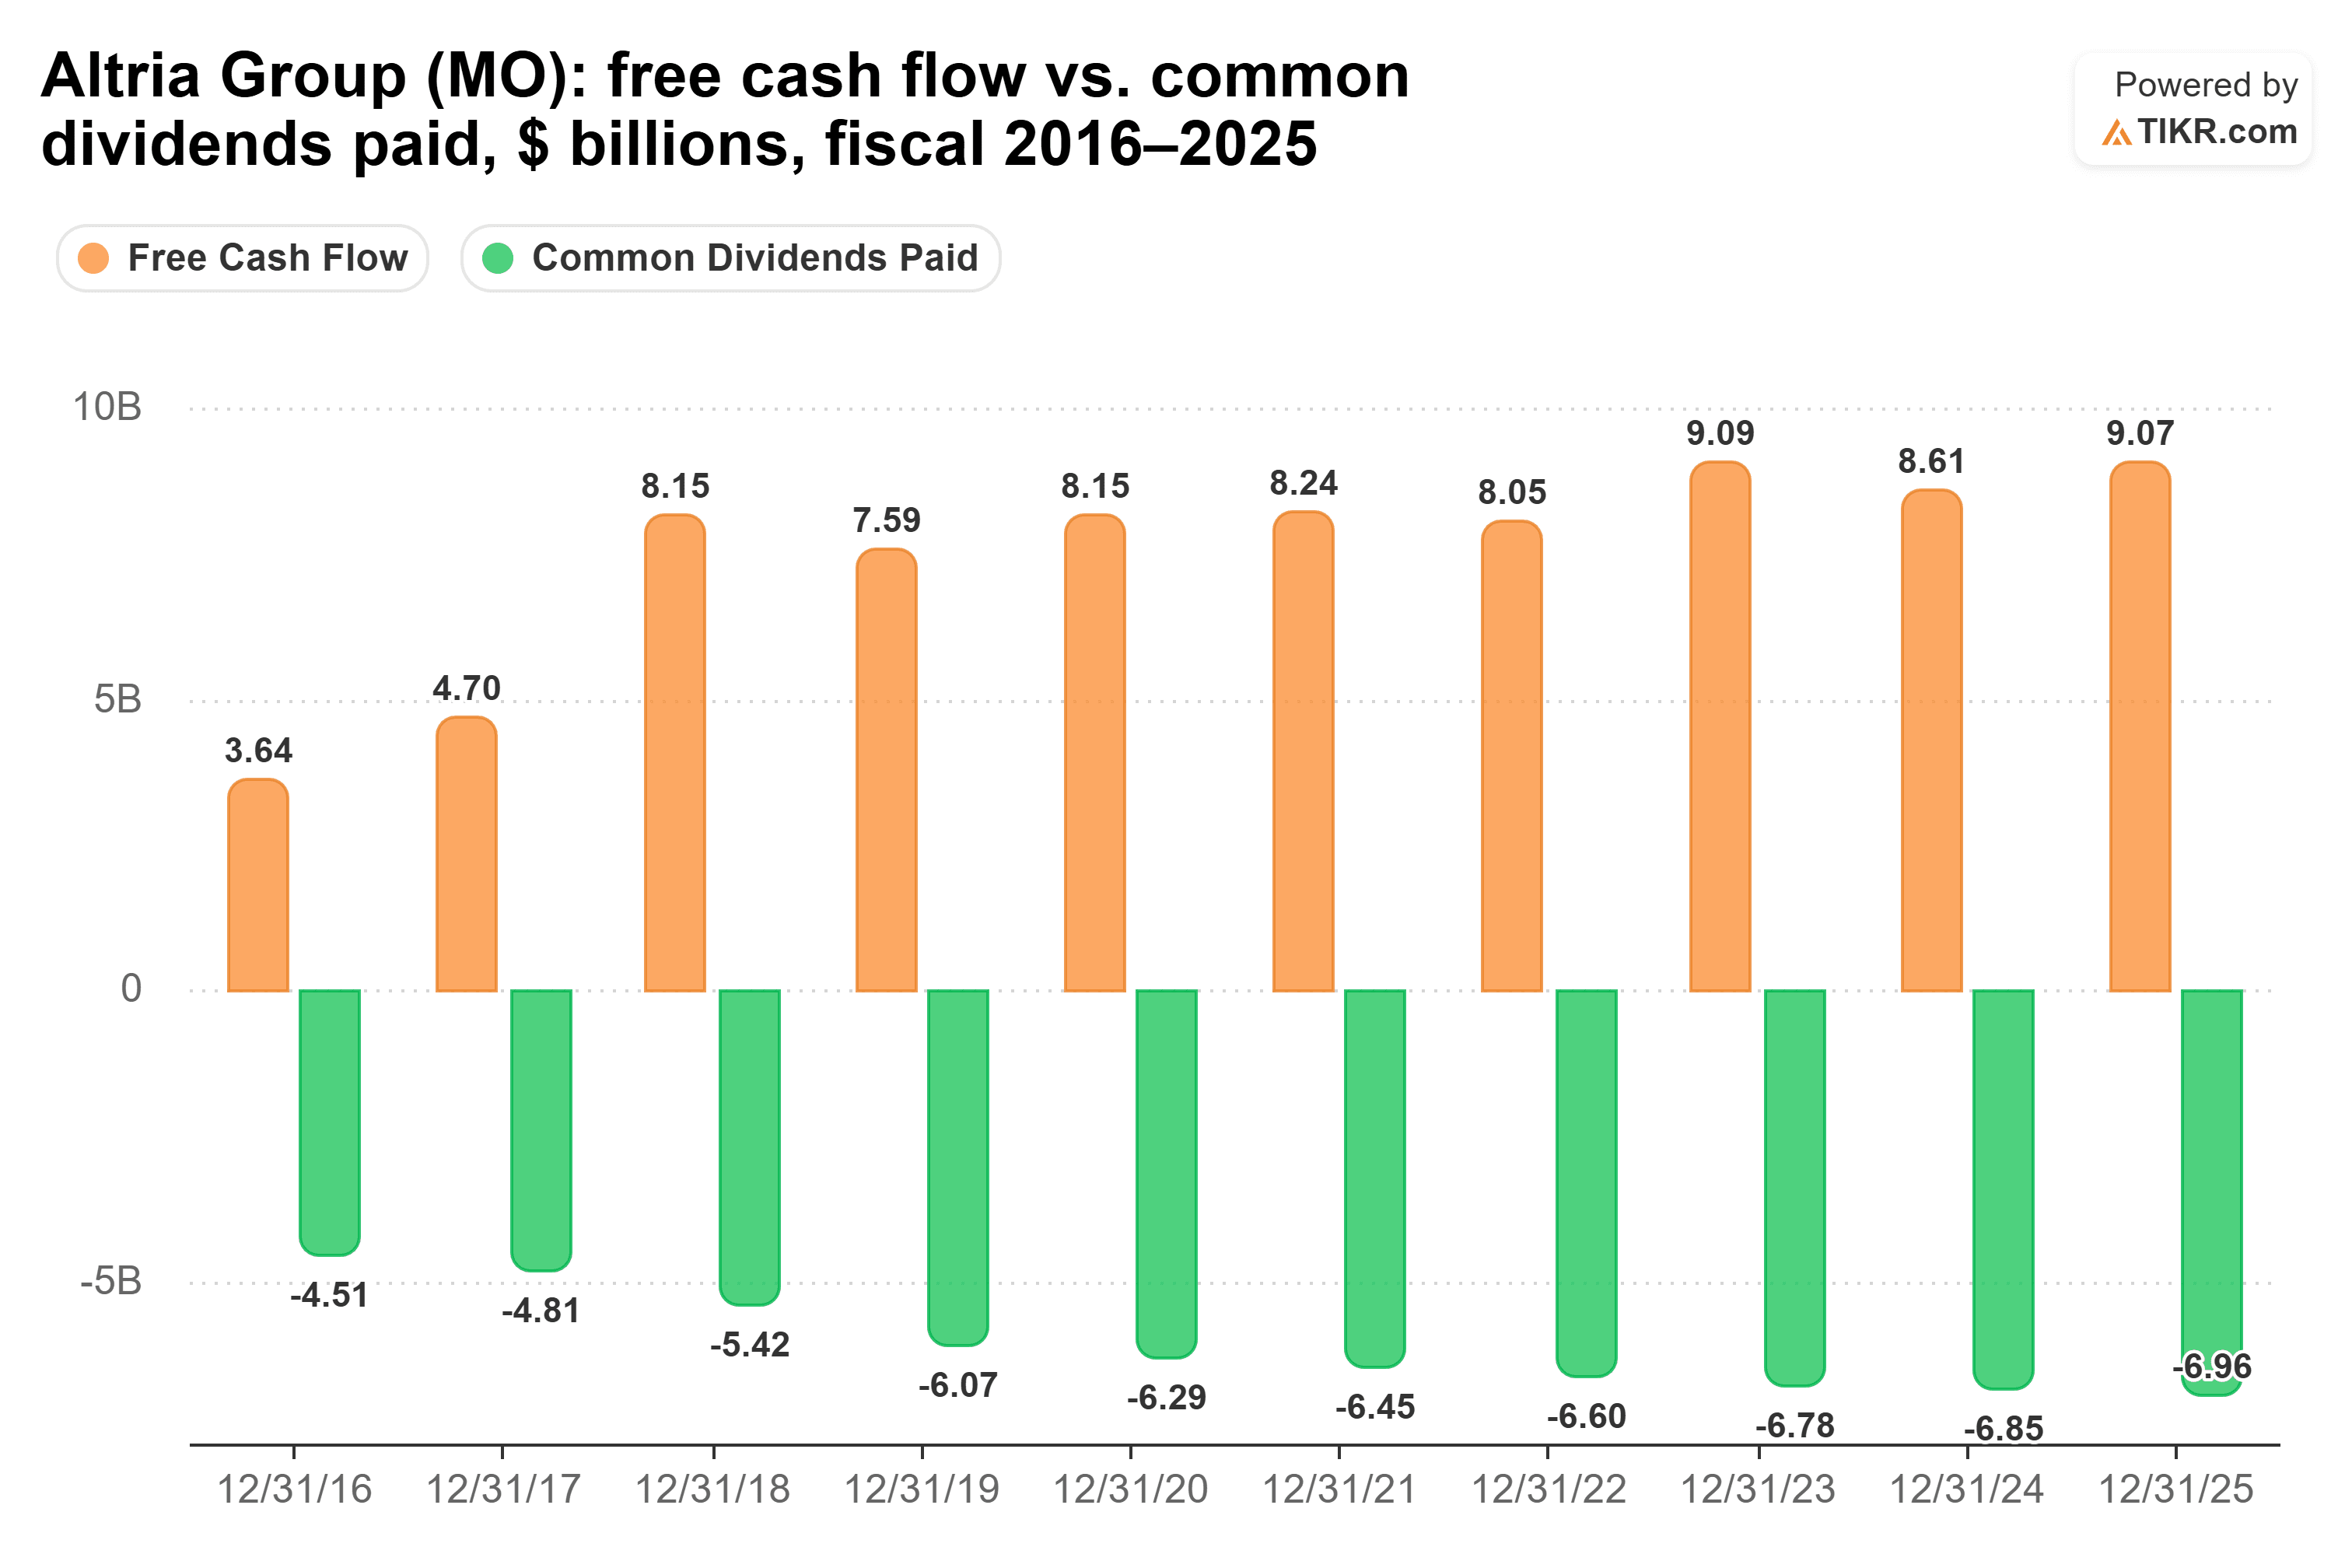
That cash funds a dividend Altria raised 4.7% in August, to $1.11 a share each quarter. Over the 12 months to Sept. 30, 2026, Altria paid out a manageable 78% of its free cash flow, $7.12 billion of $9.07 billion.
Free cash flow has covered the dividend every year since fiscal 2018. It rose from $8.15 billion that year to $9.07 billion in fiscal 2025, while dividends paid went from $5.42 billion to $6.96 billion:
Management targets mid-single-digit dividend growth each year through 2028. With 2026 adjusted EPS guided up 4.5% to 6.0%, earnings are keeping pace with that goal. The risk is that cigarette volumes drop faster than the pouches can make up.
Enbridge has growth on its side
Altria is managing a shrinking core, while Enbridge’s growth is coming from gas. Its gas transmission and distribution businesses grew by double digits in the third quarter of 2026, and Enbridge has C$38 billion of secured projects in its backlog.
Enbridge raised its dividend 3% on Dec. 3, 2025, to C$0.97 a quarter. The dividend is set in Canadian dollars, so the $2.80 a year a US holder gets at today’s exchange rate moves with the currency. Canada also withholds tax on dividends paid to US holders.
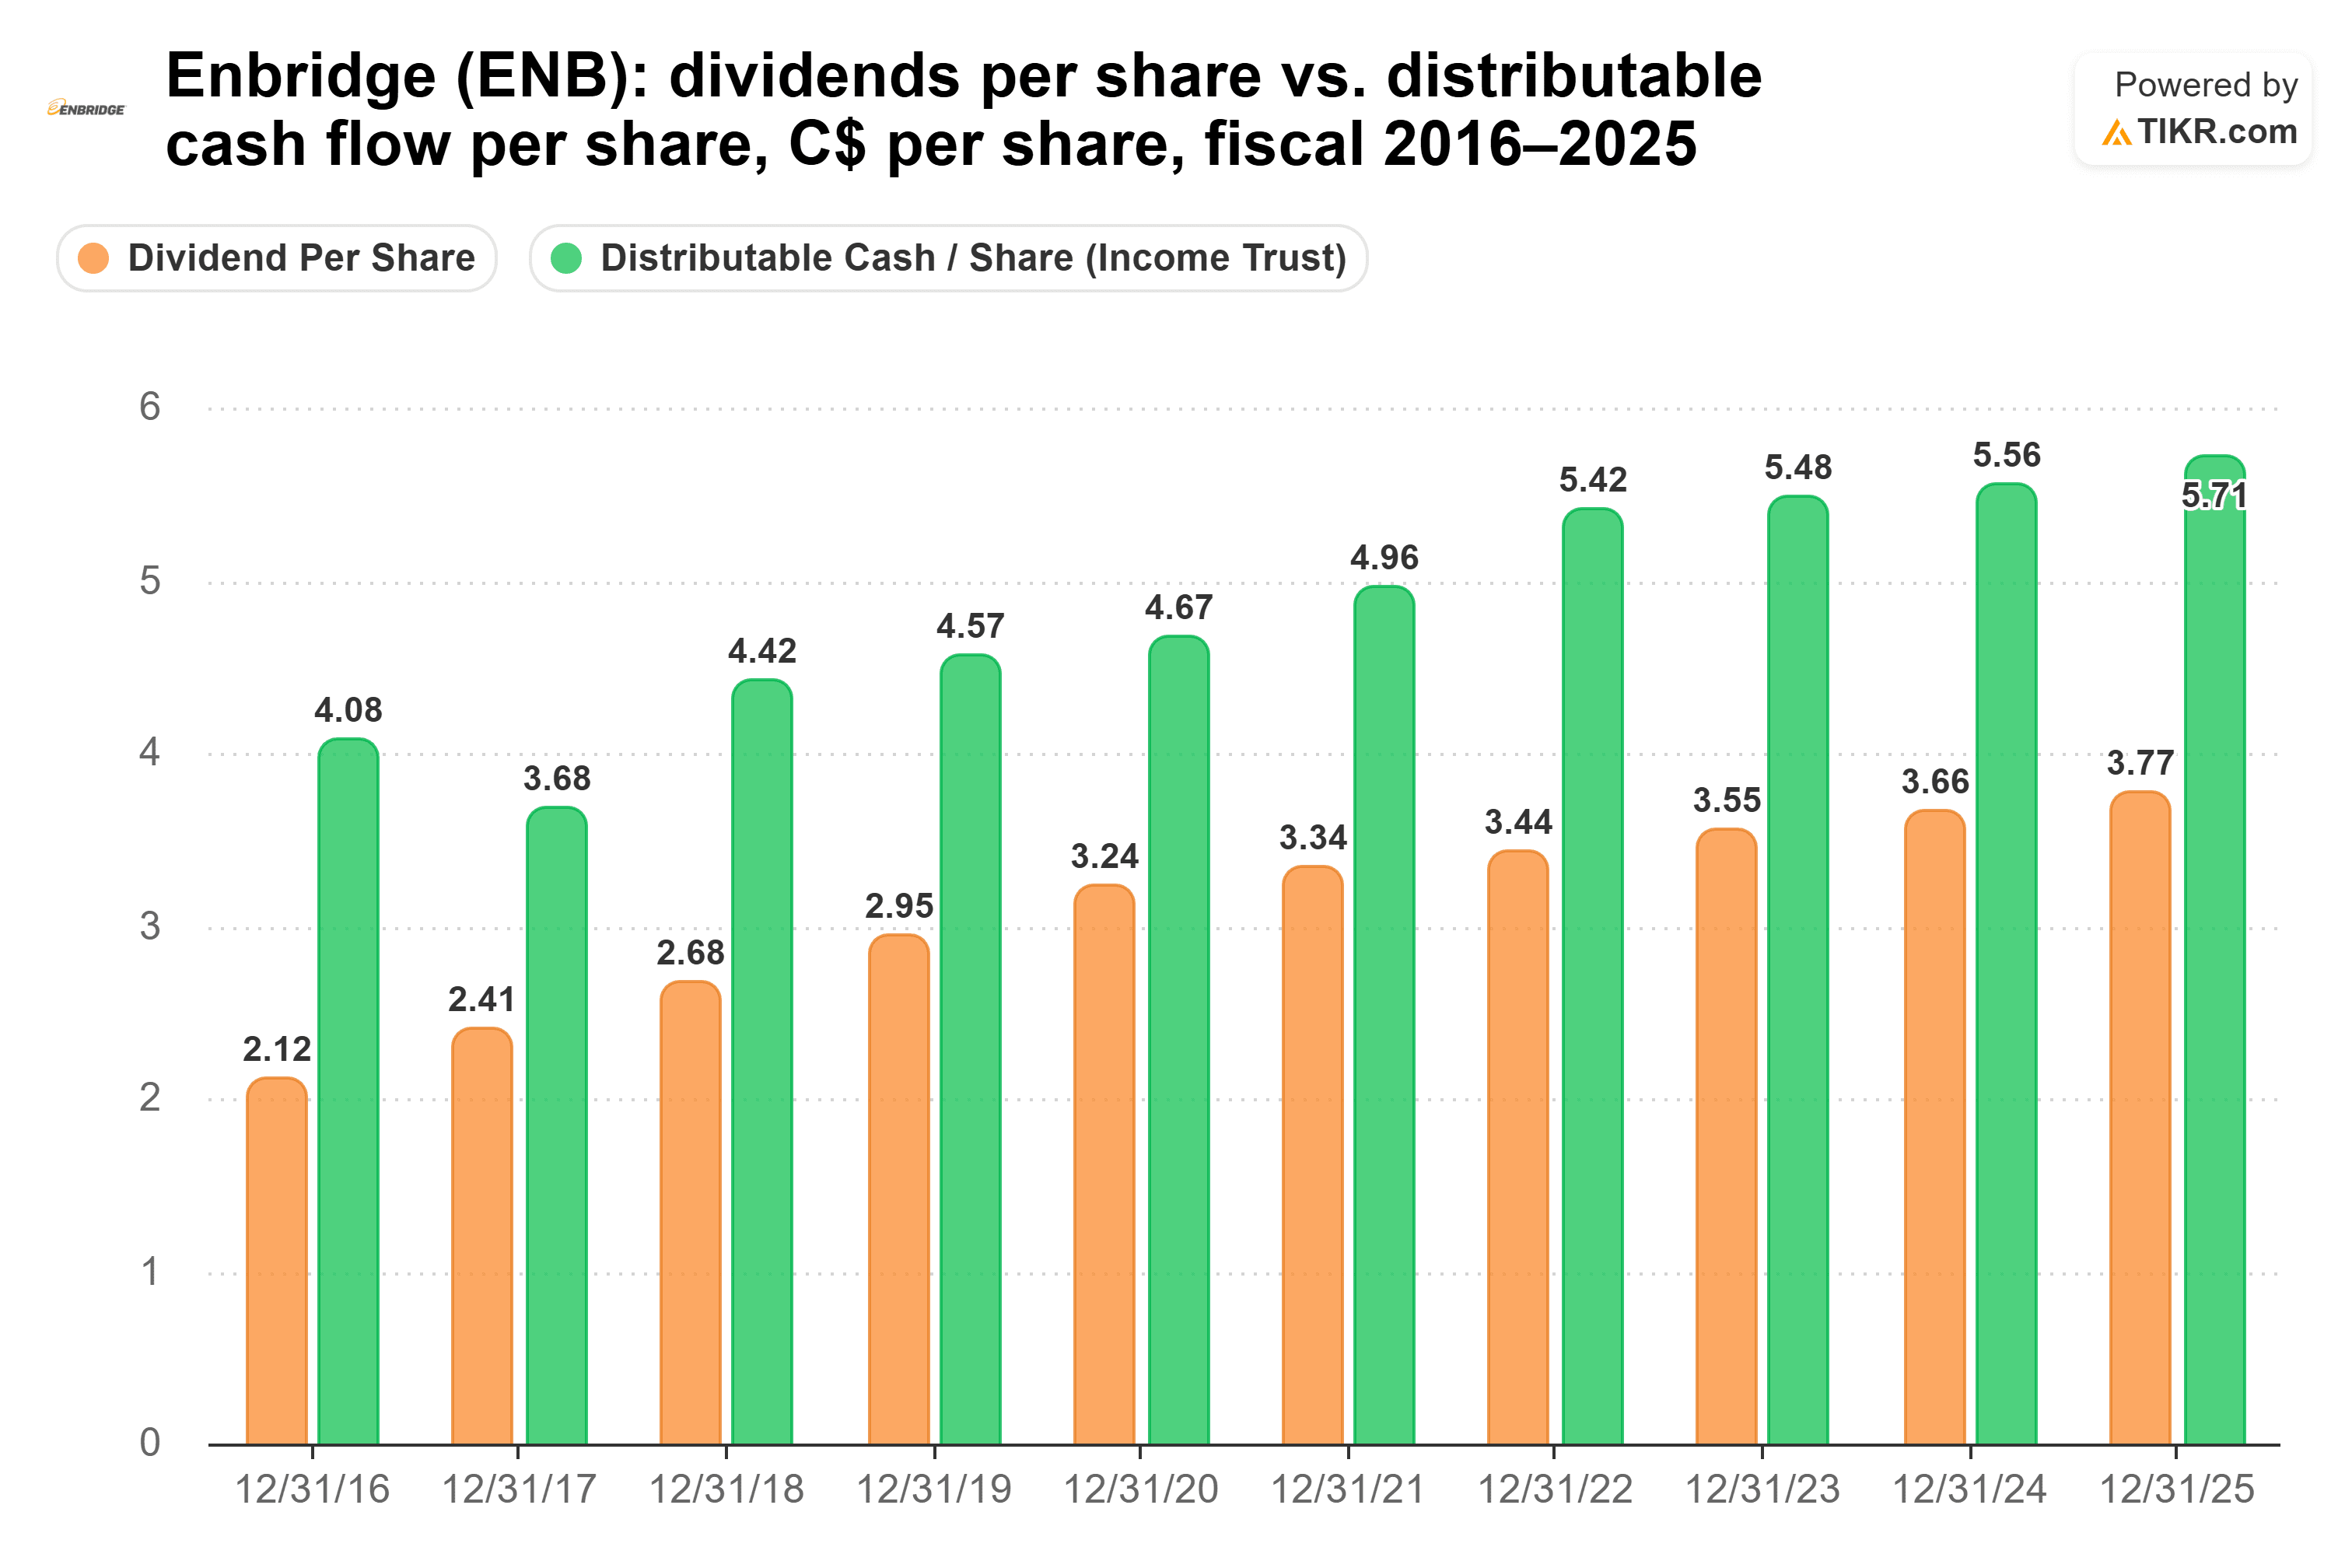
In fiscal 2025, distributable cash flow of C$5.71 a share covered the C$3.77 dividend a comfortable 1.51x. Coverage has held between 1.44x and 1.58x every year since fiscal 2020:
Management expects distributable cash flow per share to grow about 5% a year over the medium term. That’s faster than its latest 3% raise, which leaves room to keep the streak going. The business risk is Canadian policy uncertainty, which management says is affecting when it commits capital to expanding the Mainline.
So which dividend wins?
Altria is the better high-yield dividend stock, mainly because so little debt sits behind its dividend. Enbridge’s net debt has run at 5.5x EBITDA or more in each of the last five fiscal years, and it was 6.0x in fiscal 2025:
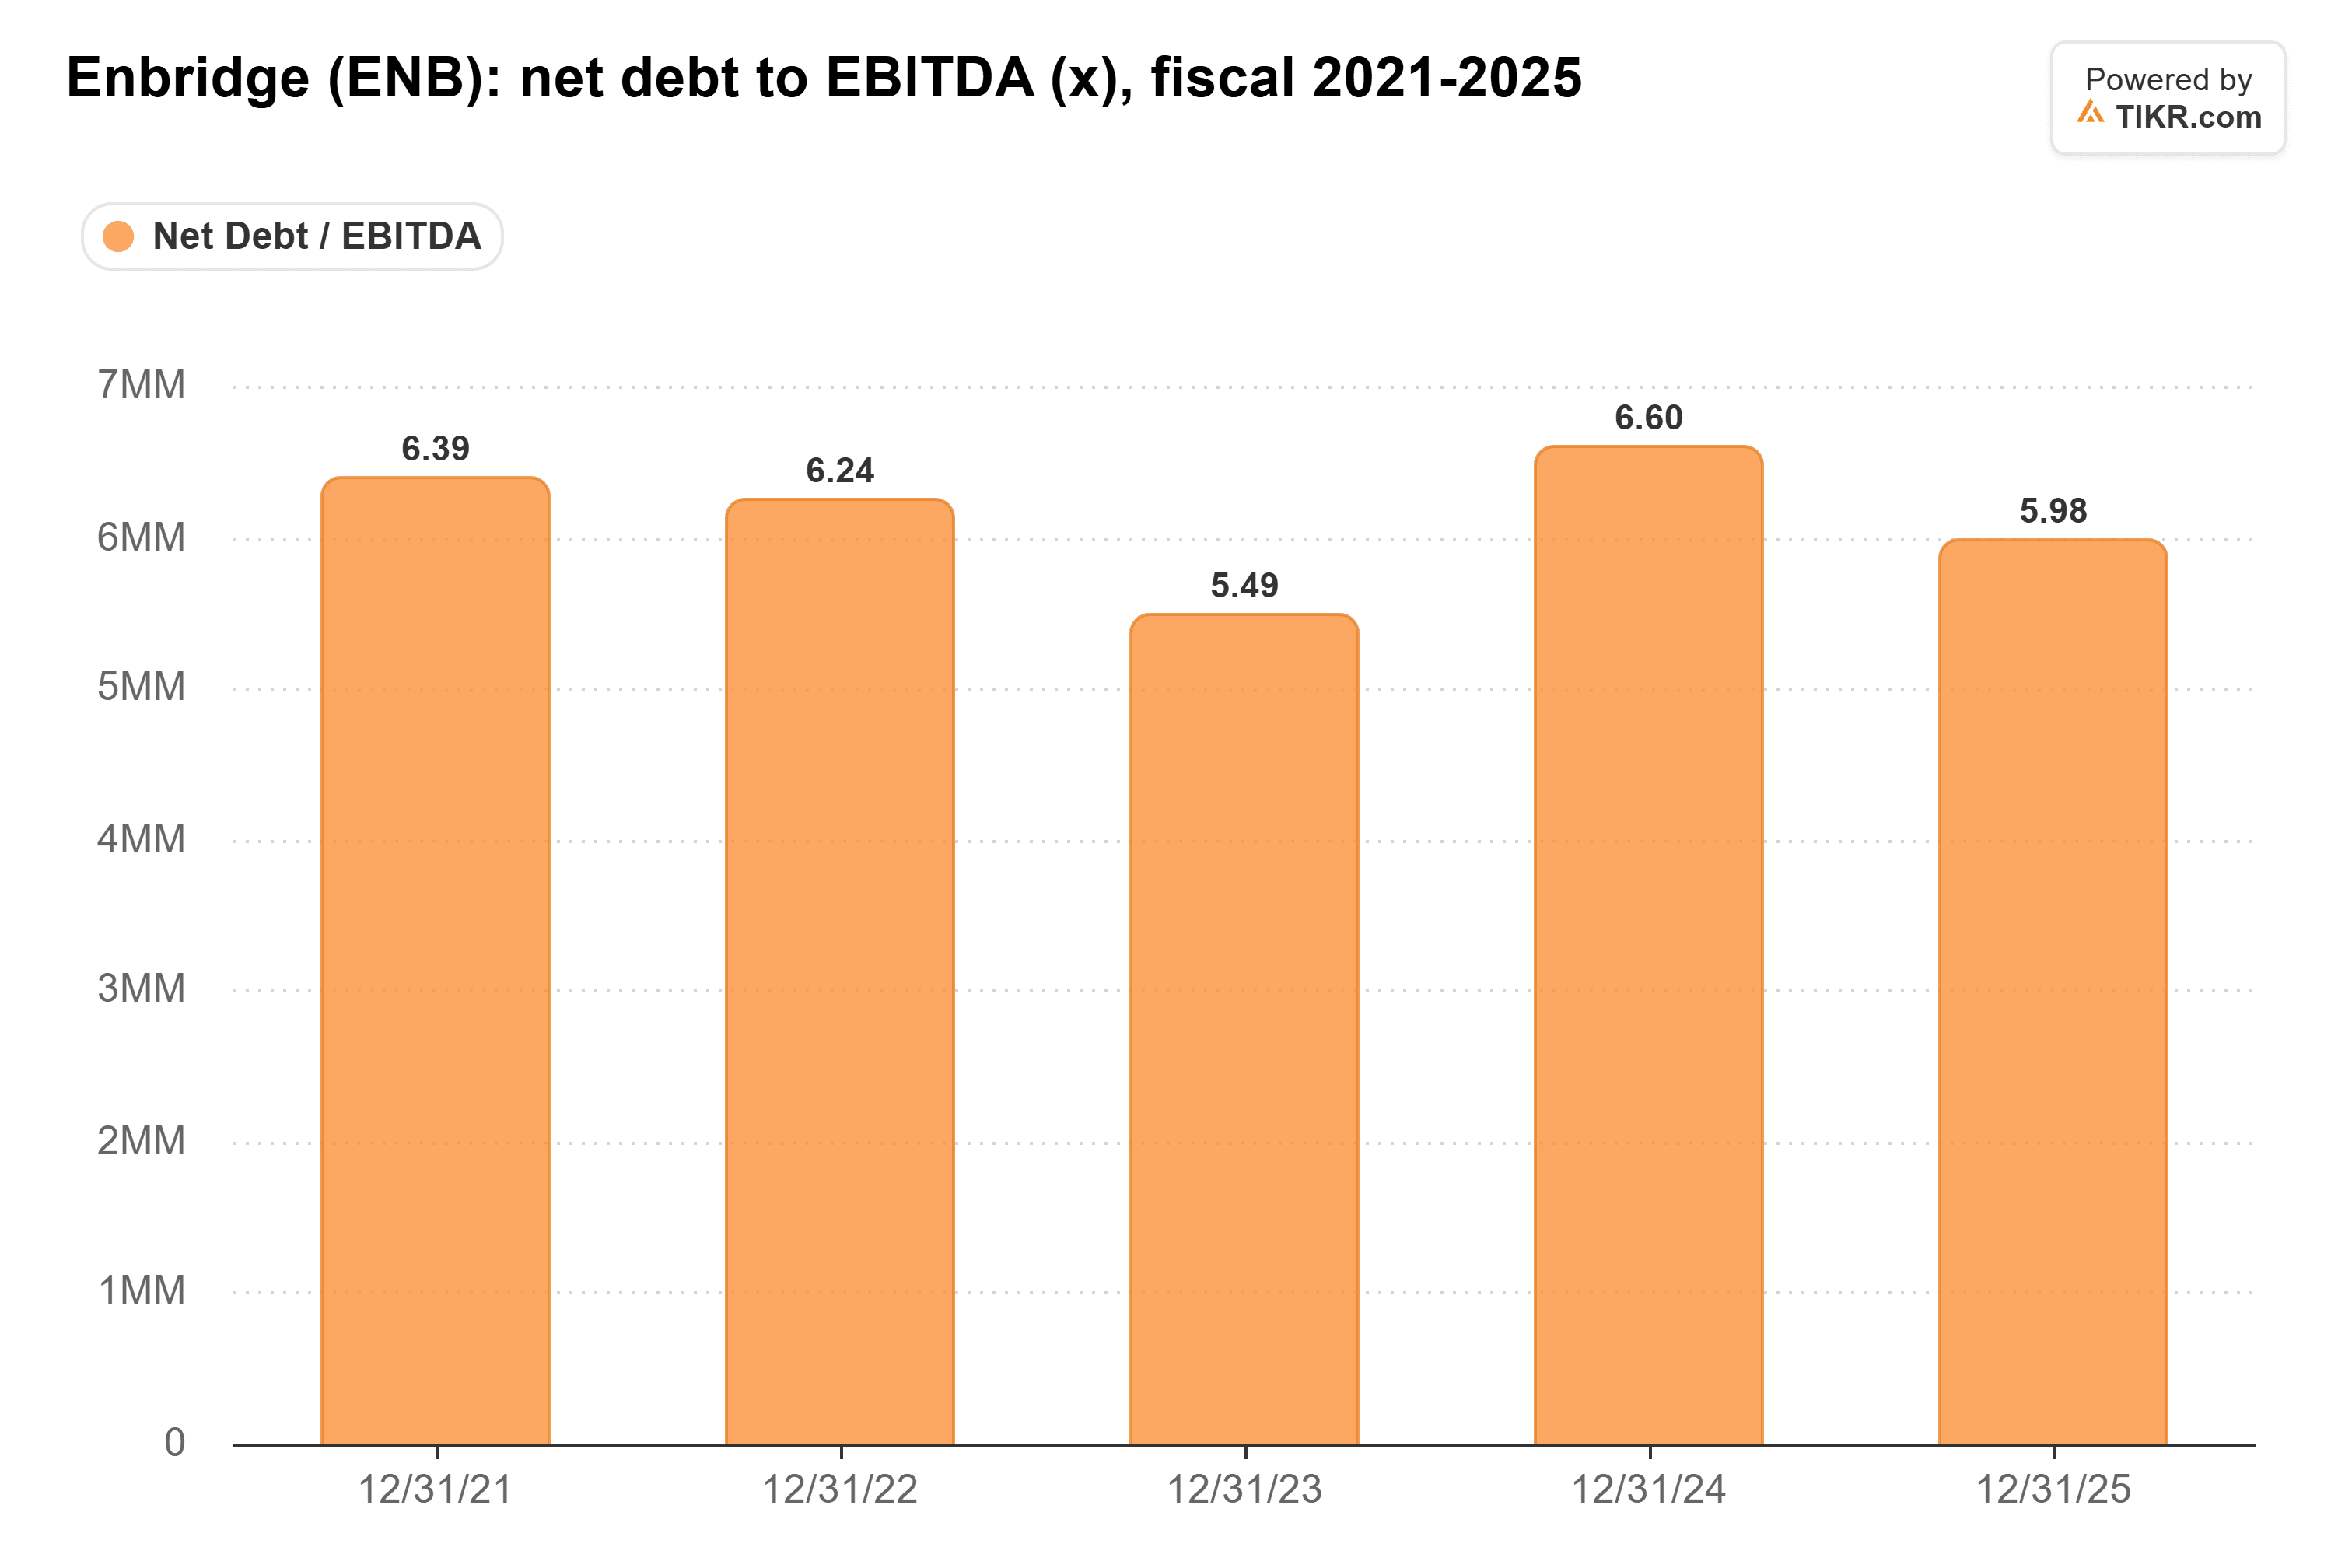
Altria’s is 1.7x, and its operating earnings cover its interest 10.9x, against 2.4x at Enbridge. Altria’s dividend has also grown faster: 4.1% a year from fiscal 2020 to fiscal 2025, against 3.1% for Enbridge in Canadian dollars. At those rates, $10,000 in Altria pays $590 a year today, against $600 from Enbridge. Altria’s income passes Enbridge’s by 2028, and it reaches about $848 in year 10, an 8.5% yield on the original $10,000. Enbridge’s reaches about $788, or 7.9%.
This isn’t to say Enbridge’s dividend is in trouble. Its coverage has barely moved in years, its gas business is growing, and management calls the dividend “central to our strategy.” It’s just that, for a dividend I’m counting on for income, I’d rather own the one with far less debt behind it.
Of course, Enbridge’s own debt measure, which it figures differently, was 5.1x at the end of September, just above its 4.5x-5x target. If Enbridge gets back inside it as its backlog comes into service, I’d take a fresh look.
Forget Altria Group: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Altria Group isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!