Key Takeaways
- Former Treasury Secretary Jack Lew said this week that “nobody can let Social Security be cut 22 percent.” His figure lines up with the trustees’ projection for when the retirement trust fund runs dry in late 2032.
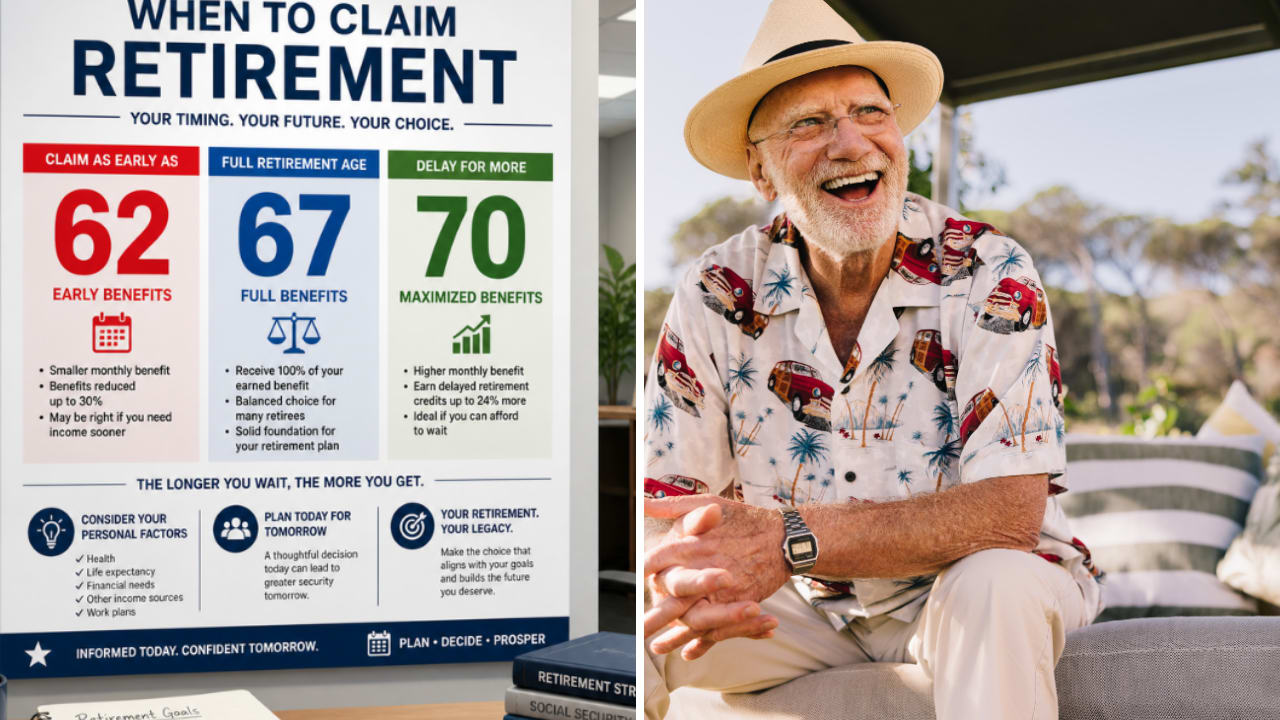
- A worker with a $2,000 benefit at full retirement age would get $1,400 a month by claiming at 62, or $2,480 by waiting to 70.
- A 22% cut to both checks would shrink them to $1,092 and $1,934.40, so waiting to 70 would still pay $842.40 a month more.
- A cut that hits everyone the same leaves the break-even age a little past 80, so fear of a cut on its own is a weak reason to claim early.
Former Treasury Secretary Jack Lew had a warning on CNBC’s Squawk on the Street this week. He was talking about the country’s long-term deficits and his point that Social Security runs out of money within the six-year terms of the senators just elected. He said Social Security offers “the best opportunity to deal with some of these long-term fiscal issues because nobody can let Social Security be cut 22 percent.”
If you’re in your early 60s, a line like that can make claiming right away feel like the safe move: get the money before anyone cuts it. But I ran the numbers, and an across-the-board cut would leave waiting to 70 well ahead.
Congress hasn’t cut anything yet
That 22% is Lew’s figure, and no law sets it. It does line up with the Social Security trustees’ 2026 report. The report projects that the retirement trust fund runs dry in late 2032, after which incoming payroll taxes would cover about 78% of scheduled retirement benefits. Lew himself said he isn’t optimistic that the next two years will bring a big long-term deal, though he hopes lawmakers keep compromises on the table.
So nobody knows what a fix will look like, or whether one comes before the money runs short. A flat 22% cut is the worst case Lew named, and today’s claiming rules show us what it would do to each choice.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
Two paths, same $2,000
Let’s take a hypothetical worker born in 1960 or later whose benefit at full retirement age would be $2,000 a month. For anyone born in 1960 or later, full retirement age is 67, and you can start collecting as early as 62. Claim at 62, and the benefit is 30% smaller for life. Wait past 67, and each year adds 8% to the benefit (2/3 of 1% a month) until 70, when the increase stops.
So at 62, our worker’s $2,000 becomes $1,400 a month. At 70, three years of 8% credits add 24%, and it becomes $2,480. Under today’s rules, waiting pays $1,080 a month more.
A cut shrinks both checks
Now apply Lew’s 22% cut to both checks:
| Monthly benefit | Today’s rules | After a 22% cut |
|---|---|---|
| Claim at 62 | $1,400 | $1,092 |
| Claim at 70 | $2,480 | $1,934.40 |
| Waiting pays this much more | $1,080 | $842.40 |
The gap shrinks by the same 22% as the checks, and waiting to 70 still pays $842.40 a month more. A cut would sting either way, but claiming early would still mean the smaller check.
It doesn’t change when waiting pays off, either. By 70, the early claimer has collected eight years of checks: $134,400 at $1,400 a month under today’s rules, or $104,832 at $1,092 after a cut. Divide each total by its monthly gap ($1,080, or $842.40 after a cut). Either way, the worker who waited needs about 124 months, or roughly 10 years and 4 months, to catch up. That’s a little past 80, cut or no cut. Live longer than that, and every month after it puts the worker who waited further ahead.
Claiming early buys a head start
If you reach 70 before late 2032, a cut would land on both checks the same way, since both paths would already be collecting. But if you’re 62 today, a cut wouldn’t hit right away. Claiming now means about six years of full checks before late 2032, while someone waiting to 70 would collect only the smaller, cut checks. That head start pushes the break-even later, but it doesn’t touch the $842.40 a month that keeps coming from 70 on.
A real fix could also land differently than a flat 22%. Lawmakers could spare people already collecting and put more of the cost on later claimants, which would favor getting in early. They could just as easily do the opposite, or fix it with revenue and cut nothing. None of that is law, and I wouldn’t lock in a 30% smaller check for life to bet on one version of it.
Fear is a bad reason to claim at 62
Frankly, if you’d wait to 70 with no cut in the news, I don’t think Lew’s 22% should change your mind. A cut that hits everyone the same leaves the same break-even age and a check that’s still $842.40 a month bigger. You’d still weigh your health, your savings and how long you expect to live, the same as before.
Of course, a fix that treats people differently by age or by when they claimed could change that answer. So keep an eye on what the new Congress actually proposes, and on next year’s trustees report.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!