Key Takeaways
- Arista Networks fell 11% today as an AI hardware selloff tied to Democrats’ midterm sweep hit networking stocks, and Ciena fell even harder.
- The drop came two days after Arista guided 2027 revenue to about $18.5 billion, well above the $16.4 billion analysts expected.
- A downgrade of Cisco over AI hardware margins added pressure, though Arista’s own gross margin improved last quarter.
- Arista’s forward P/E is below its five-year average, and the selloff looks overdone.
Arista Networks (ANET) stock is down 11% today, wiping out its post-earnings gain as the AI hardware selloff that followed Democrats’ midterm sweep hits networking stocks.
Ciena (CIEN) is down 15% with no news of its own, and Cisco Systems (CSCO) is off 8% after an analyst’s downgrade. Investors are selling AI networking as one trade, on fears that a Democratic Congress will slow the data center buildout.
Arista’s outlook just got better
Arista’s third-quarter revenue grew 58.5% to $3.66 billion, and management guided 2027 revenue to about $18.5 billion, which would be growth of 38%-40%.
Going into the report, analysts expected 2027 revenue of $16.4 billion:
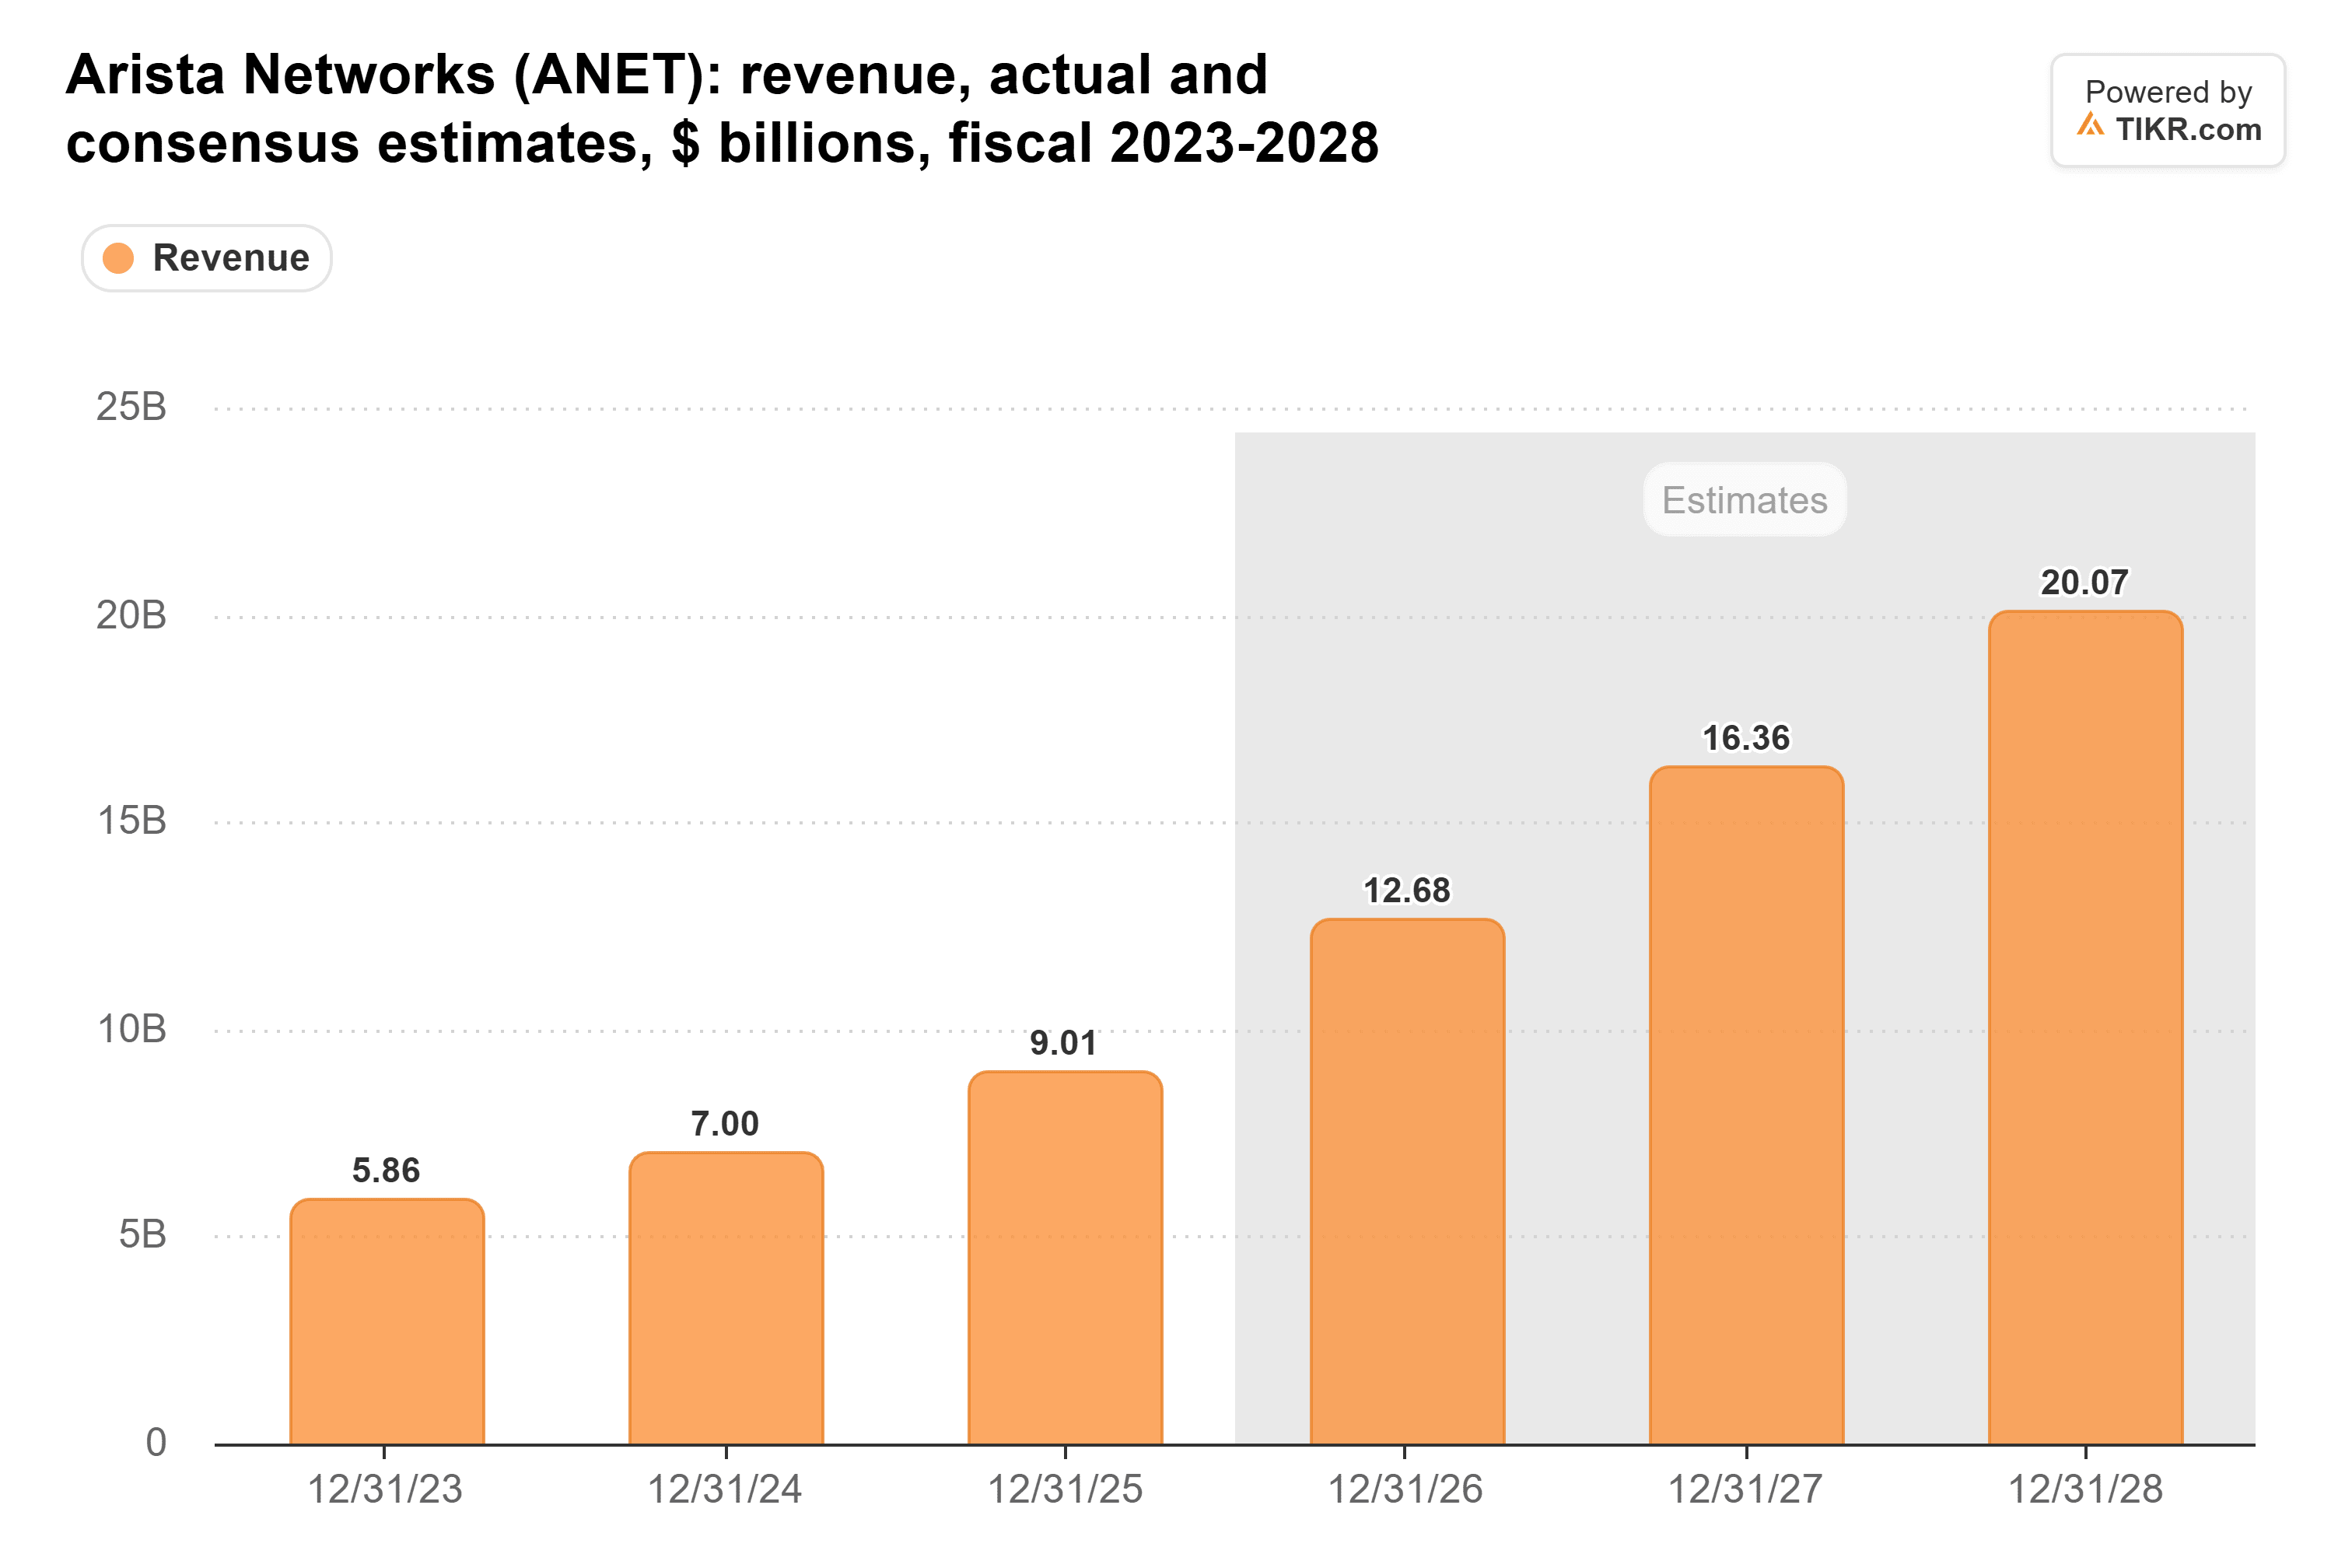
Arista’s guide is about $2 billion above that, and nothing in today’s selling gives analysts a reason to cut their estimates.
TIKR tracks 30 analysts on Arista Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arista Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arista Networks’ Analyst Ratings
Cisco’s downgrade spilled over
Morgan Stanley’s Meta Marshall cut Cisco to Equal Weight from Overweight. “CSCO can continue to appreciate through earnings growth, but strong expectations and gross margin headwinds from AI business leave less room for upside,” Marshall said.
Cisco’s adjusted gross margin was 66.3% in its quarter ended July 25, down from 68.4% a year earlier. Arista sells into the same data centers, but its adjusted gross margin rose to 64.0% in the third quarter from 63.4% in the second, though that’s still below the 65.2% of a year earlier.
Ciena’s exposure looks more like Arista’s. Two customers made up 41.7% of Ciena’s revenue in its quarter ended Aug. 1, when revenue rose 37% to $1.67 billion. Arista’s two biggest customers, Microsoft and Meta, bought 42% of its 2025 revenue. None of those cloud buyers has announced a cut.
Cheaper than usual
On TIKR’s latest reading, Arista’s forward P/E was 35x, just below its 36x five-year average:
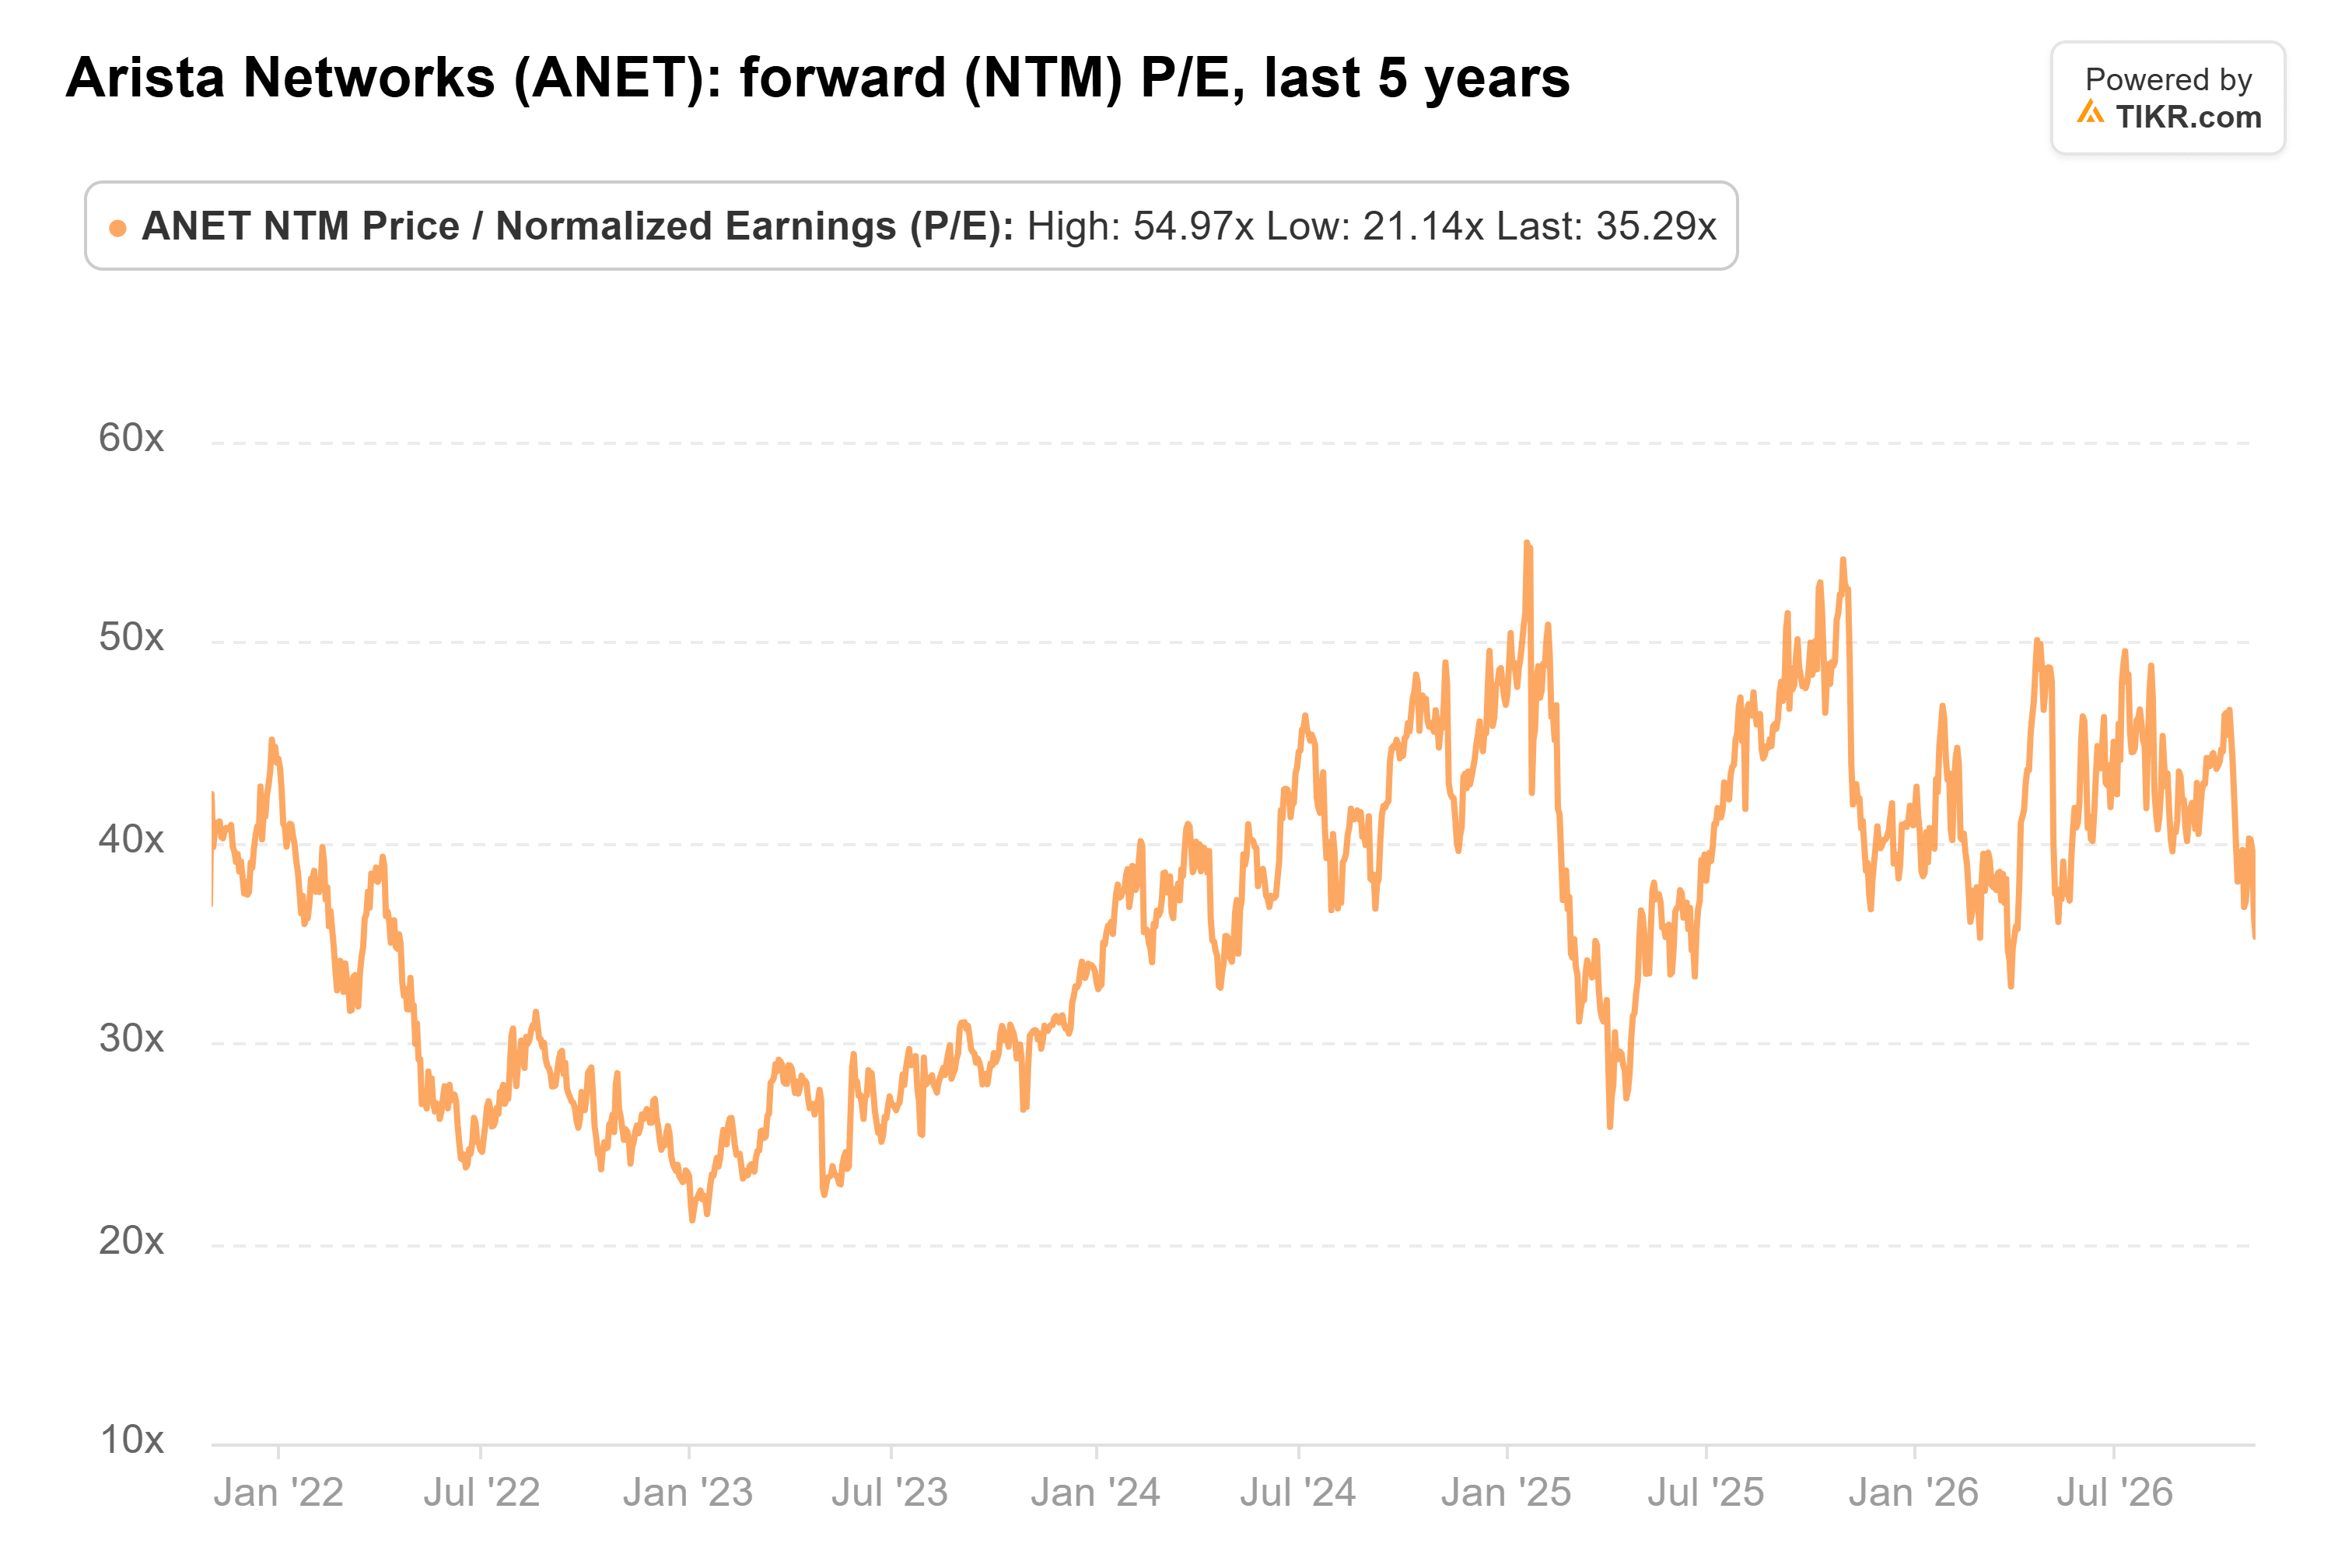
At today’s price, it’s even lower, about 32x.
The way I see it, the market is pricing in a slowdown none of Arista’s customers has announced. For a company guiding to 38%-40% growth next year, the drop looks overdone.
Of course, if Democrats move to slow data center construction, Arista’s biggest customers could rein in spending. Management’s appearance at UBS’s conference on Dec. 1 is the next chance to hear whether orders have changed.
So what is Arista Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Arista Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Arista Networks for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!