Key Takeaways
- At $1.5 trillion, Anthropic’s IPO would value the AI lab at about 19x its $81 billion revenue run rate. Scott Galloway says that’s about where Broadcom and AMD trade.
- Anthropic’s revenue rose 1,200% over the first nine months of 2026, while Broadcom grew 86% and AMD grew 45% in their latest quarters, so the IPO doesn’t look overvalued next to its suppliers.
- The main risk is Anthropic’s compute bill: about $901 billion of commitments against about $132 billion of cash and short-term investments, and Goldman Sachs doesn’t expect positive free cash flow until 2030.
- Broadcom and its financing partners are the largest counterparty on Anthropic’s compute commitments, and Broadcom and AMD are both anchor investors in the deal.
Anthropic is set to price its IPO on Nov. 18, and the best case that it isn’t overvalued comes from two chipmakers putting their own money into the deal: Broadcom (AVGO) and Advanced Micro Devices (AMD).
The range is $70 to $78 a share, or about $1.4 trillion at the top end, and Bloomberg reported on Nov. 11 that the book was already multiple times oversubscribed. On the Nov. 16 episode of the Prof G Markets podcast, Scott Galloway was talking through the deal and noted that “at a $1.5 trillion valuation, that’s 19 times its $81 billion revenue run rate, that trades about where Broadcom and AMD trade.”
At the top of the range, the multiple is closer to 17x. For this kind of growth, that’s not much at all.
Galloway thinks Anthropic has decided “that valuation isn’t the most important thing here. It’s having a pop and raising a lot of money.”
TIKR tracks 51 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
Growth at a chipmaker’s price
Anthropic’s revenue for the nine months to September rose 1,200% to $33.2 billion. Its annualized run rate hit $81 billion at the end of October, up $10 billion in a month. Broadcom’s revenue grew 86% to $29.6 billion in its fiscal third quarter. AMD’s revenue grew 45% to $13.4 billion in its third quarter, and AMD expects about 66% growth in the fourth.
Those are terrific numbers for chipmakers, and analysts expect Broadcom to keep them coming:
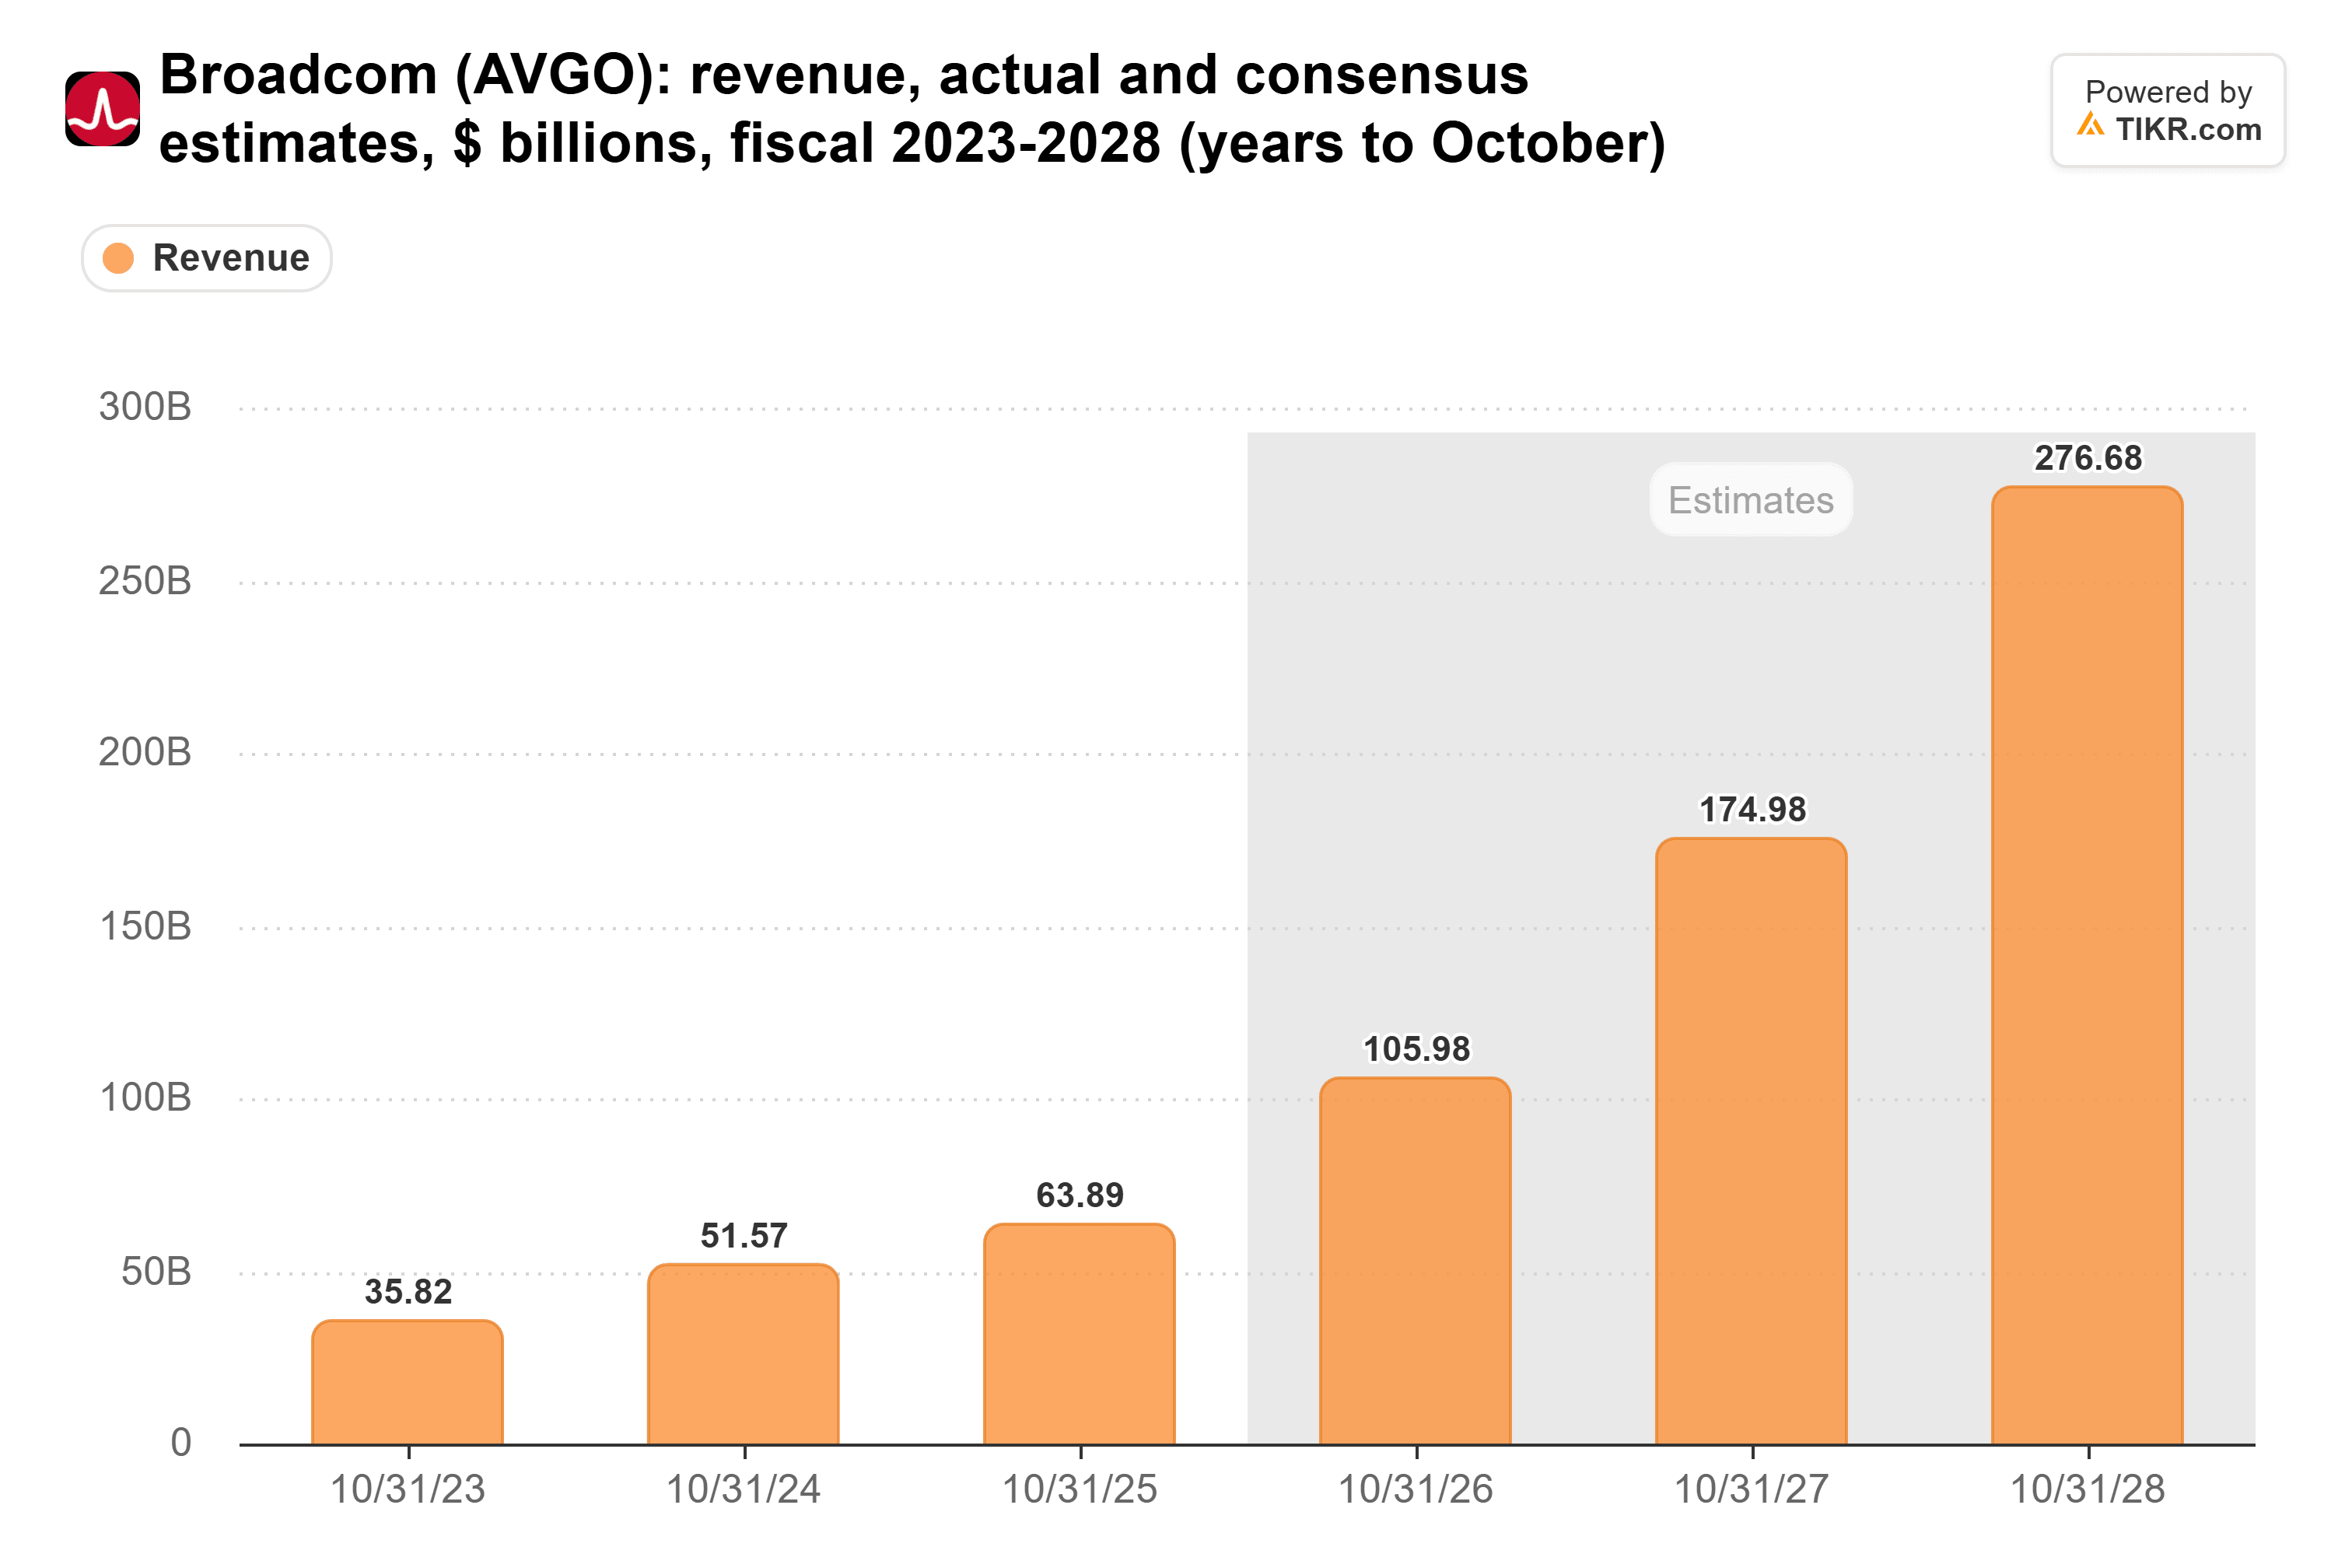
Anthropic’s run rate is already more than three-quarters of the $106 billion consensus for Broadcom’s fiscal 2026, which just ended. Nothing in the IPO itself should move those estimates. But Broadcom expects Anthropic to be its largest custom-chip customer in 2027, so a good part of the next two years’ estimates rests on the lab’s growth.
Broadcom and AMD have profits to price
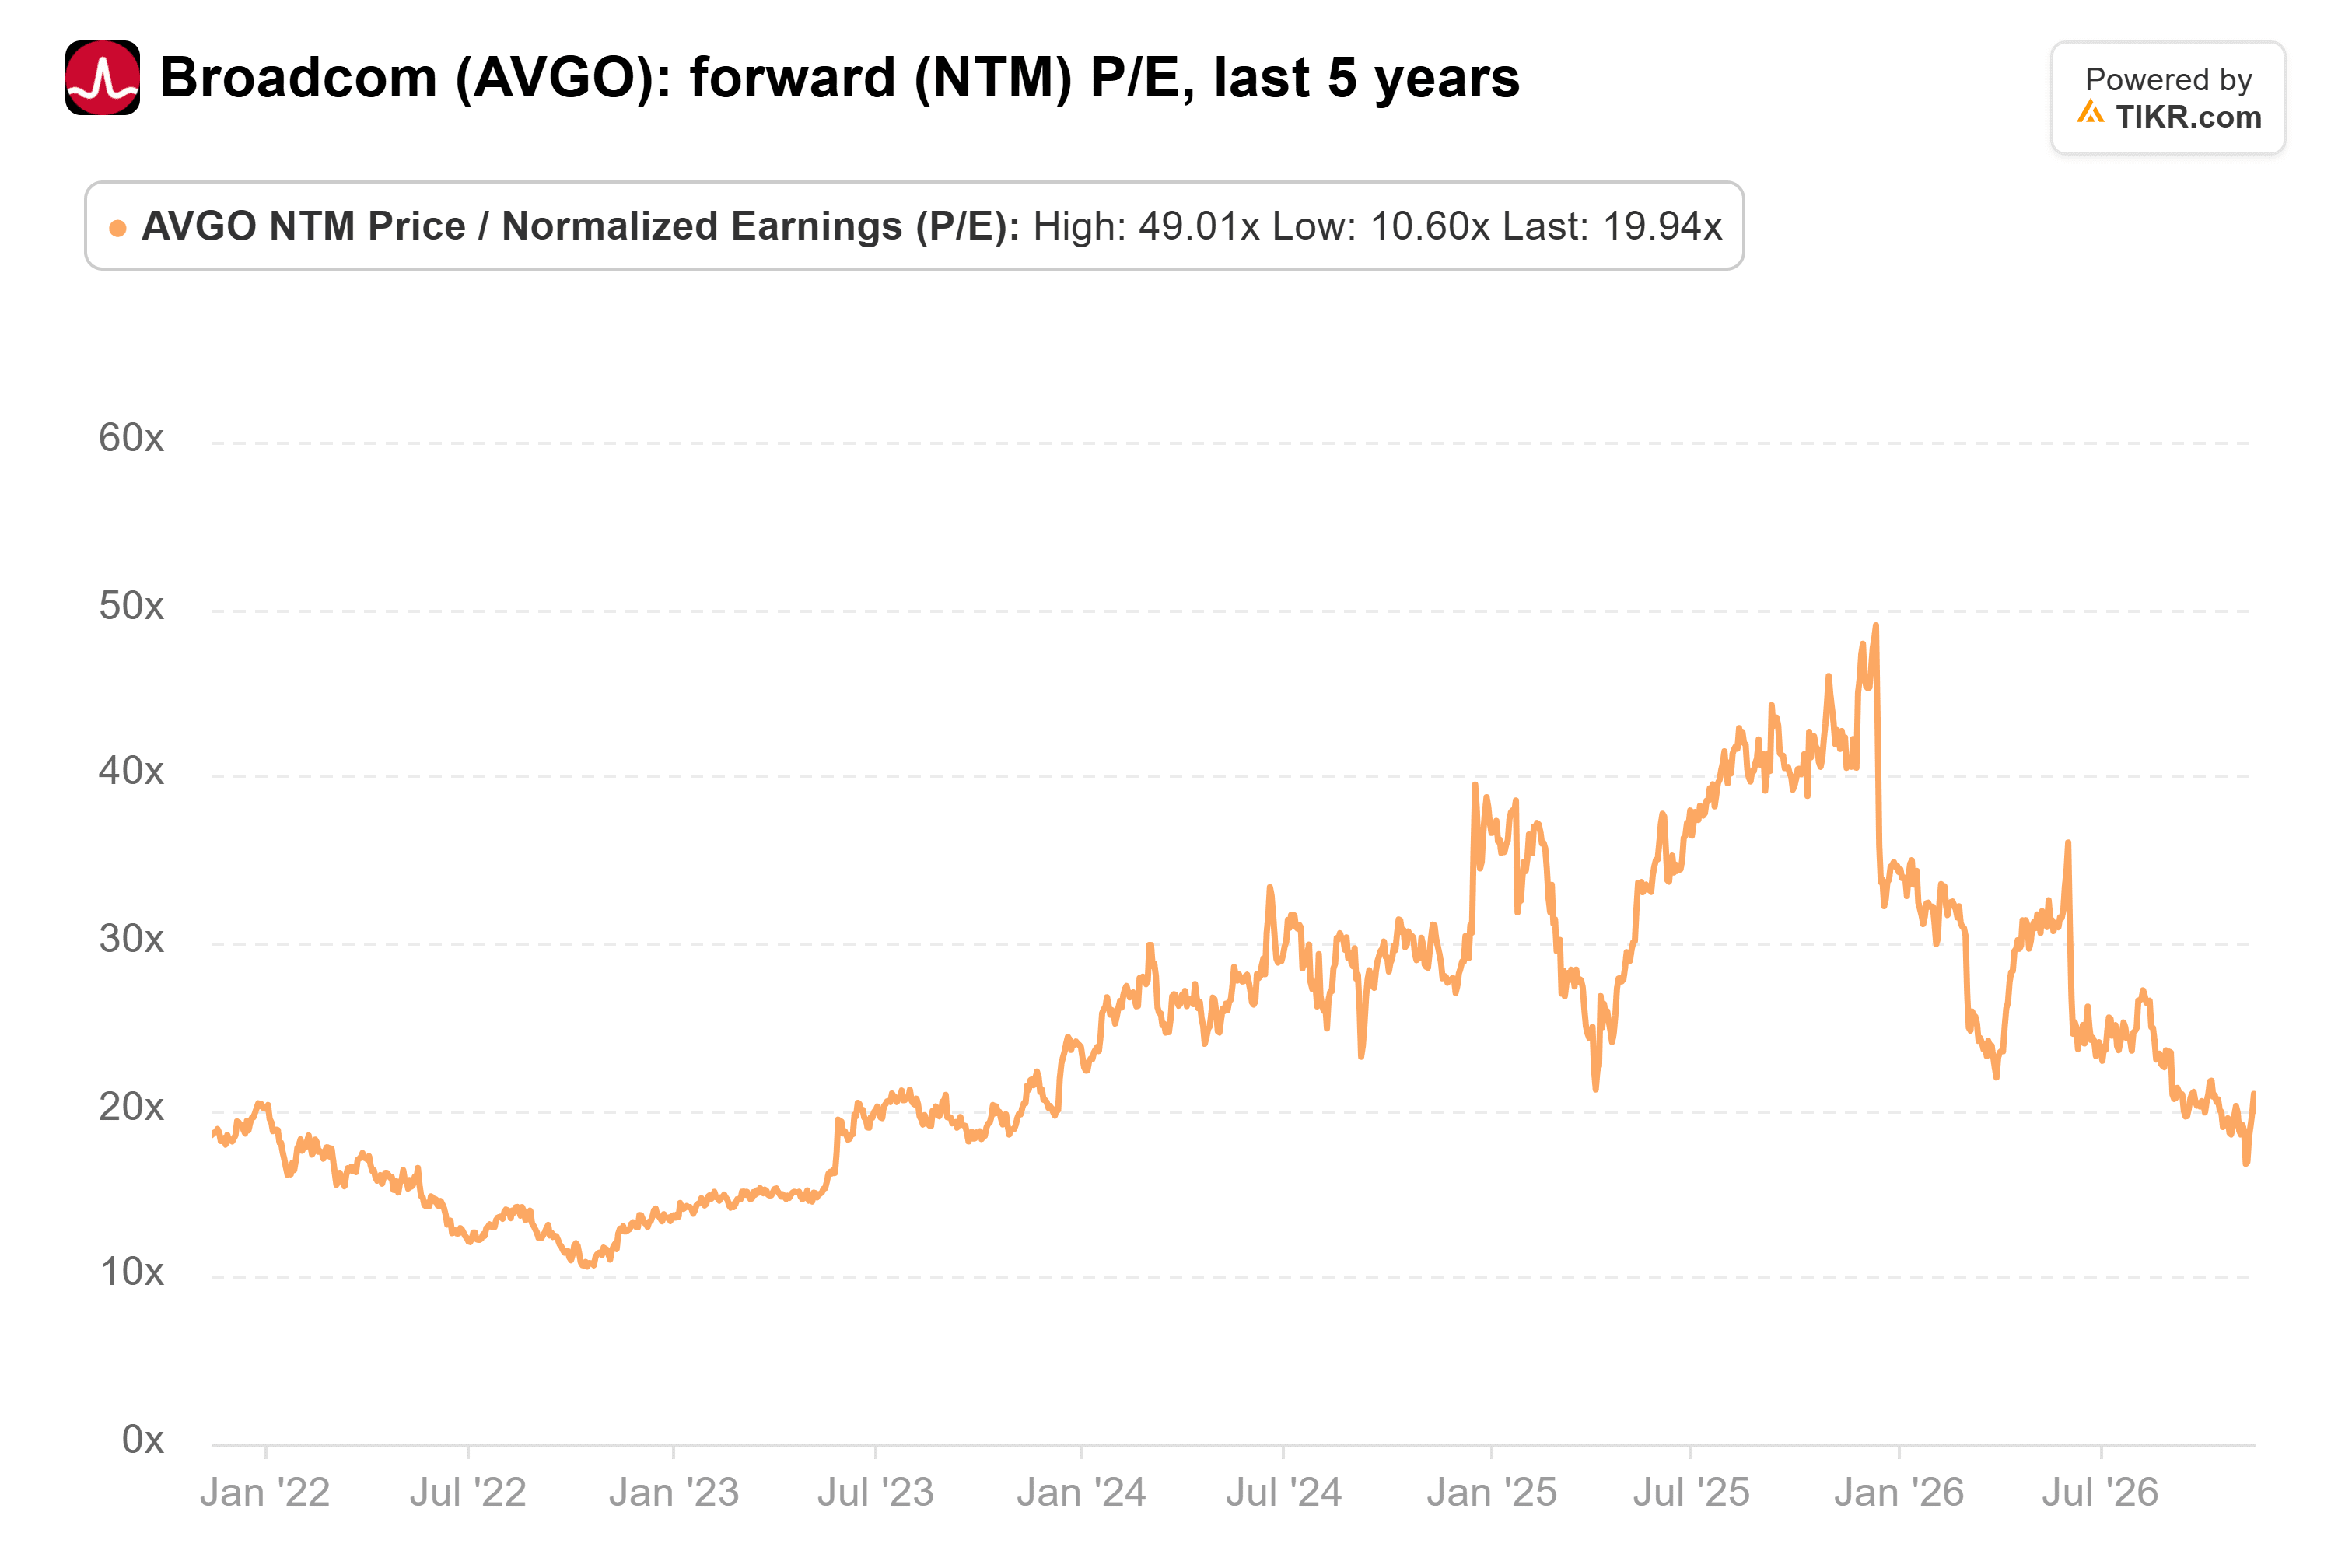
Still, Broadcom and AMD earn real profits, and Anthropic doesn’t yet. Broadcom turned 67.9% of its fiscal third-quarter revenue into non-GAAP operating profit, and its forward P/E of 20x is below its five-year average of 24x:
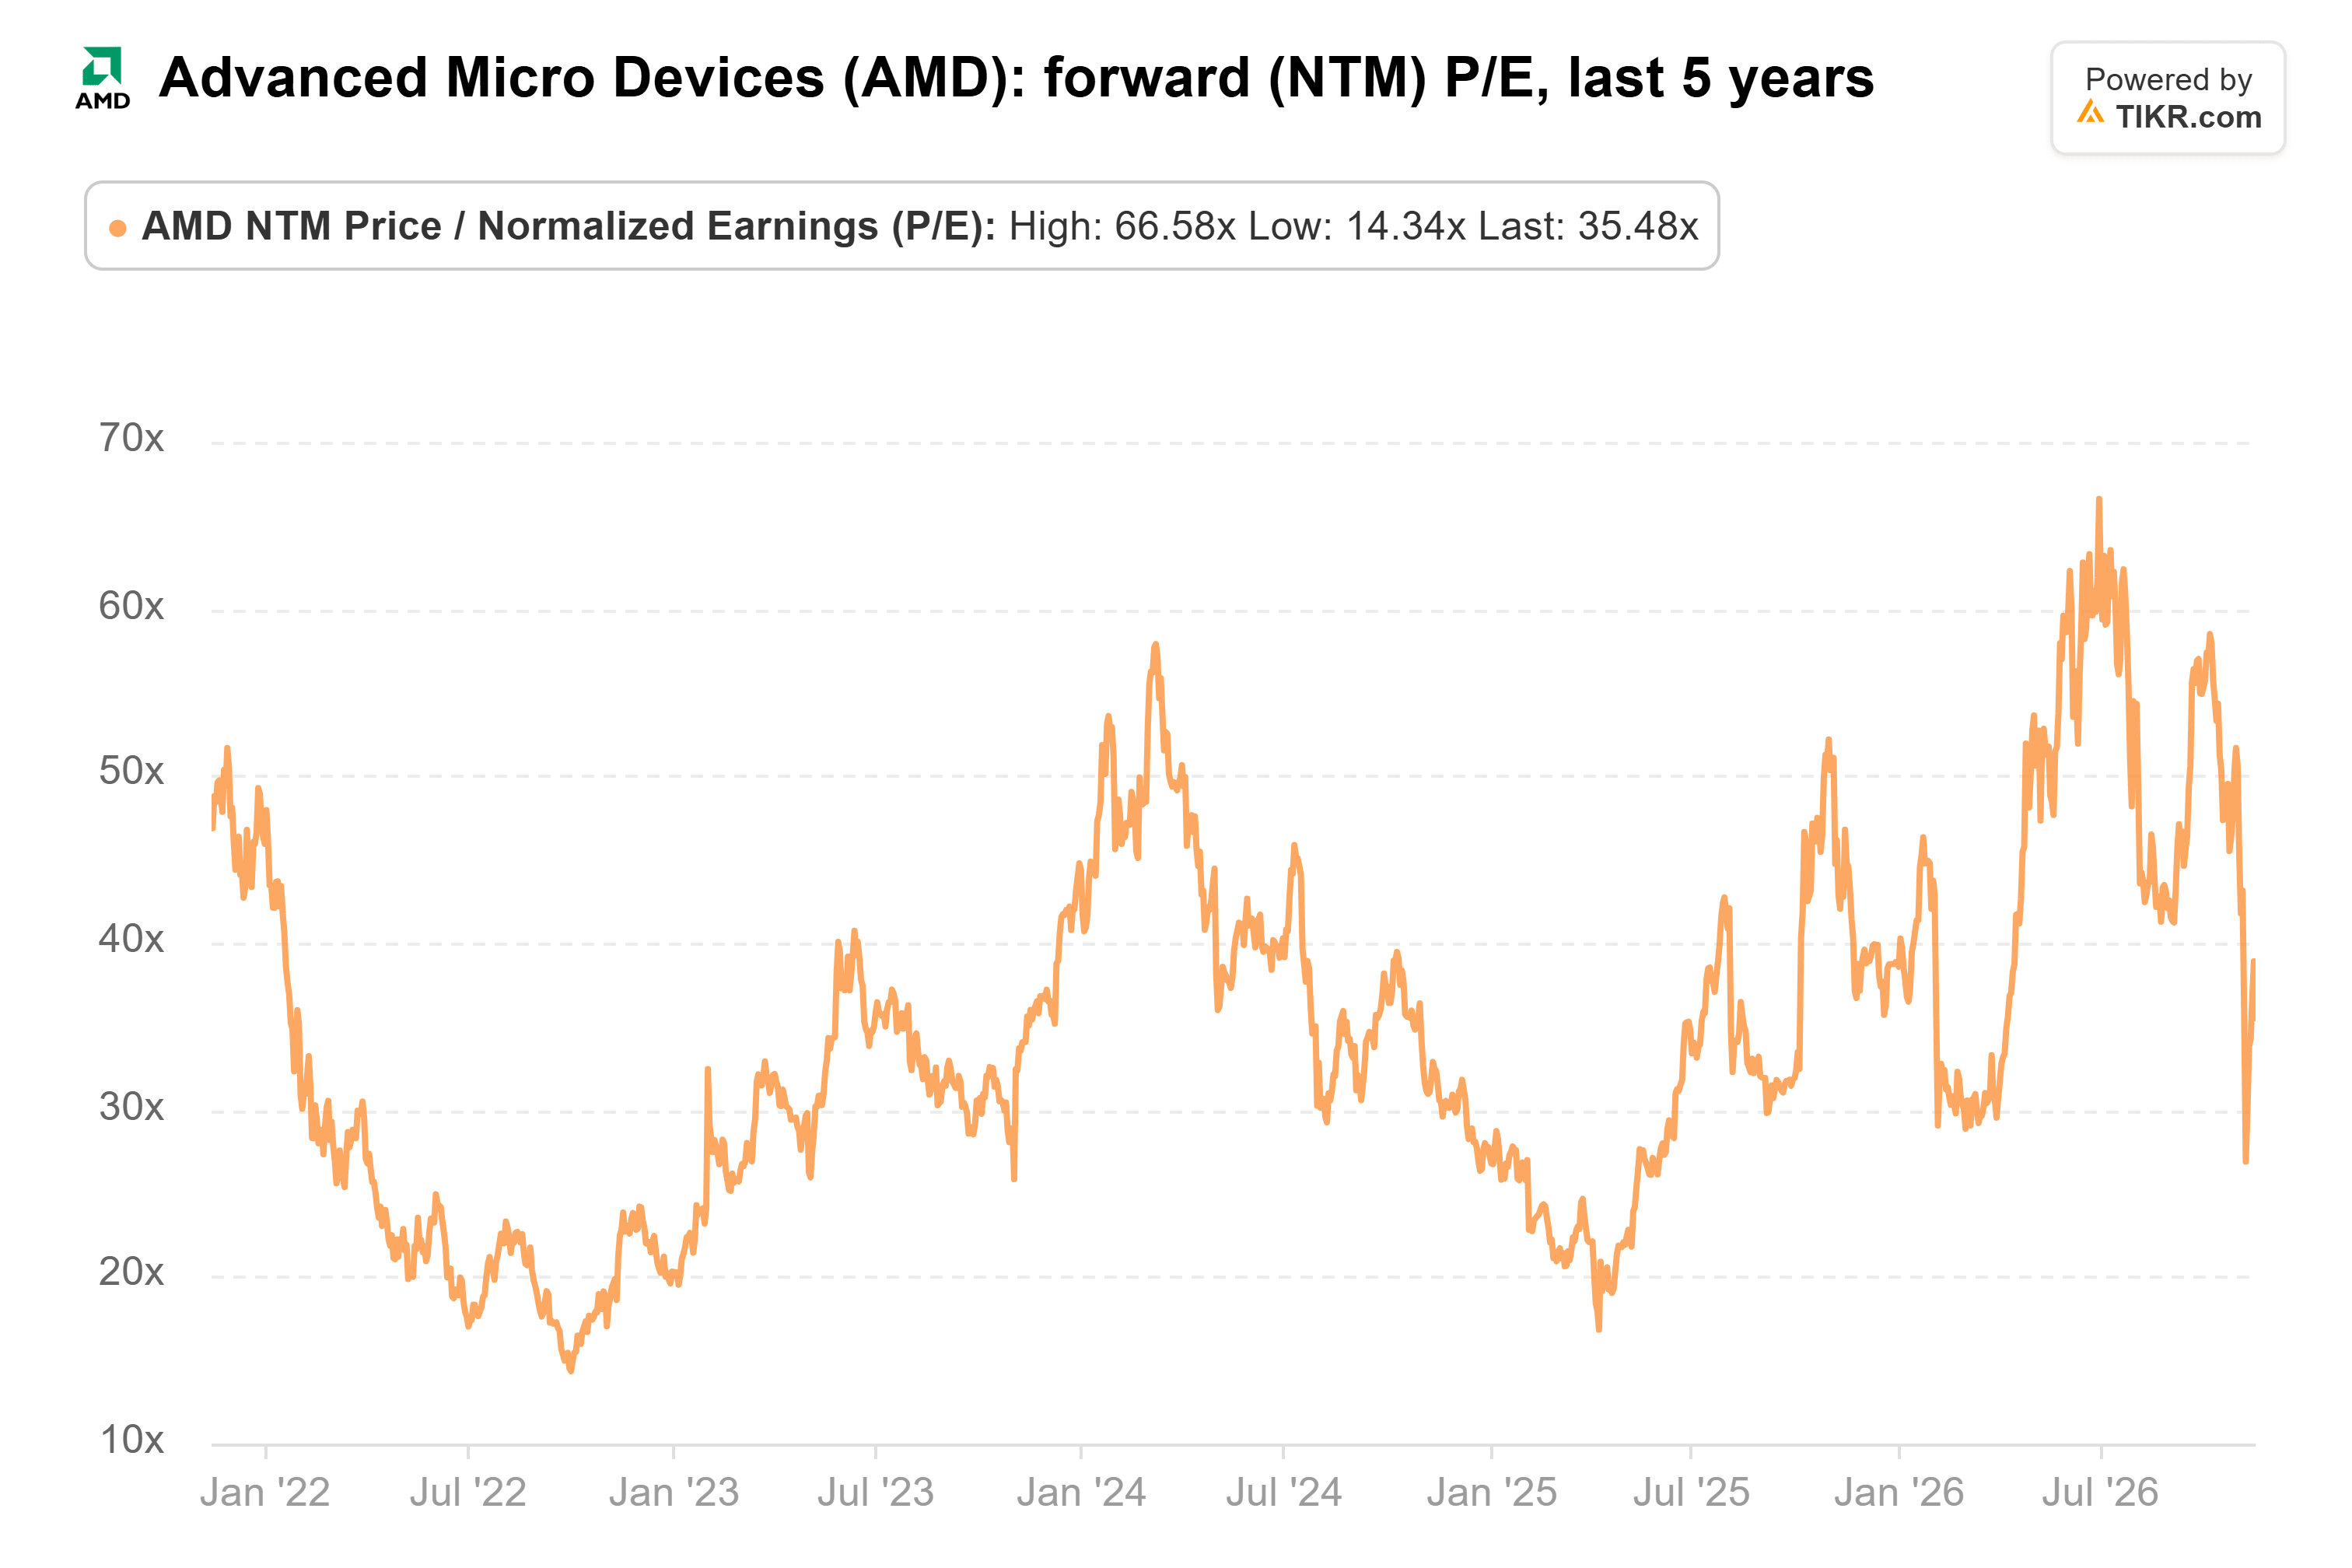
AMD earned $2.8 billion of operating income in its third quarter. It trades at 36x forward earnings, close to its five-year average of 35x and about half its June peak:
Anthropic has no earnings to put a P/E on. It posted a $567 million operating loss in the third quarter. Goldman Sachs, one of the banks leading the IPO, doesn’t expect it to turn free cash flow positive until 2030, Bloomberg reported.
But the lab made a $974 million operating profit in the second quarter. Its filing blames most of the third-quarter swing on $5.0 billion of short-term compute, which costs more than capacity bought under multiyear deals, and $2.0 billion of non-cash donation-matching charges. Compute and infrastructure costs rose about 77% from the second quarter, while revenue rose about 47%. That looks like a company buying capacity as fast as it can sell it, and paying 19x for a run rate that grew $10 billion in a month looks fair.
Broadcom is already in on the bet
Plus: the chipmakers aren’t watching from the sidelines. On the Money Stuff podcast, Matt Levine pointed out that Anthropic launched the deal with $26 billion of anchor investments from its suppliers, Broadcom and AMD among them. He called it “price insensitive money to gross up the IPO without having to find more public buyers who could flip it.” Anthropic’s Nov. 10 filing puts AMD’s share at $2.5 billion and Broadcom’s at $1 billion.
Broadcom and its financing partners are also the largest counterparty on Anthropic’s compute commitments, at about $161 billion of roughly $901 billion. Anthropic expects to incur about $452 billion of those before the end of 2030, and it had about $132 billion of cash and short-term investments at Sept. 30, before this raise. If Anthropic’s growth stalls, its new shareholders and Broadcom’s will feel it at the same time.
A fair price for this growth
That doesn’t look like an overvalued IPO. Anthropic is growing more than 10 times as fast as its suppliers. If Galloway is right that the deal prices Anthropic about where they trade on sales, it’s the better deal on growth, even with no profit yet.
Of course, compute costs grew faster than revenue last quarter. If that keeps up, Goldman’s 2030 date for free cash flow could slip. Anthropic’s expected Nov. 19 debut will show what the market makes of it, and Broadcom’s Dec. 9 report will show whether its fiscal 2027 outlook still holds.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!