Key Takeaways
- Anthropic’s stock closed Friday 20% below its debut-day open, a hit to Amazon’s stake of about 15% and Alphabet’s 13.7%.
- Gil Luria says Anthropic drove all of the recent acceleration in AWS and Google Cloud, which makes it a risk to both companies’ revenue growth.
- Anthropic’s cash covers next year’s commitments, so the real risk is that its spending grows more slowly.
- A data-center builder that borrows heavily has the same exposure with less room for error, and Amazon’s and Alphabet’s fourth-quarter reports are the next test.
Anthropic (ANT) gave back most of its first-day pop in two sessions. The stock opened at $111.50 on Thursday, 34% above its $83 IPO price, and closed Friday at $88.91.
That slide matters to Amazon (AMZN) and Alphabet (GOOG). Per Anthropic’s S-1, Amazon owns about 15% of Anthropic after the IPO and Alphabet owns 13.7%.
On Wednesday’s episode of CNBC’s Fast Money, D.A. Davidson’s Gil Luria put Amazon and Google at the top of the list of companies tied to Anthropic, because “the entire acceleration in AWS and Google Cloud has come from Anthropic.”
Whether the AI labs can keep paying for more compute matters to CoreWeave (CRWV) too, since it borrows heavily to build data centers for them.
Much of the growth comes from one customer
Analysts expect Amazon’s revenue growth to pick up, from 12% in 2025 to 16% this year and next, and 17% in 2028:
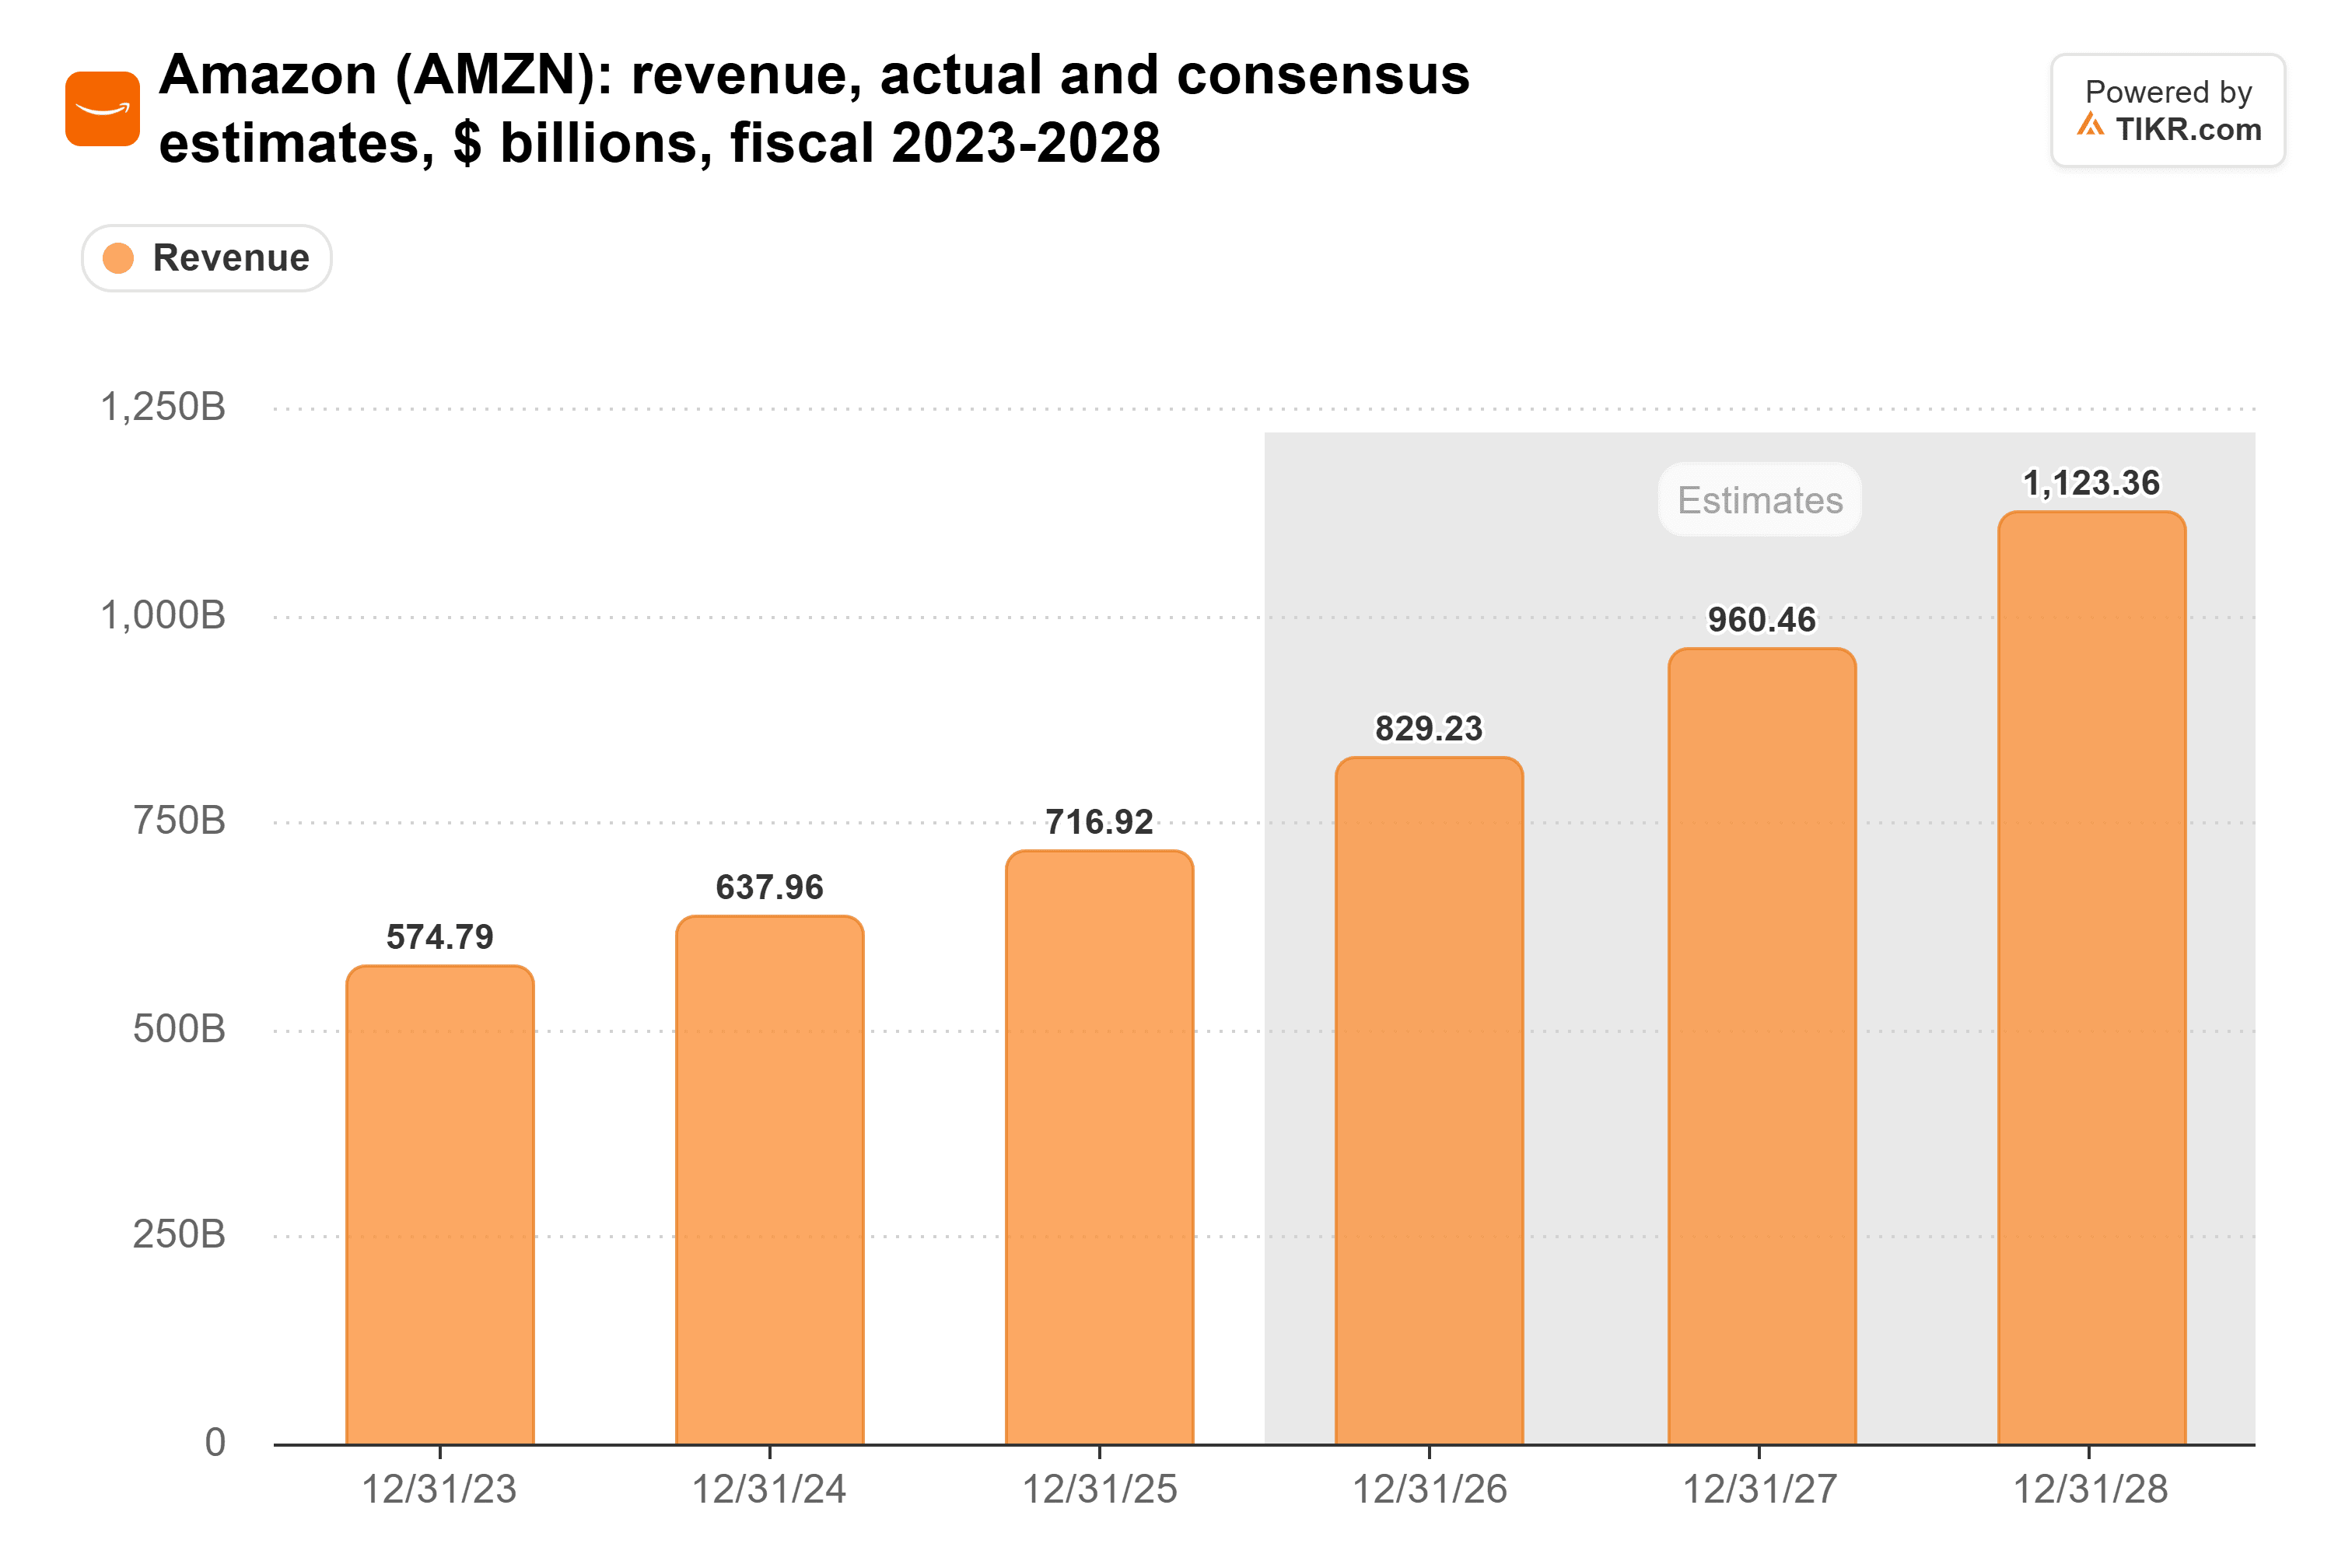
AWS revenue grew 37% in the second quarter, against 17% a year earlier. In that same quarter, Anthropic added more than $100 billion of AWS commitments over 10 years, per Amazon’s 10-Q.
Analysts see an even steeper climb at Alphabet, from 15% revenue growth in 2025 to 24% this year and 27% in 2027:
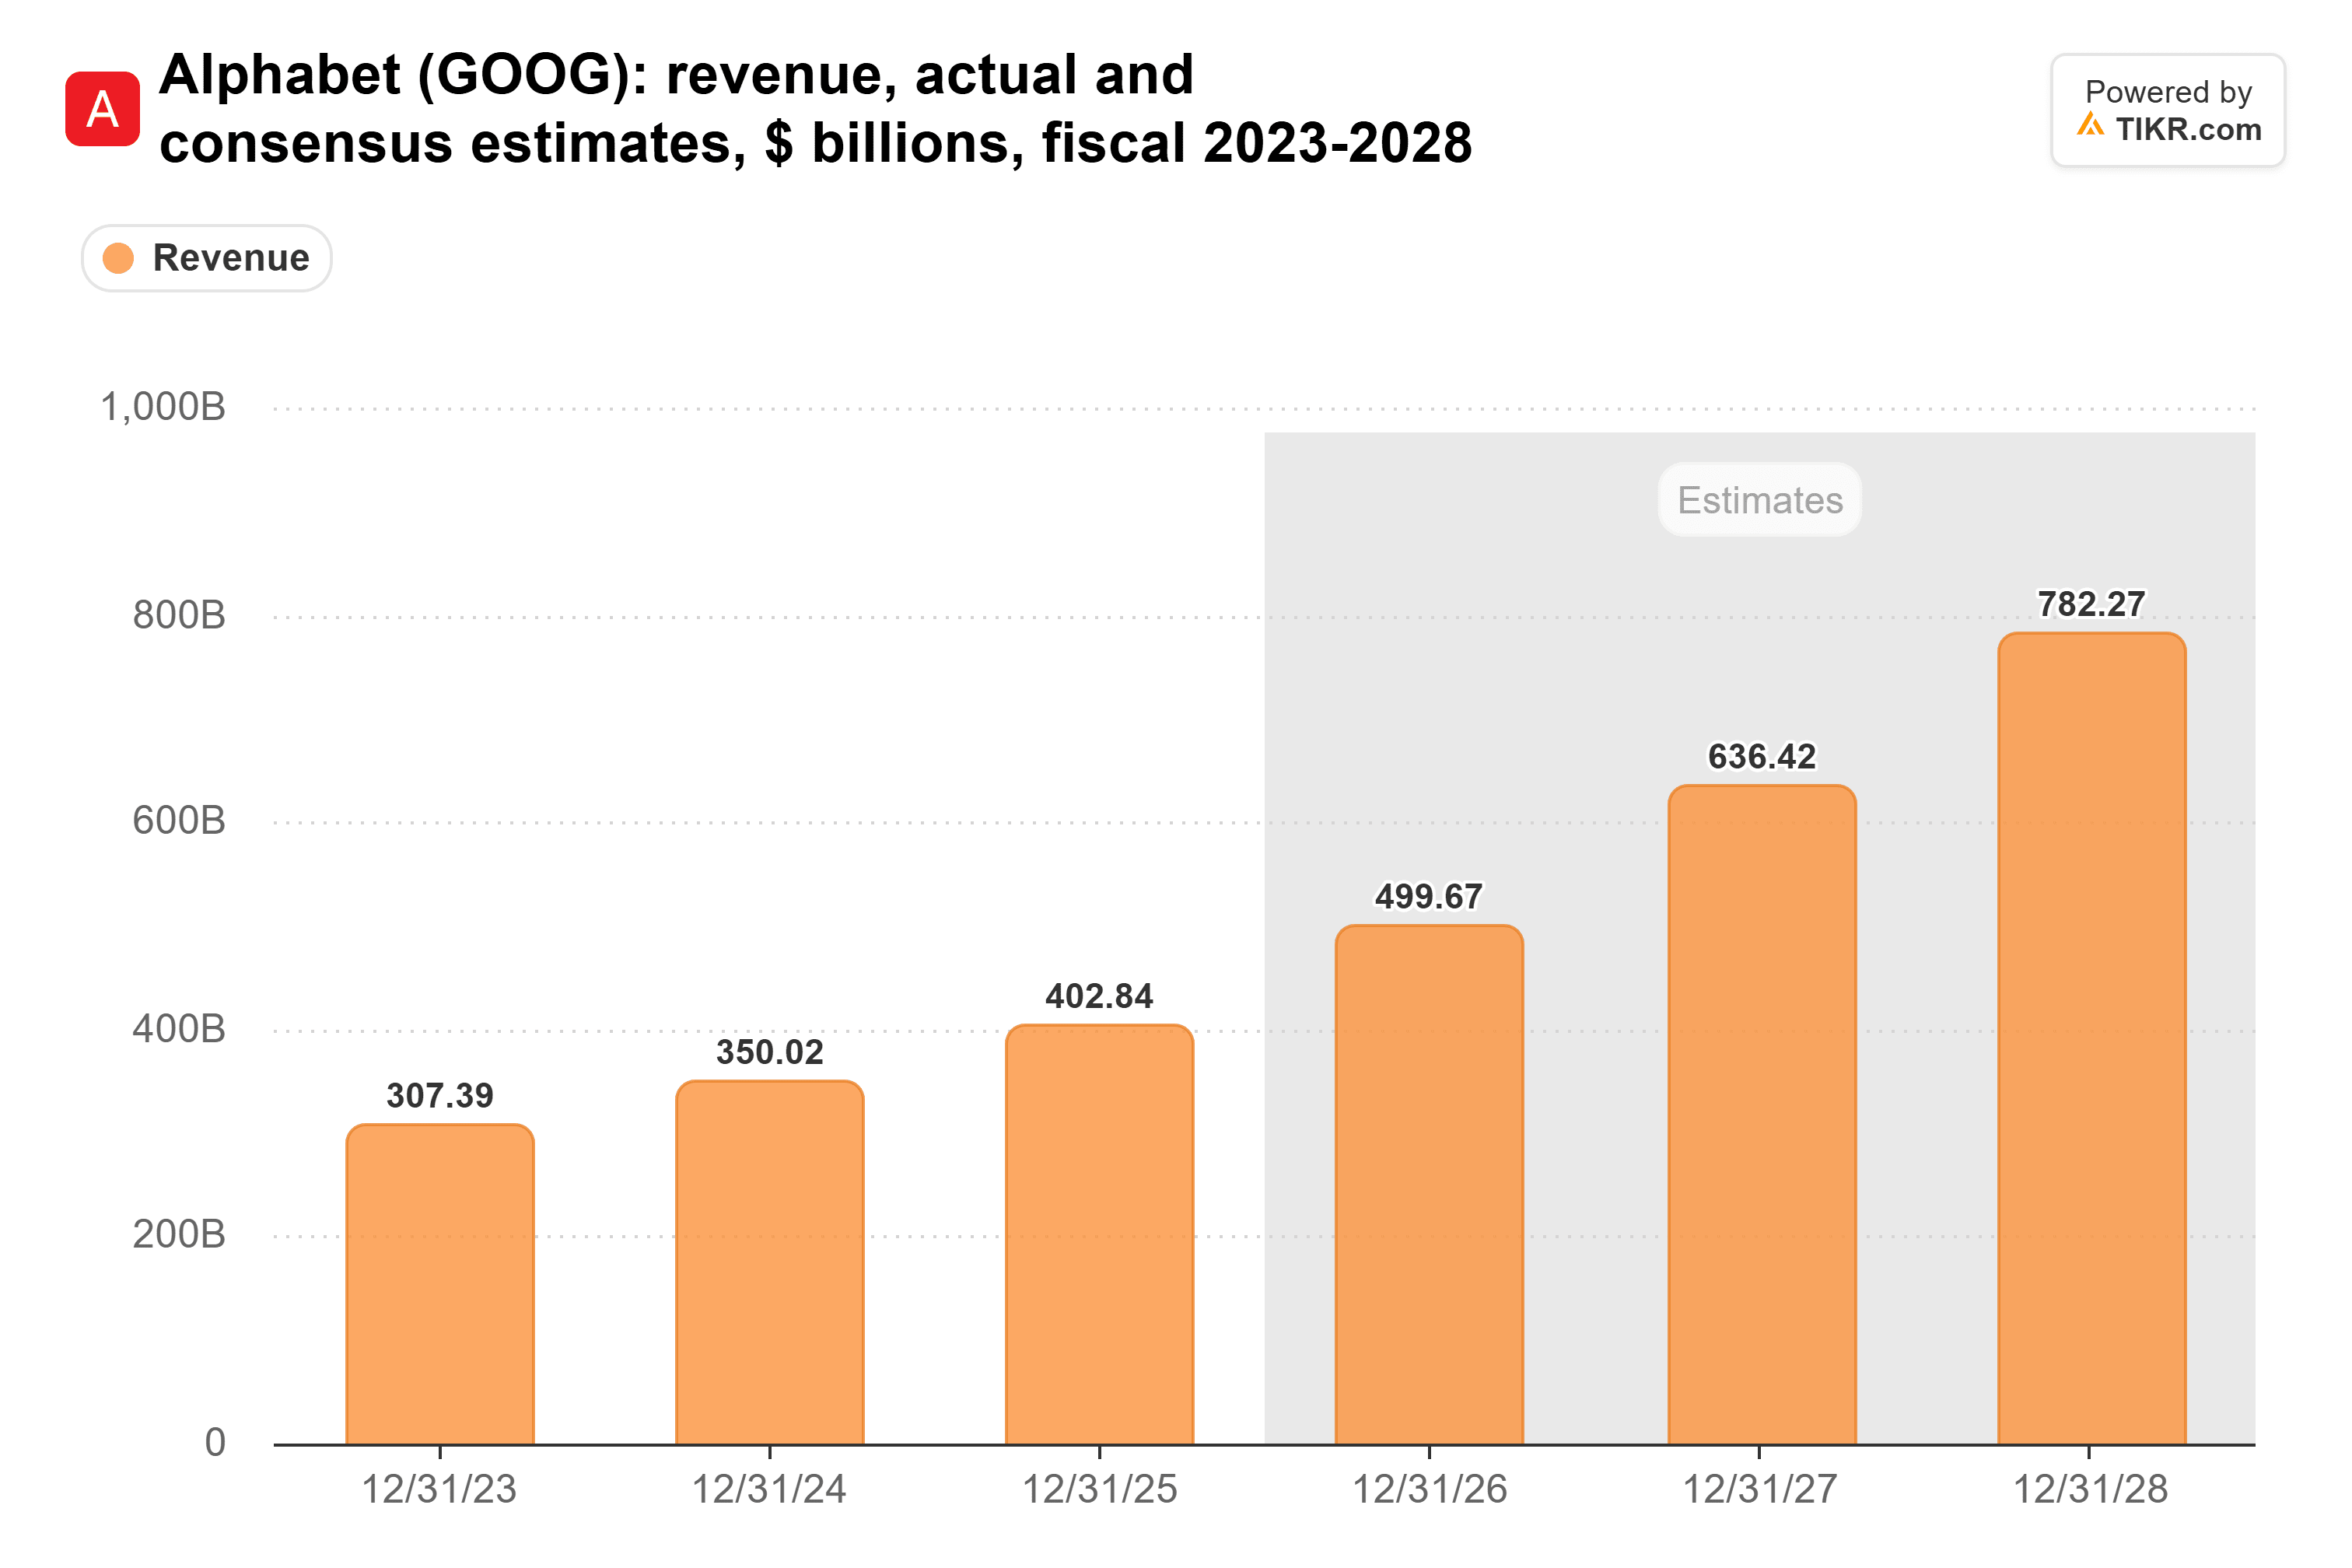
Not all of that comes from Google Cloud. But by one tally of Anthropic’s deals posted on X, Anthropic has committed at least $121.3 billion to it.
TIKR tracks 8 analysts on Anthropic. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Anthropic, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Anthropic’s Analyst Ratings
Amazon has already paid for the capacity
Amazon is spending ahead of that demand. Its free cash flow fell to $7.7 billion in 2025, from $32.9 billion in 2024:
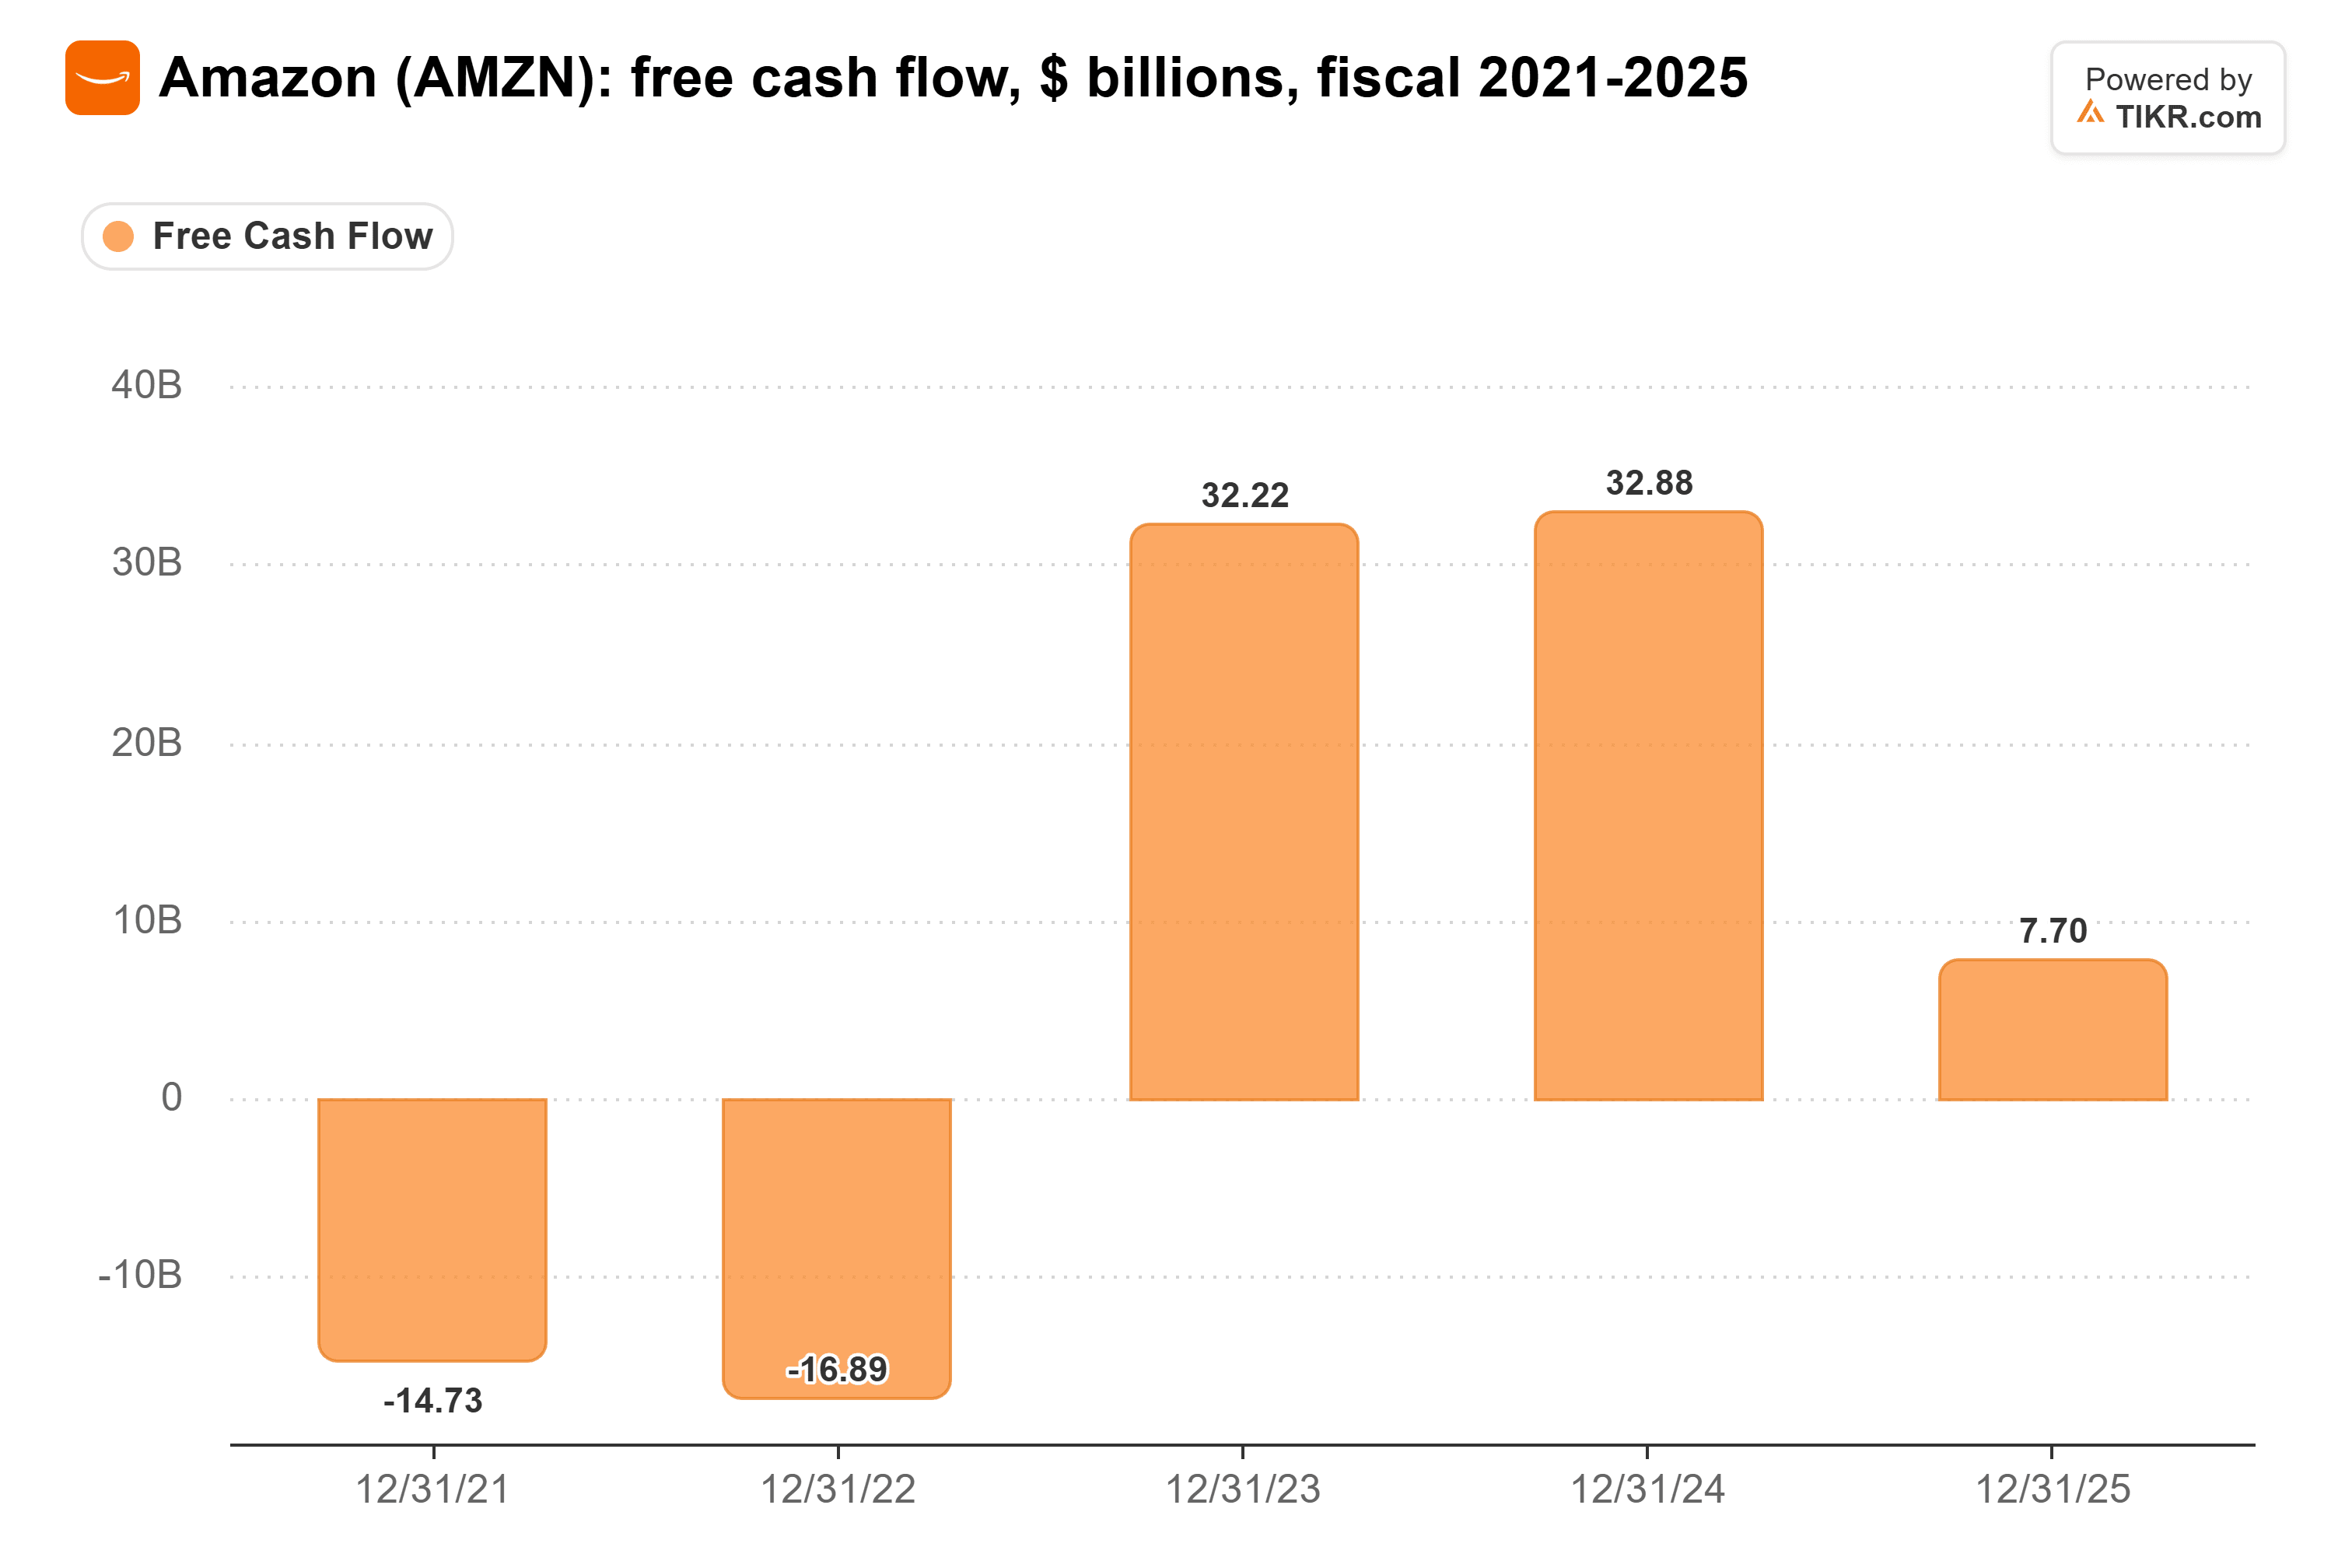
Over the twelve months to June, it turned into a $7.6 billion outflow. Management expects about $220 billion of capital spending this year.
Amazon is also lending Anthropic part of what it spends on AWS. Per Amazon’s 10-Q, $15 billion remained at June 30 on a $20 billion facility that becomes available to Anthropic as AWS delivers compute. If Anthropic slows its buying, Amazon is left holding capacity it has already paid for.
Anthropic has to keep buying more
Anthropic can cover what it owes in the near term. On Bloomberg Tech, Bloomberg’s Michael Regan put its spending commitments at “about $900 billion in future years, $71 billion due next year.” Against that, Anthropic had more than $130 billion of cash and investments before an IPO that raised $81.3 billion.
But Amazon’s and Alphabet’s forecasts need Anthropic to keep adding commitments. Goldman Sachs analysts don’t expect it to turn cash-flow positive until 2030, as Bloomberg reported. So Anthropic will keep needing investors’ money, and a falling stock makes that money more expensive.
CoreWeave has less room for error
CoreWeave sells to the same AI labs, and it carries far more debt. In its third-quarter release, interest expense of $846 million was about 4x its $207 million of GAAP operating income. CEO Michael Intrator expects about $9 billion of customer prepayments and deposits in the next three months, which help pay for the build, so a lab that pulls back would hit CoreWeave’s funding as well as its revenue.
A real risk, if a slow one
Until AWS and Google Cloud show they can keep accelerating on other customers, I’d treat Anthropic as the biggest risk in both companies’ cloud businesses.
Amazon’s and Alphabet’s fourth-quarter reports in early February are the next test. If AWS grows at or above the second quarter’s 37%, with backlog rising on deals other than Anthropic’s, the growth is spreading.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!