Key Takeaways
- Alibaba stock fell 36.9% in the 12 months to Nov. 11. Spending on AI and quick commerce cut its fiscal 2026 normalized (non-GAAP) earnings per ADS 59%.
- DBS has a Buy rating and a $207 target on Alibaba, 104% above the Nov. 11 close of $101.52.
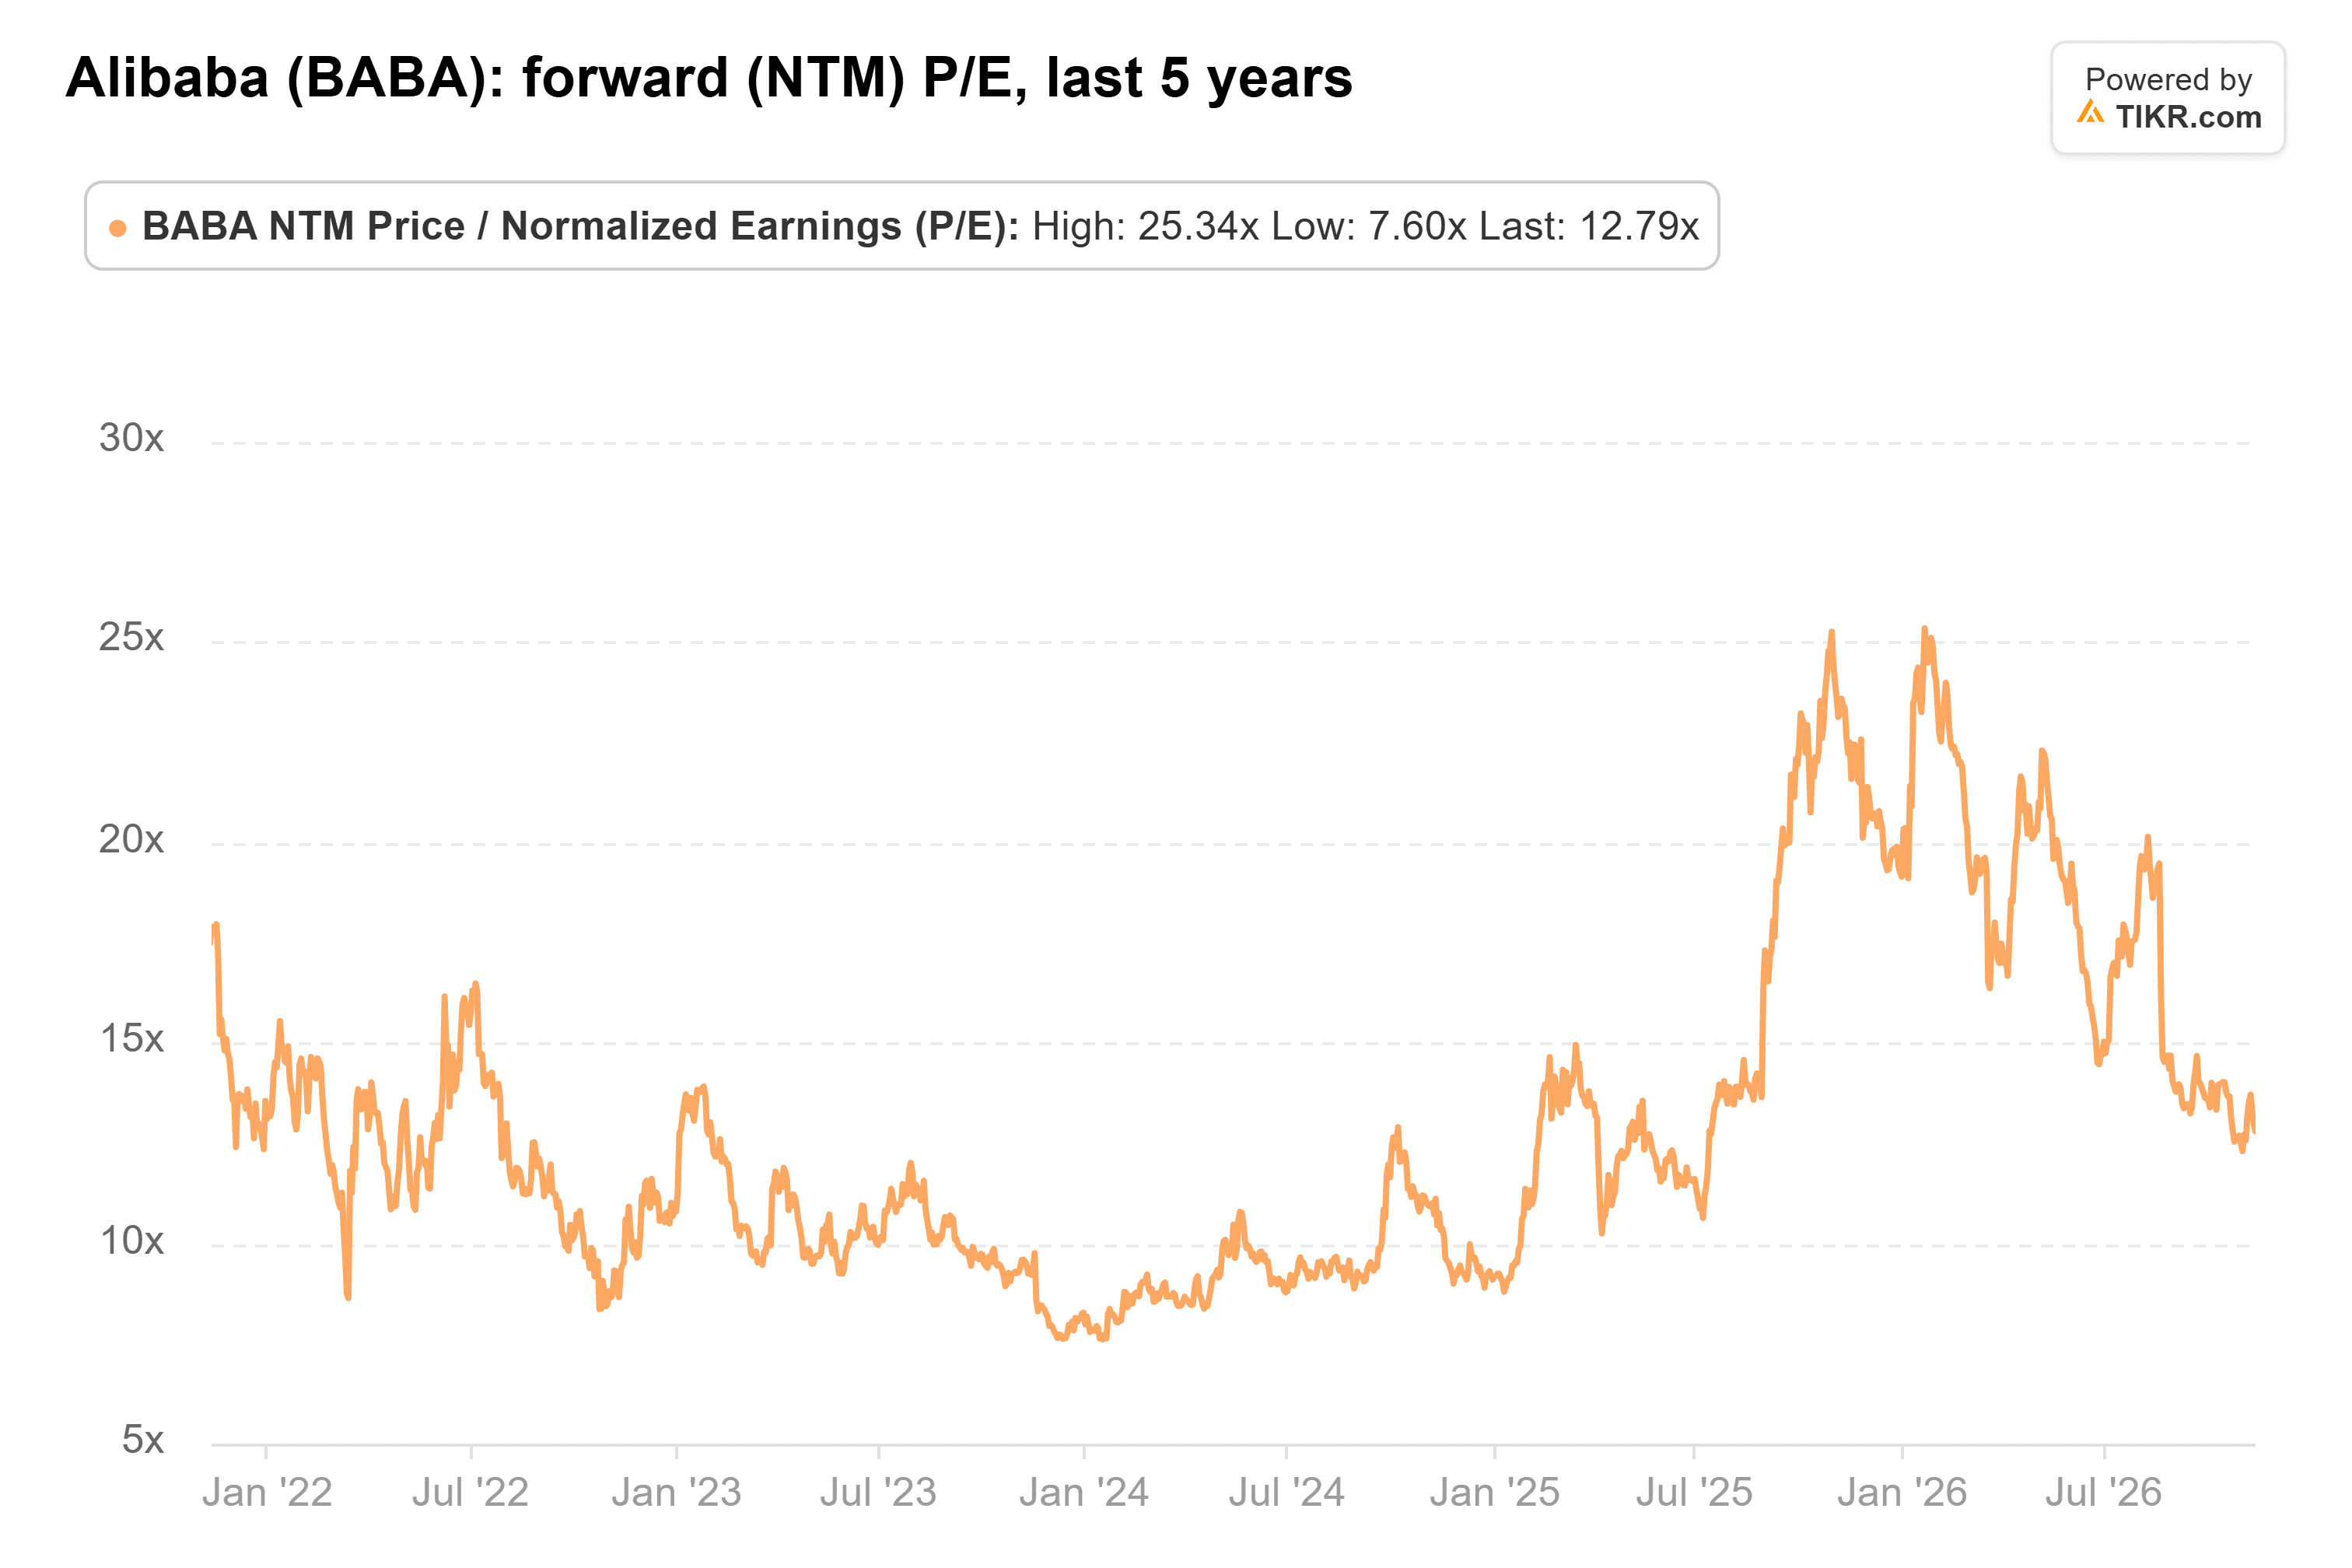
- Measured on the earnings analysts expect a year from now, $207 is about 19.6x, roughly 52% above Alibaba’s five-year average of 13x.
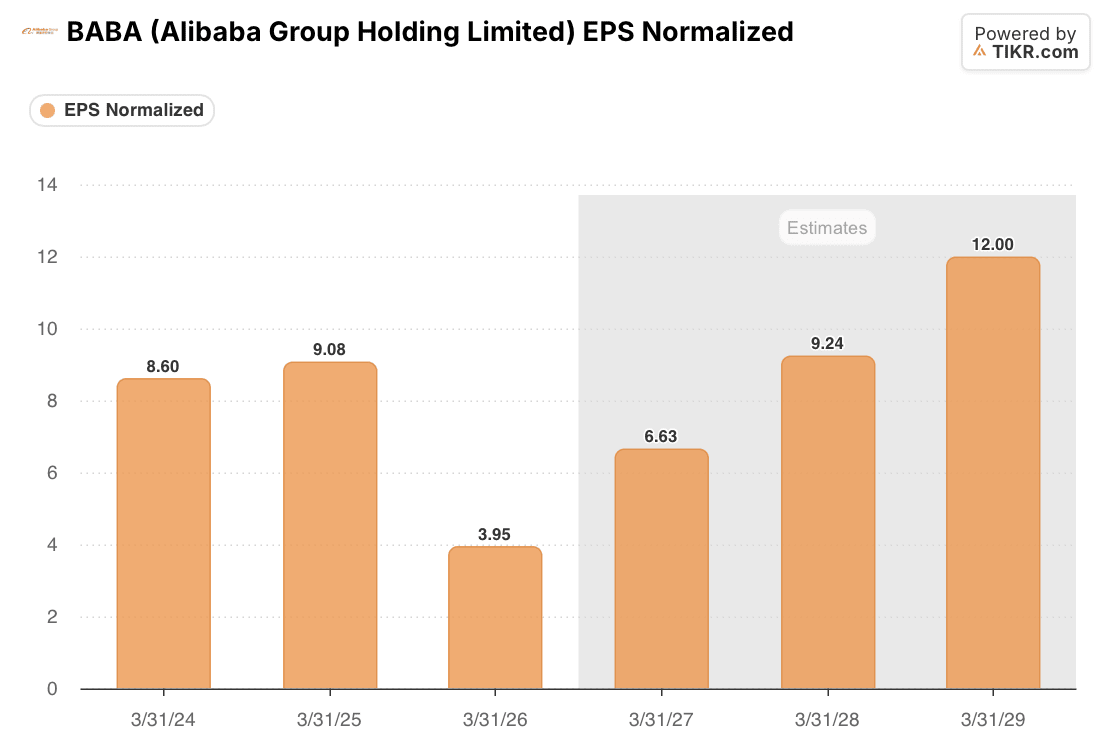
- Analysts expect earnings to more than double by fiscal 2028, and the Nov. 19 report is the next test.
Alibaba (BABA) stock fell 36.9% in the 12 months to Nov. 11, and DBS still sees it more than doubling. Its $207 target sits 104% above that day’s $101.52 close.
Over that stretch, Alibaba’s spending on AI and quick commerce cut deep into its earnings. Supply is a problem too: Chinese buyers, Alibaba among them, are still waiting on chips from Nvidia (NVDA).
Spending First, Profits Later
Capital spending jumped to RMB 126.1 billion (about $18.3 billion) in fiscal 2026 (the year ended March 2026), from RMB 32.1 billion two years earlier. Its push into quick commerce ate into profits too, and normalized earnings fell 59% in yuan terms, to RMB 26.80 per ADS.
The June quarter brought no relief: adjusted EBITA fell 30%, and free cash flow was an outflow of RMB 44.7 billion (about $6.6 billion).
On Nov. 4, Bloomberg reported that Chinese tech companies, Alibaba among them, have ordered about 6 million Nvidia RTX Pro 5500 chips but expect only about 1% of them over the next four months.
DBS’s $207 Rests on Two Businesses
DBS analyst Andy Yu kept his Buy rating and raised his target to $207 in August, valuing Alibaba’s core commerce and cloud businesses separately.
The newest development is T-Head. On Nov. 10, Alibaba disclosed that Hong Kong’s exchange had let it proceed with a spin-off of its chip unit, which applied to list on Sept. 11. But Alibaba’s announcement calls the spin-off insignificant next to its total assets, revenue and net income, so T-Head won’t get the stock to $207 on its own.
TIKR Tracks 41 Analysts on Alibaba. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alibaba, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alibaba’s Analyst Ratings
Analysts Expect Alibaba’s Earnings to Rebound
Analysts’ average target is $184, down from $198 at the end of 2025. They expect normalized earnings of $6.63 per ADS in fiscal 2027, $9.24 in fiscal 2028 and $12.00 in fiscal 2029:
At 13x forward earnings, the stock trades right at its five-year average, well below the 25x it reached in January:
What $207 Asks of Alibaba Stock
A 12-month target is a price one year out, so it should be set against the earnings expected a year from now, which analysts put about a third above today’s forward estimate. On that basis, $207 is about 19.6x, roughly 52% above Alibaba’s usual multiple. That’s below January’s peak, but it still needs a re-rating on top of the rebound.
The risk is cash: analysts expect capital spending to rise to RMB 198.4 billion (about $30 billion) in fiscal 2027 and free cash flow to stay negative.
What Alibaba’s Nov. 19 Report Needs to Show
At 13x, Alibaba is priced at its usual multiple, on earnings that analysts expect to more than double from fiscal 2026 to fiscal 2028. That’s a fine reason to own it. But reaching $207 within a year takes that rebound plus a multiple near 20x, and I wouldn’t count on both.
On Nov. 19, external cloud growth above June’s 45% and a smaller loss in AI Labs and Applications than June’s RMB 13.9 billion (about $2.0 billion) would keep the rebound on track.
So What Is Alibaba Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alibaba could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!