Key Takeaways
- Airbnb’s third-quarter revenue grew 19% to $4.87 billion, its fastest growth in more than three years.
- CEO Brian Chesky credits AI. He says it handles 40% of support tickets and helps Airbnb ship 75% more software with flat headcount.
- Booking Holdings and Expedia are also using AI to work more efficiently, so Airbnb’s real edge is growth: its nights booked rose 16%, against 7% at each rival.
- Analysts expect Airbnb’s revenue to grow faster than Booking’s through 2028, and Airbnb’s raised outlook gives little reason to cut those estimates.
Airbnb (ABNB) just posted its fastest revenue growth in more than three years, and its CEO knows what to credit.
Revenue rose 19% to $4.87 billion in the third quarter, beating estimates, and the stock jumped after Thursday’s report. That evening, Jim Cramer asked Brian Chesky on Mad Money what was behind the acceleration. Chesky said “execution and AI.” Then he went a step further:
“I think AI is the best thing that ever happened to Airbnb.”
That’s a bold line while investors are still sorting travel companies into AI’s winners and losers, Booking Holdings (BKNG) and Expedia (EXPE) included. And Airbnb’s quarter makes a pretty good case for it.
Airbnb is taking share
Chesky told Cramer the travel economy is “kind of stagnant or stable.” He put Booking’s and Expedia’s growth at 1% to 3% and 3% to 5%, against 16% for Airbnb’s nights and 19% for its revenue.
Booking’s 1% to 3% is the room-night growth it expects for the fourth quarter. In the third quarter, Booking and Expedia each grew room nights 7%. Airbnb’s nights and seats booked rose 16% to 155 million, more than twice as fast.
Analysts expect Airbnb to keep that lead. Consensus has its revenue rising 44% from 2025 to 2028, from $12.2 billion to $17.6 billion:

Booking is more than twice Airbnb’s size, and analysts expect its revenue to grow 28% over the same three years, to $34.3 billion:
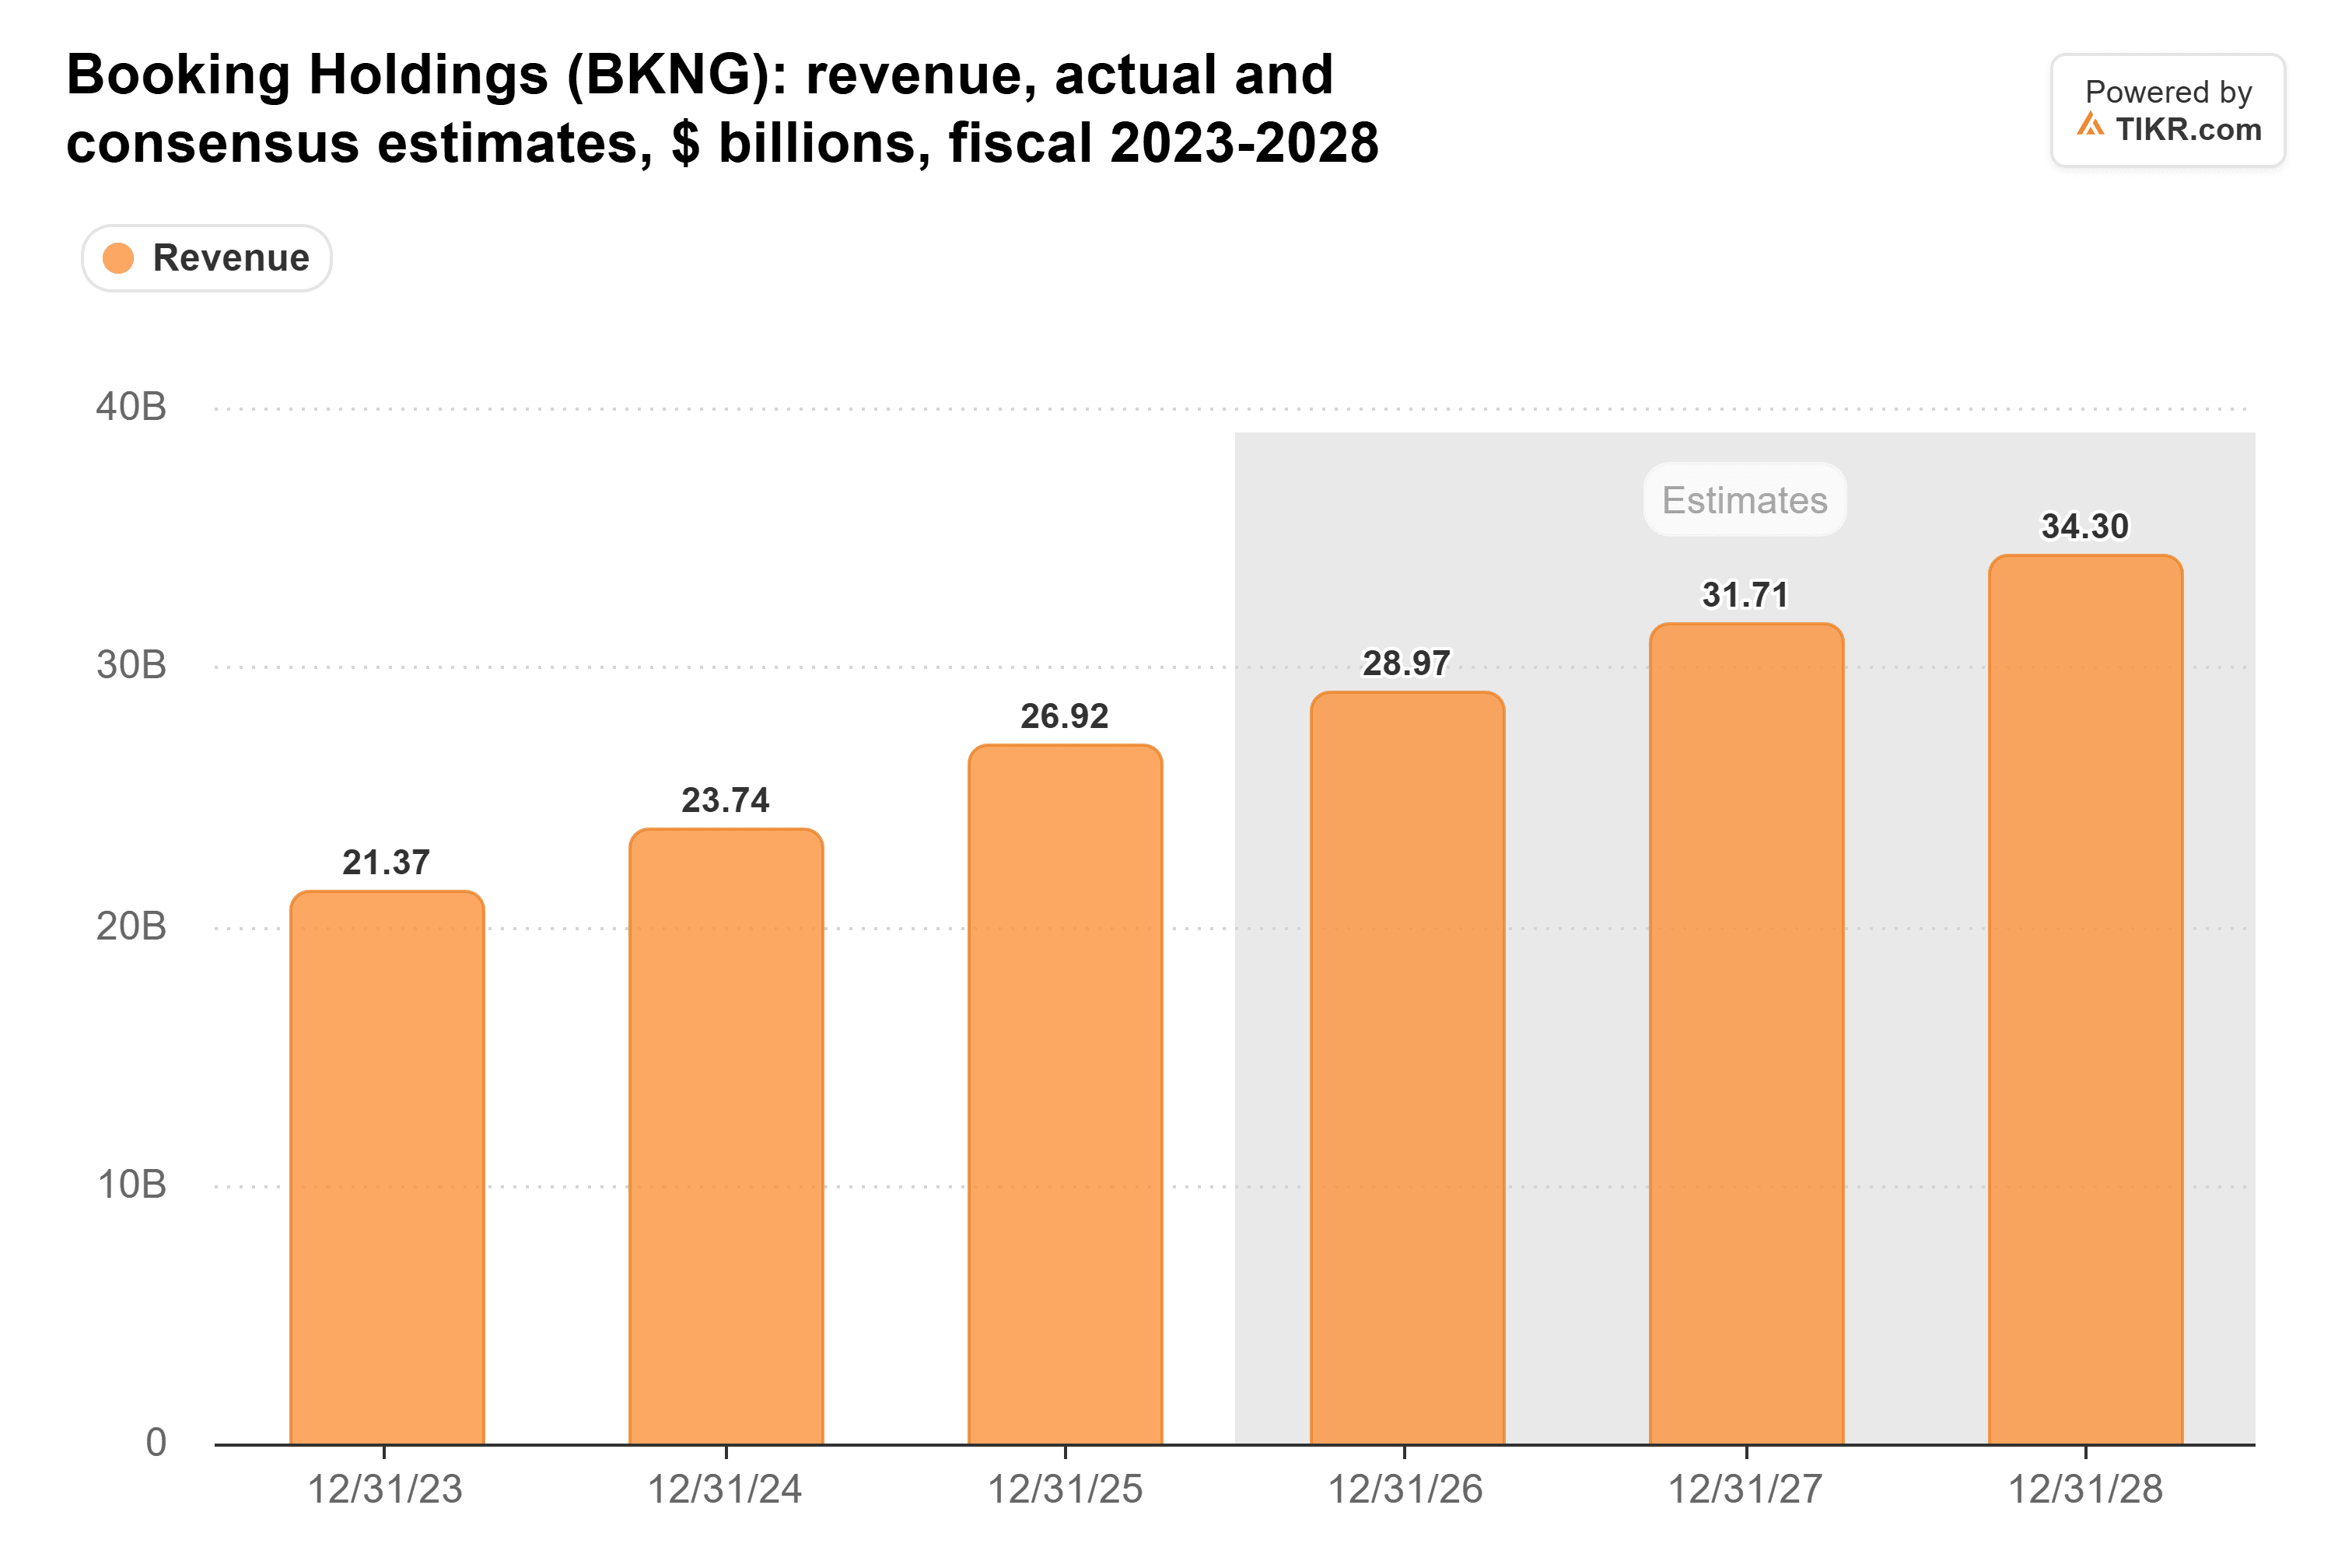
Airbnb now expects high-teens revenue growth for 2026, so nothing in this quarter makes me expect its estimates to come down.
TIKR tracks 44 analysts on Airbnb. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Airbnb, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Airbnb’s Analyst Ratings
AI is shrinking the support bill
Chesky says AI now handles 40% of Airbnb’s support tickets, “so, we have a 70% reduction in our cost of customer service.”
The 40% matches what Airbnb reported. In the third quarter, its AI assistant resolved about 40% of support issues without a person, up from a third in the second quarter. Airbnb’s own cost figure is smaller: support costs per booking fell more than 17% from a year earlier. My read is that Chesky’s 70% is the saving on the tickets AI handles, and the 17% covers the whole support bill.
He also says Airbnb ships 75% more software than a year ago, with headcount “pretty flat this year.” He added that the code “probably generated, you know, hundreds and hundreds of millions of dollars of incremental revenue this year.” That’s his own estimate, and outsiders can’t check it.
Airbnb’s operating margin slipped to 20.8% in 2025, down from 23.0% in 2024:

The third quarter of 2026 looked better. Net income grew 38% to $1.89 billion, twice as fast as revenue, and the adjusted EBITDA margin widened to 52% from 50% a year earlier.
Booking and Expedia have AI too
The AI savings aren’t Airbnb’s alone. Booking said on its third-quarter call this week that AI helped bring its customer service costs down even as bookings grew, and its stock jumped after that report. Expedia said on its own call that two-thirds of its bookings come direct, so AI search hasn’t pulled its travelers away so far.
Chesky’s answer to the disruption fear is that finding a place to stay is hard, and travelers want to look at photos and message hosts. “Most people don’t want to offload it to an agent,” he said.
So AI is helping all three companies run leaner. Airbnb is the one growing more than twice as fast while it does.
Bottom line: Chesky’s 70% is generous, but his bigger point holds. Airbnb is taking share from Booking and Expedia with flat headcount and a falling support bill per booking. Of the three, it’s the travel stock I’d want to own right now.
Of course, Airbnb expects growth to slow to 16% to 18% in the fourth quarter. If travel demand turns down, it will need to keep taking share in a shrinking market. Its fourth-quarter report, likely in February, should tell us whether those gains hold.
So what is Airbnb stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Airbnb could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!