Key Takeaways
- Shopify fell as much as 17% today after its third-quarter GMV came in just under what analysts expected, and Adyen is down 42% this year.
- Apart from the GMV miss, Shopify’s quarter was solid: revenue grew 32%, and its fourth-quarter outlook beat what analysts expected going in.
- Adyen trades at about 18x expected 2027 earnings and Shopify at about 57x, though analysts expect Shopify’s earnings to grow faster.
- At these prices Adyen is the better buy, but it has to stop cutting its margin outlook.
Shopify (SHOP) fell as much as 17% this morning after its third-quarter report, even though revenue grew 32% and its fourth-quarter outlook came in ahead of what analysts expected.
That puts it in the same boat as Adyen (ADYEN), the Dutch payments company that’s down 42% this year. Both still grow revenue by more than 20% a year. After their selloffs, though, Adyen costs about a third as much as Shopify per dollar of expected 2027 earnings.
So which is the better buy?
The miss was small
The miss came from GMV, which rose 29% to $119.1 billion. Analysts expected $120.1 billion, so Shopify fell short by less than 1%.
The rest of the quarter held up. Revenue of $3.74 billion roughly matched expectations. Operating income rose 66% to $568 million. Free cash flow was $816 million, a 22% margin, well ahead of the $723 million analysts expected going in.
Management also guided fourth-quarter revenue growth to a “low-thirties percentage rate.” Before the report, analysts had penciled in about 30%.
The weak spot is gross profit. It grew 28%, slower than revenue, and Shopify expects gross profit to grow at a “high-twenties percentage rate” in the fourth quarter too. Merchant solutions revenue grew 35% and subscriptions 20%, and the merchant side keeps far less of each dollar as gross profit.
Going into the report, analysts expected Shopify’s normalized EPS to more than double from 2025 to 2028:
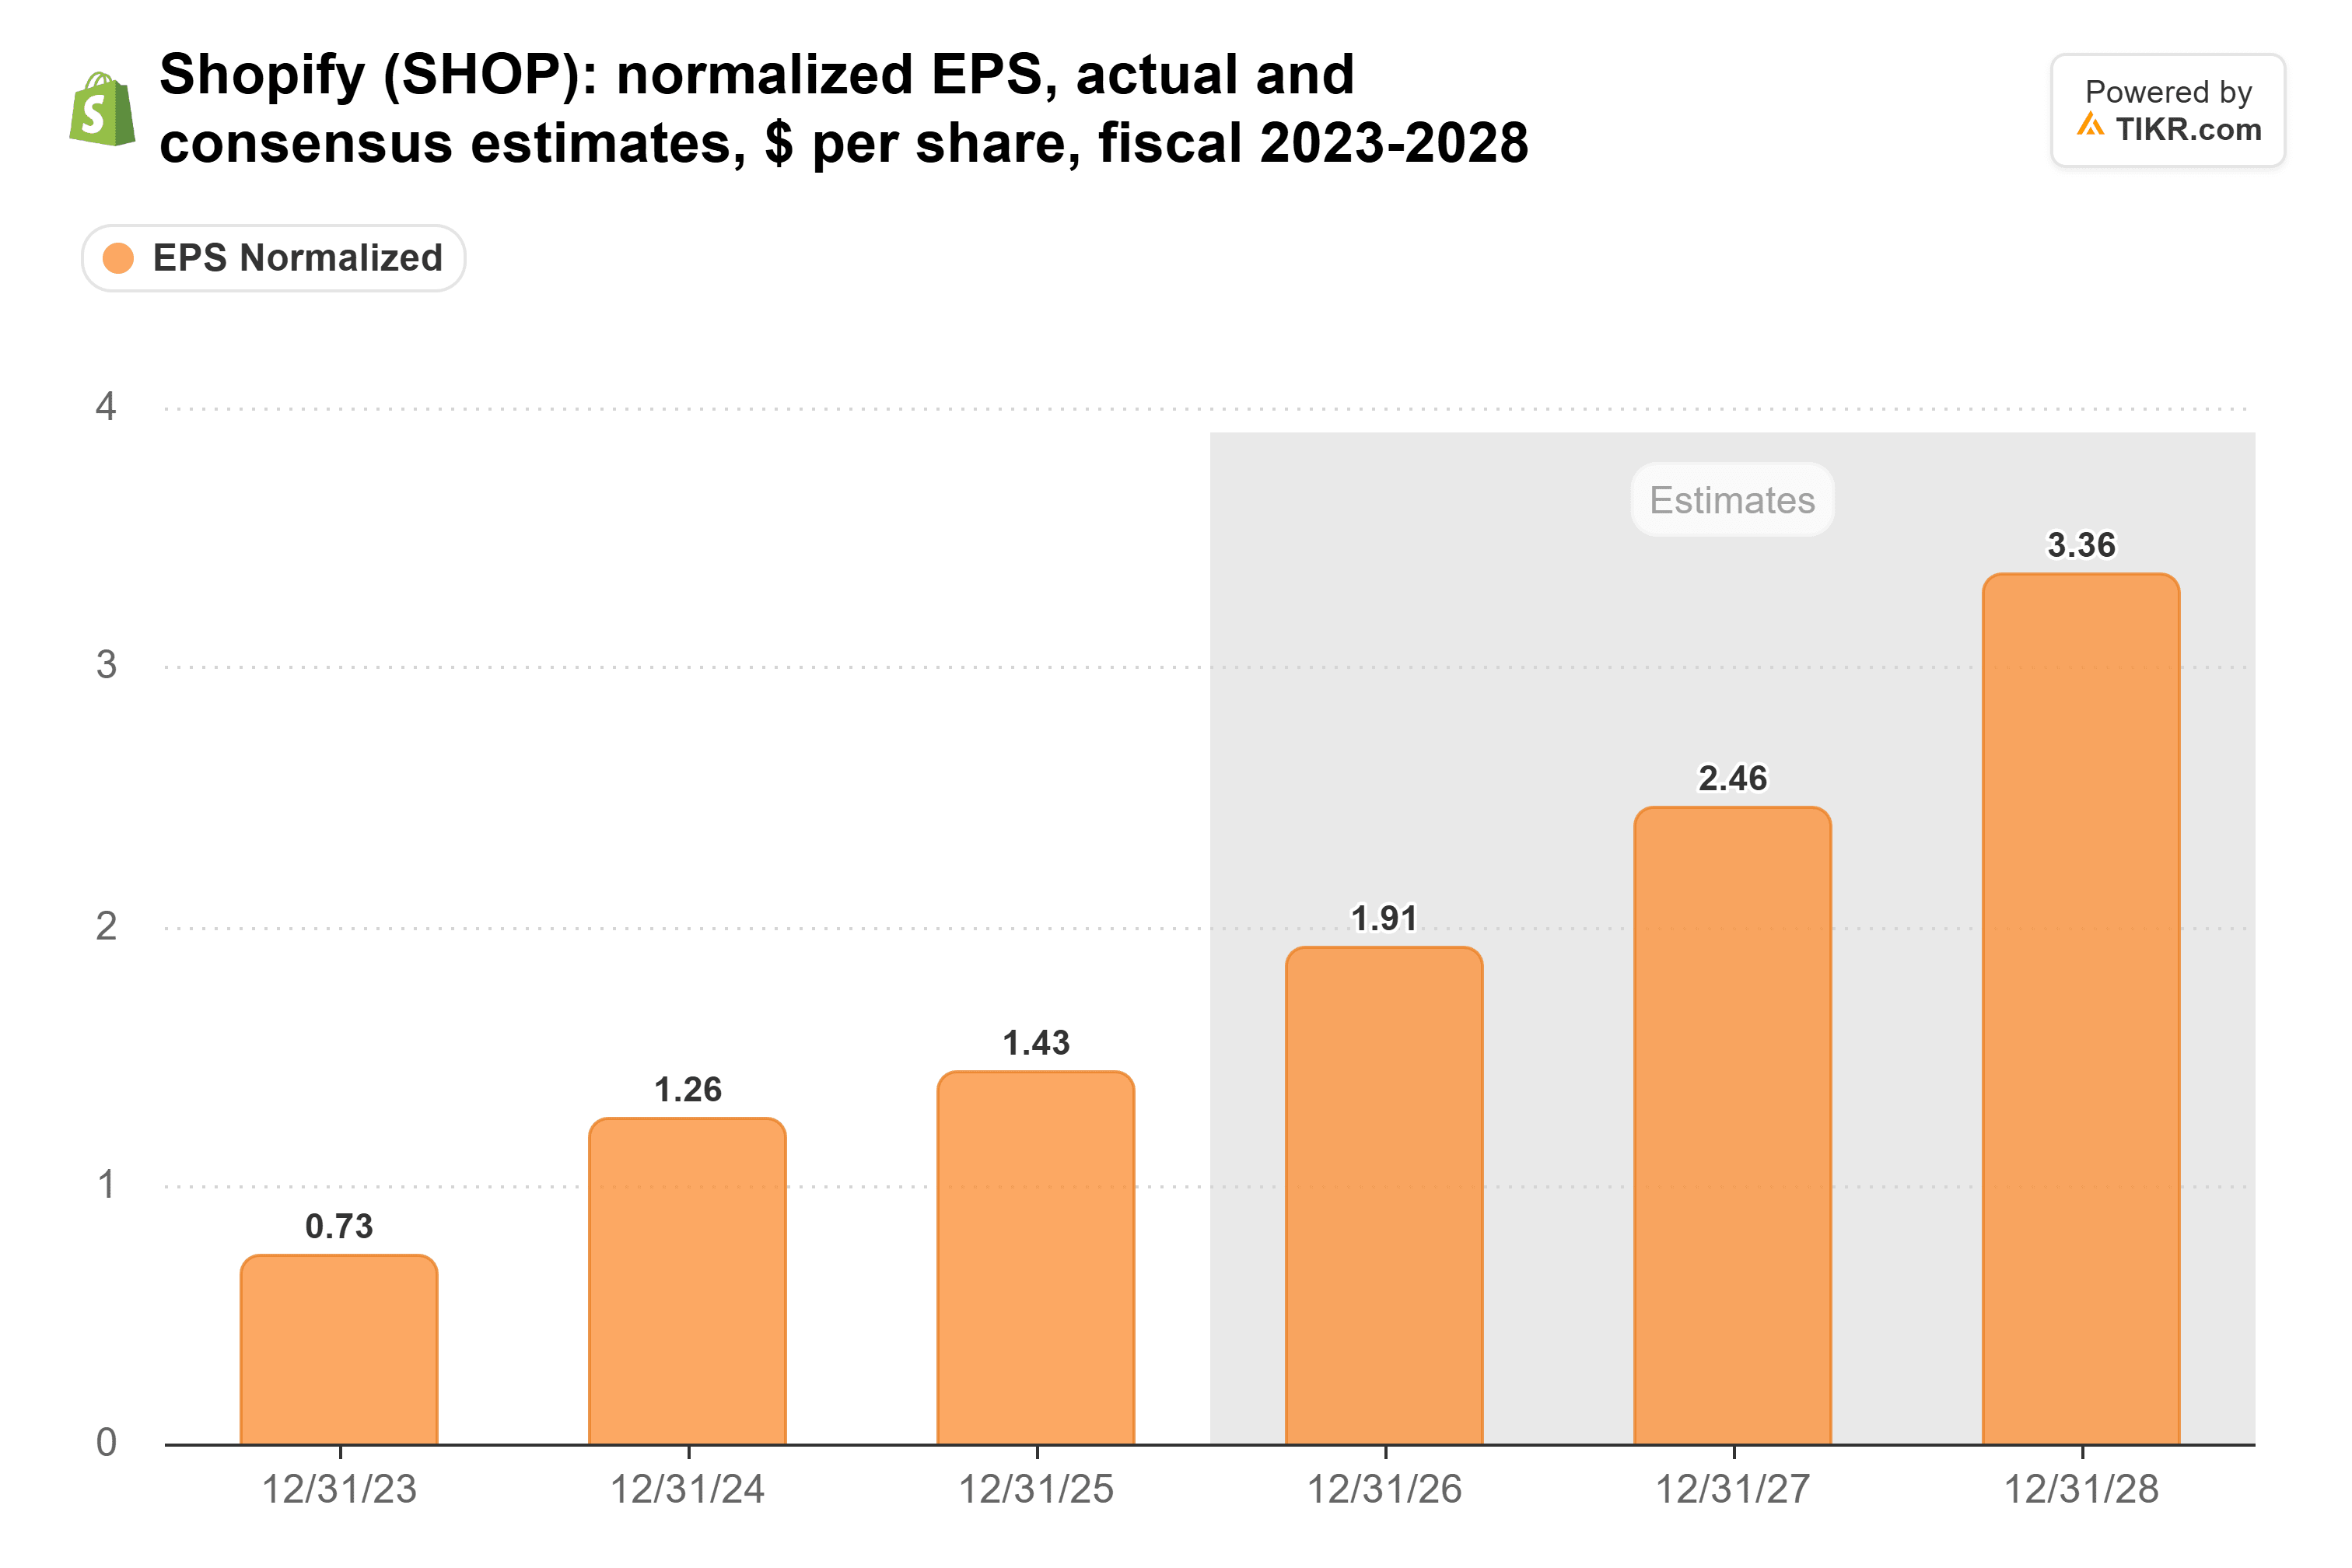
The fourth-quarter guide runs ahead of those estimates, so I don’t see a case for big cuts on the revenue side. Slower gross profit growth could trim the earnings line a bit.
TIKR Tracks 54 Analysts on Shopify. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Shopify, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Shopify’s Analyst Ratings
The catch is the price. At Monday’s close, Shopify traded at 74x forward earnings, right around its average since late 2023. Even at this morning’s price of about $141, it trades at about 57x what analysts expect it to earn in 2027.
Adyen’s problem is margins
Adyen knows Shopify’s merchants well. The two companies partnered in 2023 to offer Adyen’s payments to Shopify’s biggest merchants. Adyen’s own selloff has a different cause, though.
On Oct. 28, Adyen said third-quarter net revenue rose 23% to €738 million (about $828 million), or 22% in constant currency. It kept its 2026 growth outlook of 21%-23% in constant currency, which it had raised in August from the 20%-22% it set in February.
The trouble was the margin outlook. Adyen cut its 2026 EBITDA margin outlook to about 50%, from roughly 52% before and below the 53% it reported for 2025. TIKR’s measure, which treats some costs differently, puts 2025 at about 50%, and shows the margin has slipped before, from 61% in 2021 to 45% in 2023:

Investors have been here before. Adyen’s February outlook trailed expectations, and in August 2025 it walked back its growth outlook, blaming US tariffs. Adyen also trades in euros on Euronext Amsterdam, so a US investor’s return moves with the euro against the dollar. In euros, the stock is down 39% this year. In dollars, it’s down 42%.
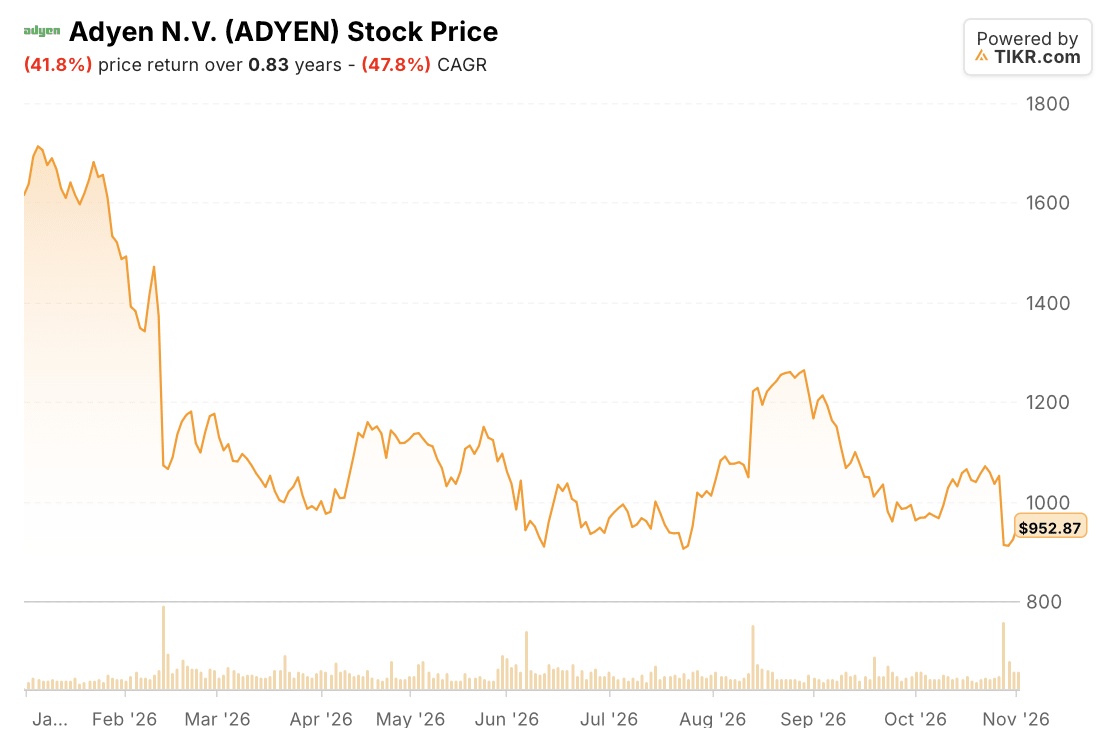
At this morning’s price in Amsterdam, Adyen trades at about 18x the €45.62 (about $51) analysts expect it to earn in 2027. Analysts expect EPS to grow 20% that year and 23% in 2028.
Adyen is the better buy at these prices
Analysts expect Shopify’s EPS to grow 29% in 2027 and 37% in 2028, against 20% and 23% for Adyen. Call it 1.5x Adyen’s growth rate, at about three times the price.
That’s too much to pay for the gap, so I’d take Adyen. It’s still growing net revenue in the low 20s and stood by its raised growth outlook last week. At 18x, the stock already prices in much of the margin pressure it announced at the same time.
Shopify has a real case too. Its checkout already handles orders from AI shopping agents. Its revenue growth has stayed above 30% for four straight quarters, and it turned 22% of its revenue into free cash flow this quarter. But at 57x, Shopify needs that growth to last for years. Adyen mostly needs to stop disappointing.
The risk with Adyen is that it keeps spending and its earnings estimates keep falling. It cut its margin outlook last week and dropped its 2028 margin goal.
Both companies report again in February: Adyen its full-year results, Shopify its fourth quarter. If Adyen’s growth slips below 20%, or Shopify’s gross profit starts keeping pace with revenue, I’d change my answer.
So what is Adyen stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Adyen could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!