Key Takeaways
- Adobe stock is down 30% this year, and Wells Fargo and HSBC both downgraded it in October.
- Adobe’s fiscal third quarter showed no sign of an AI slowdown: revenue rose 13% to $6.76 billion, and management raised its full-year targets.
- The warning signs are in the outlook: a fourth-quarter revenue guide below expectations, and a full-year target that Wells Fargo says needs a steep ramp in new recurring revenue.
- At 9.4x forward earnings against a five-year average of 23x, the stock looks cheap if Adobe delivers what analysts expect.
Adobe (ADBE) stock is down 30% this year, and October brought two downgrades on fears that AI is eating into its business.
That puts Adobe on the wrong side of an argument Scott Galloway made on The Prof G Pod on Nov. 2. In an episode asking whether AI is killing software, he said: “so far the market has said that the rumors of SaaS’s death have been greatly exaggerated.”
Adobe hasn’t gotten that benefit of the doubt. So did its last quarter give investors a reason to worry?
The quarter looked fine
In its fiscal third quarter, which ended Aug. 28, Adobe’s revenue rose 13% to a record $6.76 billion. That matched the second quarter’s pace and topped the 12% growth it posted in the first. Adjusted earnings per share climbed to $6.13 from $5.31, on an adjusted operating margin of about 44%.
Its AI-first annual recurring revenue grew more than 150%, and management raised its full-year revenue and earnings targets.
If AI is taking business from Adobe, it doesn’t show up here.
Analysts still expect revenue to keep climbing through fiscal 2028:

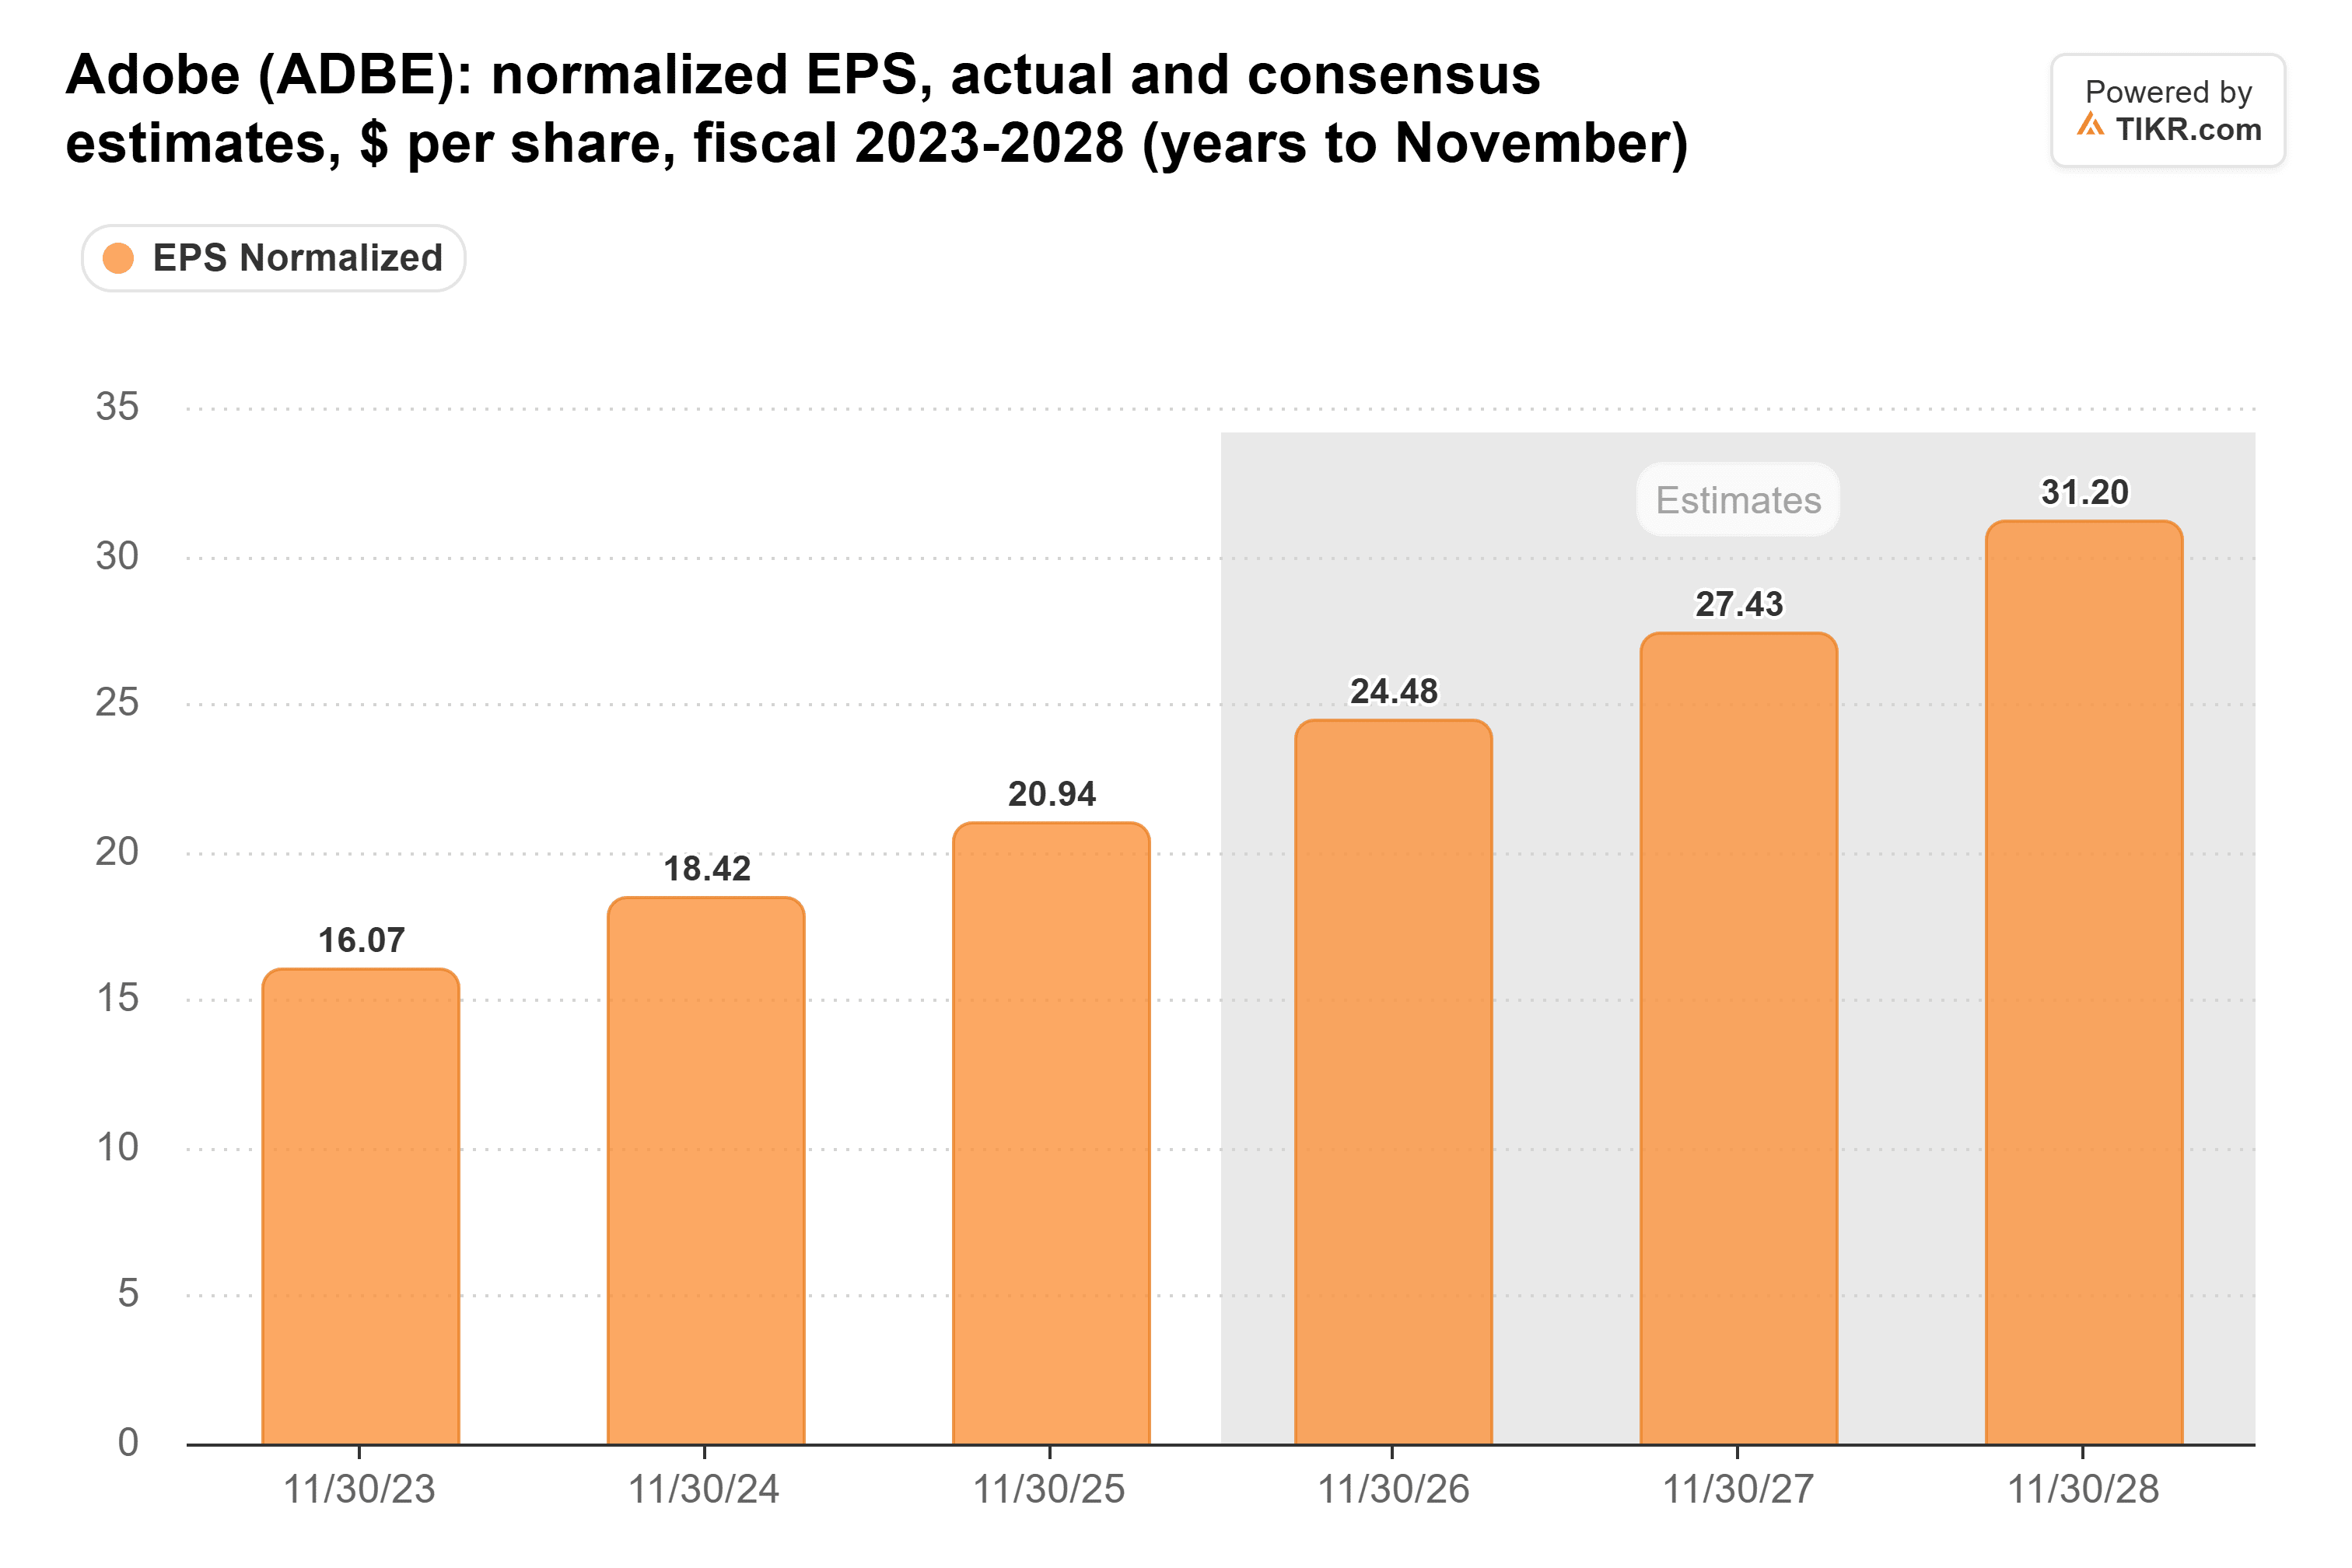
Growth cools from about 12% this year to 9% in fiscal 2027 and 8% in fiscal 2028, so some slowing is already built in. Earnings estimates hold up better, rising every year through fiscal 2028:
The warning signs are in the outlook
Adobe guided to fourth-quarter revenue of $6.80 billion to $6.85 billion, and the midpoint came in below what analysts expected.
Wells Fargo analyst Michael Turrin built on that when he cut Adobe to Underweight on Oct. 12, with a $225 target (down from $270). He said Adobe’s net new annual recurring revenue needs to roughly double from the third quarter to the fourth for the company to hit its full-year targets. He also argued that the Semrush acquisition is boosting reported growth while the core business grows more slowly. Wells Fargo’s survey of chief information officers, he added, showed Adobe losing share of AI budgets. And he flagged a management team in transition: Anil Chakravarthy takes over as CEO from Shantanu Narayen on Dec. 1, and the CFO is interim.
HSBC cut Adobe to Hold the next day, with a $267 target (down from $310). Rothschild & Co Redburn went further on Nov. 2, keeping its Sell rating and cutting its target to $140 from $270.
TIKR tracks 39 analysts on Adobe. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Adobe, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Adobe’s Analyst Ratings
Wells Fargo analyst Michael Turrin built on that when he cut Adobe to Underweight on Oct. 12, with a $225 target (down from $270). He said Adobe’s net new annual recurring revenue needs to roughly double from the third quarter to the fourth. He also said Wells Fargo’s survey of chief information officers showed Adobe losing share of AI budgets. And he flagged a management team in transition: Anil Chakravarthy takes over as CEO from Shantanu Narayen on Dec. 1, and the CFO is interim.
HSBC cut Adobe to Hold the next day, with a $267 target (down from $310).
Only the multiple has cracked
With estimates still rising, this year’s drop has come from what investors will pay for Adobe’s earnings. Its forward P/E is near the bottom of its five-year range:
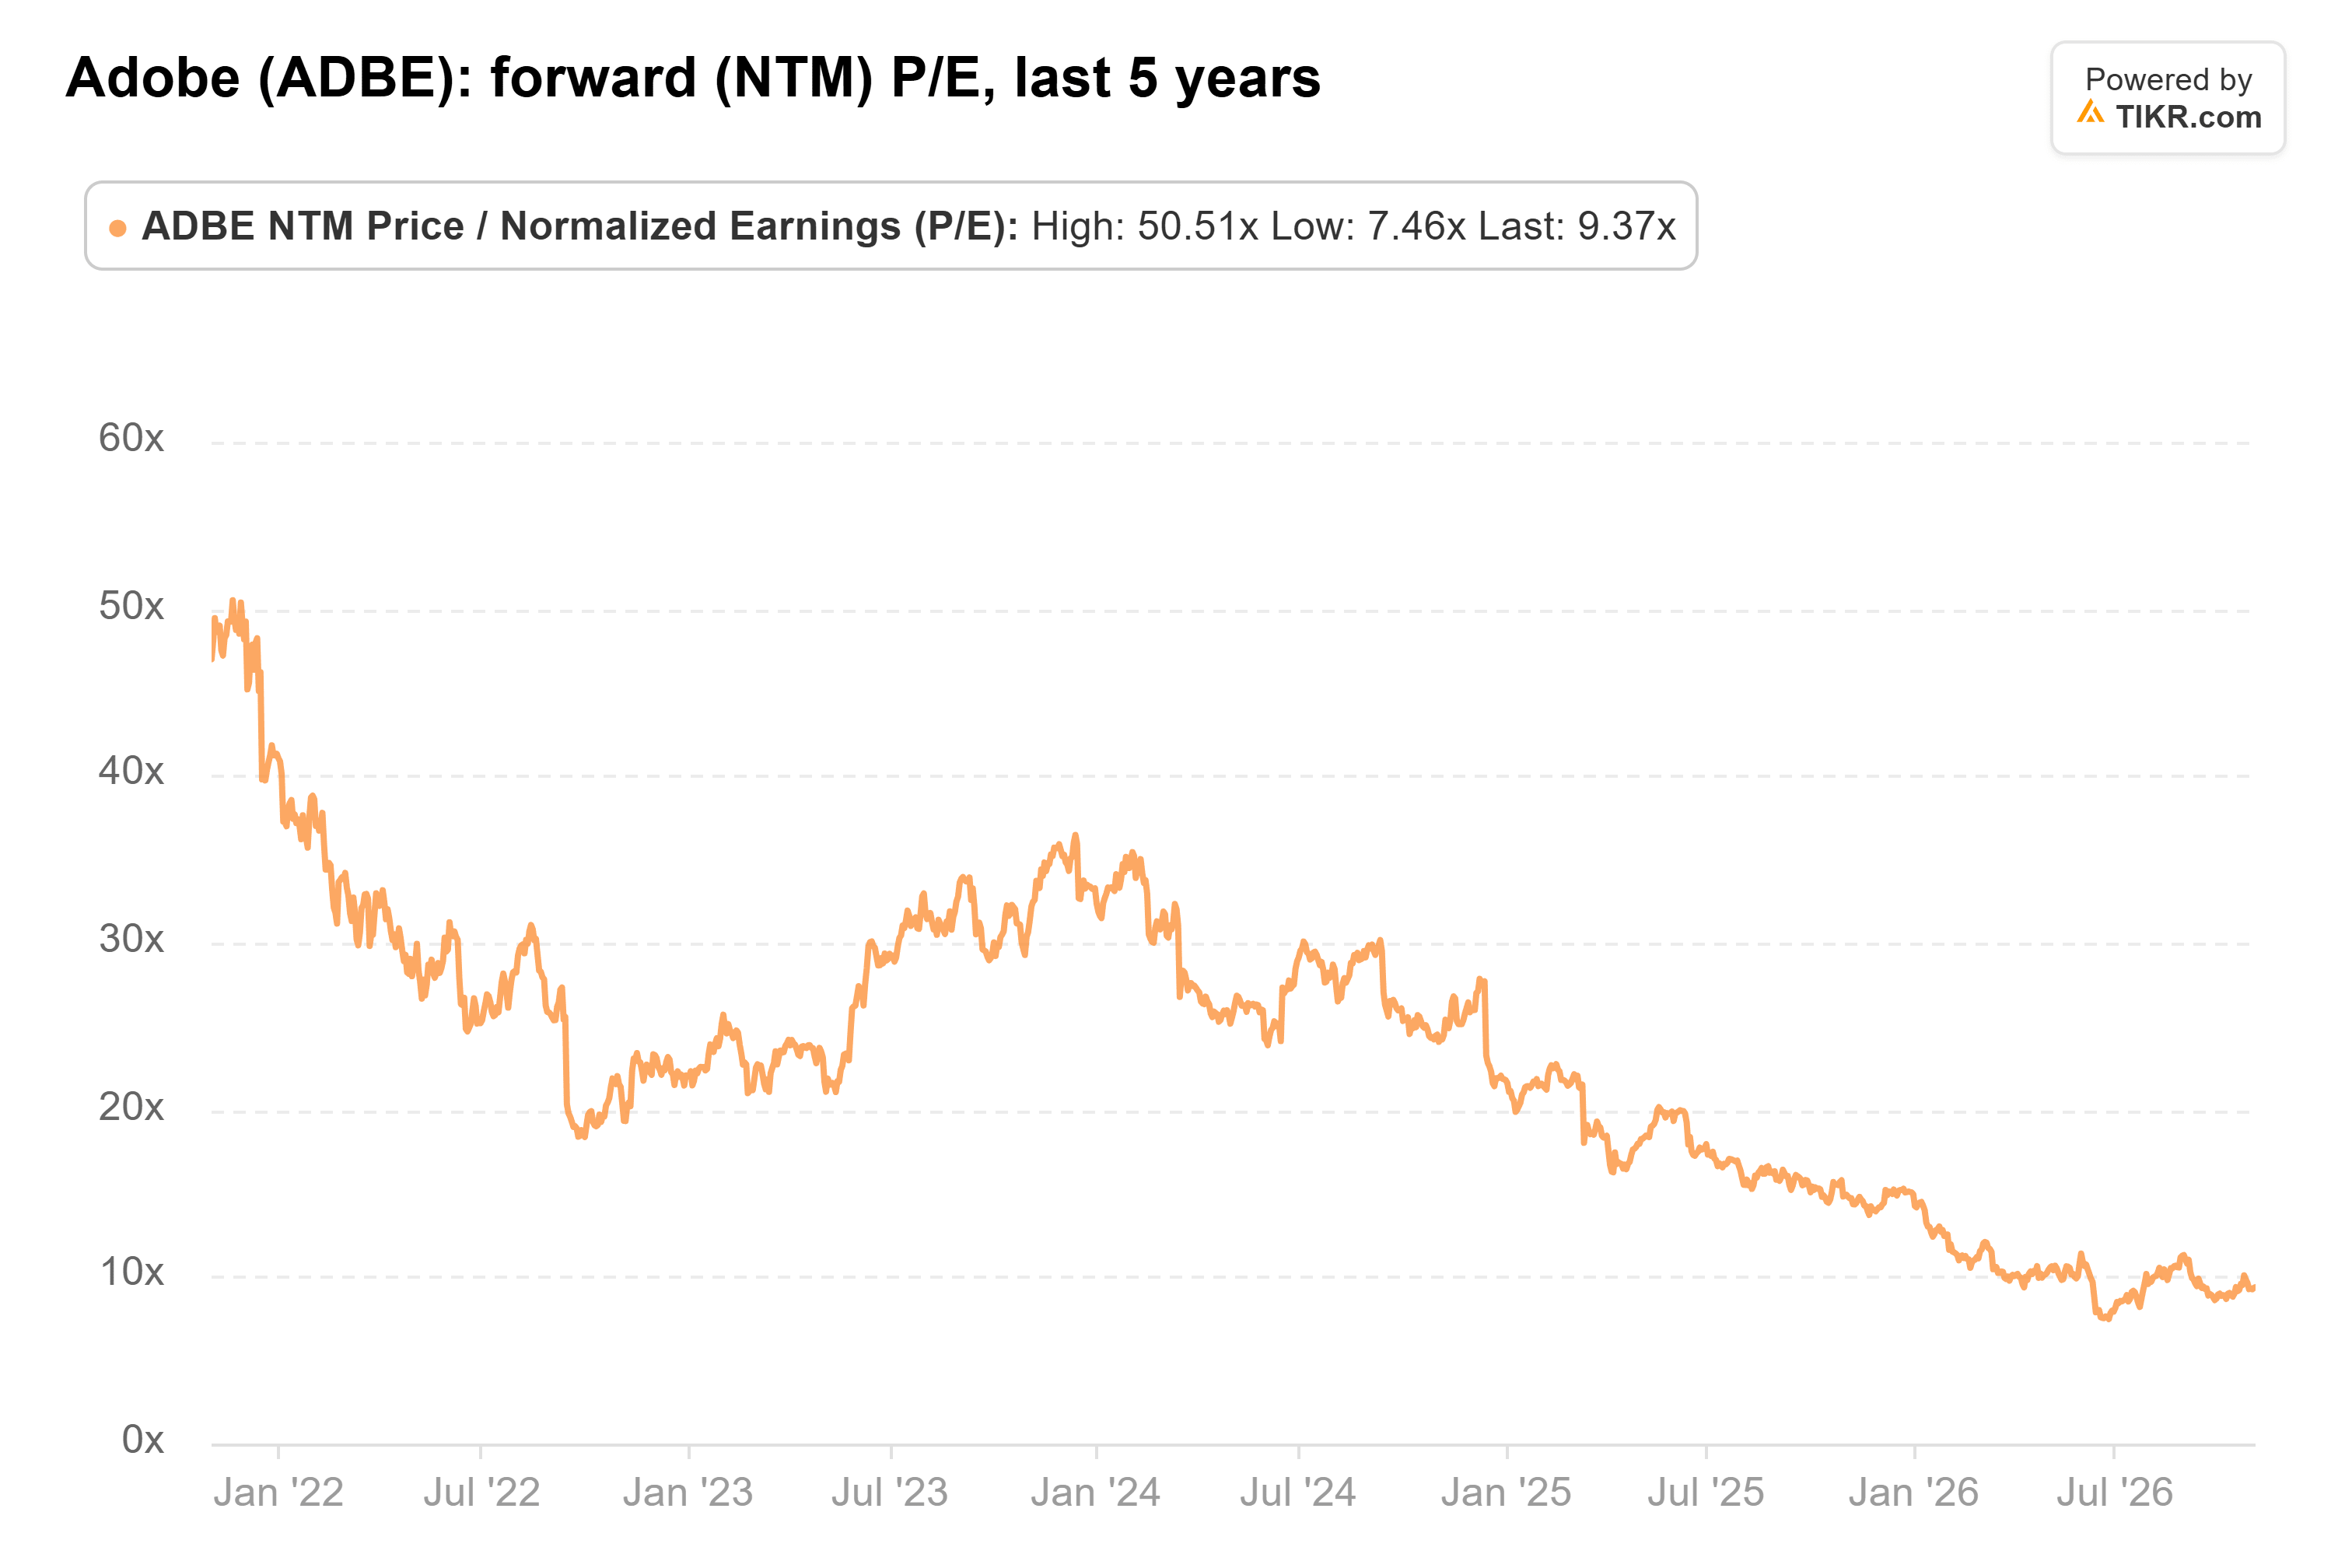
At 9.4x as of Nov. 2, it’s far below its five-year average of 23x. That’s a price for a business in decline, and Adobe’s earnings are still growing at a double-digit pace.
AI could still wear down Adobe’s seat-based pricing slowly, with the reported numbers lagging the damage. Even so, the market has priced in a slowdown that Adobe’s last quarter doesn’t show. At 9.4x earnings, Adobe only has to deliver what analysts already expect for the stock to look cheap.
Adobe’s fourth-quarter report, expected in mid-December, will show whether it hit the recurring-revenue ramp Wells Fargo flagged. A miss would hand the bears the sign they’ve been waiting for.
So what is Adobe stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Adobe could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!