Key Takeaways
- A fund with $9.2 billion in US stocks sold all of its Edwards Lifesciences, PepsiCo and ServiceNow shares in the third quarter, about a tenth of its portfolio at June 30.
- Edwards is up 17% since Sept. 30 after raising its sales outlook, which leaves only 7% to analysts’ average target.
- PepsiCo’s falling snack margins and earnings estimates back the sale, and its average target sits below the stock.
- ServiceNow’s sale is the hardest to defend, with analysts seeing 55% upside and the stock at about 22x forward earnings.
A fund with $9.2 billion in US stocks cleared three big names out of its portfolio last quarter: Edwards Lifesciences (EW), PepsiCo (PEP) and ServiceNow (NOW).
The Wellcome Trust’s 13F for the quarter ended Sept. 30, filed Nov. 12, lists 23 US stocks and none of these three. At June 30, they were worth nearly $930 million together, about a tenth of the fund.
Edwards ran without it
Edwards was the biggest of the three: 4.80 million shares worth $434 million at June 30, 4.8% of the fund. The stock is up 17% since Sept. 30 and sits within 1% of its 52-week high.
The business earned the run. Third-quarter sales grew 11.2% in constant currency to $1.72 billion, its mitral and tricuspid devices grew 44% to $207 million, and management raised its full-year sales growth outlook to about 11.5%, from 10% to 11%.
Analysts’ consensus price target has climbed all year:
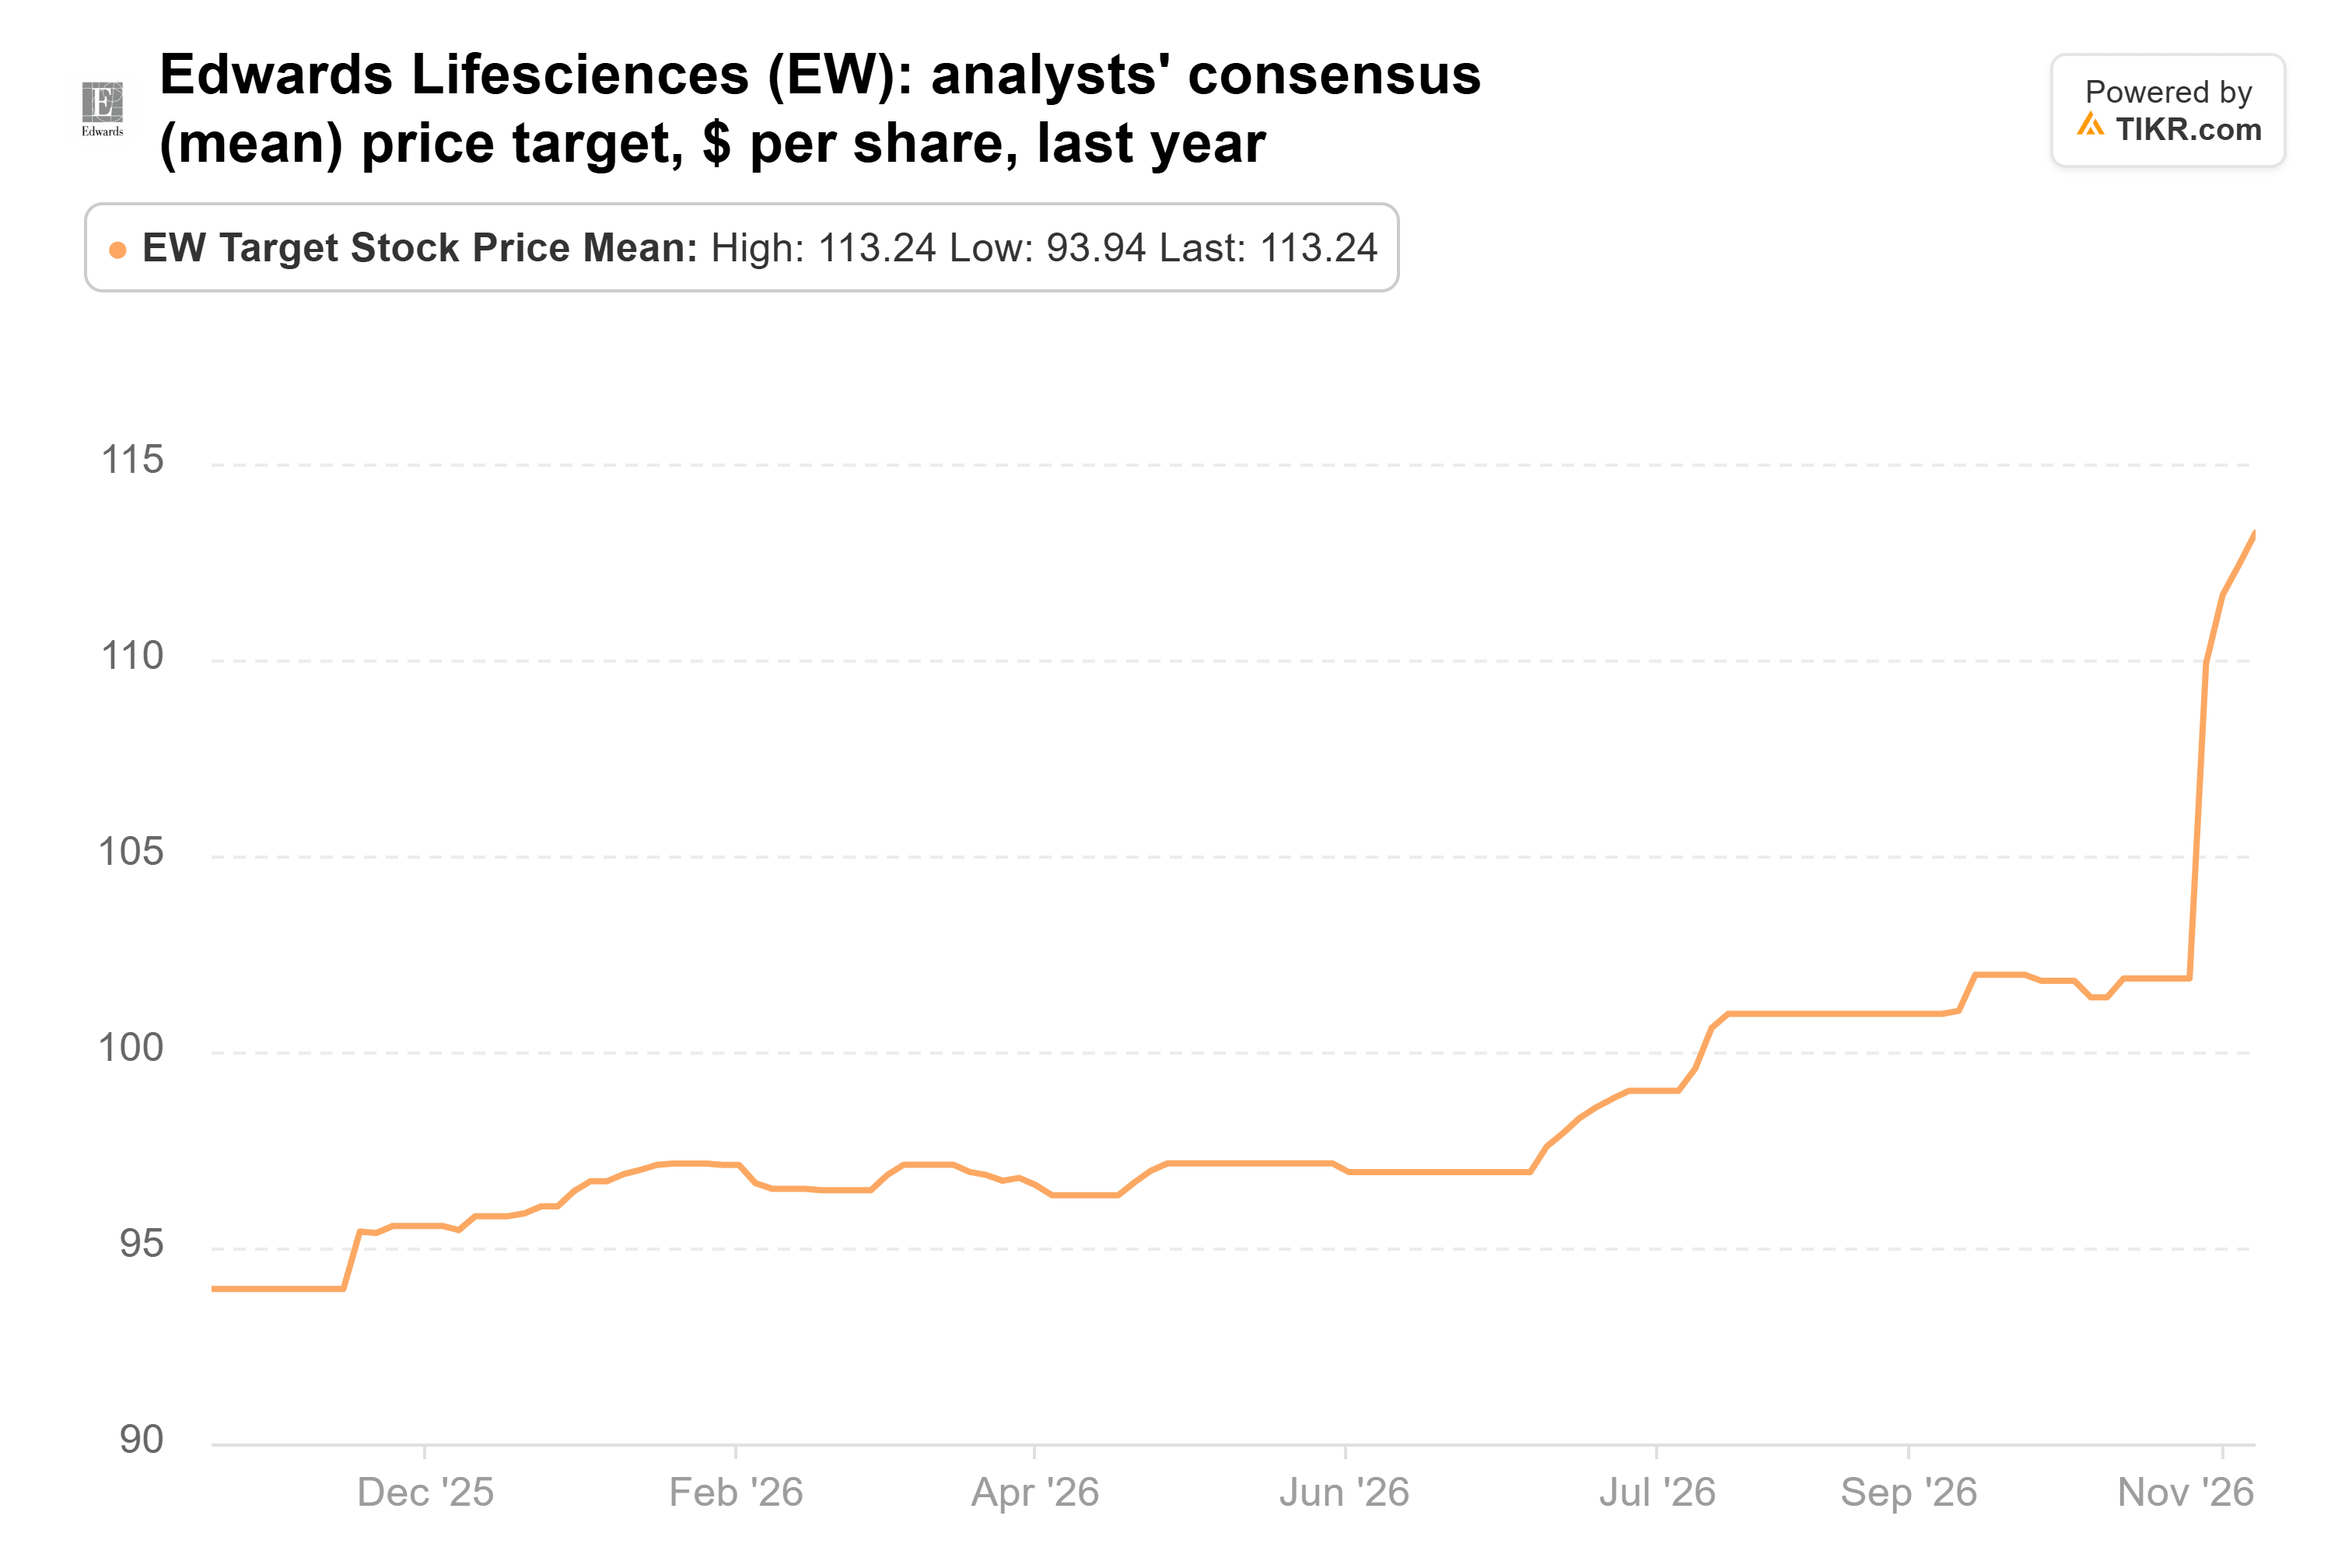
At $113, up from $94 a year ago, it’s still only 7% above the stock. With Edwards at about 33x forward earnings, I wouldn’t chase it at this price.
TIKR tracks 30 analysts on Edwards Lifesciences. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Edwards Lifesciences, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Edwards Lifesciences’ Analyst Ratings
PepsiCo’s snack problem hasn’t gone away
PepsiCo is a slower story. The trust held 2.00 million shares worth $271 million at June 30, 3.0% of the fund. The stock is up 5% since Sept. 30 and still 17% below its 52-week high.
The trouble is Frito-Lay. PepsiCo Foods North America’s core operating margin fell to 21.2% in the third quarter, from 24.1% a year earlier, after the company cut prices by up to 15% on Lay’s, Doritos and other brands in February. PepsiCo cut its 2026 outlook on Oct. 8, and the consensus for fiscal 2027 core EPS fell 5.1% between June 30 and Oct. 22, to $8.64.
The consensus target has followed the estimates down since its May peak:
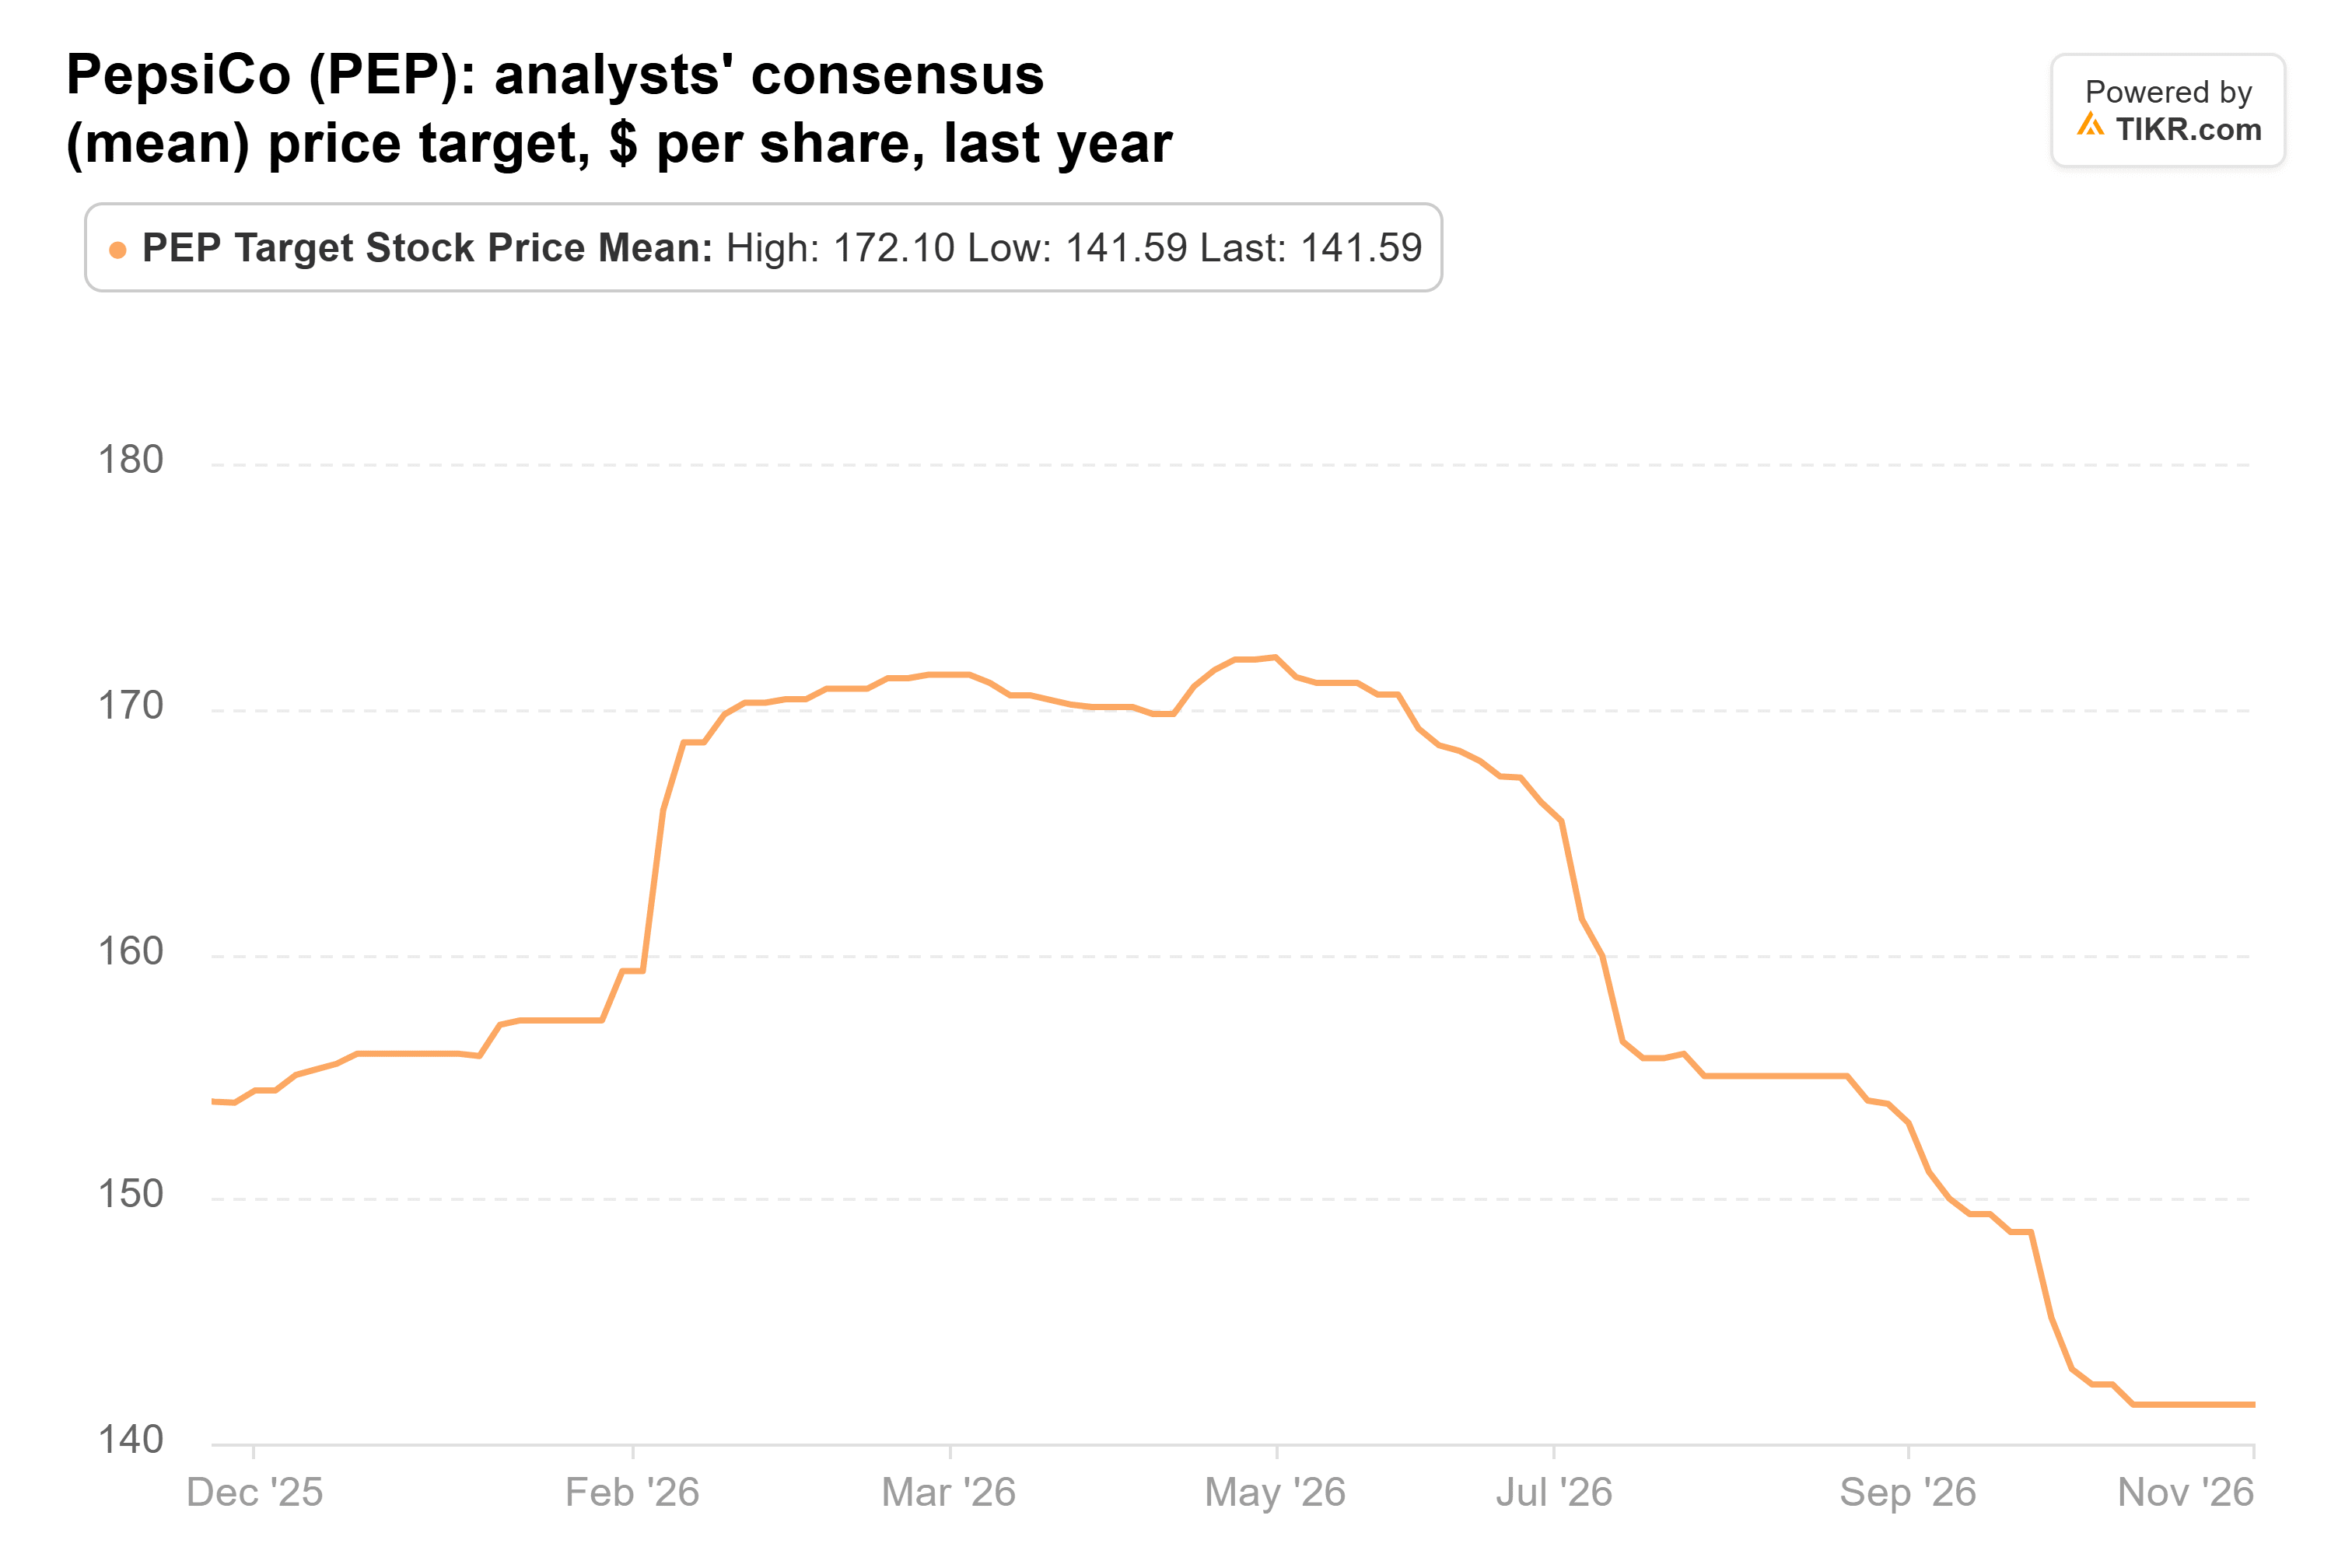
At $142, it now sits just below the stock. PepsiCo looks cheap at about 17x forward earnings, against a 5-year average near 21x. And dividends took a manageable 75% of free cash flow over the 12 months to Sept. 5, so its 54 straight years of dividend raises don’t look at risk. But with estimates still falling, I’d want to see the snack margin turn before buying.
ServiceNow has already been marked down
ServiceNow is the opposite case: a stock that’s already fallen hard. The trust held 2.25 million shares worth $223 million at June 30, 2.5% of the fund. The stock is up 1% since Sept. 30, but 42% below its 52-week high.
Its third quarter was mixed. cRPO grew 21% in constant currency, above the 20% guide, and management raised its 2026 target for AI annual contract value to $1.7 billion, from $1.5 billion. But it guided fourth-quarter cRPO to 18.5%, and the CFO said early renewals pulled into the third quarter made up about half the beat. Analysts cut their 2027 EPS estimates to $4.80 from $5.01 over the 30 days to Nov. 3, even as the CFO pushed back on fears that AI will disrupt the business.
The consensus target fell hard over the past year before winning back some ground:
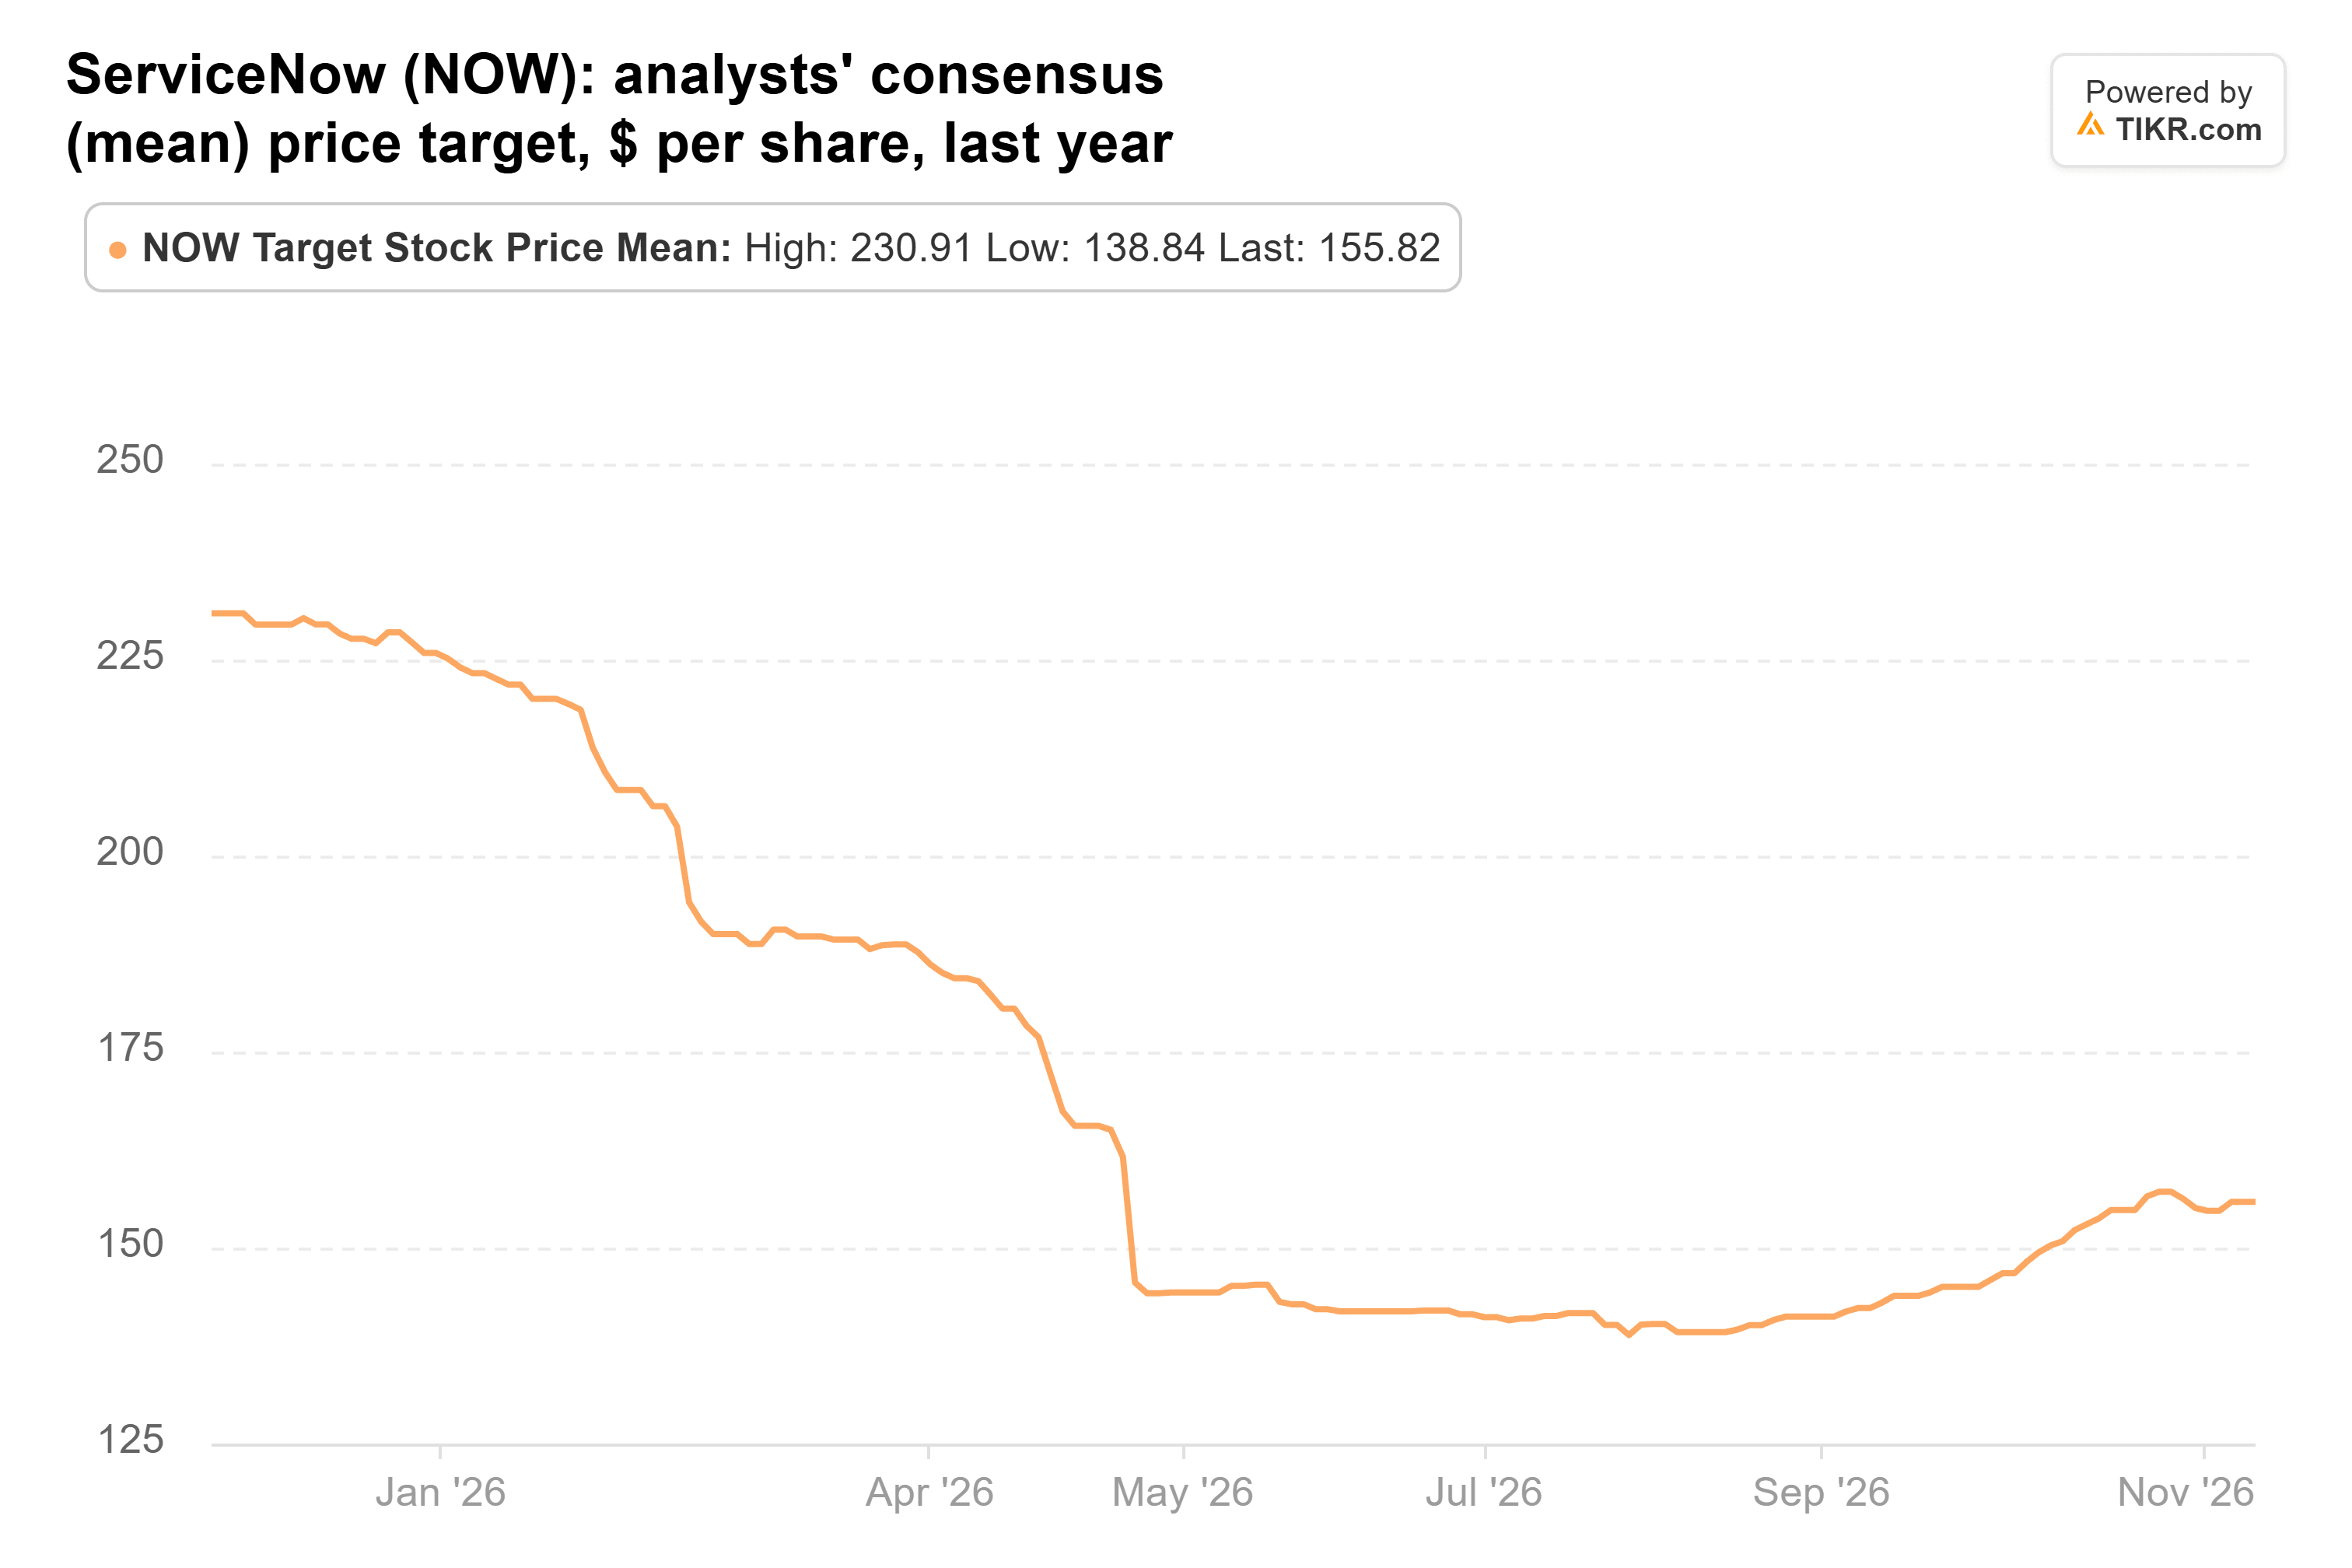
It’s $156 now, from $231 a year ago and a July low of $139, and that’s 55% above the stock. The 49 analysts’ targets run from $72 to $266, so the Street is far from united. At about 22x forward earnings, against a five-year quarter-end average of 53x, the stock already prices in a lot of doubt.
The one I’d buy back
Of the three, the numbers back the PepsiCo sale best: its estimates are still falling, and the Street’s average target sits below the price. Selling Edwards looks reasonable too, after a 17% run that leaves little room to the average target.
If I had to buy back one of the three, it’d be ServiceNow. Growth is slowing and estimates are slipping, but the stock trades at less than half its five-year average multiple while analysts see 55% upside. The risk is that growth without the acquisitions keeps sliding, and the estimates fall with it.
The next tests come early next year: ServiceNow’s fourth-quarter report and first 2027 guidance in late January, PepsiCo’s 2027 outlook in February, and the trust’s next 13F, due by mid-February.
So what is Edwards Lifesciences stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Edwards Lifesciences could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Edwards Lifesciences for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!