


Key Takeaways
- A firm that manages $7.41 billion sold all of its SpaceX, HEICO and Ferguson Enterprises shares in the third quarter. It ended the quarter with TKO Group as its biggest holding and a new stake in Meta Platforms.
- SpaceX was the big sale, at 13.5% of the firm’s 13F stocks at June 30. The numbers back it best, since analysts expect $150 billion of negative free cash flow in 2027.
- Ferguson looks like the sale to second-guess: sales are growing, guidance went up and analysts’ average target is at its high for the year.
- SpaceX’s fourth-quarter capex and cash, due in early 2027, are the next test of the biggest sale.
SpaceX (SPCX) was the biggest stock XN LP walked away from last quarter. The firm’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows it sold all 3.00 million of its SpaceX shares, worth $513 million at June 30. It also sold its stakes in HEICO (HEI.A) and Ferguson Enterprises (FERG).
It still had plenty riding on other stocks. By Sept. 30, TKO Group (TKO) was its biggest position, and Meta Platforms (META) was a new one.
SpaceX was the big one
SpaceX made up 14% of XN’s 13F stocks at June 30, so this was a real bet. Since Sept. 30, the stock has fallen 16%, and it sits 36% below its 52-week high. The worry is cash. SpaceX guided fourth-quarter capex to $35 billion to $40 billion, against $89.9 billion of cash and marketable securities at Sept. 30, and analysts now expect negative free cash flow of $150 billion in 2027. Most of that capex goes into AI data centers, and one renter, reportedly Anthropic, supplies about two-thirds of the AI segment’s sales. SpaceX’s prospectus says either side can end that contract on 90 days’ notice.
TIKR tracks 40 analysts on SpaceX. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SpaceX, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SpaceX’s Analyst Ratings
Wall Street’s targets are all over the map
Analysts haven’t given up on SpaceX, though. Their average target has gone from $114 when the stock listed in June to $257.50 now:
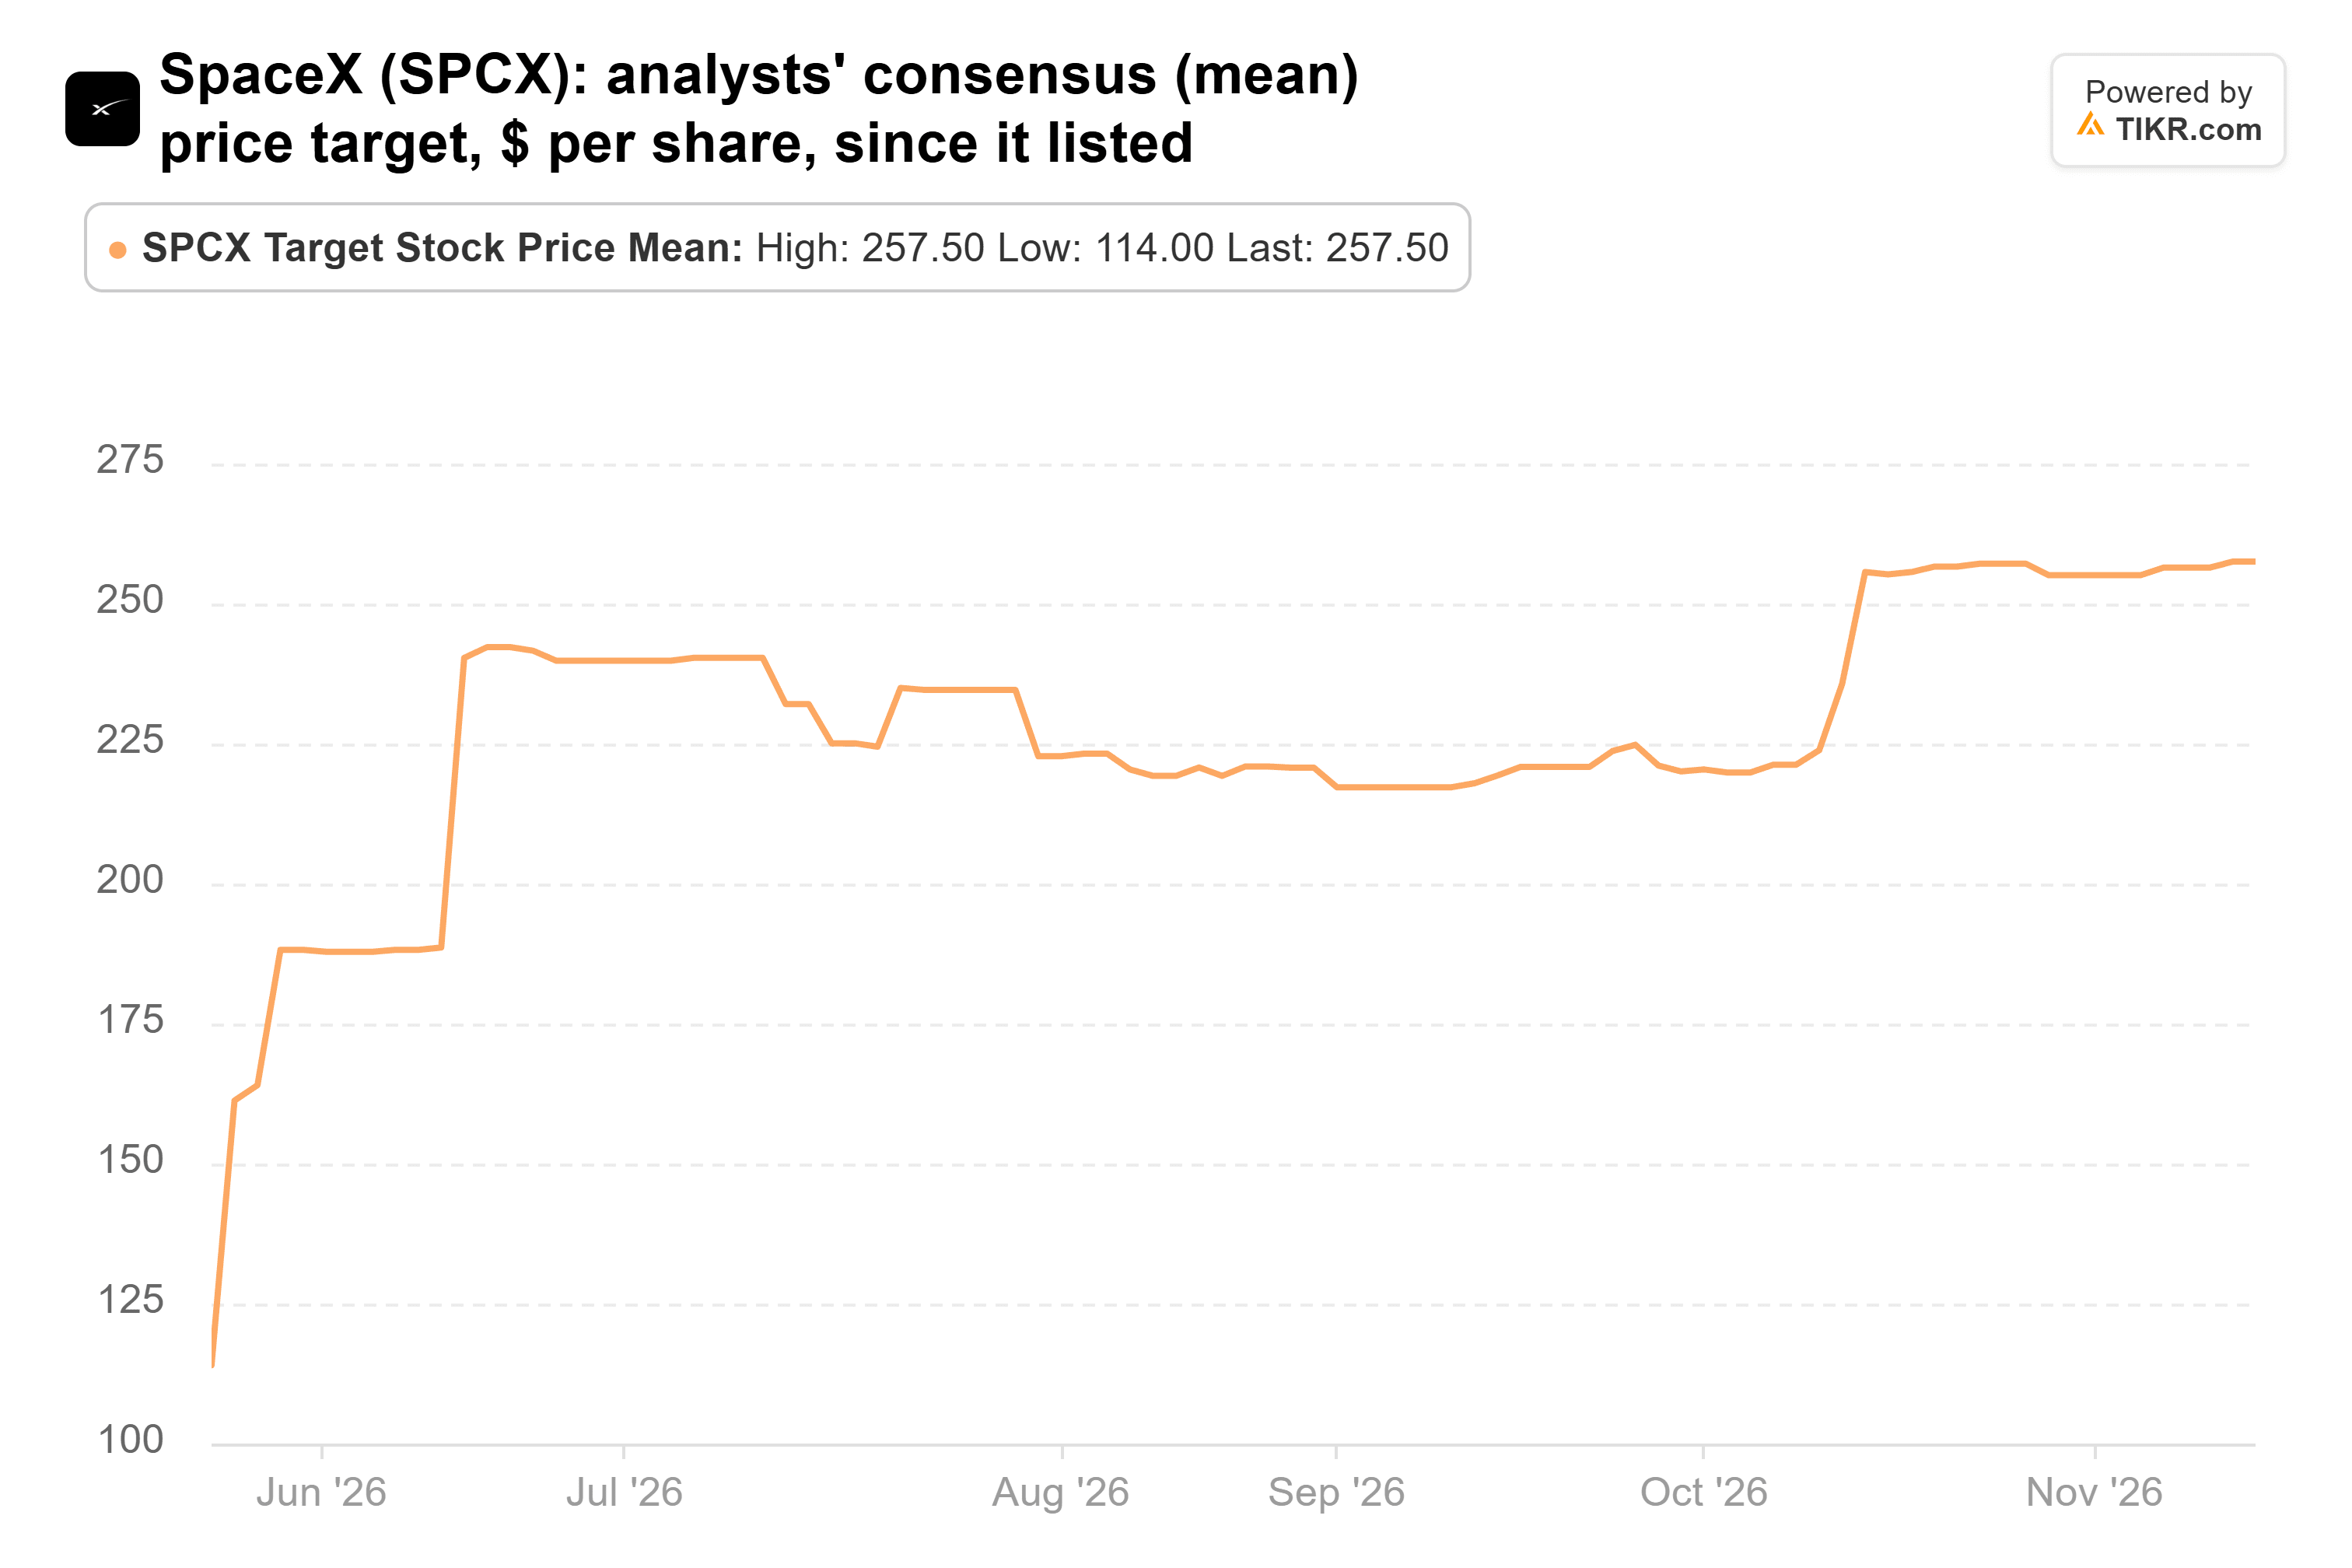
That’s 79% above the last close of $143.50, with 40 analysts behind it. But the targets run from $70 to $800, so analysts disagree wildly on how the AI compute business plays out. At about 47x forward earnings, SpaceX also needs consensus normalized EPS to climb from a $0.30 loss this year to $5.69 in 2028.
HEICO keeps growing, at a price
HEICO was a smaller position: 475,566 Class A shares worth $123 million, or 3.2% of XN’s 13F stocks at June 30. There’s nothing wrong with the business. In its fiscal third quarter, ended July 31, net sales rose 23% to $1.41 billion on 14% organic growth, and GAAP net income rose 33% to $235.4 million.
The price is the catch. The Class A shares trade at about 40x forward earnings, and their average target has slipped from $320 in June to $300:
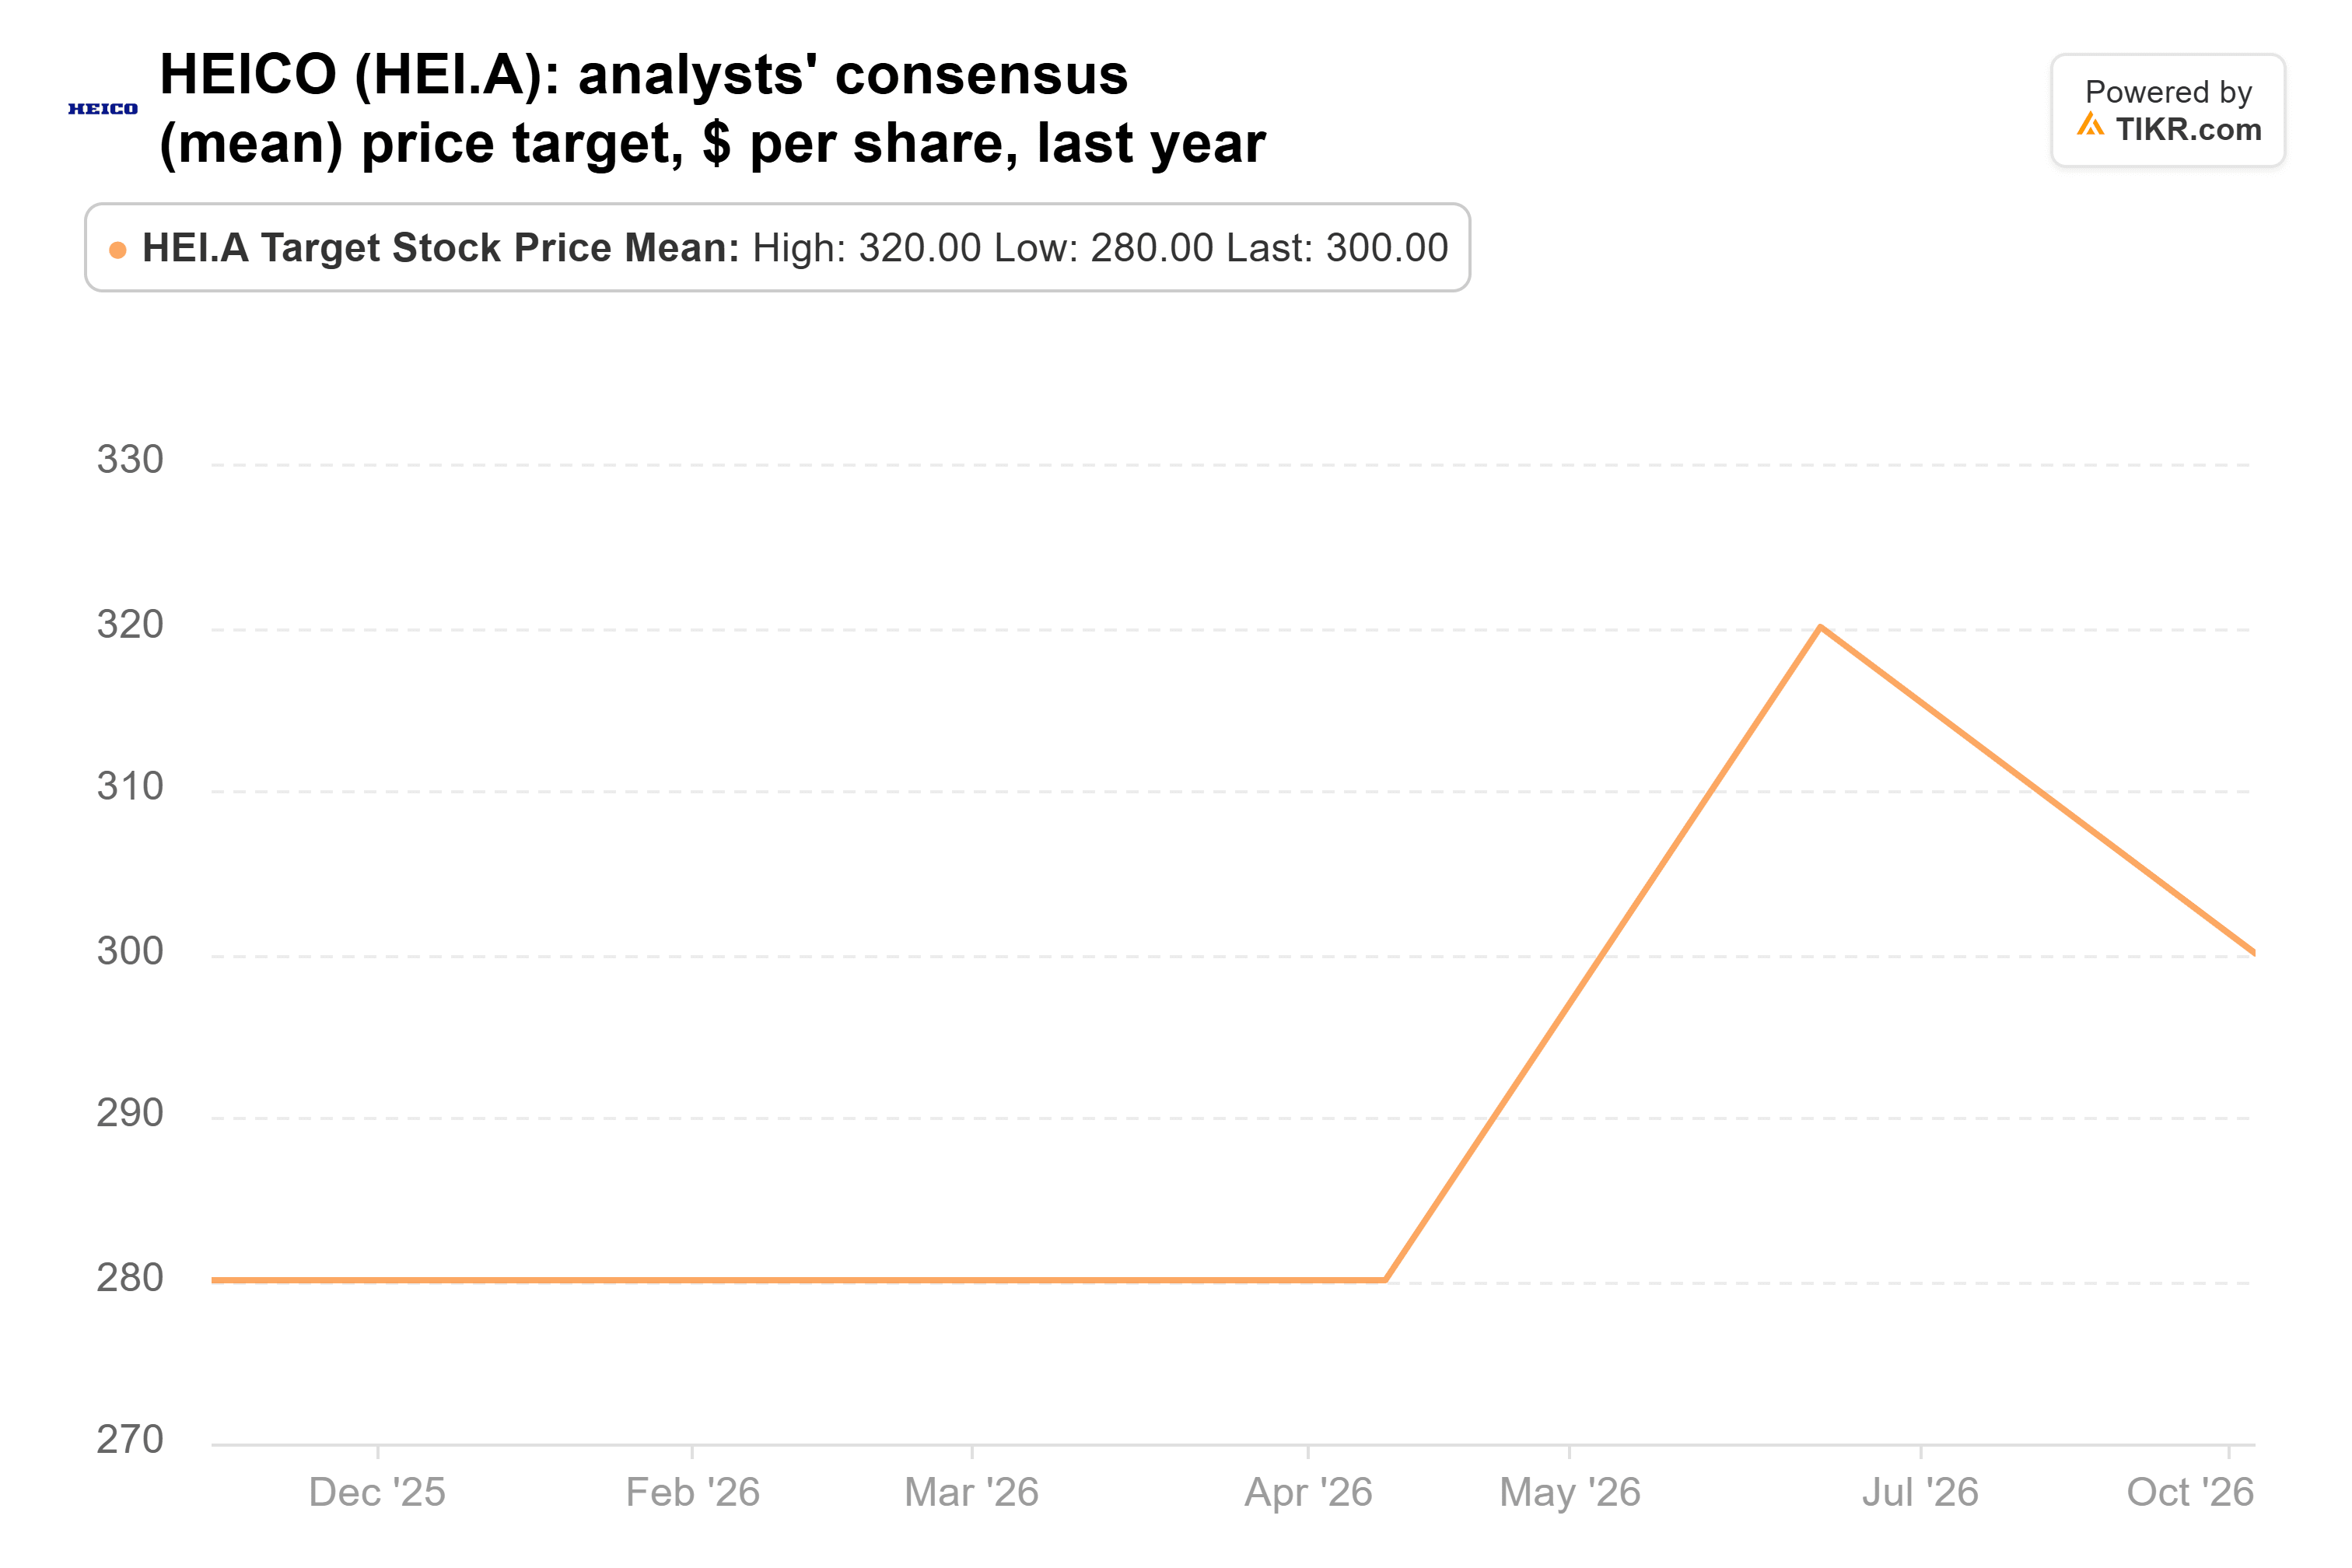
That’s still above the $248.88 last close, and the stock is down 4% since Sept. 30. HEICO reports its fiscal fourth quarter in mid-December.
Ferguson is the sale I’d question
Ferguson was also 3.2% of XN’s 13F stocks at June 30, at 515,420 shares worth $122 million, and it’s the sale I have the hardest time with. On Nov. 9, Ferguson said third-quarter sales rose 9.5% to $9.0 billion, with 7.0% organic growth and non-residential sales up 15%, and it raised its full-year guidance. Adjusted EPS rose 7.9% to $3.43 (GAAP EPS fell 4.9% to $3.08).
Analysts have followed the business up:
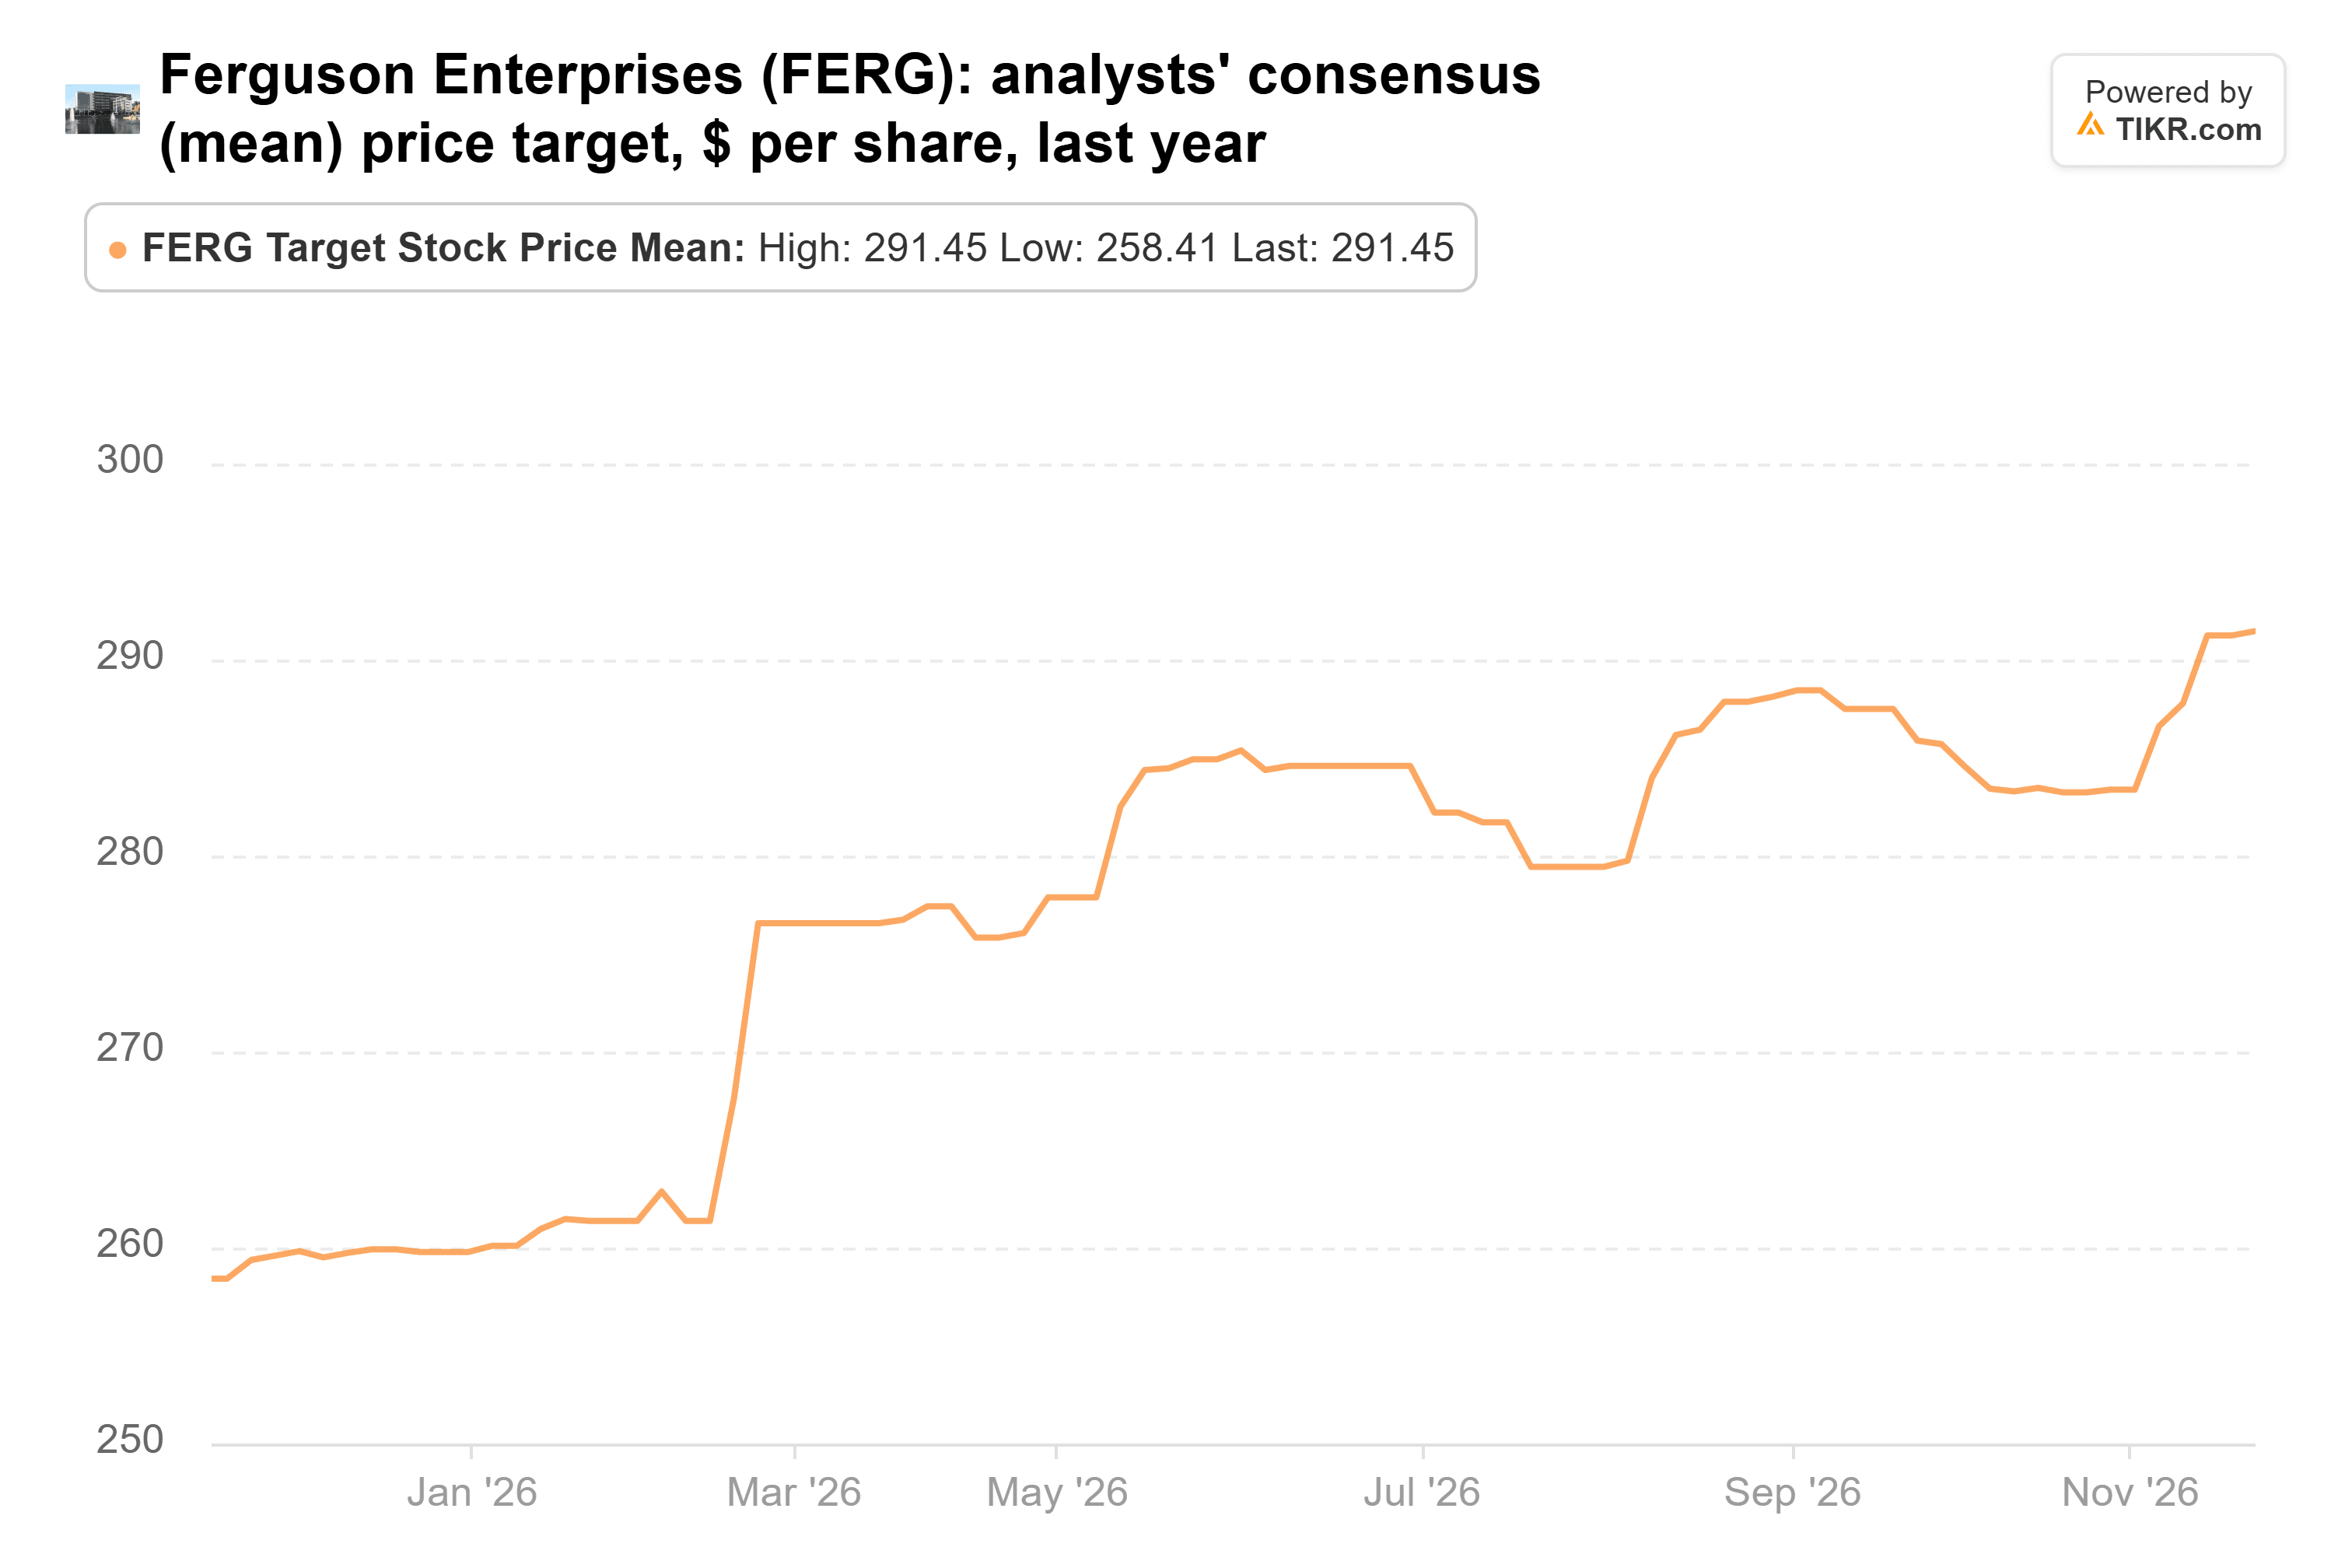
The $291.45 average target from 24 analysts is up from $258.41 a year ago and sits 16% above the last close. The lowest target has risen from $194 to $235. The stock trades at about 20x forward earnings and is up 6% since Sept. 30.
TKO is now its biggest bet
XN didn’t just sell. At Sept. 30, TKO made up 18% of its 13F stocks, 3.14 million shares worth $564 million, after it added 26% more shares in the quarter. On Nov. 4, TKO raised its full-year guidance for the second time this year, lifting adjusted EBITDA to $2.30-$2.32 billion from $2.28-$2.31 billion. Analysts’ $232.37 average target sits 22% above the last close.
Meta was new: 294,011 shares worth $213 million, 6.7% of its 13F stocks and its fourth-largest. That one has gone the wrong way so far, down 15% since Sept. 30, and analysts now see Meta’s free cash flow bottoming at negative $48.0 billion in 2027. At about 19x forward earnings, though, it trades below its five-year average of 21x.
The SpaceX sale is the one I’d back
Of the three, SpaceX is the sale that makes the most sense to me. Until its AI compute spending pays for itself, it leans on the debt market and a short list of renters, and I’d rather own a business that funds itself. Ferguson does, and if I could buy one of the three back, it’d be Ferguson. HEICO’s growth is real, but at about 40x, there’s little room for a slip.
SpaceX’s fourth-quarter report in early 2027 is the next test. If capex runs above the $40 billion top of its guide, or cash and securities fall below about $50 billion, XN’s exit will look right. If December revenue reaches $8.3 billion, the pace its $100 billion run-rate goal needs, the stock gets hard to ignore at these prices. XN’s next 13F, due in mid-February, will show whether it’s back in.
So what is SpaceX stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SpaceX could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!




