Key Takeaways
- Khrom Capital Management, a firm managing $1.19 billion, added to DoorDash, GXO Logistics and Medline in the second quarter, its latest 13F shows.
- Analysts’ average targets sit 41% above DoorDash’s price and 28% above GXO’s, but only 8% above Medline’s.
- DoorDash trades well below its usual forward earnings multiple, even as analysts raise their estimates.
- If I could buy just one of the three today, it’d be DoorDash.
When a fund holds just 15 stocks, the ones it adds to are worth a close look. Khrom Capital Management, which manages $1.19 billion, added to three in a big way in the second quarter: DoorDash (DASH), GXO Logistics (GXO) and Medline (MDLN), its 13F for the quarter ended June 30, filed Aug. 14, shows.
Khrom leaned into DoorDash
As of June 30, its latest filing, Khrom held 959,268 DoorDash shares worth $177 million, 41% more shares than three months before. That made DoorDash 14.8% of its 13F stocks and its second-largest position. The stock is down 3% from its June 30 price, and there’s been plenty of news since then. DoorDash struck a $17 billion deal for Instacart that still faces antitrust scrutiny. And Amazon now offers Prime members free Uber Eats restaurant delivery on orders of $25 or more placed in its own app, where they never open DoorDash’s. Still, DoorDash said in its Oct. 29 release that marketplace order value rose 23% in the third quarter, excluding Deliveroo.
Analysts have trimmed their average target over the past year, from $276 to $251, but it’s still 41% above the last close.

Even the lowest of the 41 analysts’ targets, $200, is above the last close.
TIKR tracks 41 analysts on DoorDash. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DoorDash, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DoorDash’s Analyst Ratings
GXO is winning more business
GXO grows more slowly than DoorDash, but it trades at a much lower earnings multiple. Khrom held 2.85 million GXO shares at June 30, worth $145 million, after adding 43% more shares in the quarter. At 12.1% of its 13F stocks, GXO was its third-largest position. The stock is up 8% from its June 30 price, and GXO’s third-quarter report on Nov. 3 was a good one:
- Revenue rose 5.7% to $3.6 billion.
- Organic growth of 6.4% was its fastest in more than three years.
- New business wins jumped 34% to $375 million.
It also reaffirmed its full-year guidance.
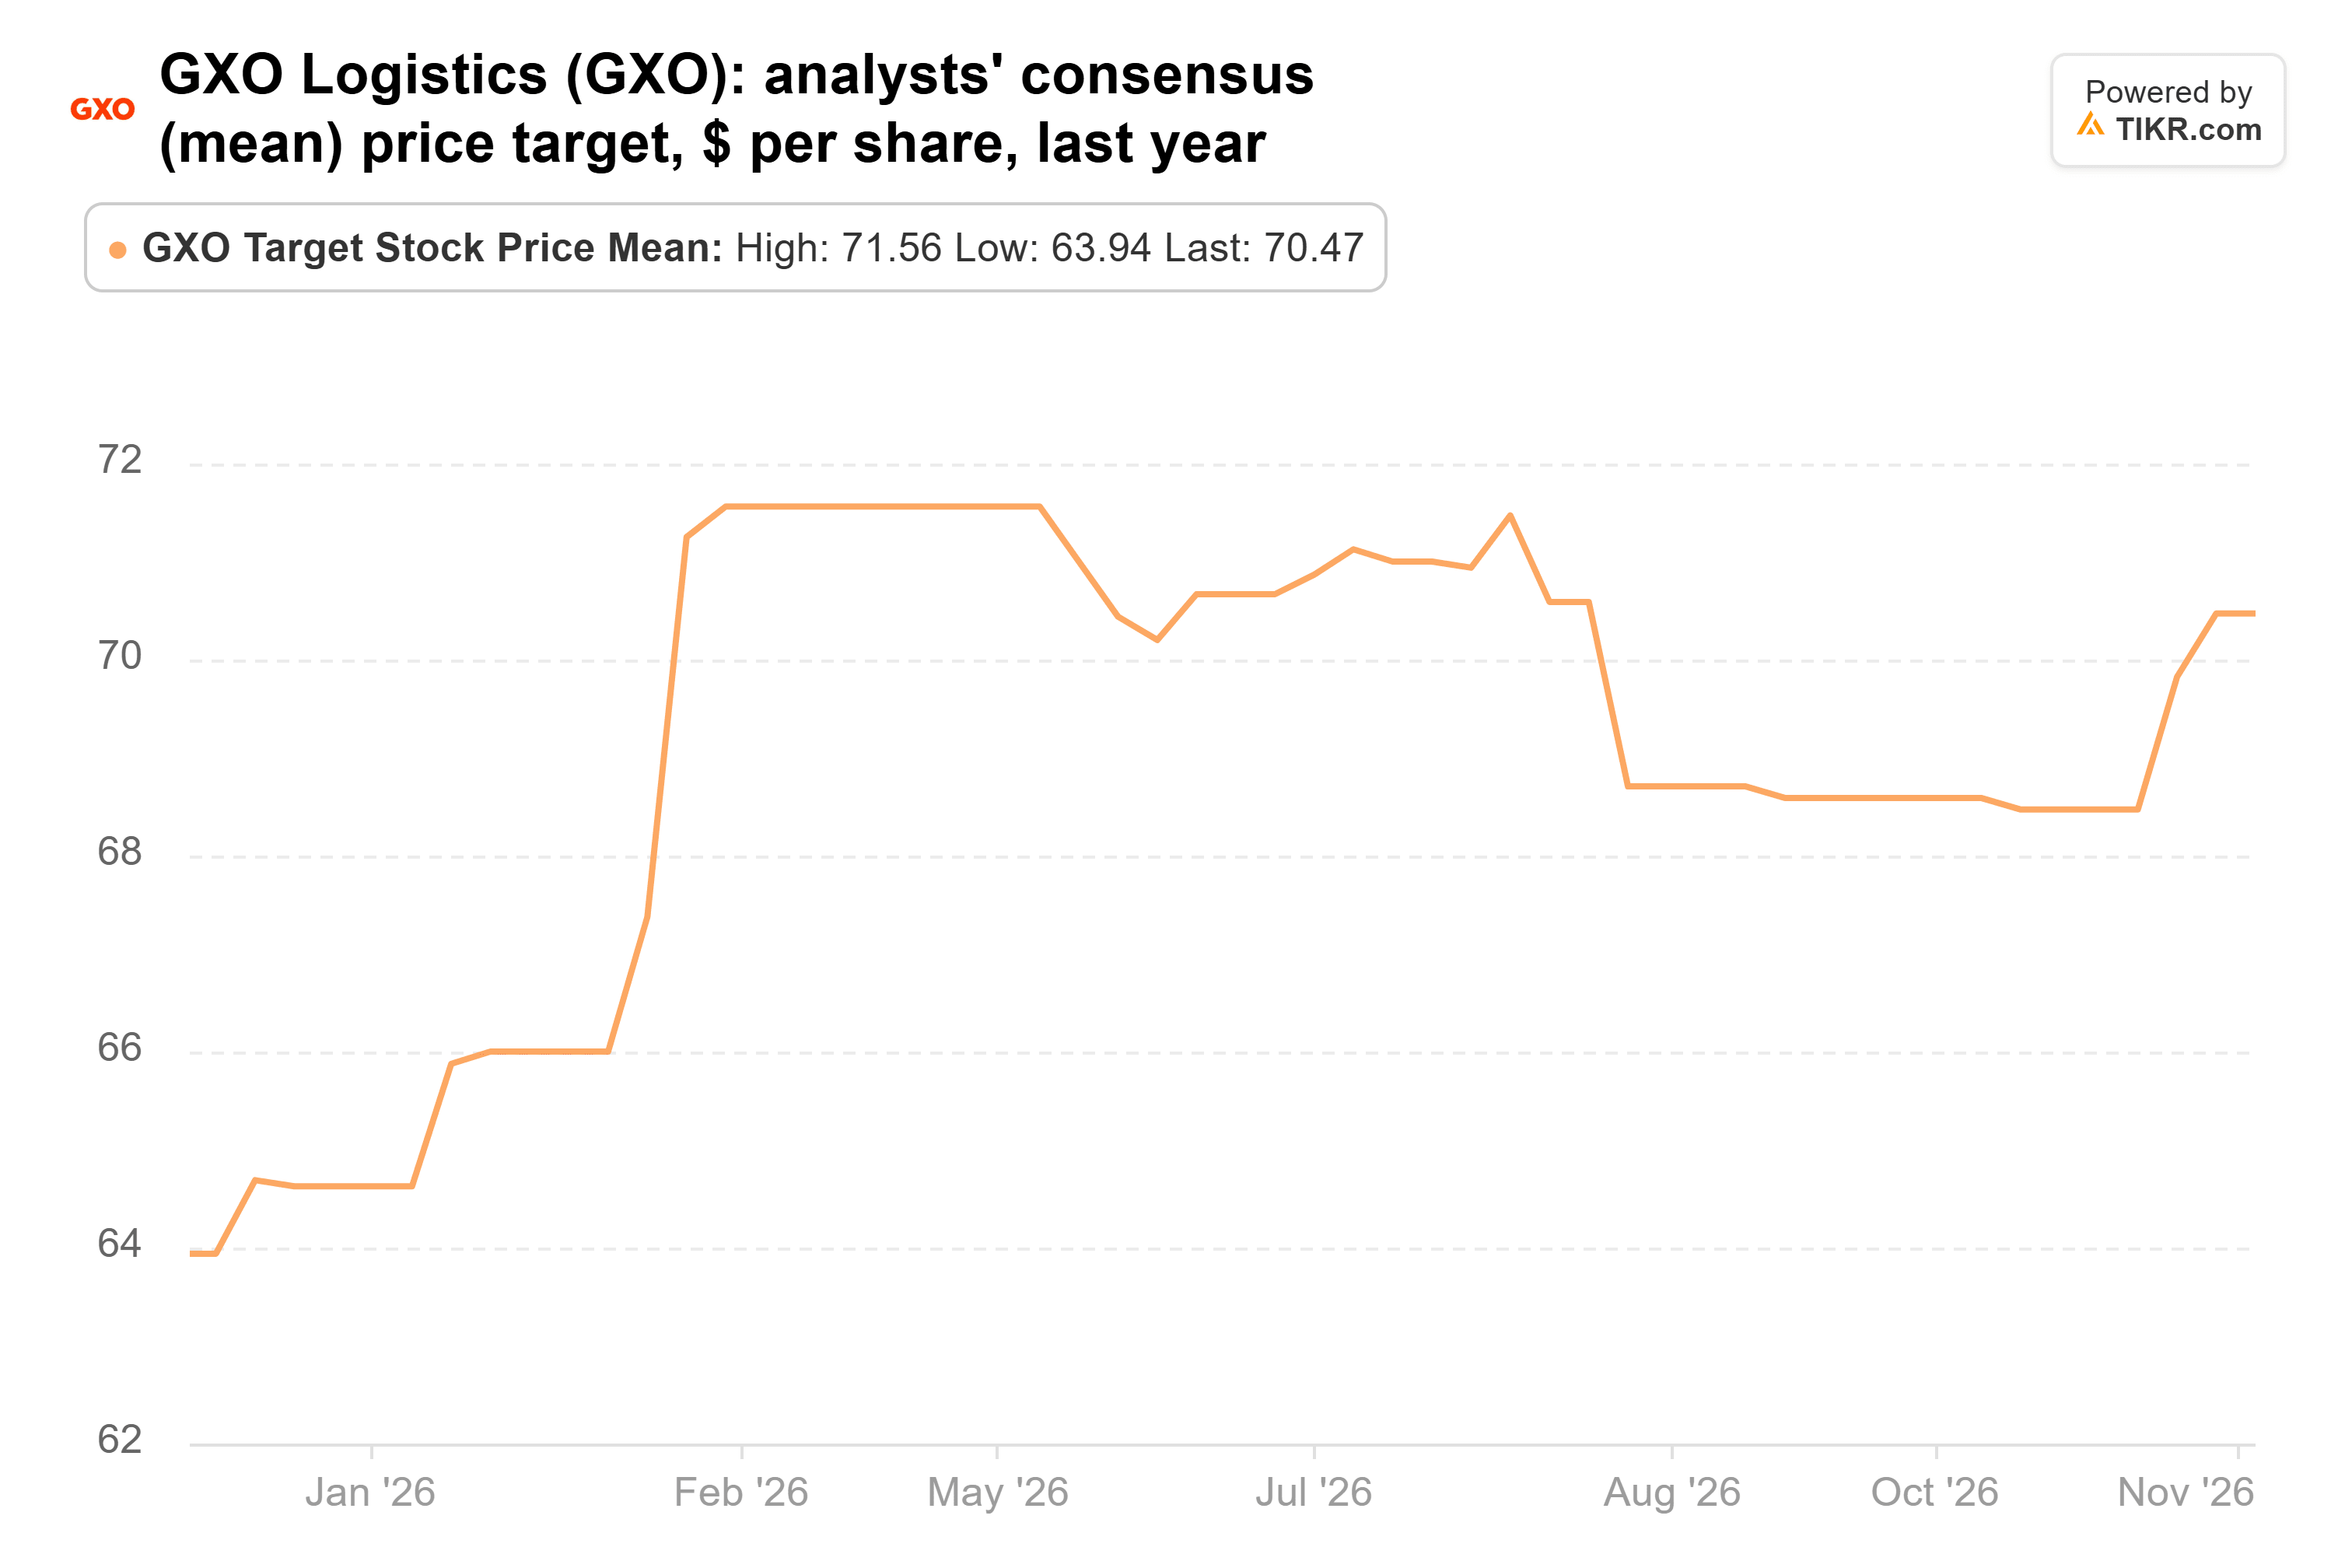
Analysts like GXO more than they did a year ago. Their average target rose from $64 to $70, and it’s 28% above the last close.
At about 16x forward earnings, that’s a modest price for a business that’s picking up speed. GXO’s investor day on Nov. 16 is the next chance to see whether its record $3.1 billion sales pipeline leads to faster growth.
Medline’s beat is already in the price
Khrom’s Medline stake grew faster still. It more than tripled in the second quarter, to 2.44 million shares worth $96 million at June 30. That was 8.0% of its 13F stocks and its sixth-largest position. The stock is up 7% from its June 30 price, after it jumped 18% on Nov. 4 on a third-quarter beat. Net sales rose 10.4% to $7.9 billion, Medline raised its full-year organic sales growth outlook to 10.0%-10.5% from 9.0%-10.0%, and its board authorized a $1 billion buyback. But it kept its $3.3 billion-$3.4 billion adjusted EBITDA outlook. The quarter’s adjusted EBITDA also included $81 million of tariff refunds, and without them it grew about 2%, against the 11.8% reported.
Analysts are less excited than they were. Their average target has slipped from $50 in January to $45, only 8% above the last close.
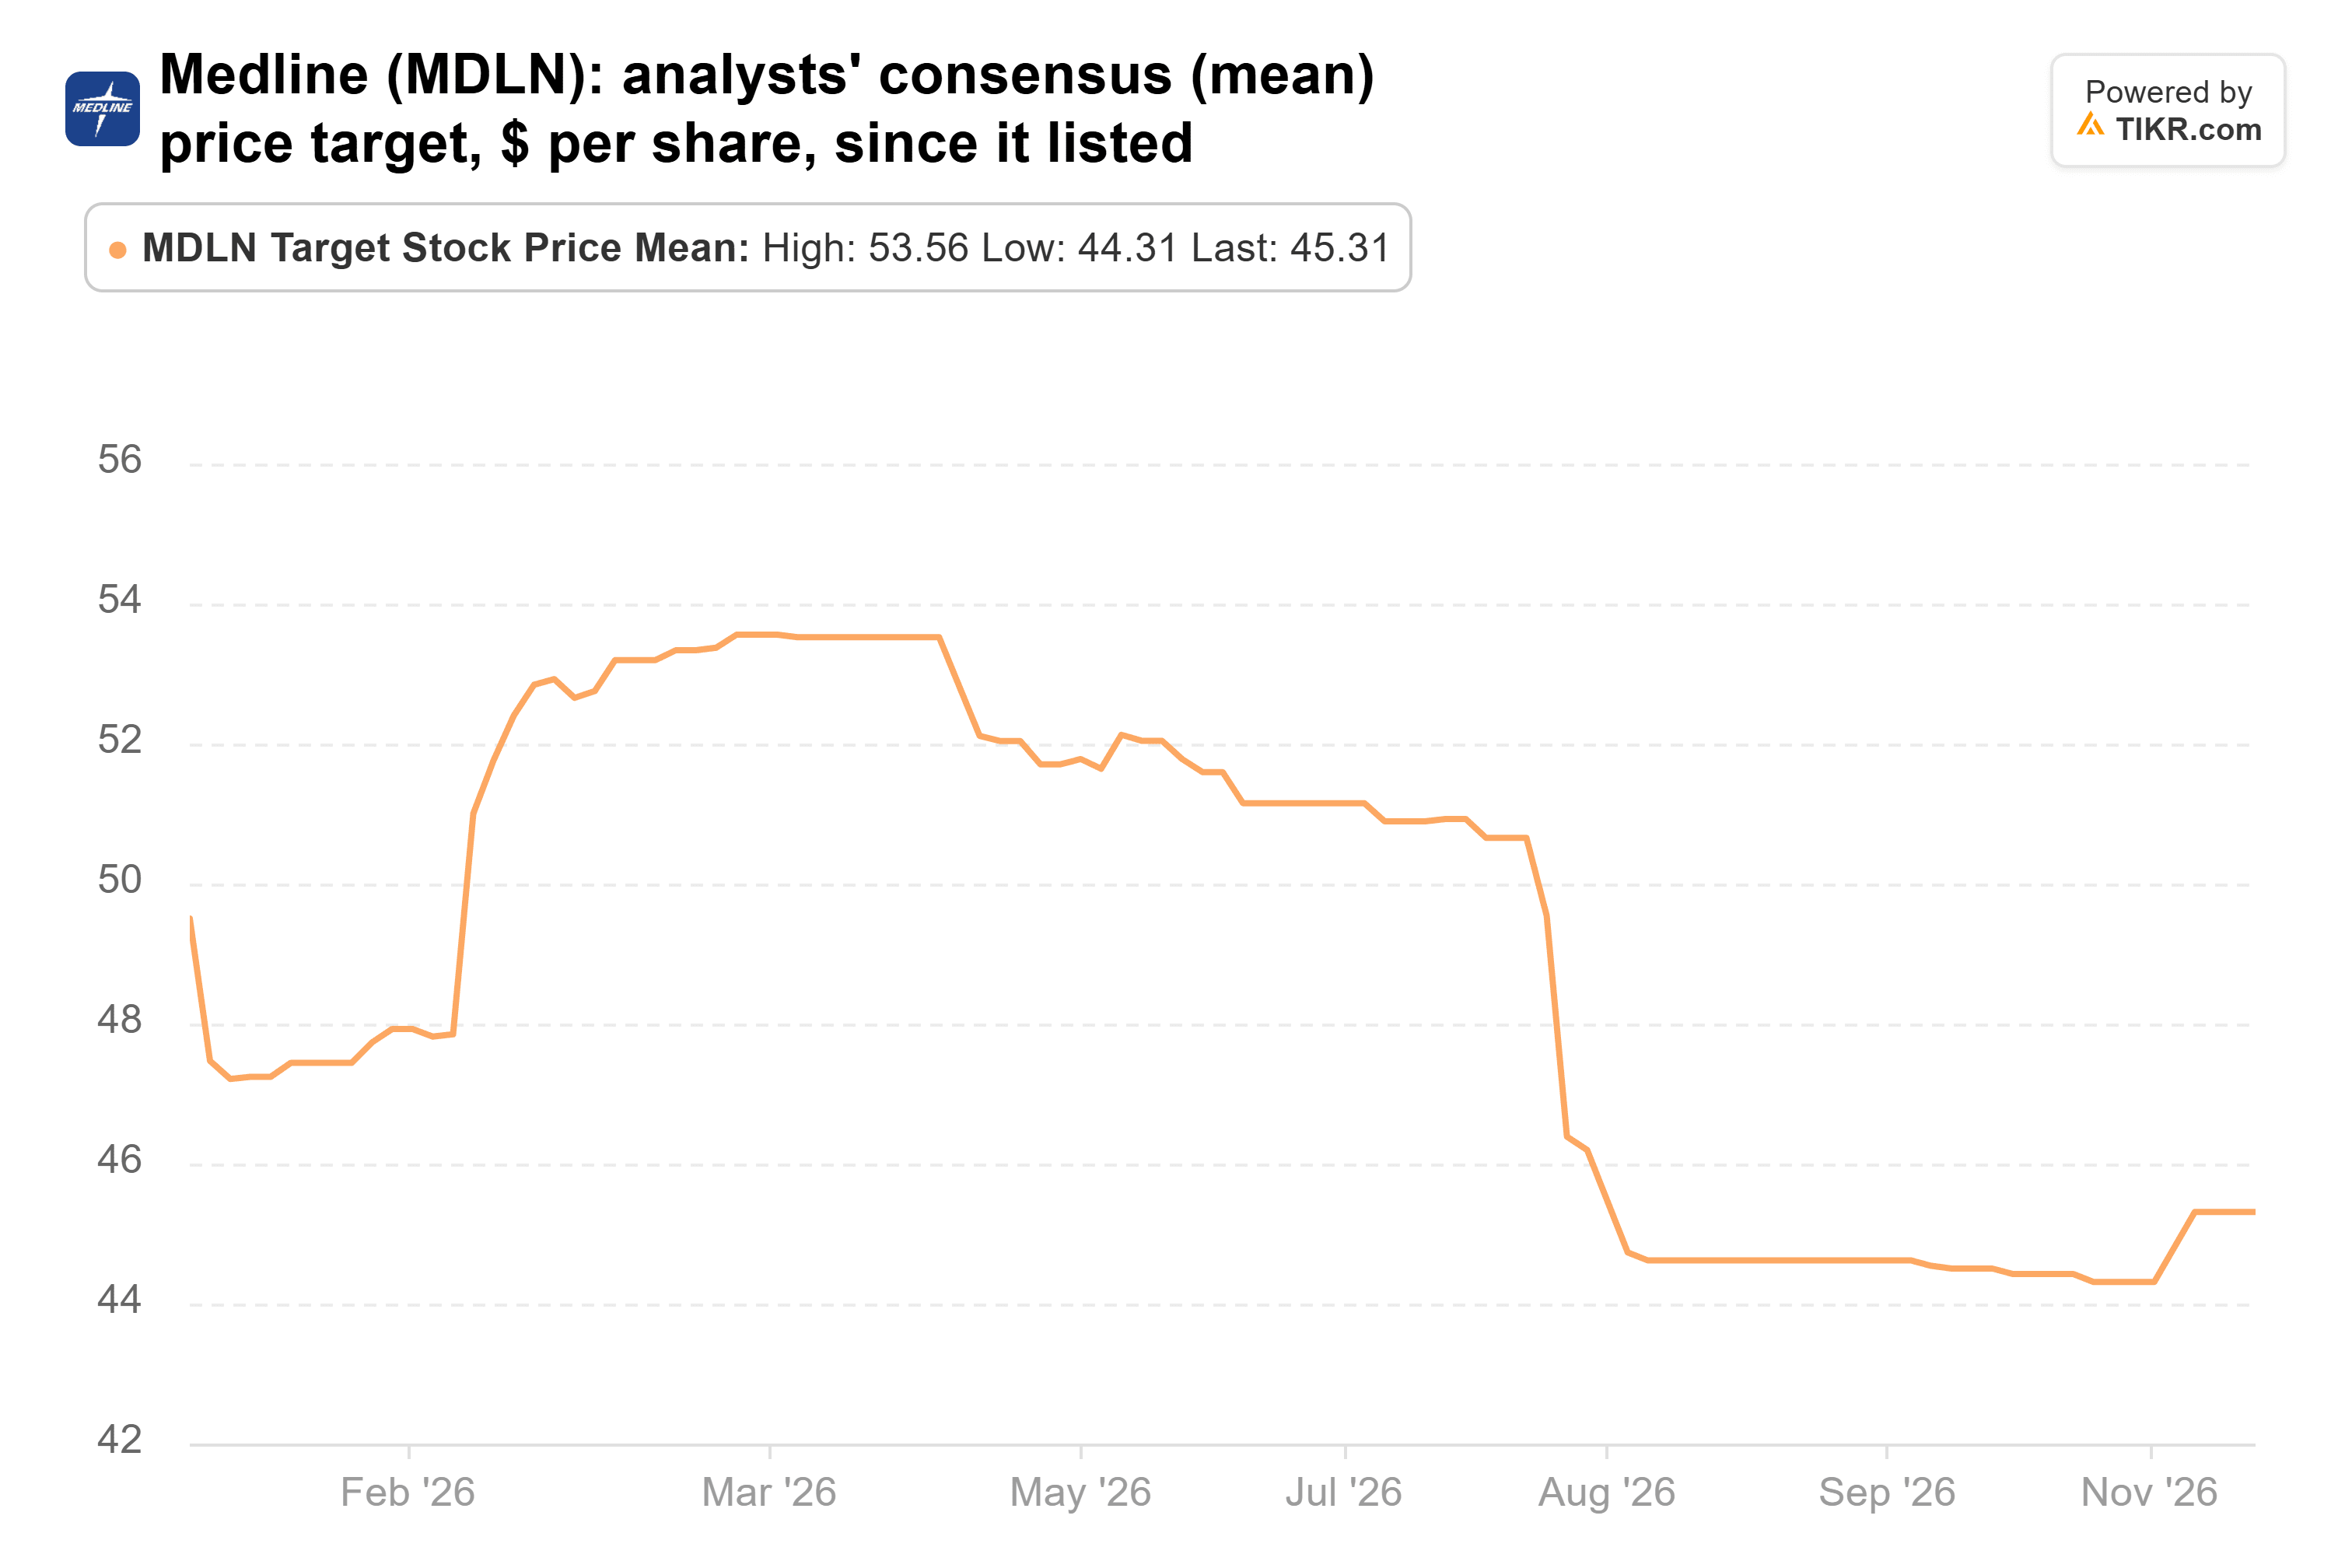
At about 28x forward earnings, Medline is priced richly for a company whose profit outlook didn’t budge.
DoorDash is the one I’d follow Khrom into
Of the three, DoorDash gives me the most for the price. It trades at about 26x forward earnings, well below its three-year average of 39x. And analysts have raised their 2026 and 2027 earnings estimates 5% to 6% since June 30. Add a 41% gap to the average target, and the numbers back Khrom on DoorDash more than on GXO or Medline.
Amazon’s deal with Uber Eats could cost DoorDash some Prime members’ orders, and the Instacart deal still has to clear antitrust review. Khrom’s next 13F, for the quarter ended Sept. 30, is due Nov. 16 and will show whether it kept adding through September. DoorDash’s fourth-quarter report, due in February, will show whether this year’s heavy spending leads to wider margins.
So what is DoorDash stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DoorDash could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!