Key Takeaways
- Six big funds, including Gavin Baker’s Atreides Management, cut their Palo Alto Networks stakes by 20% to 94% in the third quarter, and the stock is down 20% since Sept. 30.
- Five of the six still held Palo Alto positions worth 2% or more of their 13F stocks at Sept. 30.
- At about 76x forward earnings, Palo Alto costs more than Palantir and three times as much as Microsoft, while management guides to 8% to 9% EPS growth this fiscal year.
- On price, the sellers look right, and I wouldn’t buy before the Nov. 18 report shows per-share earnings catching up.
Six big funds cut their stakes in Palo Alto Networks (PANW) in the third quarter. That’s what their 13Fs for the quarter ended Sept. 30 show, filed between Nov. 5 and Nov. 16. The stock is down 20% from its Sept. 30 close, and Palo Alto reports its fiscal first quarter on Nov. 18.
Most of them still own plenty
None of the six sold out completely. The cuts ranged from a fifth of the stake to nearly all of it:
| Fund | Size | Stake cut in Q3 | Stake at Sept. 30 | Share of its 13F stocks (rank) |
|---|---|---|---|---|
| Atreides Management | $11 billion | 34% | $230 million | 2.1% (No. 11) |
| Mirova US | $14 billion | 34% | $344 million | 3.8% (No. 7) |
| Sandhill Capital Partners | $2.4 billion | 38% | $35 million | 3.1% (No. 13) |
| Kranot Hishtalmut Le Morim Ve Gananot | $2.3 billion | 25% | $66 million | 2.8% (No. 5) |
| Triodos Investment Management | $1.6 billion | 20% | $91 million | 5.5% (No. 1) |
| LGT Capital Partners | $1.6 billion | 94% | $3 million | 0.2% (No. 38) |
Source: each fund’s 13F for the quarter ended Sept. 30, 2026. Size is what the firm manages, except for Kranot, Triodos and LGT, where it’s what their 13Fs hold in US stocks.
LGT came closest to leaving, with just 6,678 shares left. Triodos sits at the other end: it trimmed 20%, and Palo Alto was still its largest holding. Gavin Baker’s Atreides cut its stake by a third, to 578,905 shares. A 13F only shows what a fund held on the last day of the quarter, so we don’t know when these funds sold, what they got, or why.
TIKR tracks 56 analysts on Palo Alto Networks. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palo Alto Networks, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palo Alto Networks’ Analyst Ratings
The same funds pay a lot less for Microsoft
Five of the six also own Microsoft (MSFT), and for some it’s a much bigger position. It was Mirova’s No. 2 holding at 6.3% of its 13F stocks, and LGT’s No. 3 at 8.2%. Four of the five trimmed it too, by 7% to 28%. Atreides went the other way and opened a new Microsoft position of 275,976 shares, worth $142 million. Microsoft trades at about 25x forward earnings, a third of Palo Alto’s multiple, and it’s up 1% since Sept. 30.
Palo Alto even costs more than Palantir (PLTR) on forward earnings. Kranot, the only one of the six that owns Palantir, added 3% to that stake. Palantir grew revenue 96% last quarter, against the 23% to 24% Palo Alto guides to for this fiscal year. Even so, Palantir trades at about 70x forward earnings, below Palo Alto’s 76x.
Is 76x too much for 9% growth?
Analysts expect Palo Alto to earn $4.18 a share in normalized terms this fiscal year, which ends in July 2027. That’s up 9%, in line with management’s guide of 8% to 9% growth. They see $4.88 the year after:
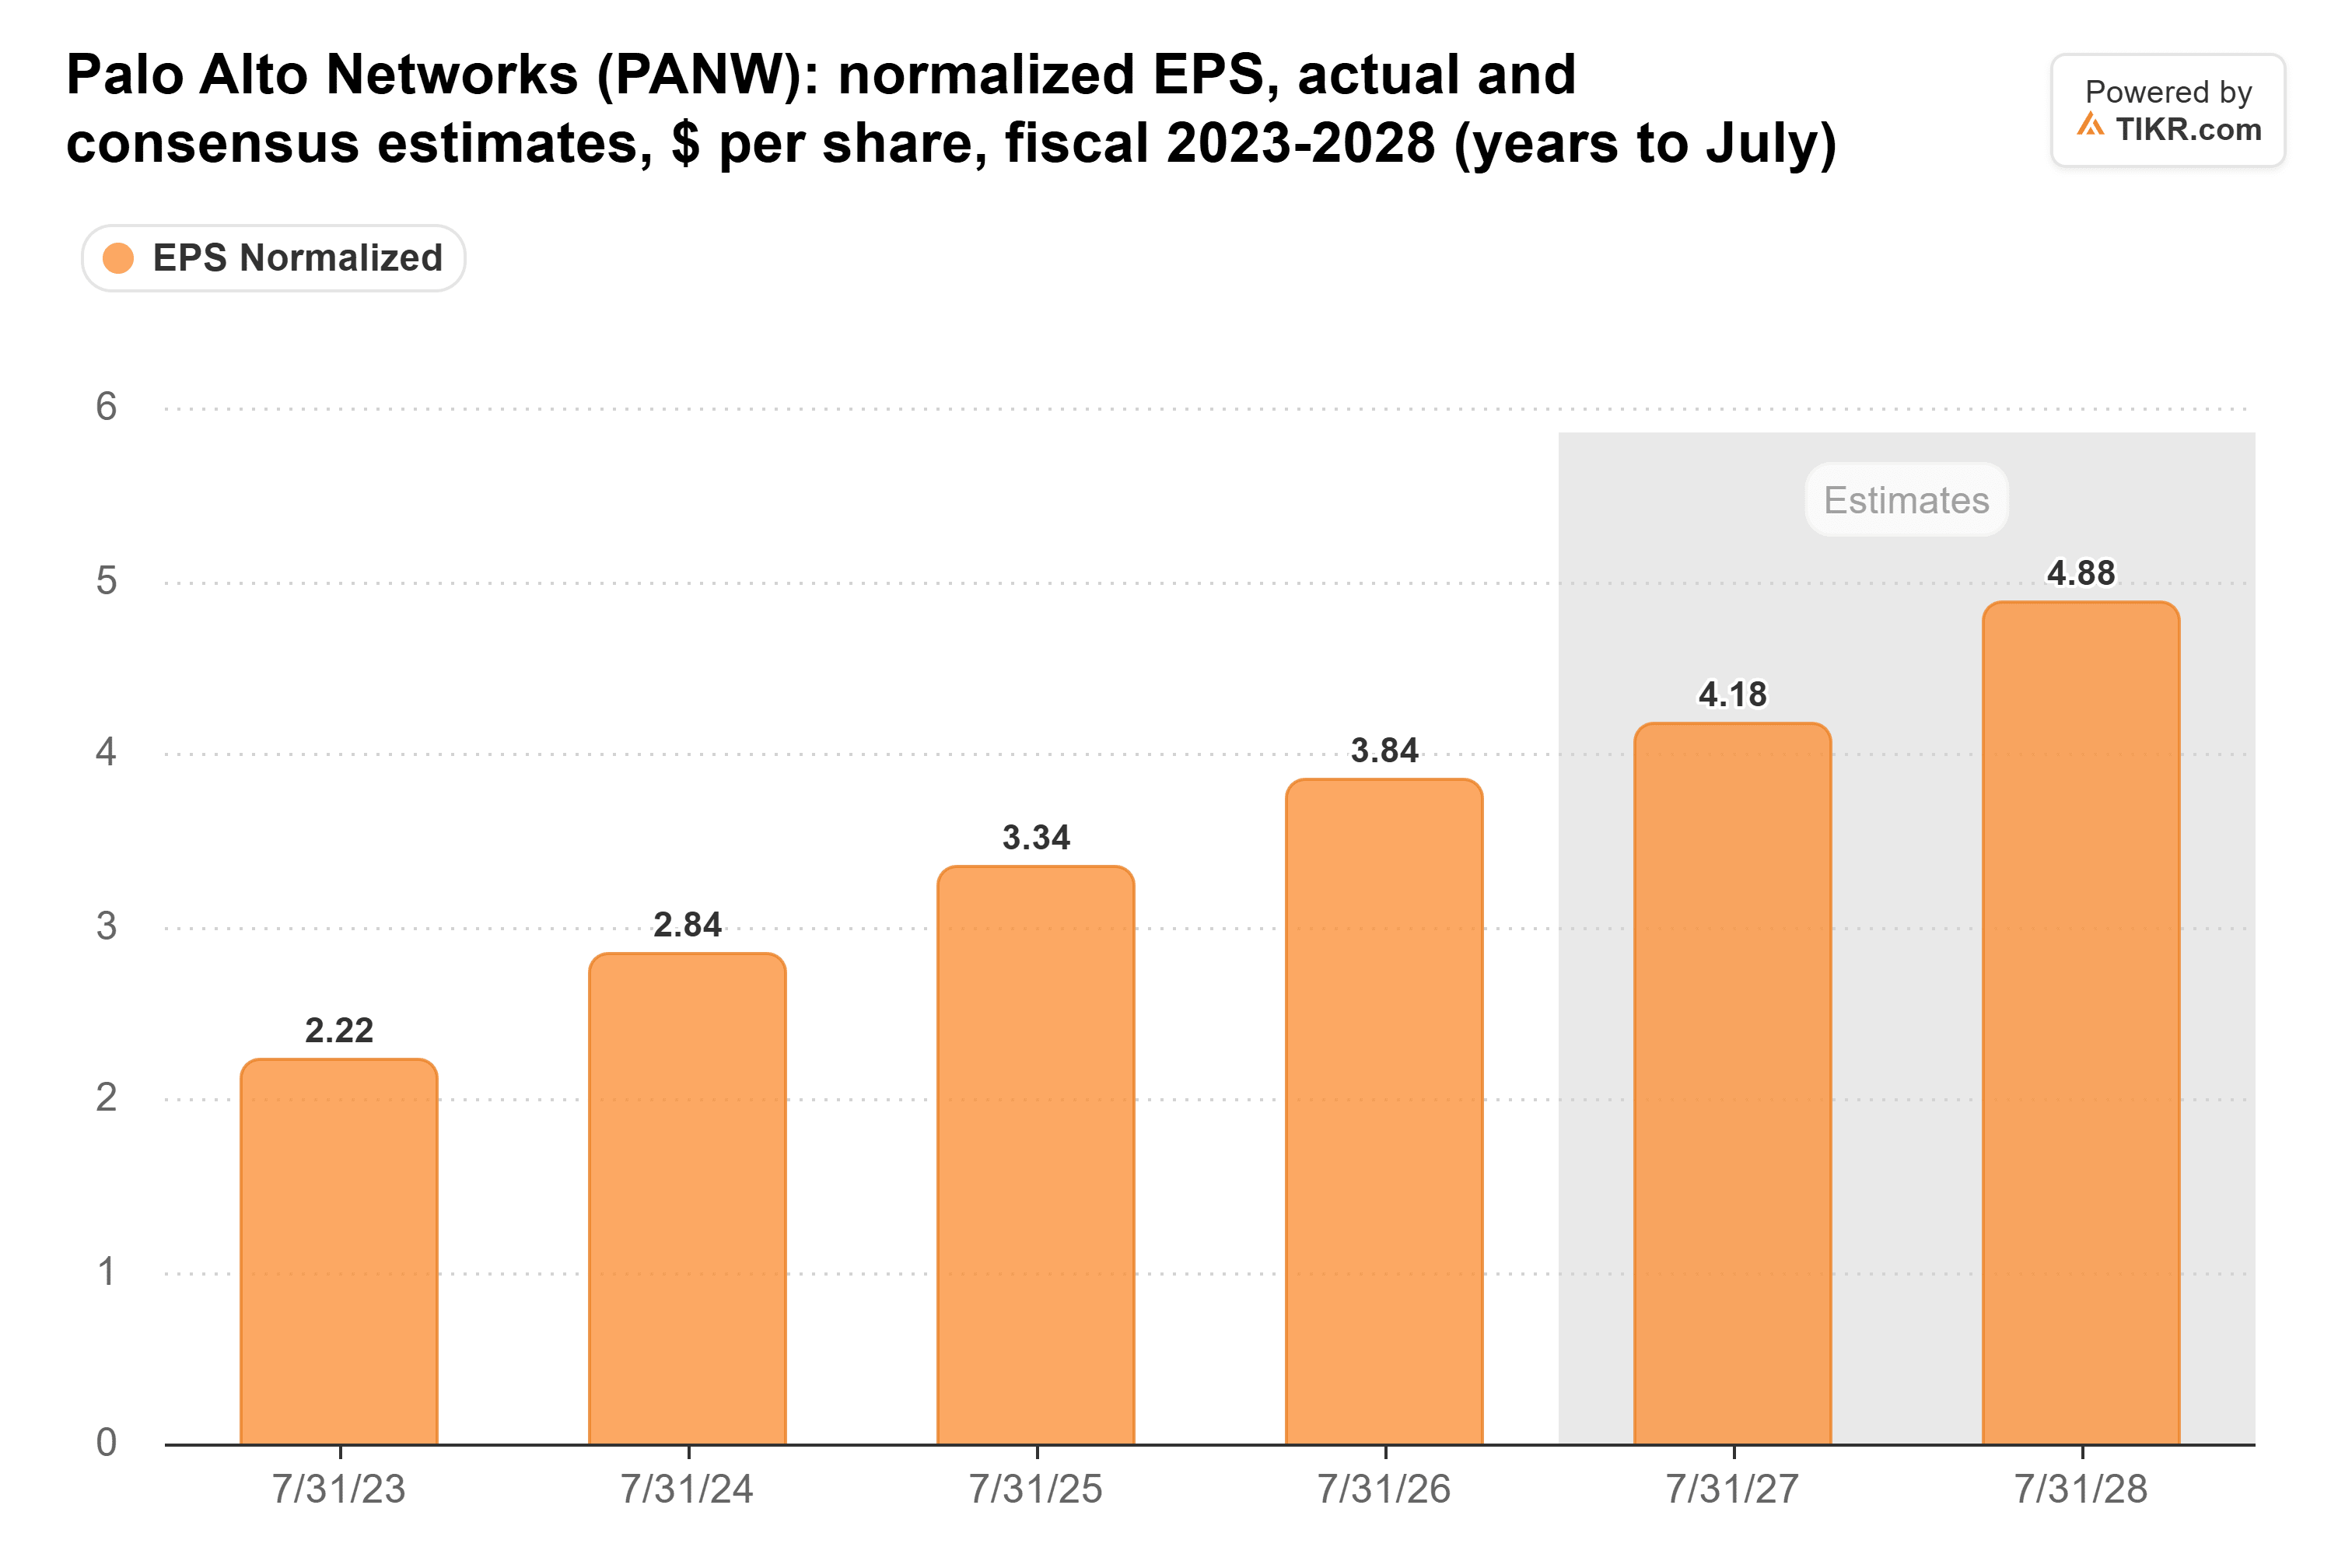
Per-share growth trails the business because Palo Alto paid for CyberArk and Chronosphere mostly in stock. Shares outstanding rose 22%, from 668 million in July 2025 to 818 million in October. That’s why a 25% jump in non-GAAP net income in fiscal 2026 became 15% EPS growth.
Investors are still paying up for those earnings. Palo Alto trades at 76x forward earnings, a third above its five-year average of 57x:
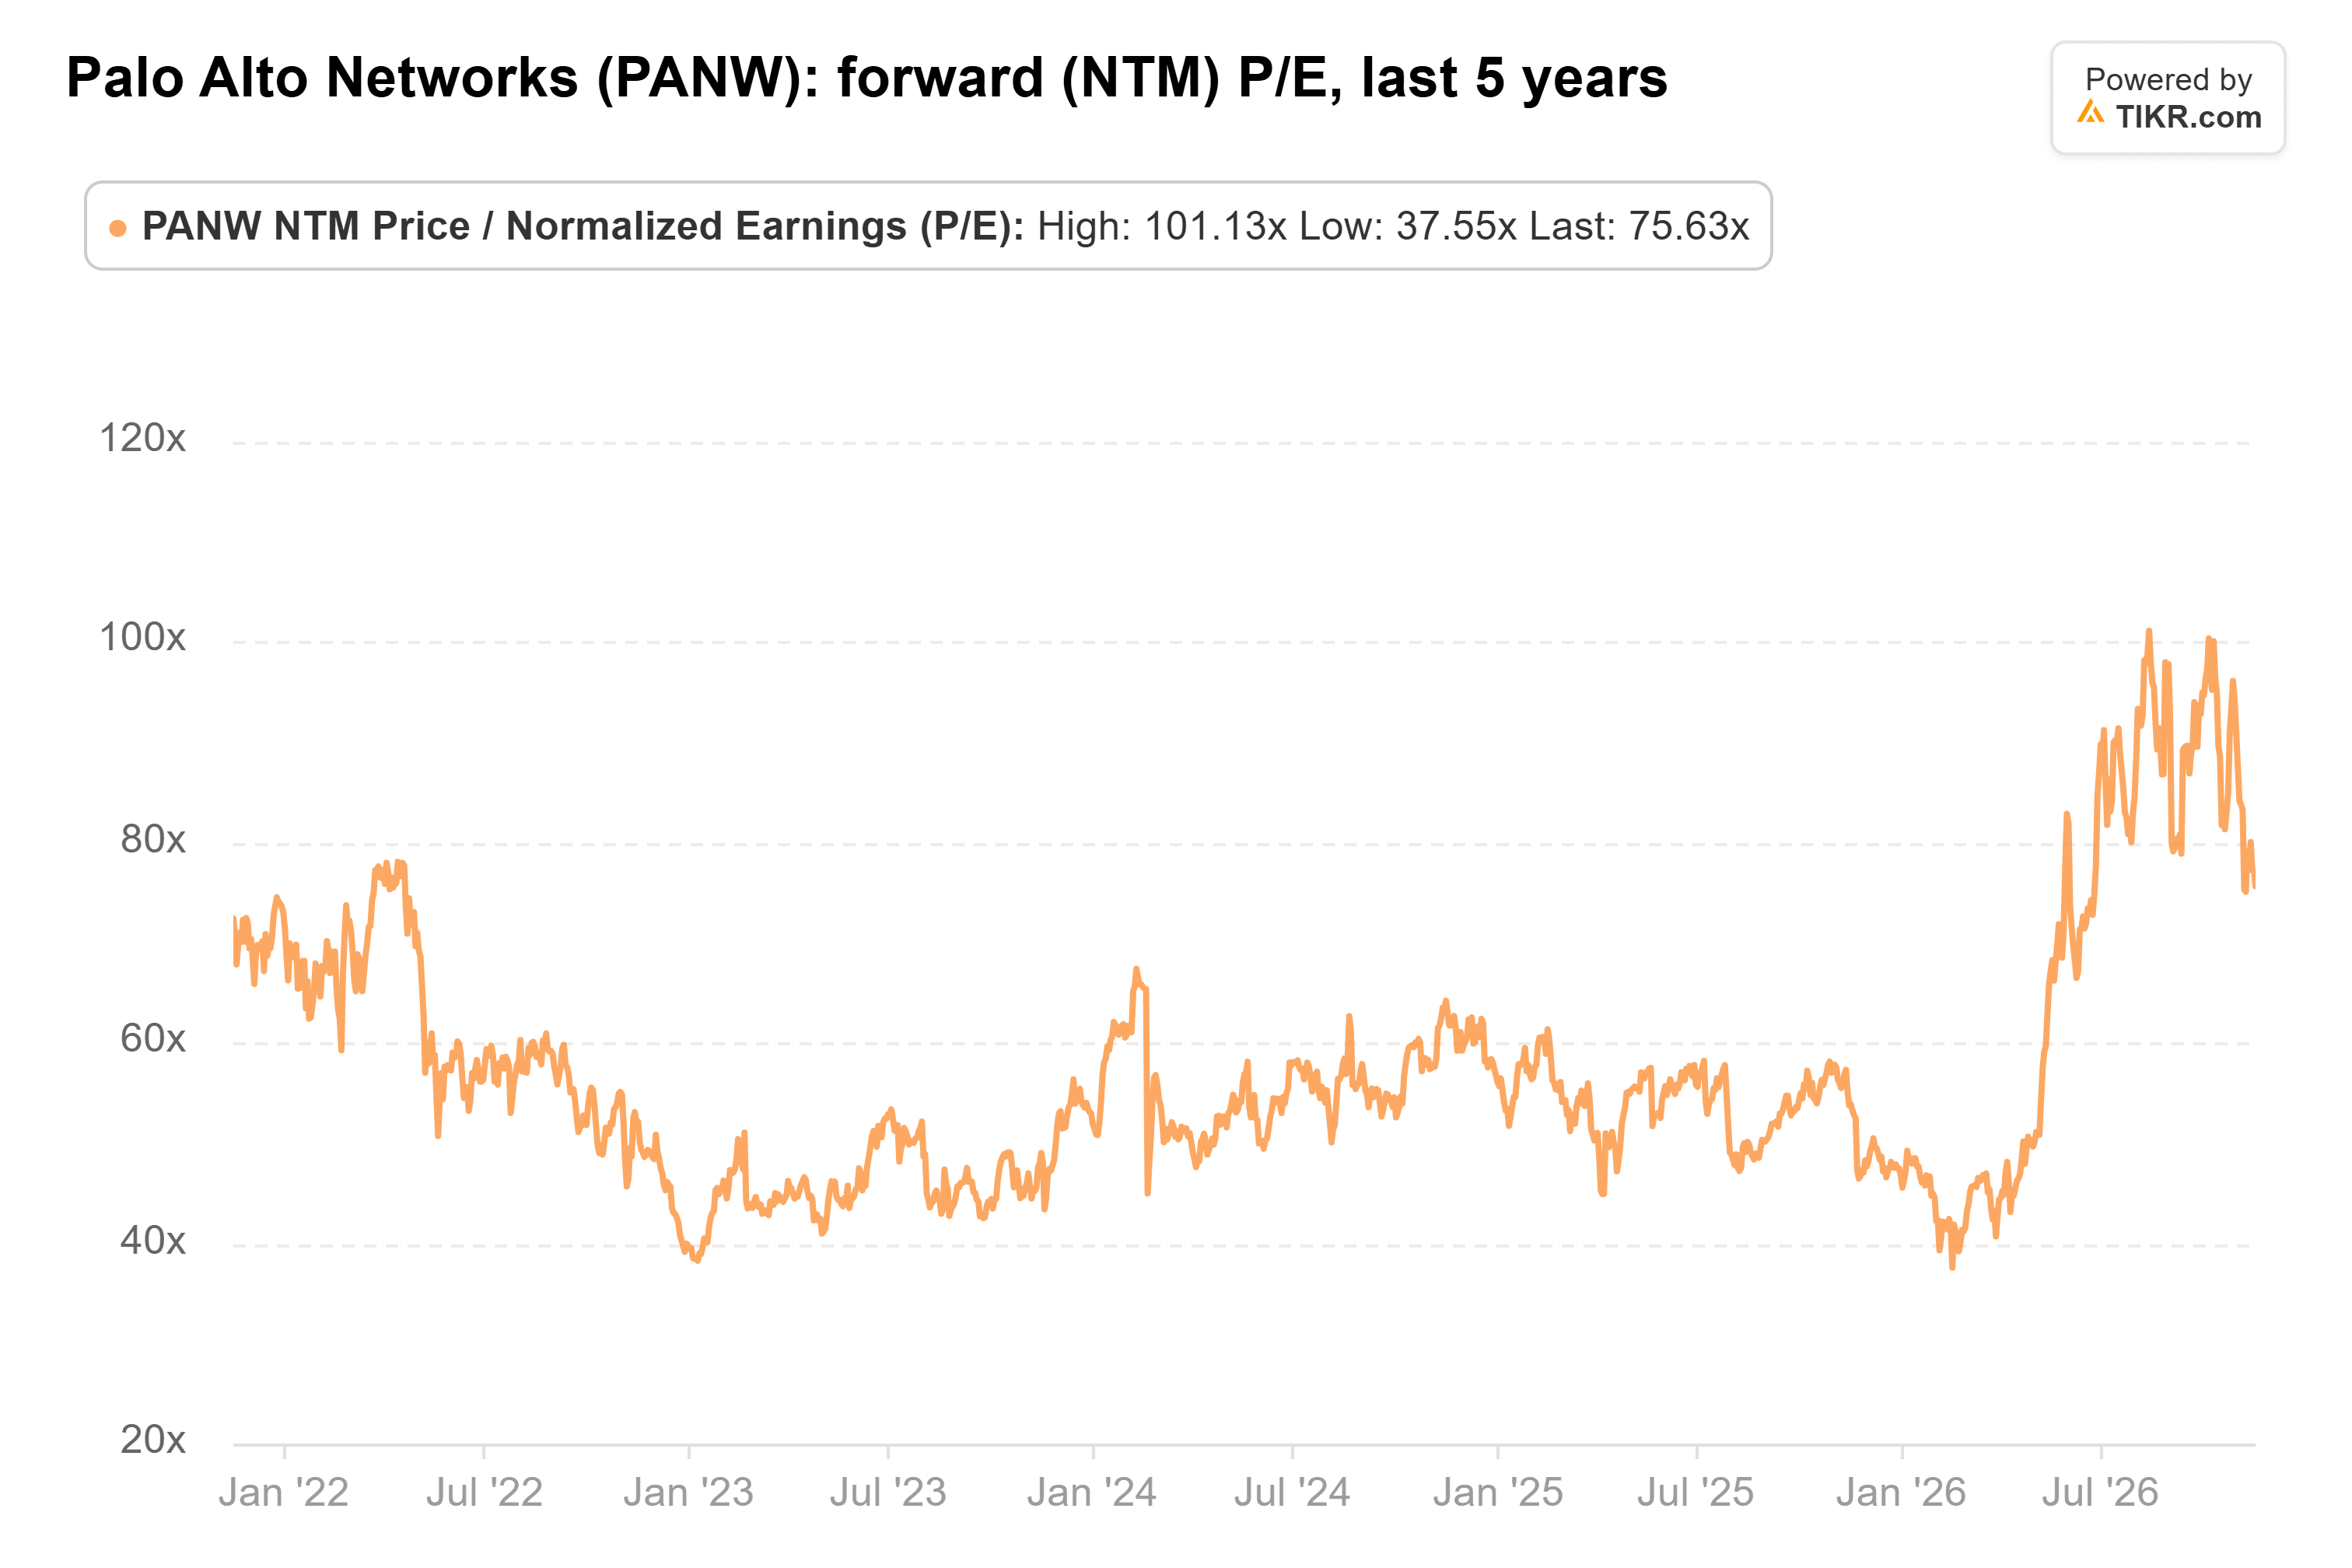
(That’s well off August’s peak of 101x, but the multiple was as low as 38x in February.)
Wall Street’s average target is $399, from 55 analysts, which is 26% above the latest close. That average has climbed from $221 a year ago:
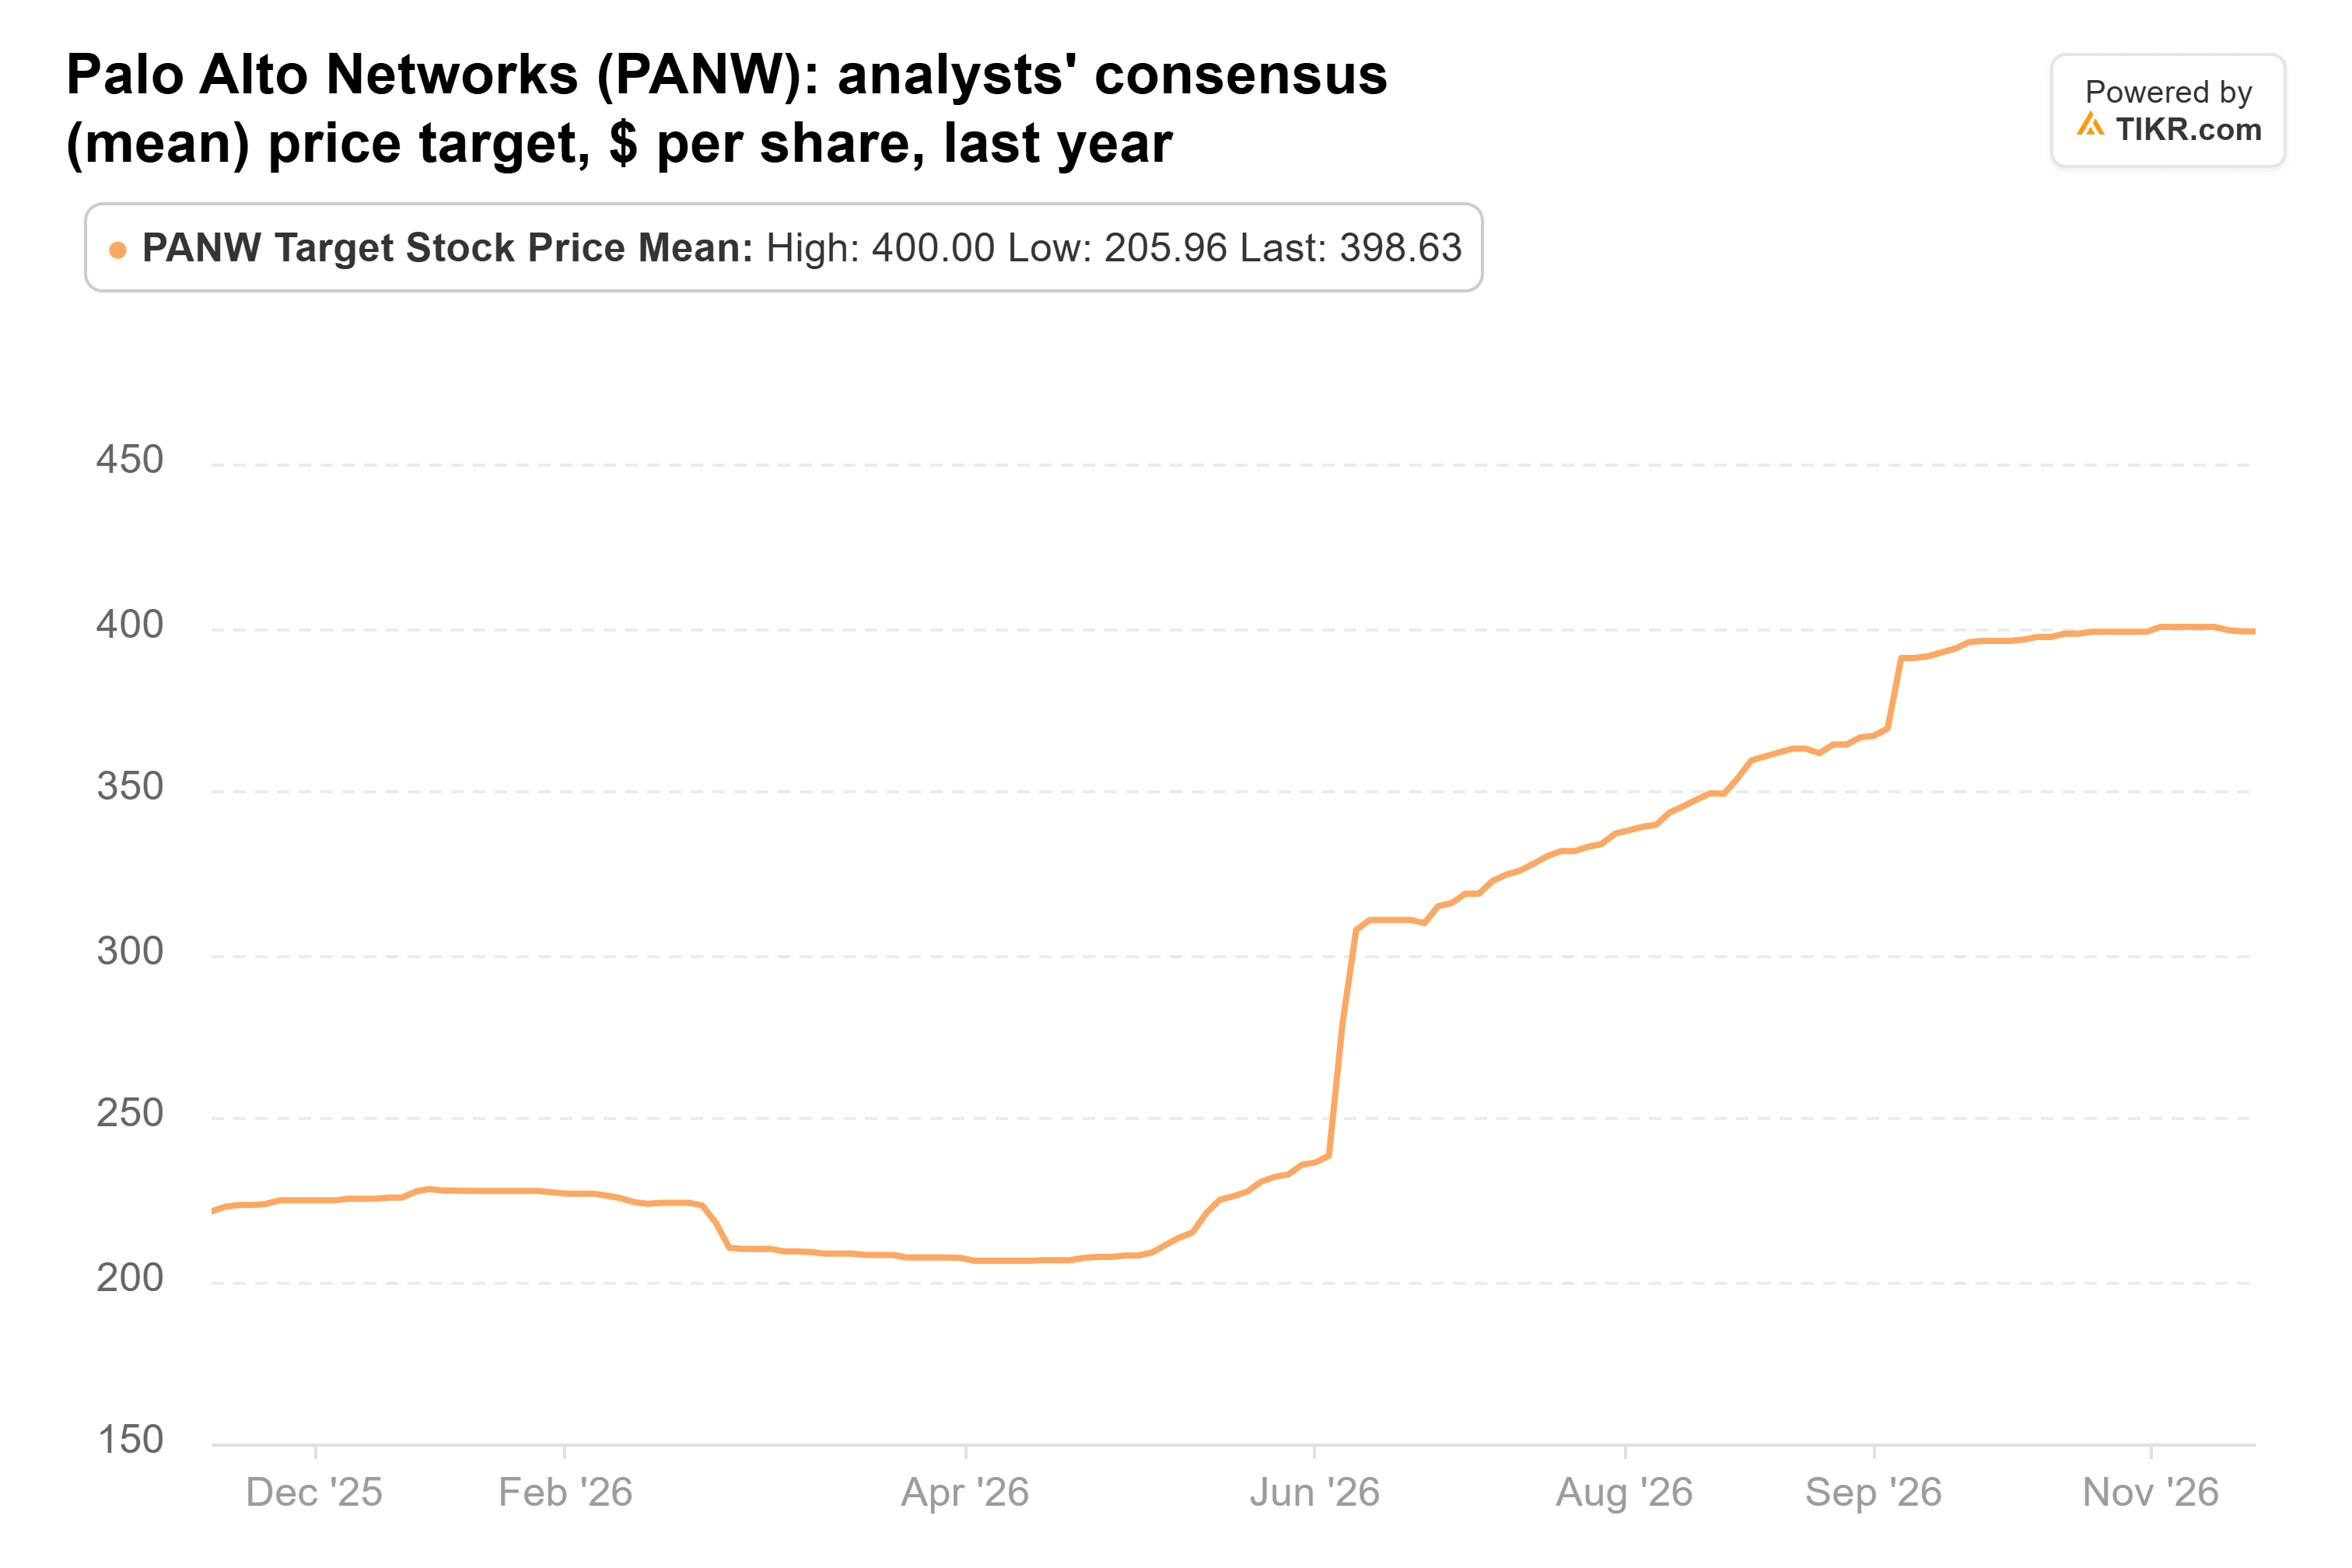
Since the end of September 2025, analysts have raised their fiscal 2027 revenue estimates 19% and cut their EPS estimates 3%. So the targets have climbed on a higher multiple alone.
I’d wait for Nov. 18
Demand looks healthy. Net new next-generation security ARR hit nearly $1 billion in the fiscal fourth quarter, and CEO Nikesh Arora still sees AI as a durable tailwind. A strong quarter could send the stock back toward that $399 average quickly.
Even so, I’d side with the sellers. At 76x forward earnings, Palo Alto is priced for growth its per-share numbers aren’t delivering yet, and I wouldn’t buy before the report.
For the first quarter, management guides to non-GAAP EPS of $0.96 to $0.98 and next-generation security ARR of $9.54 billion to $9.56 billion. Two things would start closing the gap between the multiple and the earnings. One is beating the top of those ranges. The other is a share count on track for the 844 million to 847 million diluted shares guided for the full year. And these funds’ next 13Fs, due in mid-February, will show whether they kept selling.
So what is Palo Alto Networks stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palo Alto Networks could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Palo Alto Networks for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!