

Key Takeaways
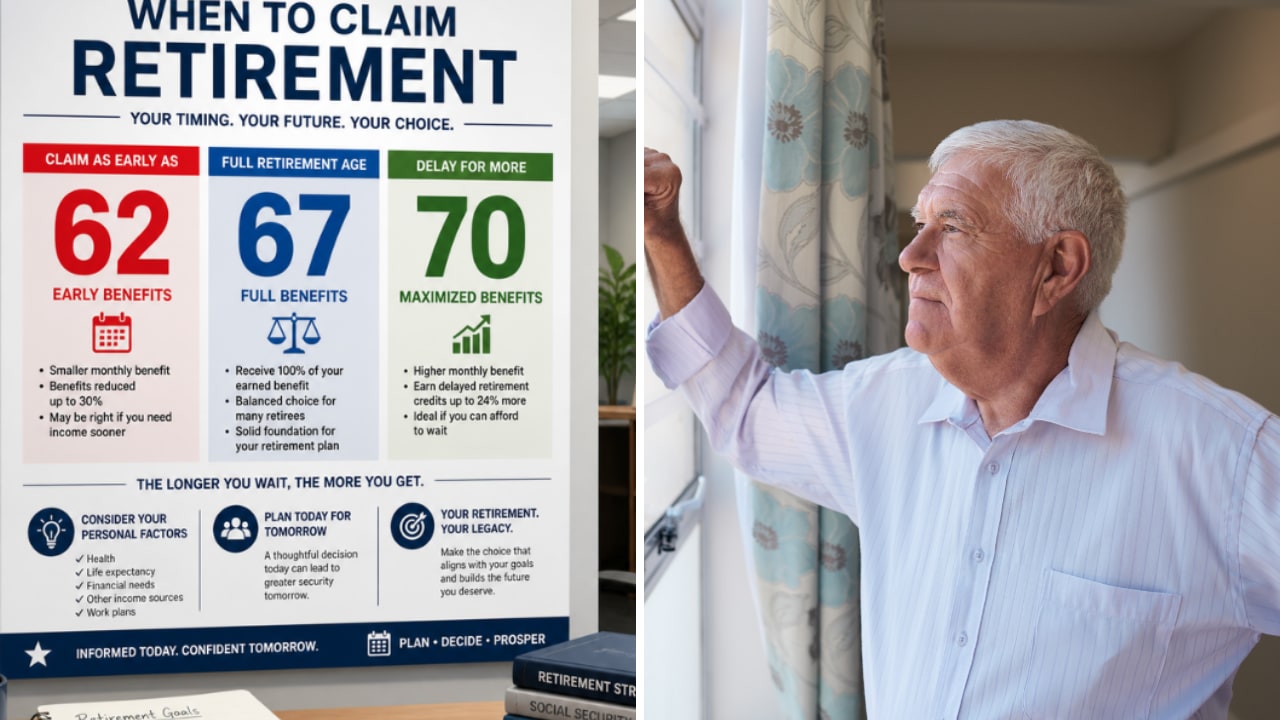
- For anyone born in 1960 or later, claiming Social Security at 62 cuts the monthly benefit by 30% for life, so a $2,000 benefit at 67 becomes $1,400.
- Compared with waiting until 67, claiming at 62 comes out ahead in total until age 78 years and 8 months, so it suits someone who doesn’t expect to live that long.
- A lower earner whose spouse waits until 70 can claim at 62, because a surviving spouse gets the higher of their own benefit and the survivor benefit, never both.
- Before full retirement age, Social Security withholds $1 for every $2 earned above $25,560 in 2027, so claiming at 62 works best for someone who has stopped working.
Claiming Social Security at 62 is usually a mistake. For anyone born in 1960 or later, it cuts the monthly benefit by 30%, and that cut lasts for life.
But usually isn’t always. I see three situations where taking the money at 62 makes sense, and one of them depends on a limit Social Security set for 2027 this month.
What claiming at 62 costs
Let’s take a hypothetical worker born in 1960 or later whose benefit at full retirement age, 67, would be $2,000 a month. Claim at 62, and Social Security pays $1,400 instead.
Claiming early gets this worker 60 checks of $1,400, or $84,000, before a claim at 67 would have paid a cent. From 67 on, though, waiting would have meant $600 more every month. Divide $84,000 by $600, and it takes 140 months, or 11 years and 8 months, to close that gap.
So this worker comes out ahead by claiming at 62 until 78 years and 8 months, and falls further behind every month after that.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
1. You don’t expect to see your late 70s
If your health or your family history says you probably won’t live past your late 70s, the smaller checks at 62 add up to more money.
Of course, aside from being a totally morbid conclusion, let’s face it – nobody knows for sure, and anyone who outlives the odds keeps the smaller check for life.
A married higher earner also has more than their own lifespan to weigh. Social Security reduces a widow or widower’s benefit when the late spouse took a reduced retirement benefit. So claiming at 62 can shrink the check a surviving spouse has to live on.
2. You’re the lower earner, and your spouse is waiting until 70
The lower earner can afford to claim early, thanks to those same survivor rules. A widow or widower who waits until full retirement age gets 100% of the late spouse’s benefit, plus the delayed retirement credits the late spouse earned. Those credits add 8% for each year past 67, until 70.
Say the higher earner is our hypothetical worker and waits until 70. Three years of credits add 24% to that $2,000, for $2,480 a month. If they die first, after reaching 70, a surviving spouse at full retirement age gets that same $2,480. (The survivor benefit is smaller if it’s taken earlier.)
Social Security never pays someone entitled to two benefits more than the highest single one. So once the survivor benefit starts, the lower earner’s own reduced check no longer matters, as long as it’s under $2,480. Their early claim costs them money only while both spouses are alive.
That’s why I like this split. The lower earner gets income coming in at 62, and by waiting, the higher earner locks in the bigger check for whichever spouse lives longer.
3. You’ve stopped working and need the money
Taking benefits at 62 while still drawing a paycheck runs into Social Security’s earnings test. Before the year a claimer reaches full retirement age, Social Security withholds $1 of benefits for every $2 of earnings above a yearly limit. That limit is $24,480 in 2026, rising to $25,560 in 2027.
But someone who has stopped working, has no other income, and can’t get by on their savings…needs money now. Even if it’s less than they’d get by waiting. No one should starve themselves now trying to get a little extra money later. Life is meant to be lived and enjoyed.
You get one do-over
Frankly, if I could afford to wait, I’d wait. A smaller check for life is a steep price for most people. But in these three cases, taking the money at 62 is the better deal.
And if circumstances change, there’s a way back. Within 12 months of first being entitled, a retiree can withdraw a claim once, in writing, by paying back every benefit received, and apply again later. So someone who claims at 62 and then lands a job, or gets a windfall, has a year to change their mind.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



