Key Takeaways
- Barclays cut its Arm Holdings price target to $325 from $360 on Nov. 5 but kept its Overweight rating. That target is [69%] above the Nov. 4 close.
- Barclays is counting on licensing revenue, up 50% last quarter, and on Arm’s new data center chip, while royalties grew just 8%.
- The target is 136x the earnings analysts expect over the next 12 months, but closer to 87x on the year after that, near Arm’s 85x three-year average.
- That makes $325 a bet that out-year estimates survive slowing royalties, and I’d want to see that first.
Arm Holdings (ARM) has lost more than half its value since June 18, and Barclays still sees a big rebound. On Thursday, after Arm’s second-quarter report, analyst Thomas O’Malley cut his price target to $325 from $360 and kept his Overweight rating. That’s [69%] above Wednesday’s [$191.80] close.
The Bad News Piled Up
On Oct. 29, Intel (INTC) guided fourth-quarter revenue to $15 billion to $16 billion, below the $17.1 billion analysts expected, and blamed a shortage of packaging substrates. Arm needs those for its own data center chip, the AGI CPU, and it fell nearly 10% on the warning.
Then on Wednesday, Arm’s royalties grew just 8% to $670 million, short of its low-teens guidance, as higher memory prices cut into phone sales. Arm expects royalty growth to slow to the low single digits this quarter.
Barclays Is Betting on Licensing and the Chip
Barclays’ case leans on licensing, which jumped 50% to $773 million, well ahead of the roughly 30% growth Arm itself had guided. O’Malley expects licensing growth to speed up again in the December quarter.
He also raised his AGI CPU estimate to about $1.5 billion from $1.1 billion. CEO Rene Haas said on the call that Arm’s confidence in “achieving up to $2 billion of revenue in Arm AGI CPU across fiscal 2027 and 2028” has grown in the past 90 days.
TIKR Tracks 43 Analysts on Arm Holdings. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arm Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arm Holdings’ Analyst Ratings
Does $325 Add Up?
The consensus target climbed to $291 on Nov. 2 from $158 a year earlier, and has held there since the summer.
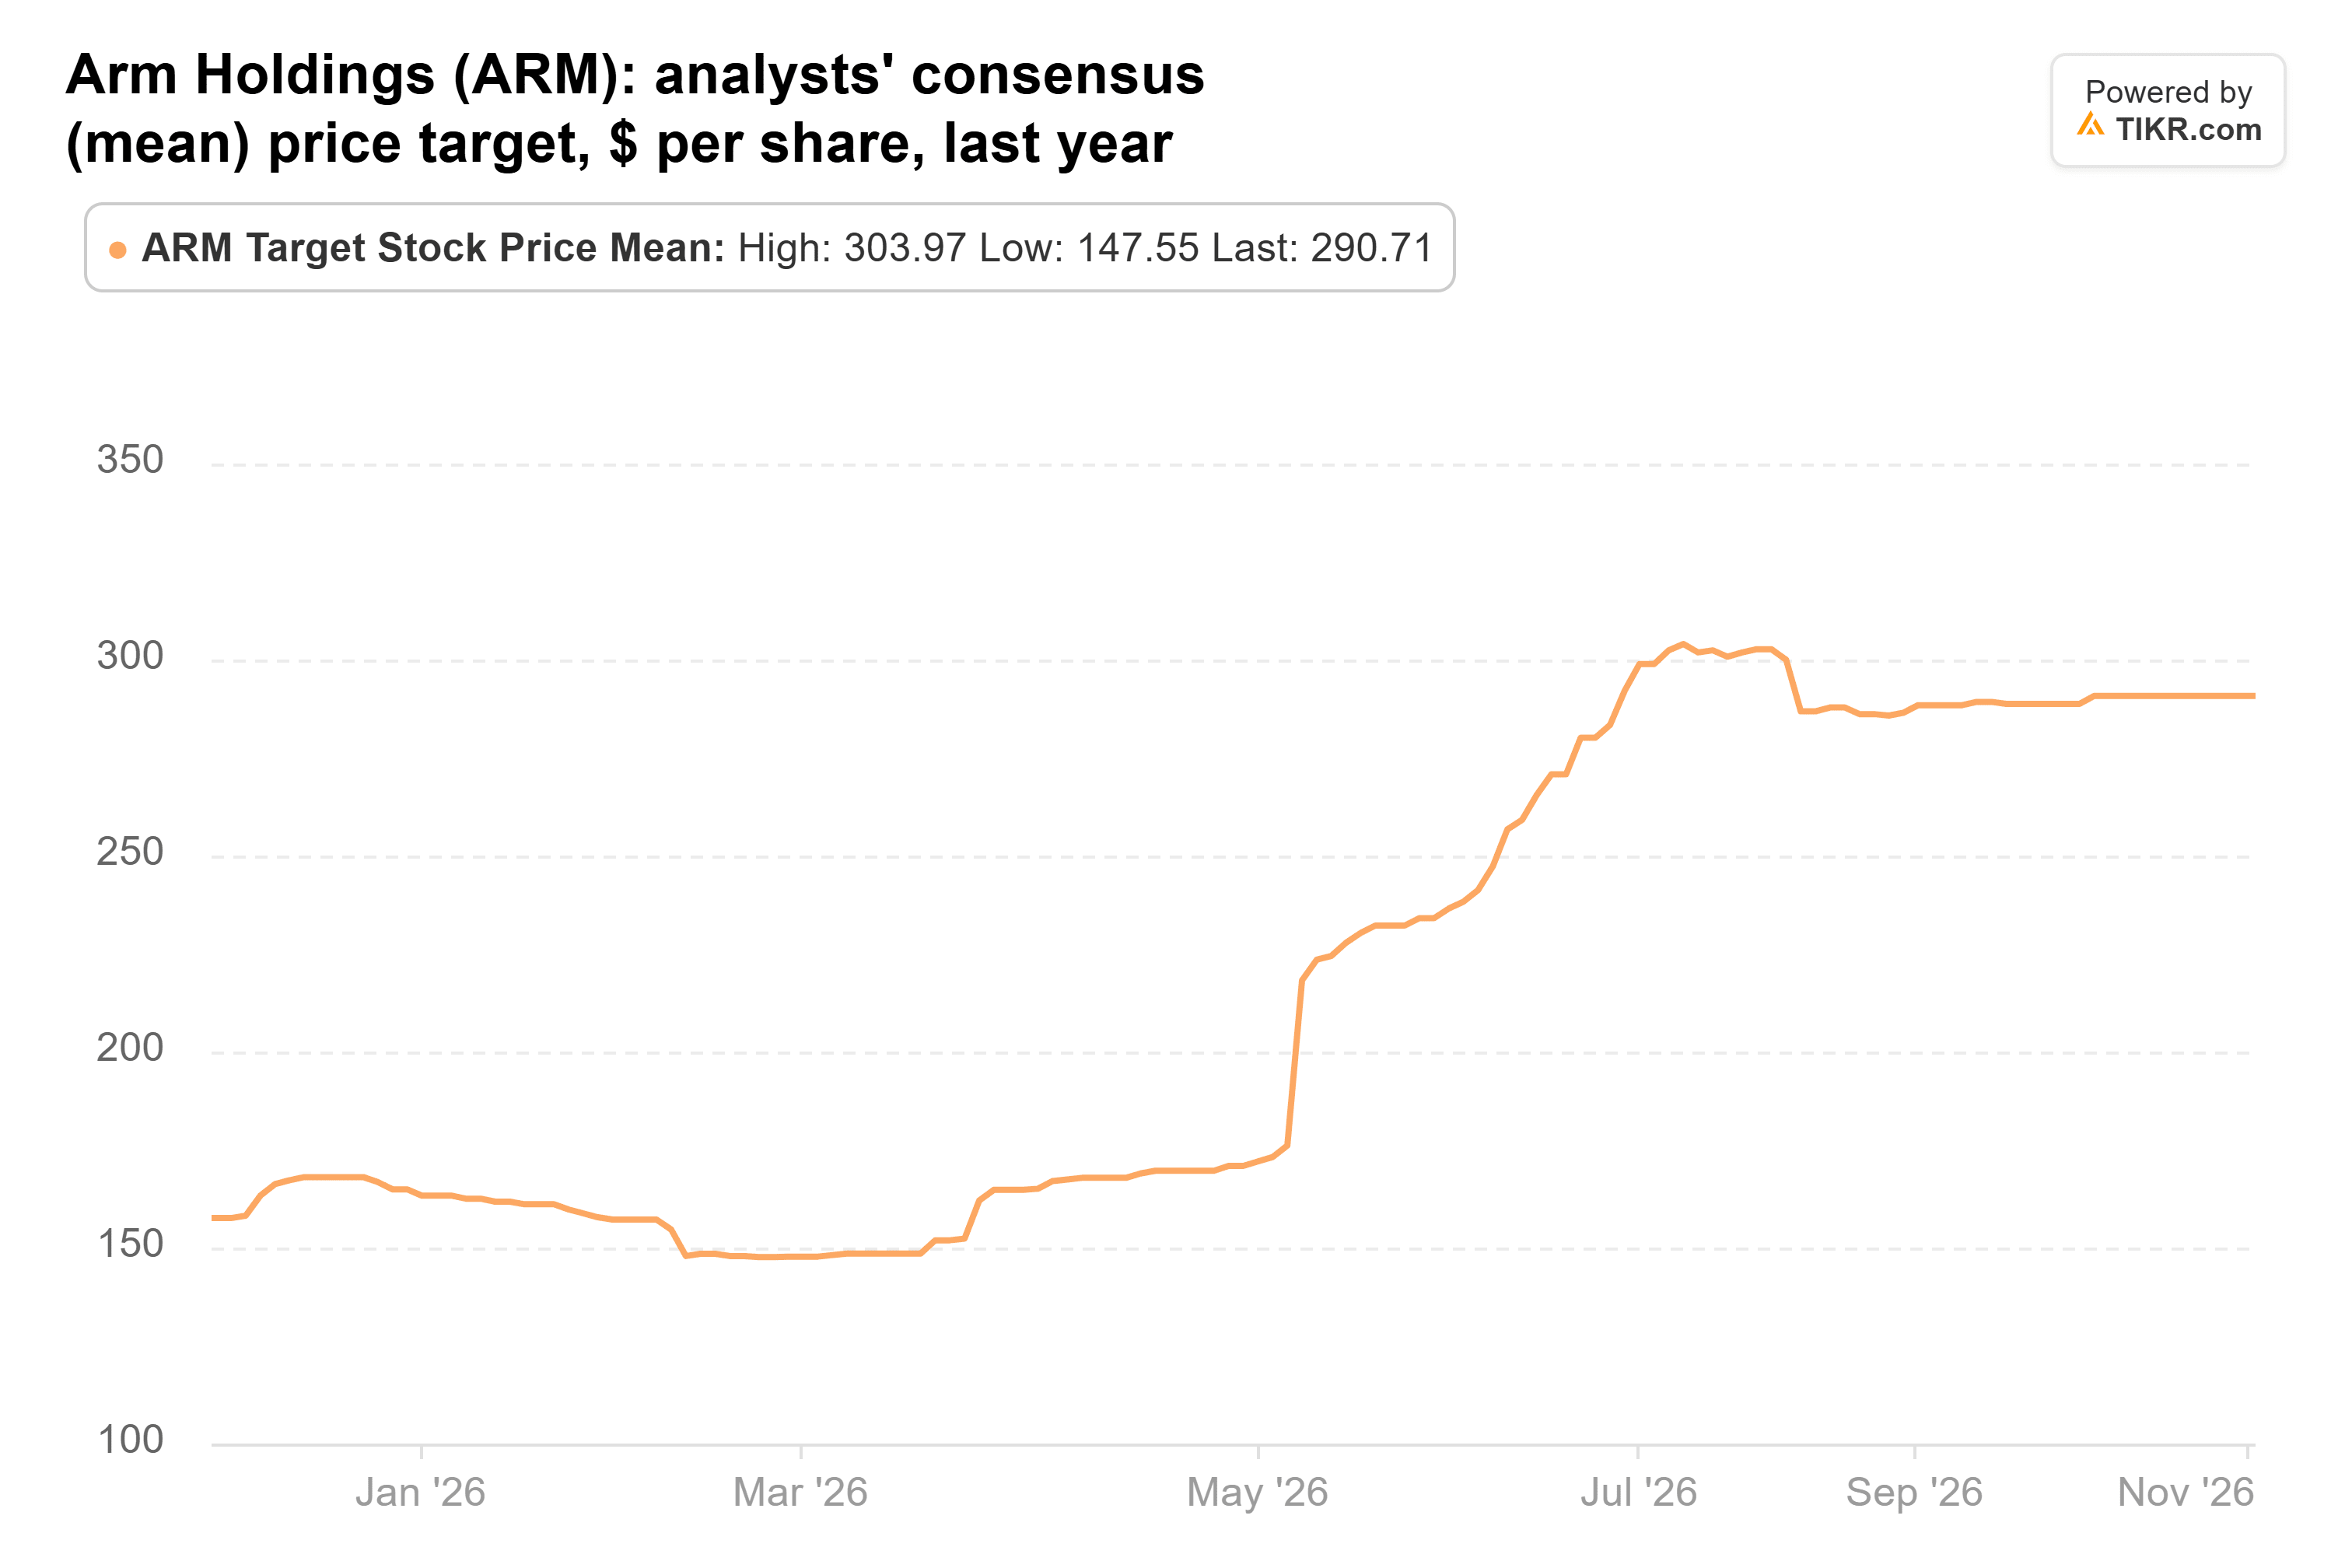
Targets run from $125 to $500, and Barclays’ $325 sits 12% above the consensus.
Earnings estimates held too, at least heading into the report. Fiscal 2027’s consensus (the year to March 2027) is $2.23 a share, the same as 90 days ago, and fiscal 2028’s is $3.06, against $3.07.

So the selloff is about what investors will pay. Arm’s forward P/E was 82x on Nov. 2, down from 202x at the June 18 peak and just under its 85x three-year average.

On the $2.39 a share analysts expect over the next 12 months, $325 works out to 136x. But a target is a one-year call. By next November, the forward window is mostly fiscal 2029, where the consensus is $4.05, and $325 drops to about 87x, close to that average.
I’d Wait for February
So Barclays doesn’t need June’s multiple back. It needs the fiscal 2029 numbers to hold, and those were set before this quarter’s royalty miss. Qualcomm adds risk too: a judge still has to rule on whether it can stop paying Arm royalties for five years, after a jury found on Oct. 13 that Arm breached its license.
I wouldn’t count on $325 until those estimates survive the post-report revisions. Arm said in July it would give a fuller chip update with its fiscal third-quarter results, expected in early February. A firm forecast that backs up the $2 billion, with royalties steadying, would make $325 look a lot more reasonable.
So What Is Arm Holdings Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Arm Holdings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!