Key Takeaways
- Williams-Sonoma fell 14% after its third-quarter results came in just below estimates and it only reiterated its fiscal 2026 outlook.
- Excluding a one-time tariff refund, gross margin barely moved as higher oil prices raised supply-chain costs.
- RH faces the same oil-driven costs, and Wayfair’s comments suggest Williams-Sonoma is still taking share.
- The stock traded at 26x forward earnings before the drop, against a 16x five-year average.
Williams-Sonoma (WSM) sank 14% this morning after its third-quarter results came up just short of estimates and management only reiterated its full-year outlook.
Demand held up, but margins needed a tariff refund, and higher oil prices are squeezing RH (RH) too. Meanwhile, the latest numbers from Wayfair (W) suggest Williams-Sonoma is still winning share.
Two cents short, and no raise
Adjusted EPS rose 11.7% to $2.19, against the $2.21 analysts expected. Revenue rose 5.8% to $1.99 billion, a hair under expectations. Comparable brand revenue grew 5.1%. That’s share-taking: Wayfair’s U.S. revenue grew 11.4% in its quarter to Sept. 30, and CEO Niraj Shah said that growth came “against a roughly flat category.” (At 29x forward earnings, Wayfair needs those gains to keep coming.)
Analysts expected earnings to grow about 8% this year and 11% next:
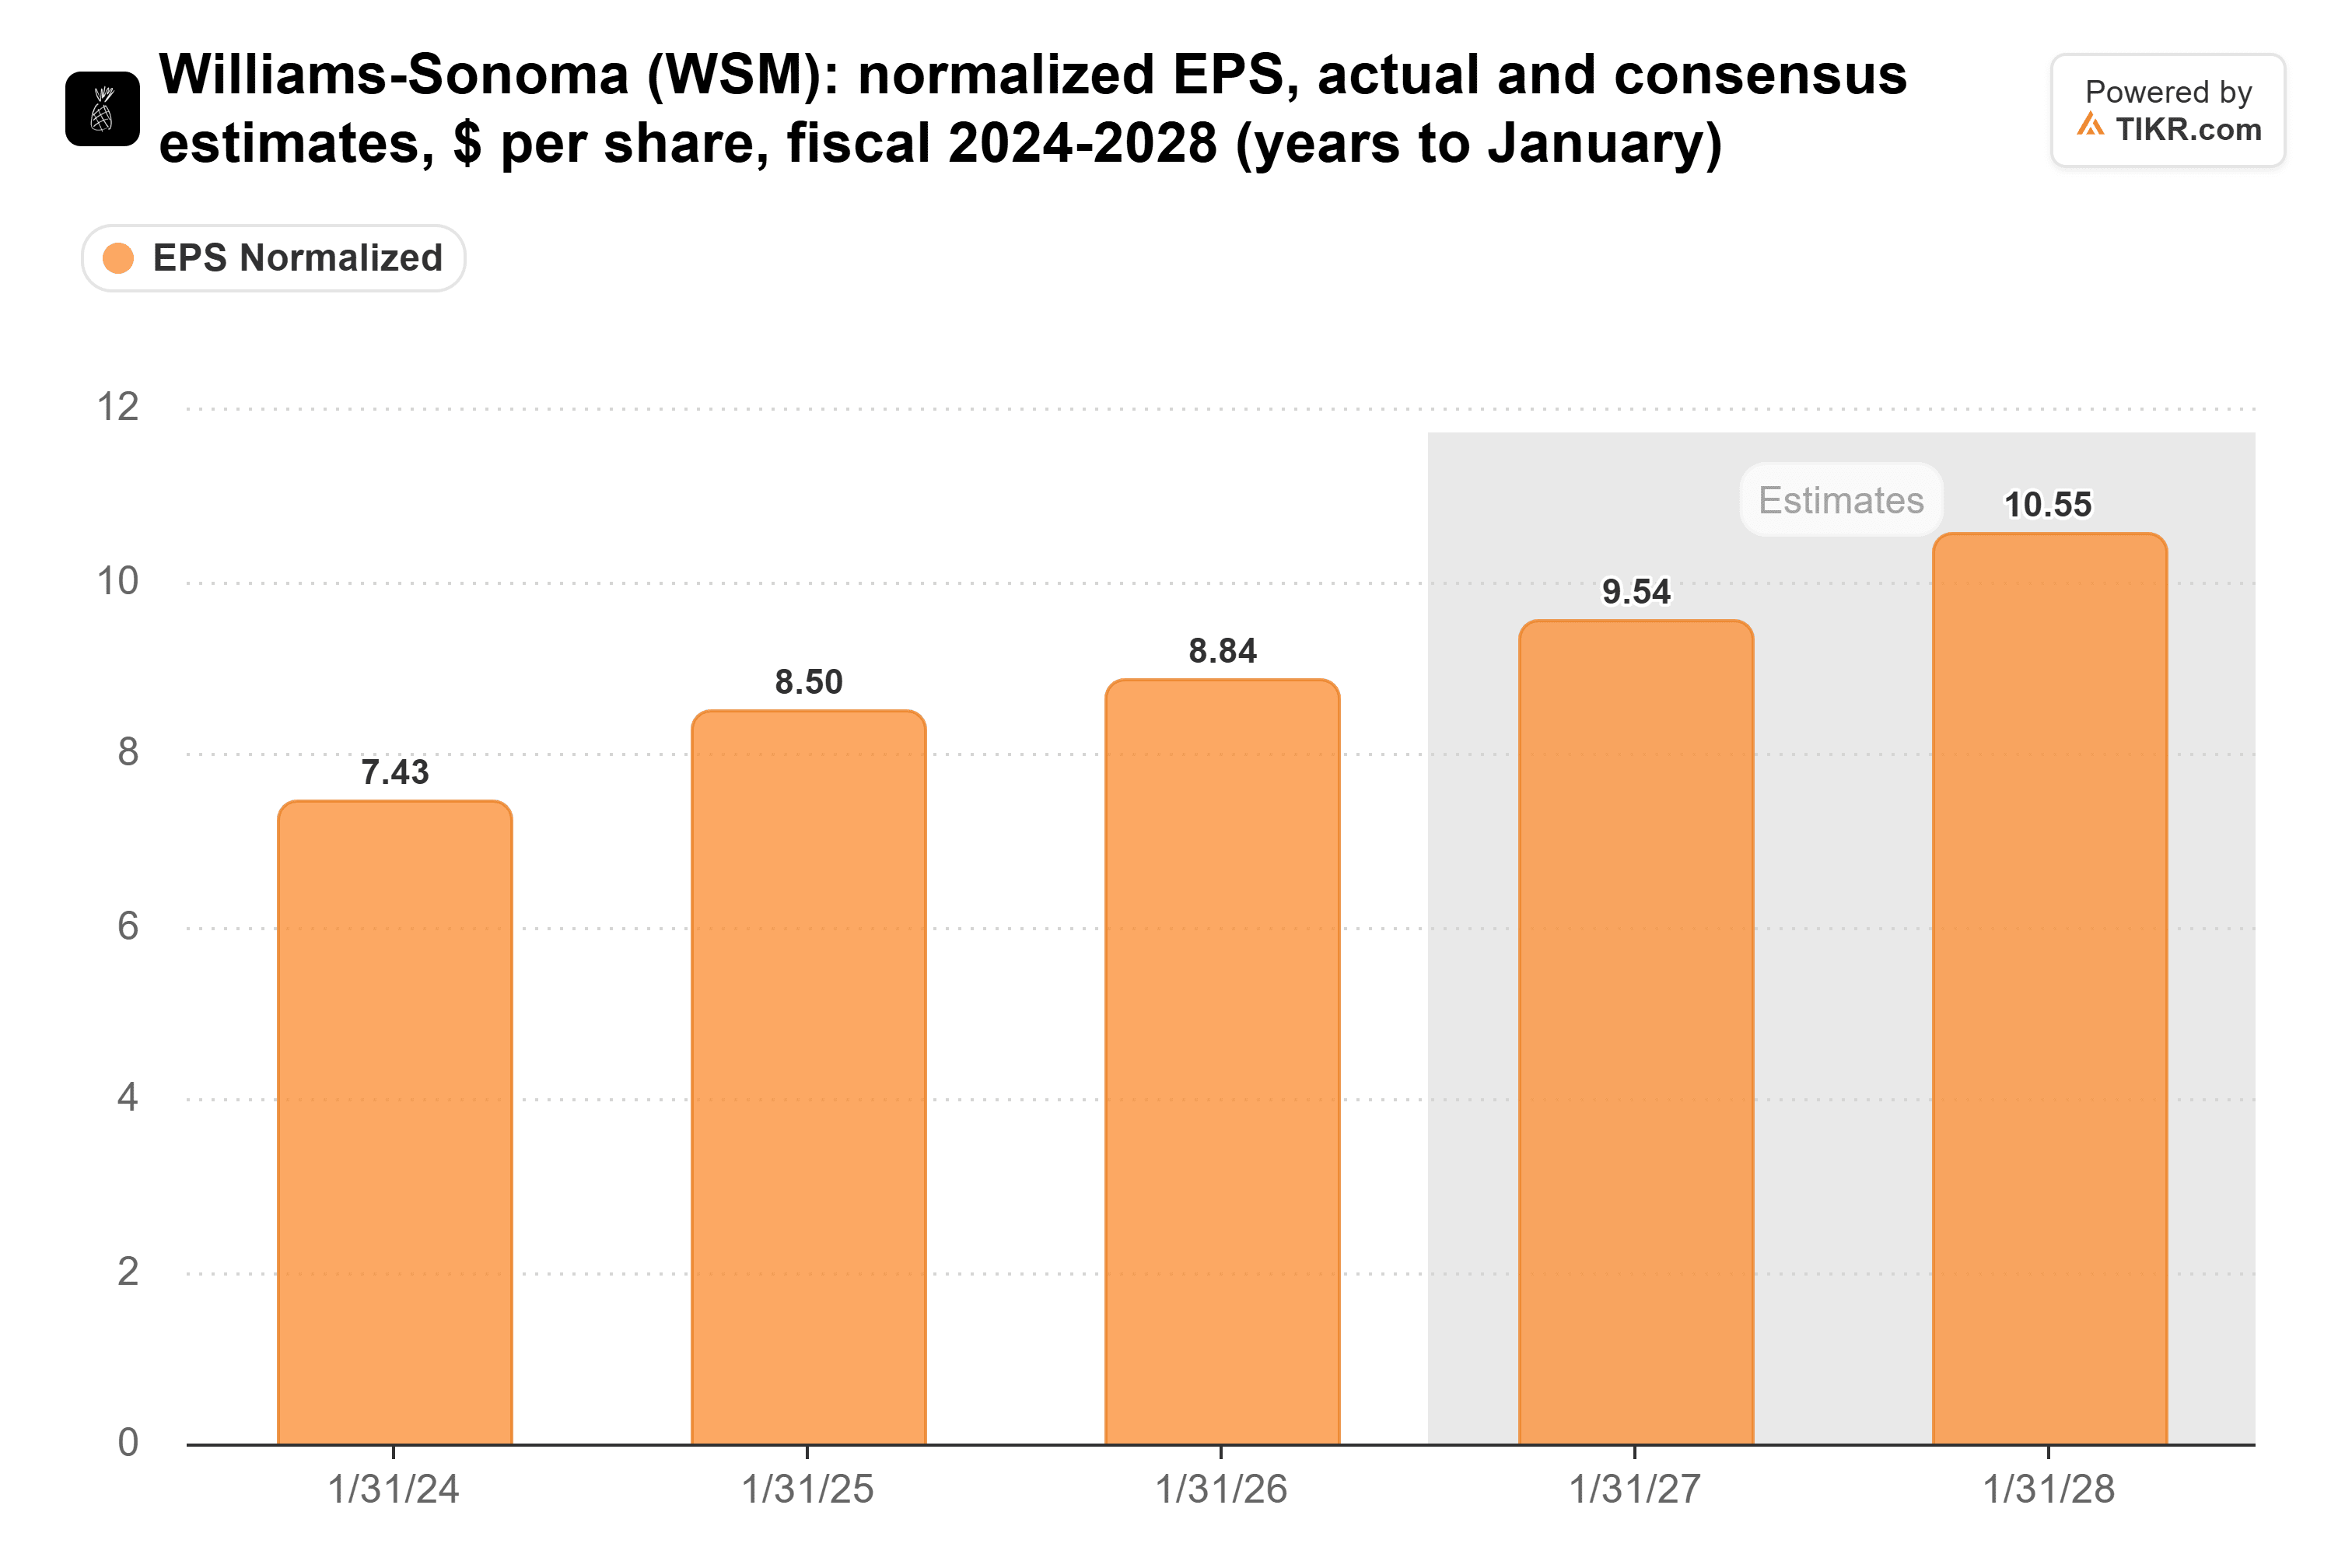
Those estimates predate the report, and nothing in it should push them higher. To hit this year’s $9.54, Williams-Sonoma needs about $3.31 a share in the holiday quarter, roughly 10% more than a year ago.
TIKR tracks 24 analysts on Williams-Sonoma. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Williams-Sonoma, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Williams-Sonoma’s Analyst Ratings
The tariff refund did the heavy lifting
GAAP EPS jumped 21.4% to $2.38, but $0.19 of that came from a $29.3 million IEEPA tariff refund. Gross margin swings with the seasons, so compare the same quarter a year ago:
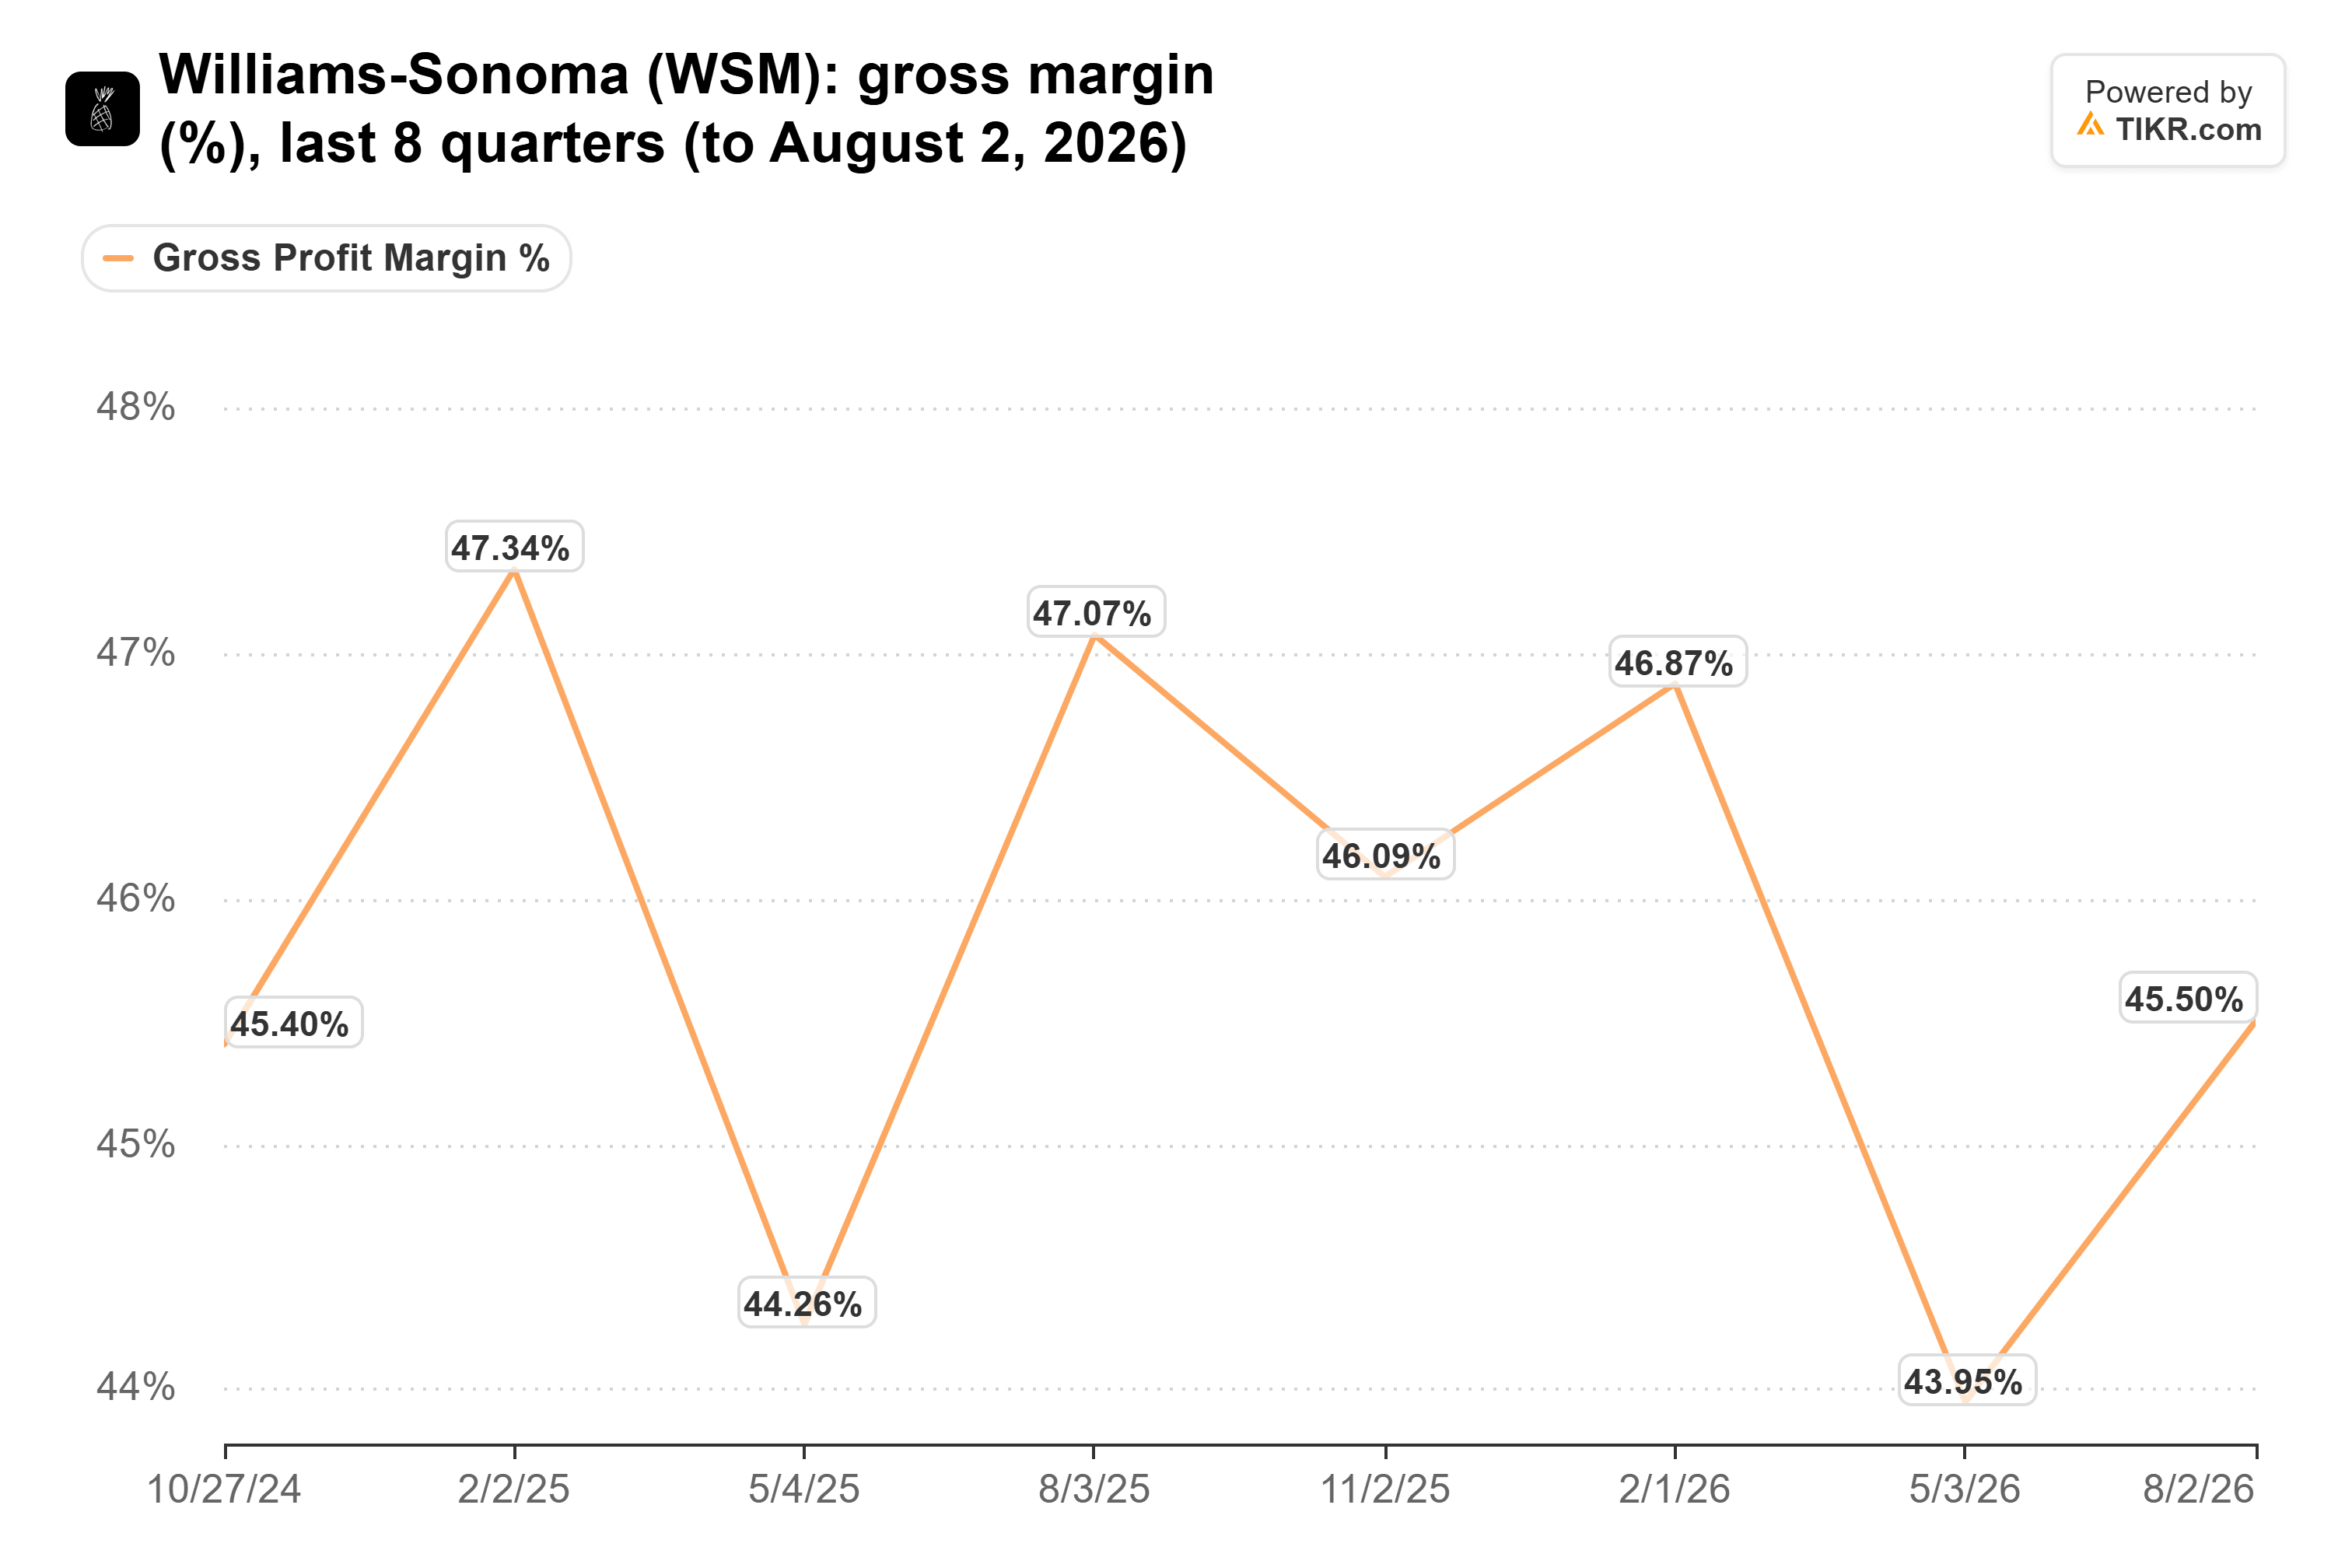
That quarter came in at 46.1%. This one was 47.6% as reported and 46.2% without the refund, because oil-driven supply-chain costs took back 50 basis points.
RH flagged the same squeeze in September: CEO Gary Friedman wrote in its second-quarter shareholder letter that RH would use the rest of its own tariff refund to offset “$50 million of unplanned cost increases across our supply chain” as oil prices spiked. When RH reports in mid-December, its margin without the refund will show whether the whole premium home group has a problem.
Priced for more
Going into the report, Williams-Sonoma’s valuation sat near the top of its own range:
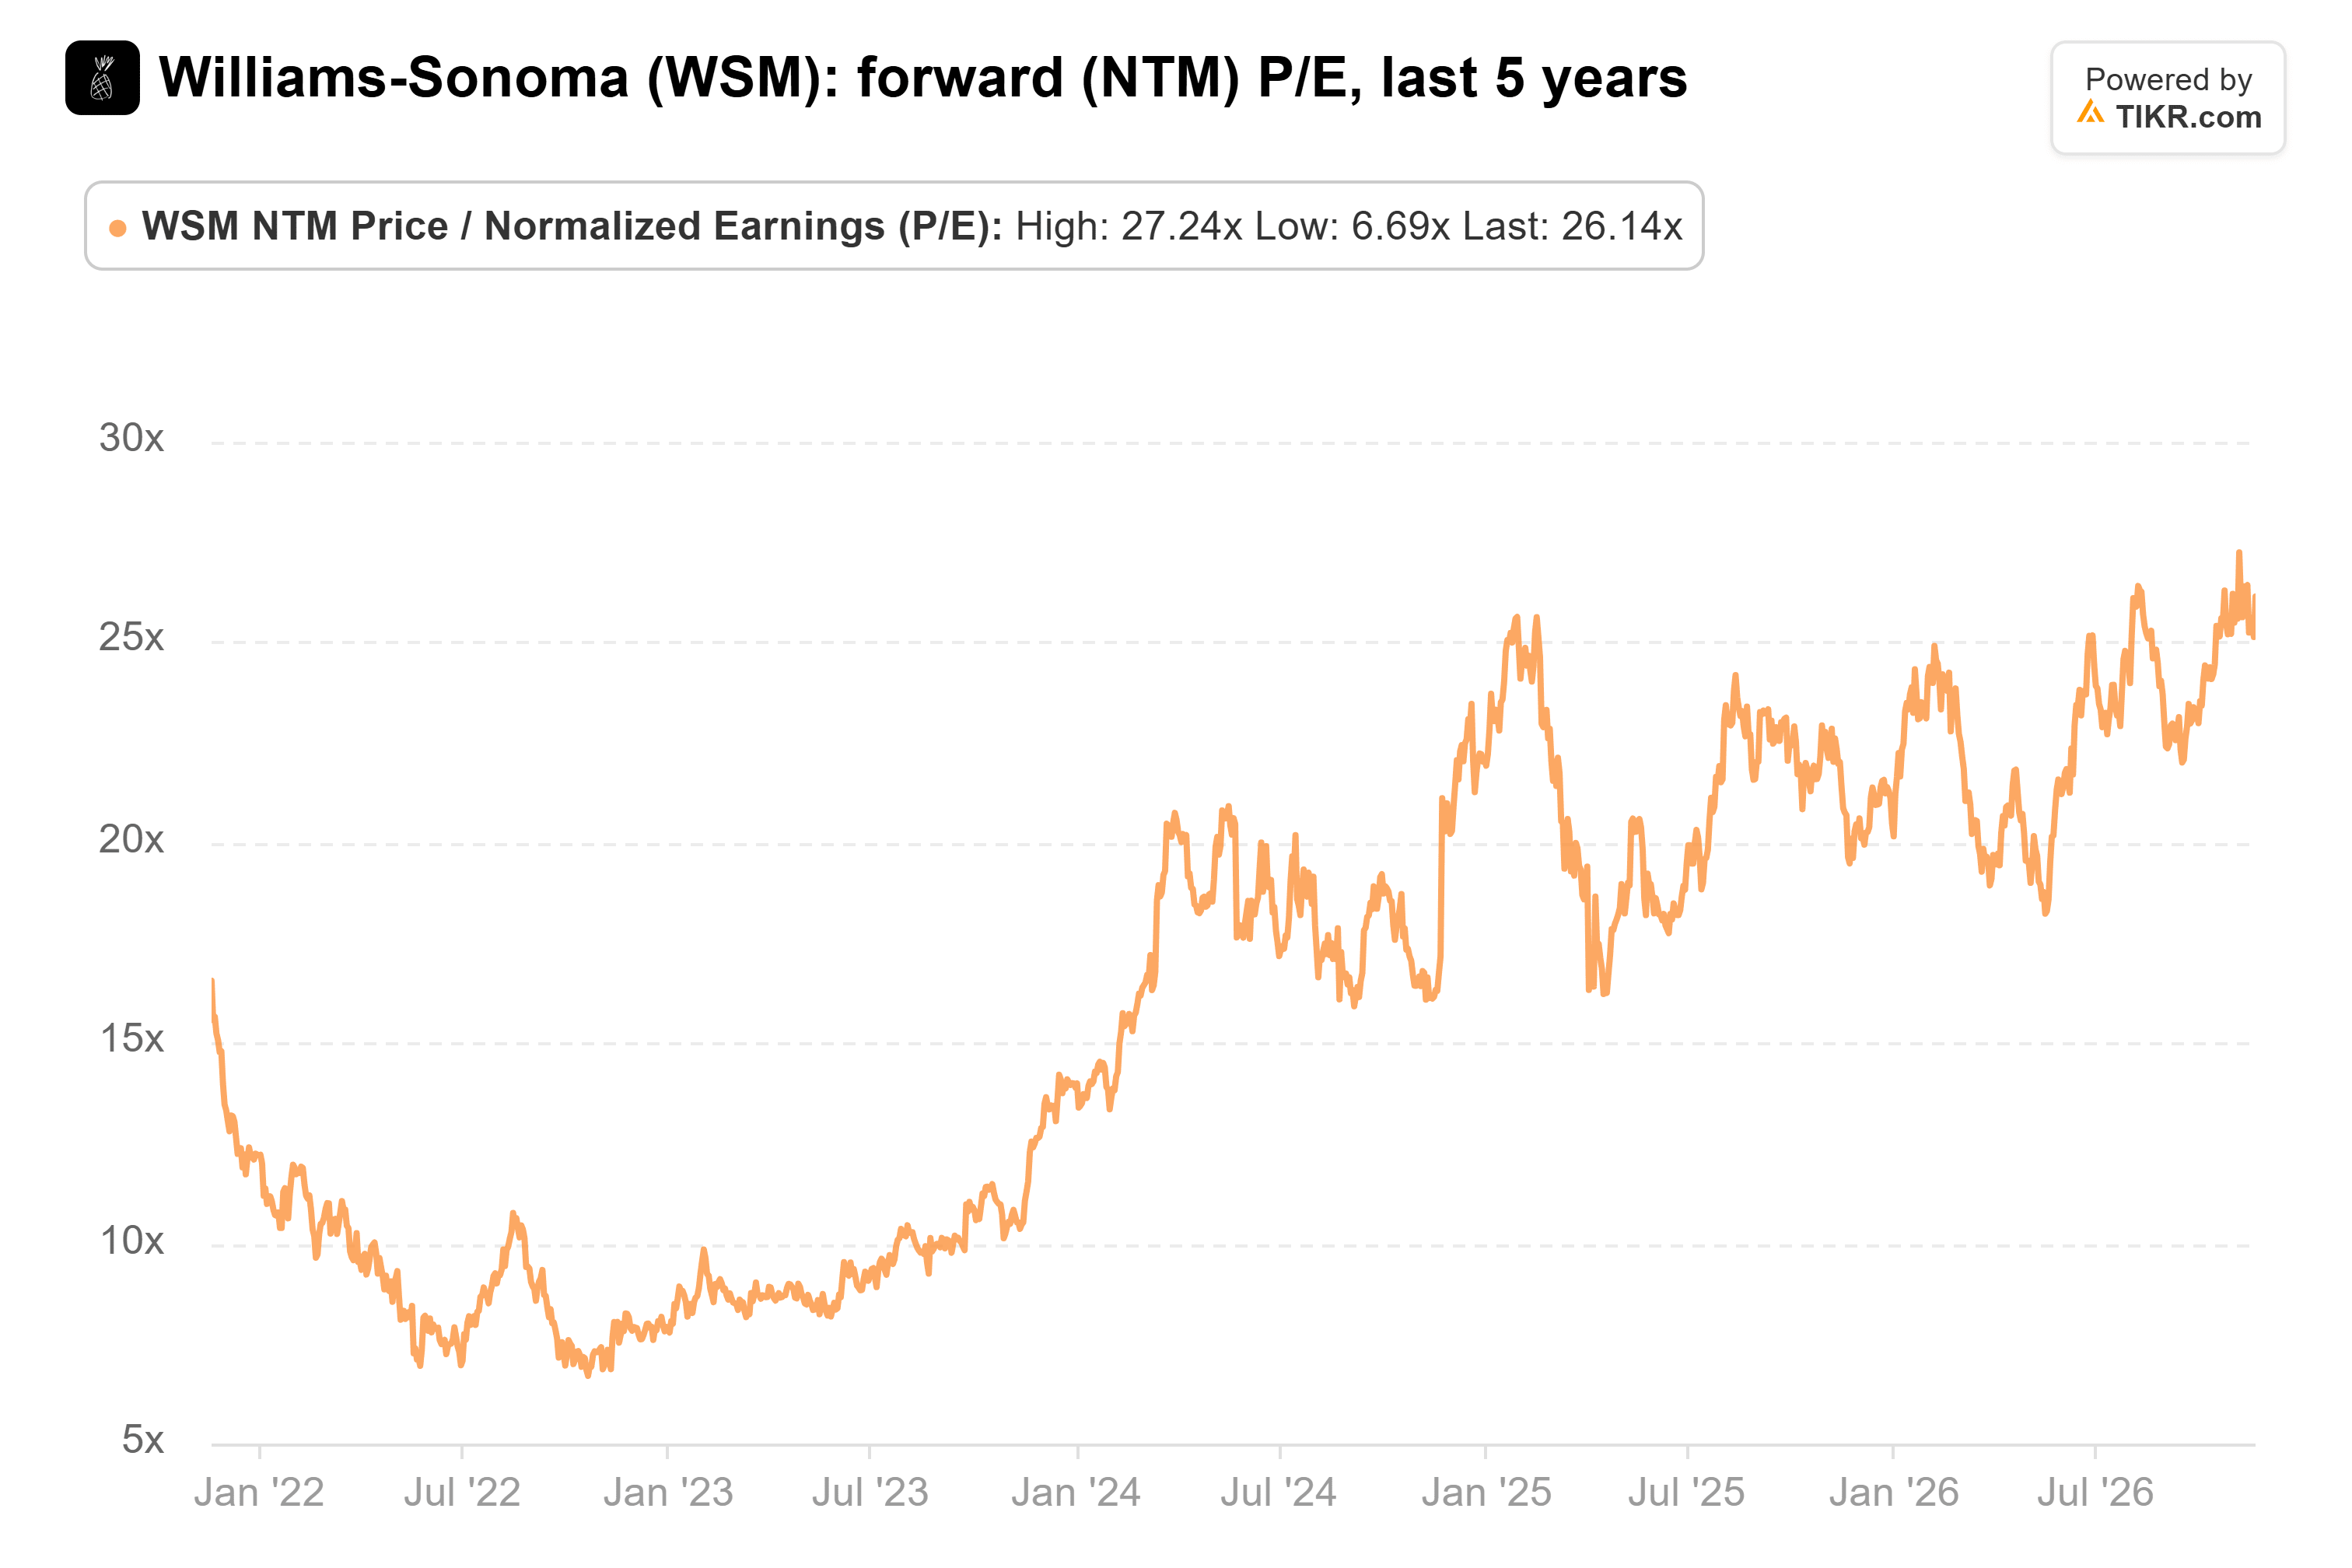
It traded at 26x at the last close, near its 27x high on Nov. 4 and far above its 16x average. Today’s drop still leaves it well above average.
The way I see it, this was a solid quarter at a price that needed a great one. The next test is the holiday quarter’s $3.31, and fiscal 2027 guidance comes in March.
So what is Williams-Sonoma stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Williams-Sonoma could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Williams-Sonoma for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!