Key Takeaways
- USA Rare Earth (USAR) fell approximately 15% during the week ended November 6, closing near $8.23 as broader market weakness pressured rare earth stocks.
- MP Materials (MP) also experienced sector volatility, although its 10-year government-backed price floor of $110 per kilogram for neodymium-praseodymium products provides greater pricing protection.
- USA Rare Earth reported $3.0 million in third-quarter revenue and approximately $1.16 billion in cash, cash equivalents, and restricted cash as of September 30, 2026.
- USAR could offer significant upside if production scales successfully, but operating losses, cash consumption, and execution risks make it a speculative growth investment.
What Happened?
USA Rare Earth (USAR) stock fell approximately 15% during the week ended November 6, closing near $8.23 as broader market weakness pressured speculative rare earth stocks.
The selloff also affected MP Materials (MP), whose established operations and government-backed pricing arrangement provide a useful comparison with USA Rare Earth’s developing rare earth supply chain.
USAR reached a 52-week intraday low of $6.84 on November 5 before rebounding nearly 11% the following day, highlighting how quickly sentiment can shift around rare earth supply expectations.
The company subsequently reported third-quarter financial results on November 9, providing investors with a clearer picture of its progress toward establishing an integrated rare earth supply chain.
Quarterly revenue reached $3.0 million, while the company recorded a $141.4 million operating loss. Revenue for the first nine months of 2026 totaled approximately $14.5 million.
CEO Thras Moraitis described the quarter as reflecting “the growing positive momentum at USA Rare Earth.”
The company completed the first stage of Serra Verde’s optimization program in September and began commercial-scale shipments in October, with sales following in November.
Serra Verde is targeting a production run rate of 4,000 metric tonnes of total rare earth oxides annually by the second quarter of 2027.
USA Rare Earth also reported its first commercial magnet sales and produced light and heavy rare earth oxide samples for customer qualification.
Despite these milestones, shares declined approximately 9.6% on November 10, the first trading session following earnings, before recovering to $8.27 on November 11.
These developments show that USA Rare Earth is beginning to convert production plans into commercial activity, but investors still need evidence that operations can generate enough revenue to justify its valuation.
Is USA Rare Earth Stock Undervalued or Overvalued?
USA Rare Earth’s valuation depends heavily on its ability to scale production and deliver substantial future revenue growth. While the stock could offer meaningful upside if those plans succeed, its limited operating history and significant cash requirements make it difficult to establish whether shares are currently undervalued.
TIKR consensus estimates prepared before the November 9 earnings release projected approximately $710 million in 2027 revenue, compared with $14.5 million reported during the first nine months of 2026. These forecasts depend on successful production expansion and may change following the latest results.

USAR’s valuation depends heavily on achieving the substantial revenue growth analysts previously forecast for 2027. While successful production expansion could make the stock more attractive, delays or weaker-than-expected commercial sales could materially reduce its potential upside.
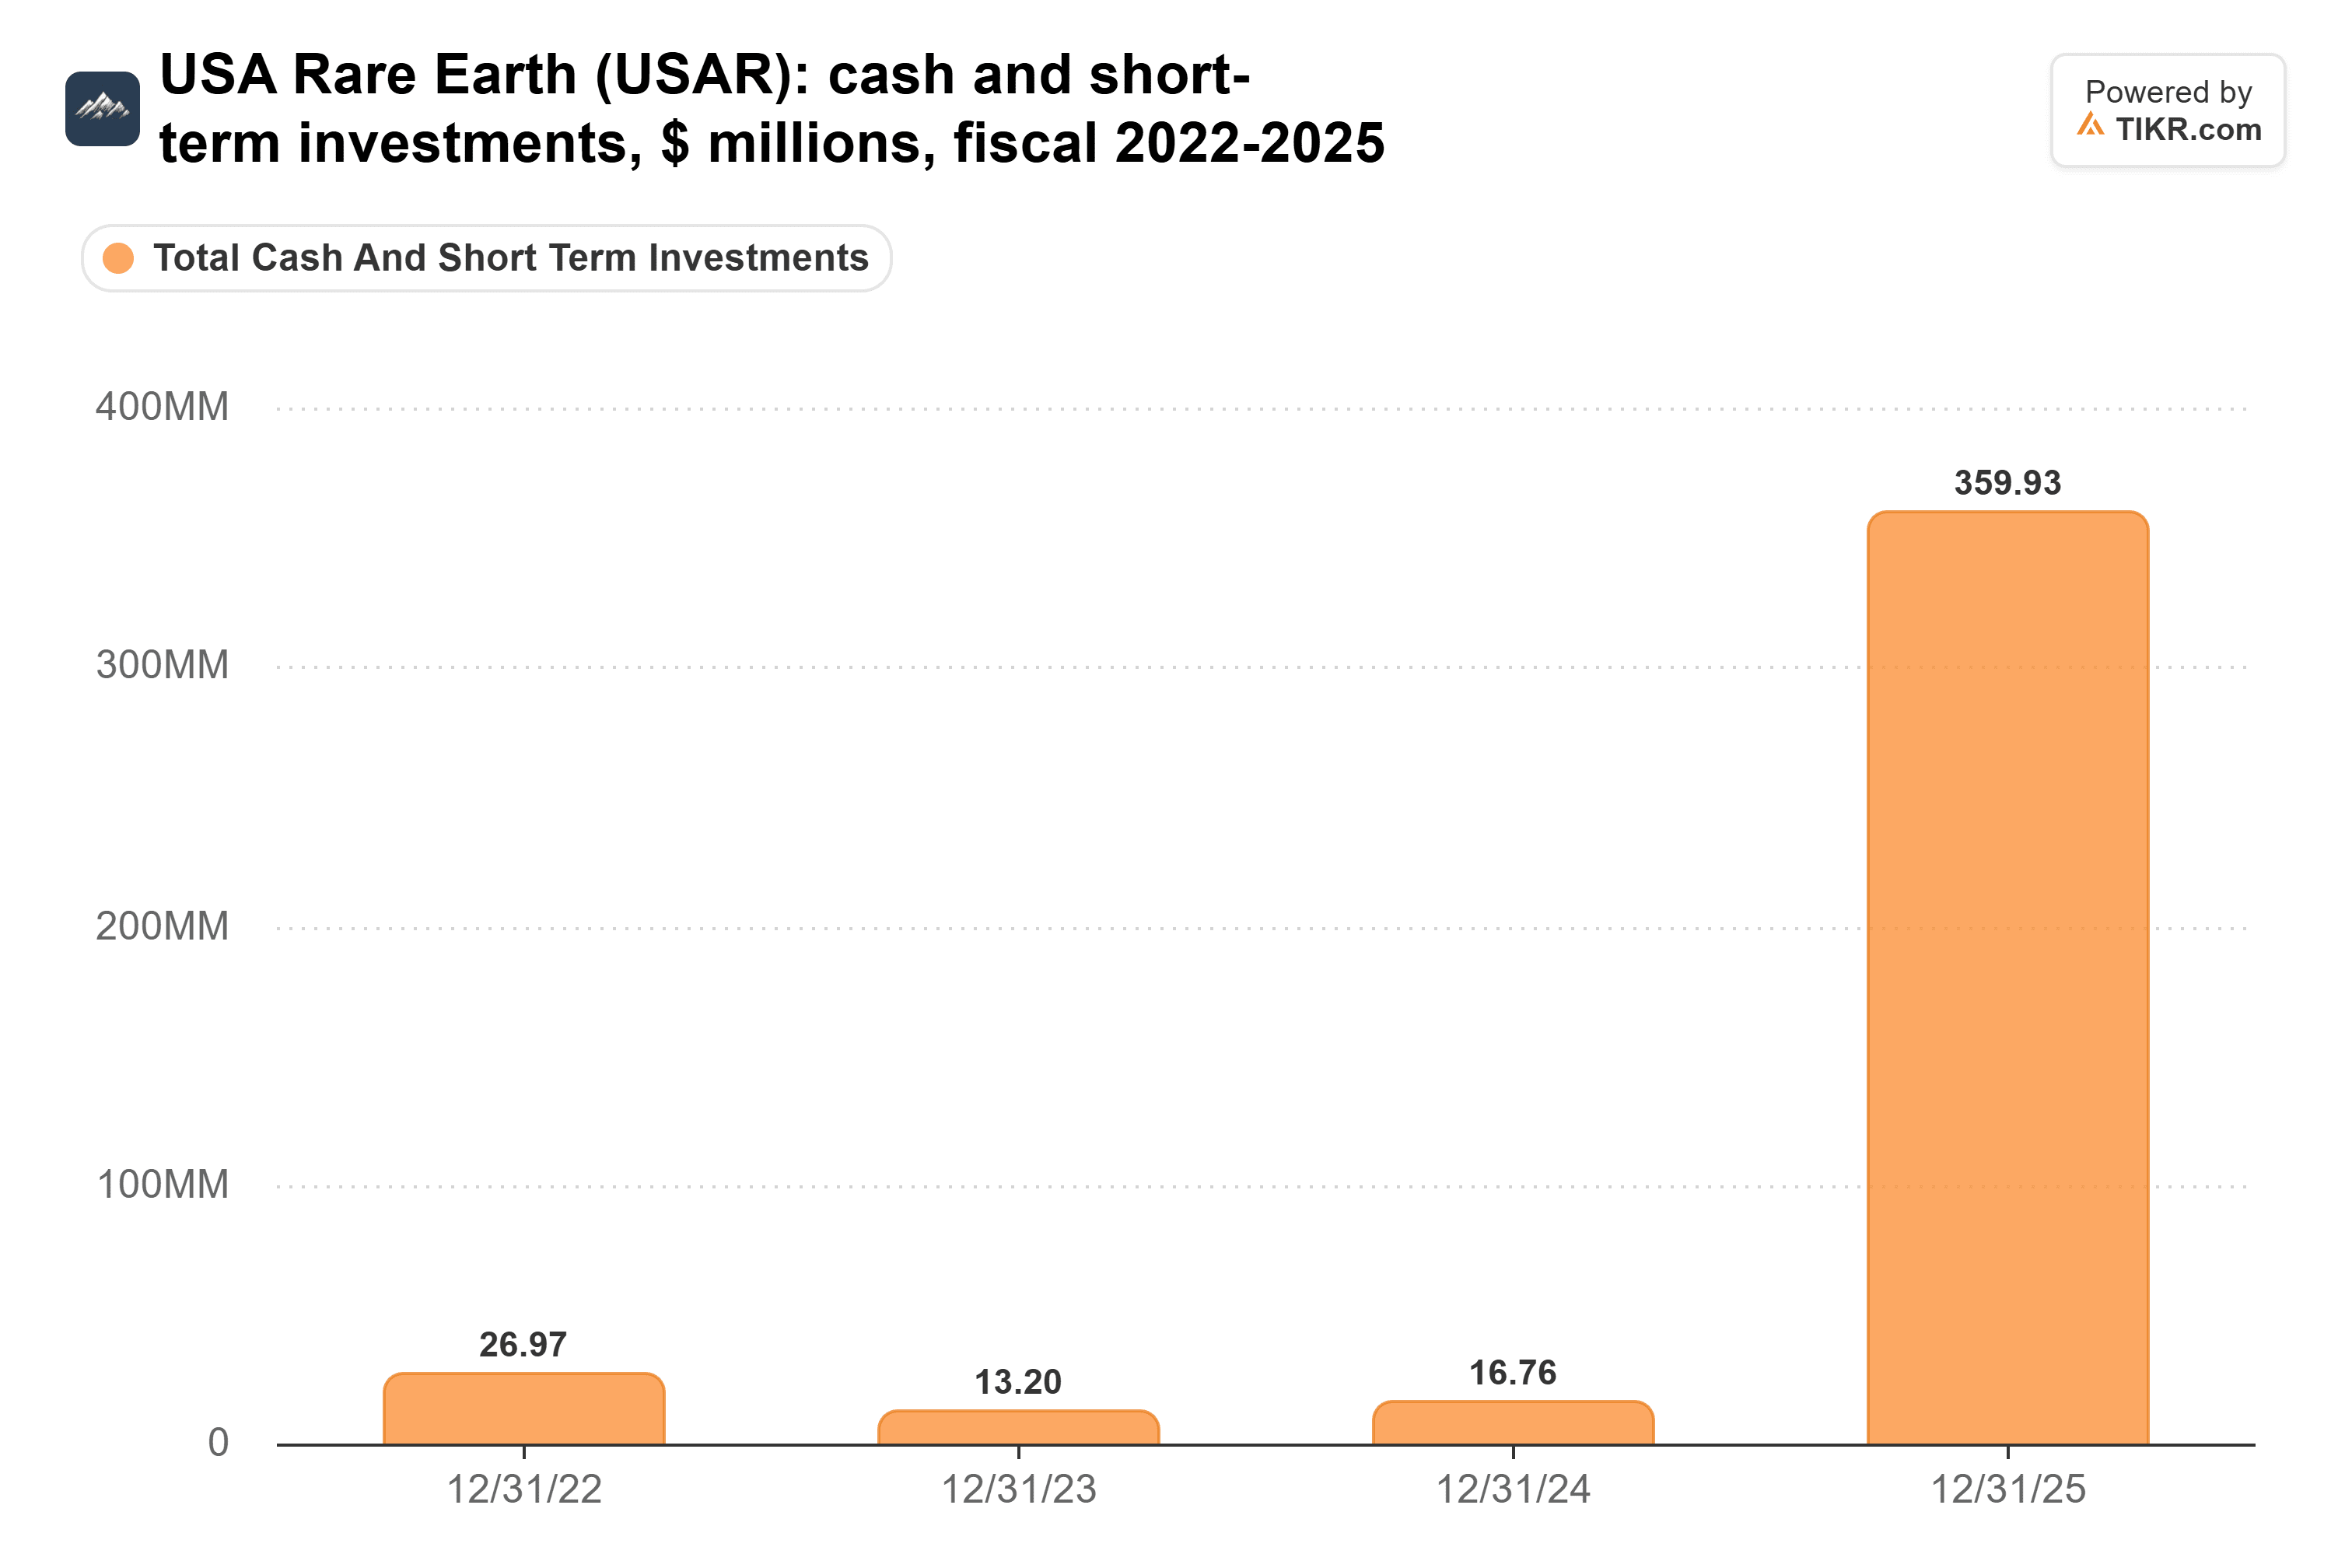
USA Rare Earth reported approximately $1.09 billion in cash and cash equivalents as of September 30, compared with approximately $360 million at year-end 2025. Including restricted cash, its September balance totaled approximately $1.16 billion.
However, operating cash outflows reached approximately $219 million during the first nine months of 2026, underscoring the substantial capital requirements of expanding its mining, processing, and magnet manufacturing operations.
Government backing adds another potential catalyst for domestic rare earth production. MP Materials secured a 10-year government-backed price floor of $110 per kilogram for its neodymium-praseodymium products, providing greater pricing visibility than most emerging rare earth producers enjoy.
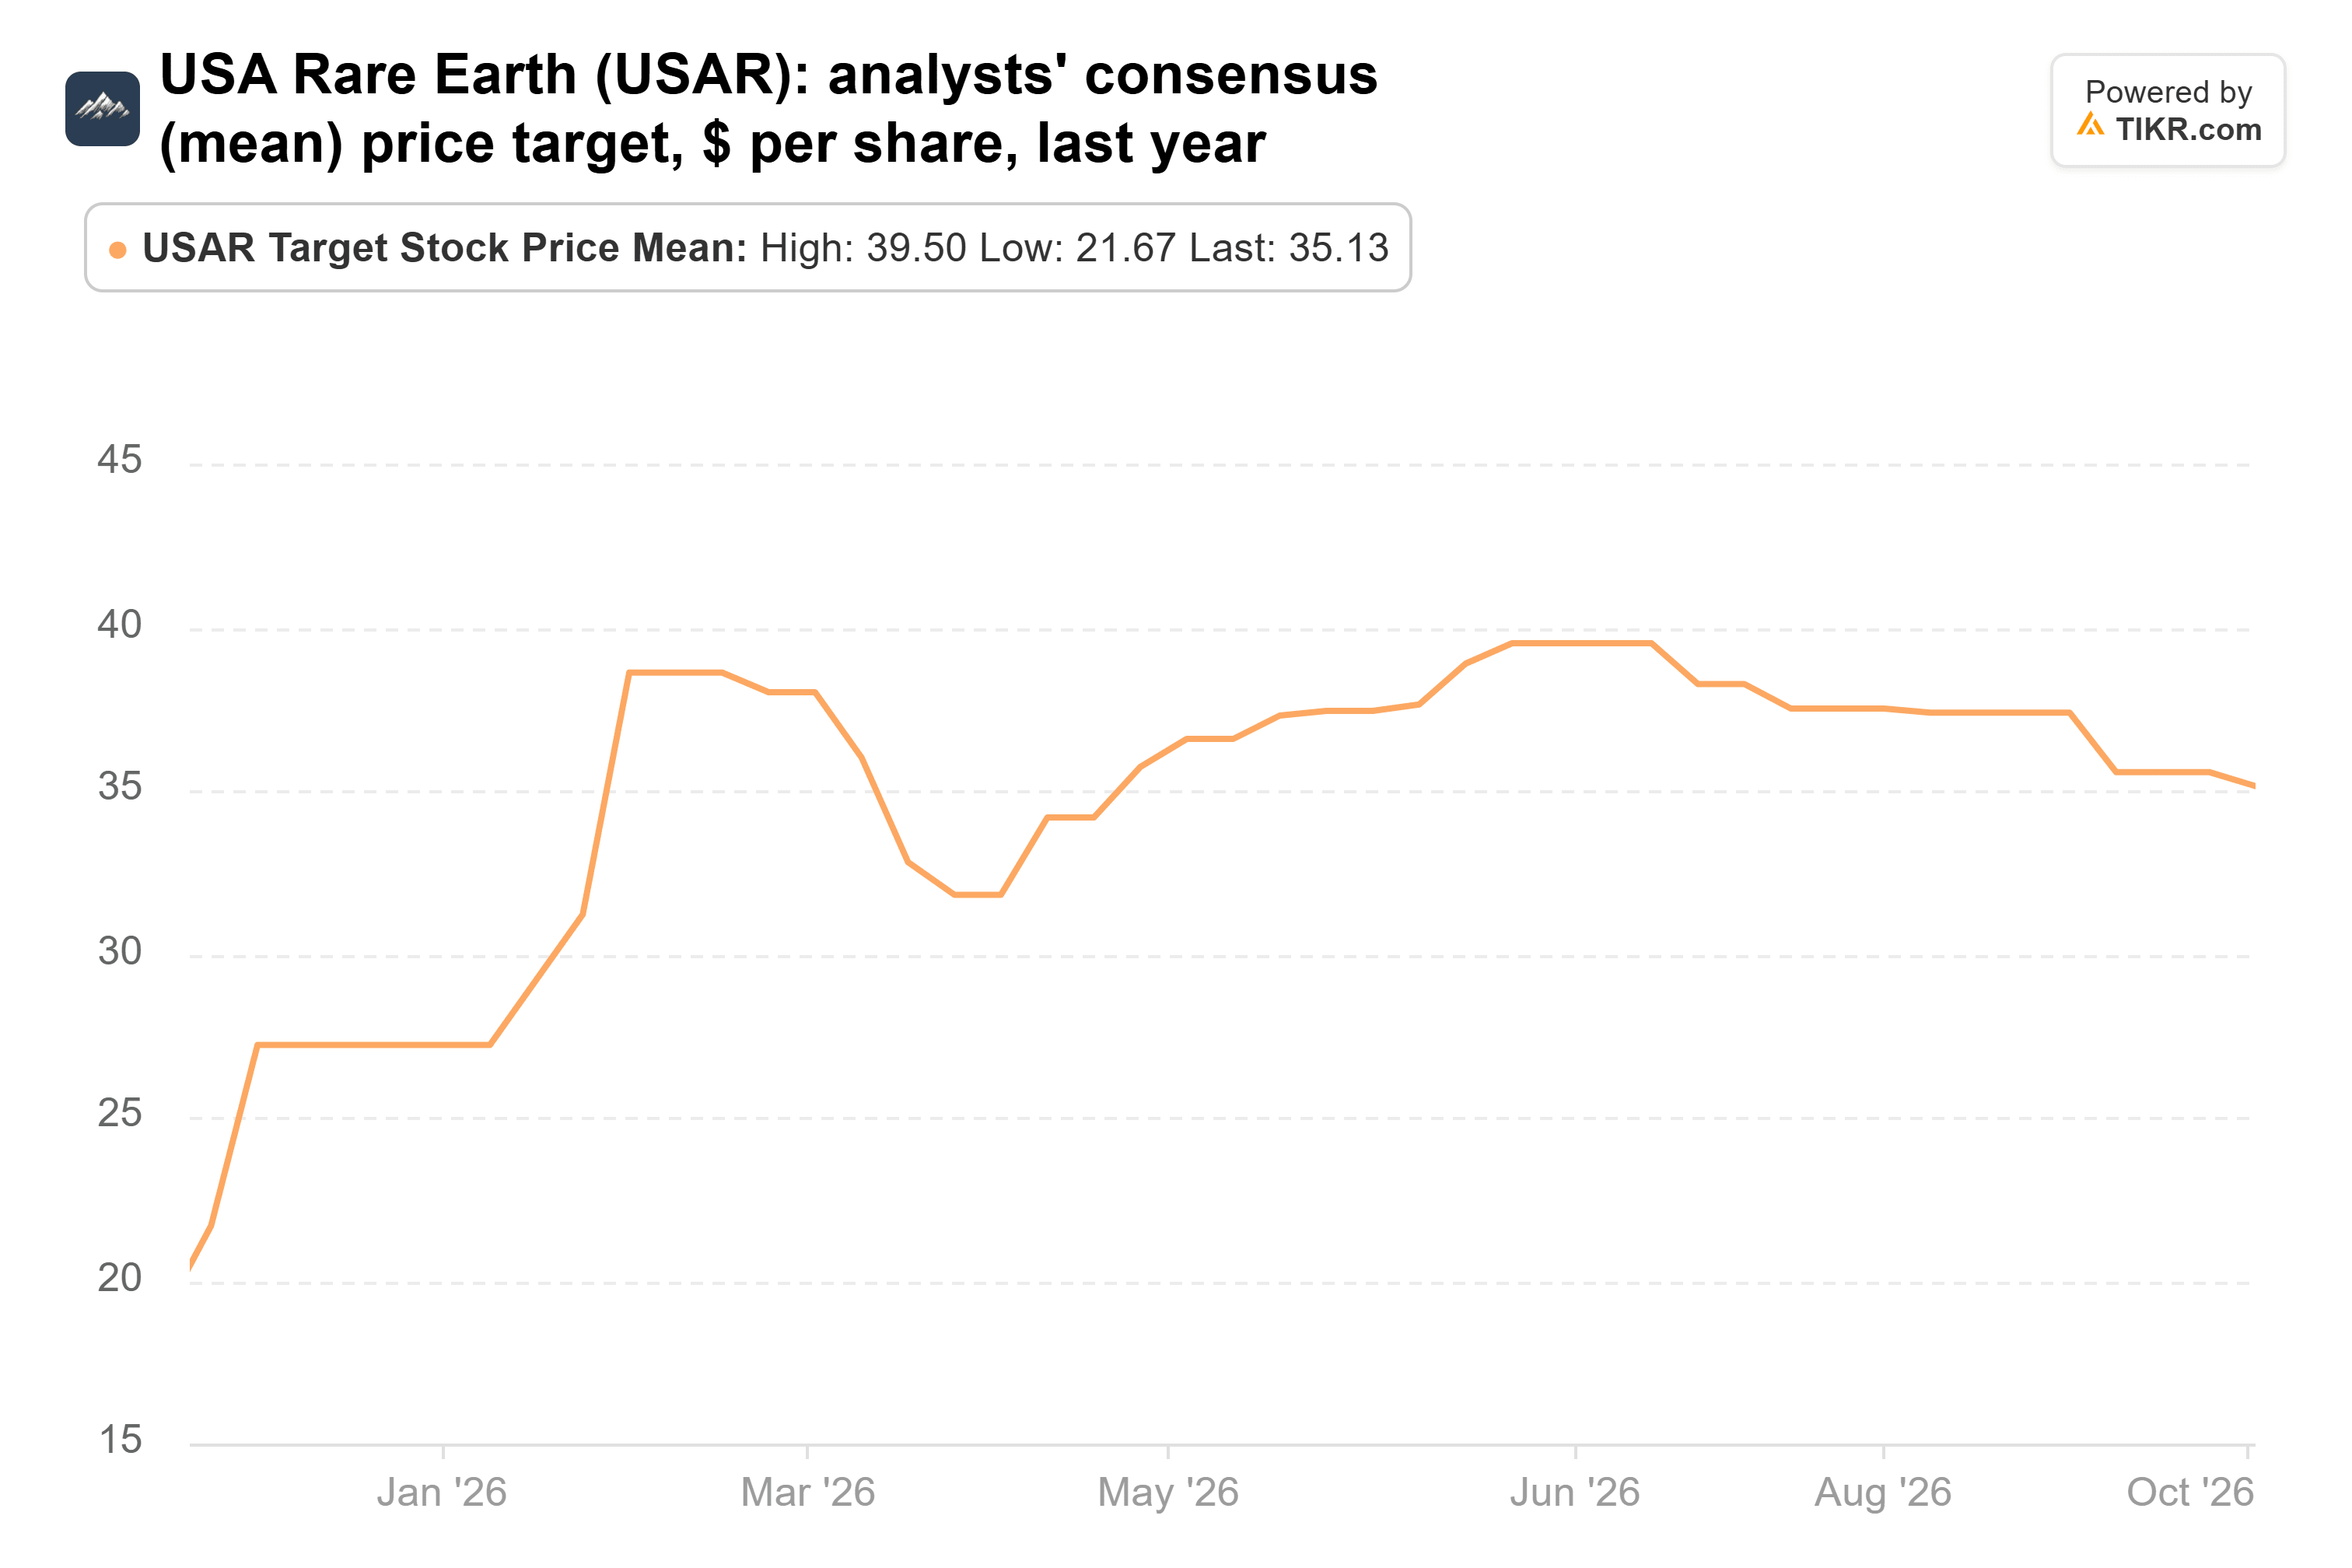
An external analyst consensus price target of approximately $33.33 suggested roughly 303% upside from USAR’s November 11 closing price of $8.27. The accompanying TIKR chart shows an earlier consensus near $35, reflecting a different reporting date. Analyst price targets ranged from $20 to $45, highlighting uncertainty surrounding the company’s execution and future profitability.
Over the next 12 months, the stock’s performance will likely depend on Serra Verde’s production ramp, commercial magnet sales, operating cash consumption, and the company’s ability to convert production milestones into meaningful revenue growth.
USA Rare Earth looks potentially undervalued if its long-term growth targets materialize, but substantial execution risk and capital requirements make it a speculative investment rather than a proven value opportunity.
So what is USA Rare Earth stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what USA Rare Earth could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!