


Key Takeaways
- Berenberg cut DraftKings to Hold and Wells Fargo cut it to Equal Weight on Nov. 10, with targets of $20 and $21, after a third-quarter report that slashed the company’s 2026 profit outlook.
- DraftKings now plans $650 million to $700 million of adjusted EBITDA investment in Predictions this year, more than double its earlier plan, and it bought back no stock in the third quarter.
- The midpoint of DraftKings’ 2027 adjusted EBITDA guidance came in about 20% below pre-report expectations.
- Both downgrades look right: the stock has fallen hard, but buying can wait until the next report shows 2027 guidance holding.
DraftKings (DKNG) closed at $19.64 on Nov. 11, 46% below its 52-week closing high of $36.24 from Jan. 5. Berenberg and Wells Fargo both downgraded it on Nov. 10, and Berenberg’s new $20 target sits just 2% above the share price.
Predictions Got a Lot More Expensive for DraftKings
The selloff started with DraftKings’ third-quarter report on Nov. 5. Revenue rose 16% to $1.33 billion, but the adjusted EBITDA loss widened to $316.9 million from $126.5 million a year earlier. The company cut its 2026 adjusted EBITDA guidance to $175 million to $275 million, from $700 million to $900 million, mainly because its adjusted EBITDA investment in Predictions is now set at $650 million to $700 million, up from $200 million to $300 million.
2027 doesn’t fix it. Adjusted EBITDA guidance of $800 million to $1.0 billion, including $300 million of adjusted EBITDA investment in Predictions at the midpoint, came in below the roughly $1.12 billion analysts expected going in. The $900 million midpoint is about 20% short.
DraftKings Bought Back No Stock in the Third Quarter
Berenberg’s Jack Cummings cut DraftKings to Hold from Buy, and his target to $20 from $27.50. Wells Fargo cut the stock to Equal Weight from Overweight the same day, and its target to $21 from $30. The two joined JPMorgan, UBS and Stifel, which downgraded DraftKings a day earlier.
Shareholders shouldn’t count on buybacks to cushion the fall. DraftKings bought back no stock in the third quarter, so all $154.2 million it spent under its program this year was done by June.
Cash is tight, too. Operating cash flow was $63.0 million in the first nine months, less than the $168.9 million DraftKings spent on equipment and software, and it carries $2.19 billion of debt against $1.10 billion of cash.
TIKR Tracks 37 Analysts on DraftKings. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DraftKings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DraftKings’ Analyst Ratings
Is $20 Too Low for DraftKings Stock?
The consensus target has dropped to $27 from $47 a year ago:
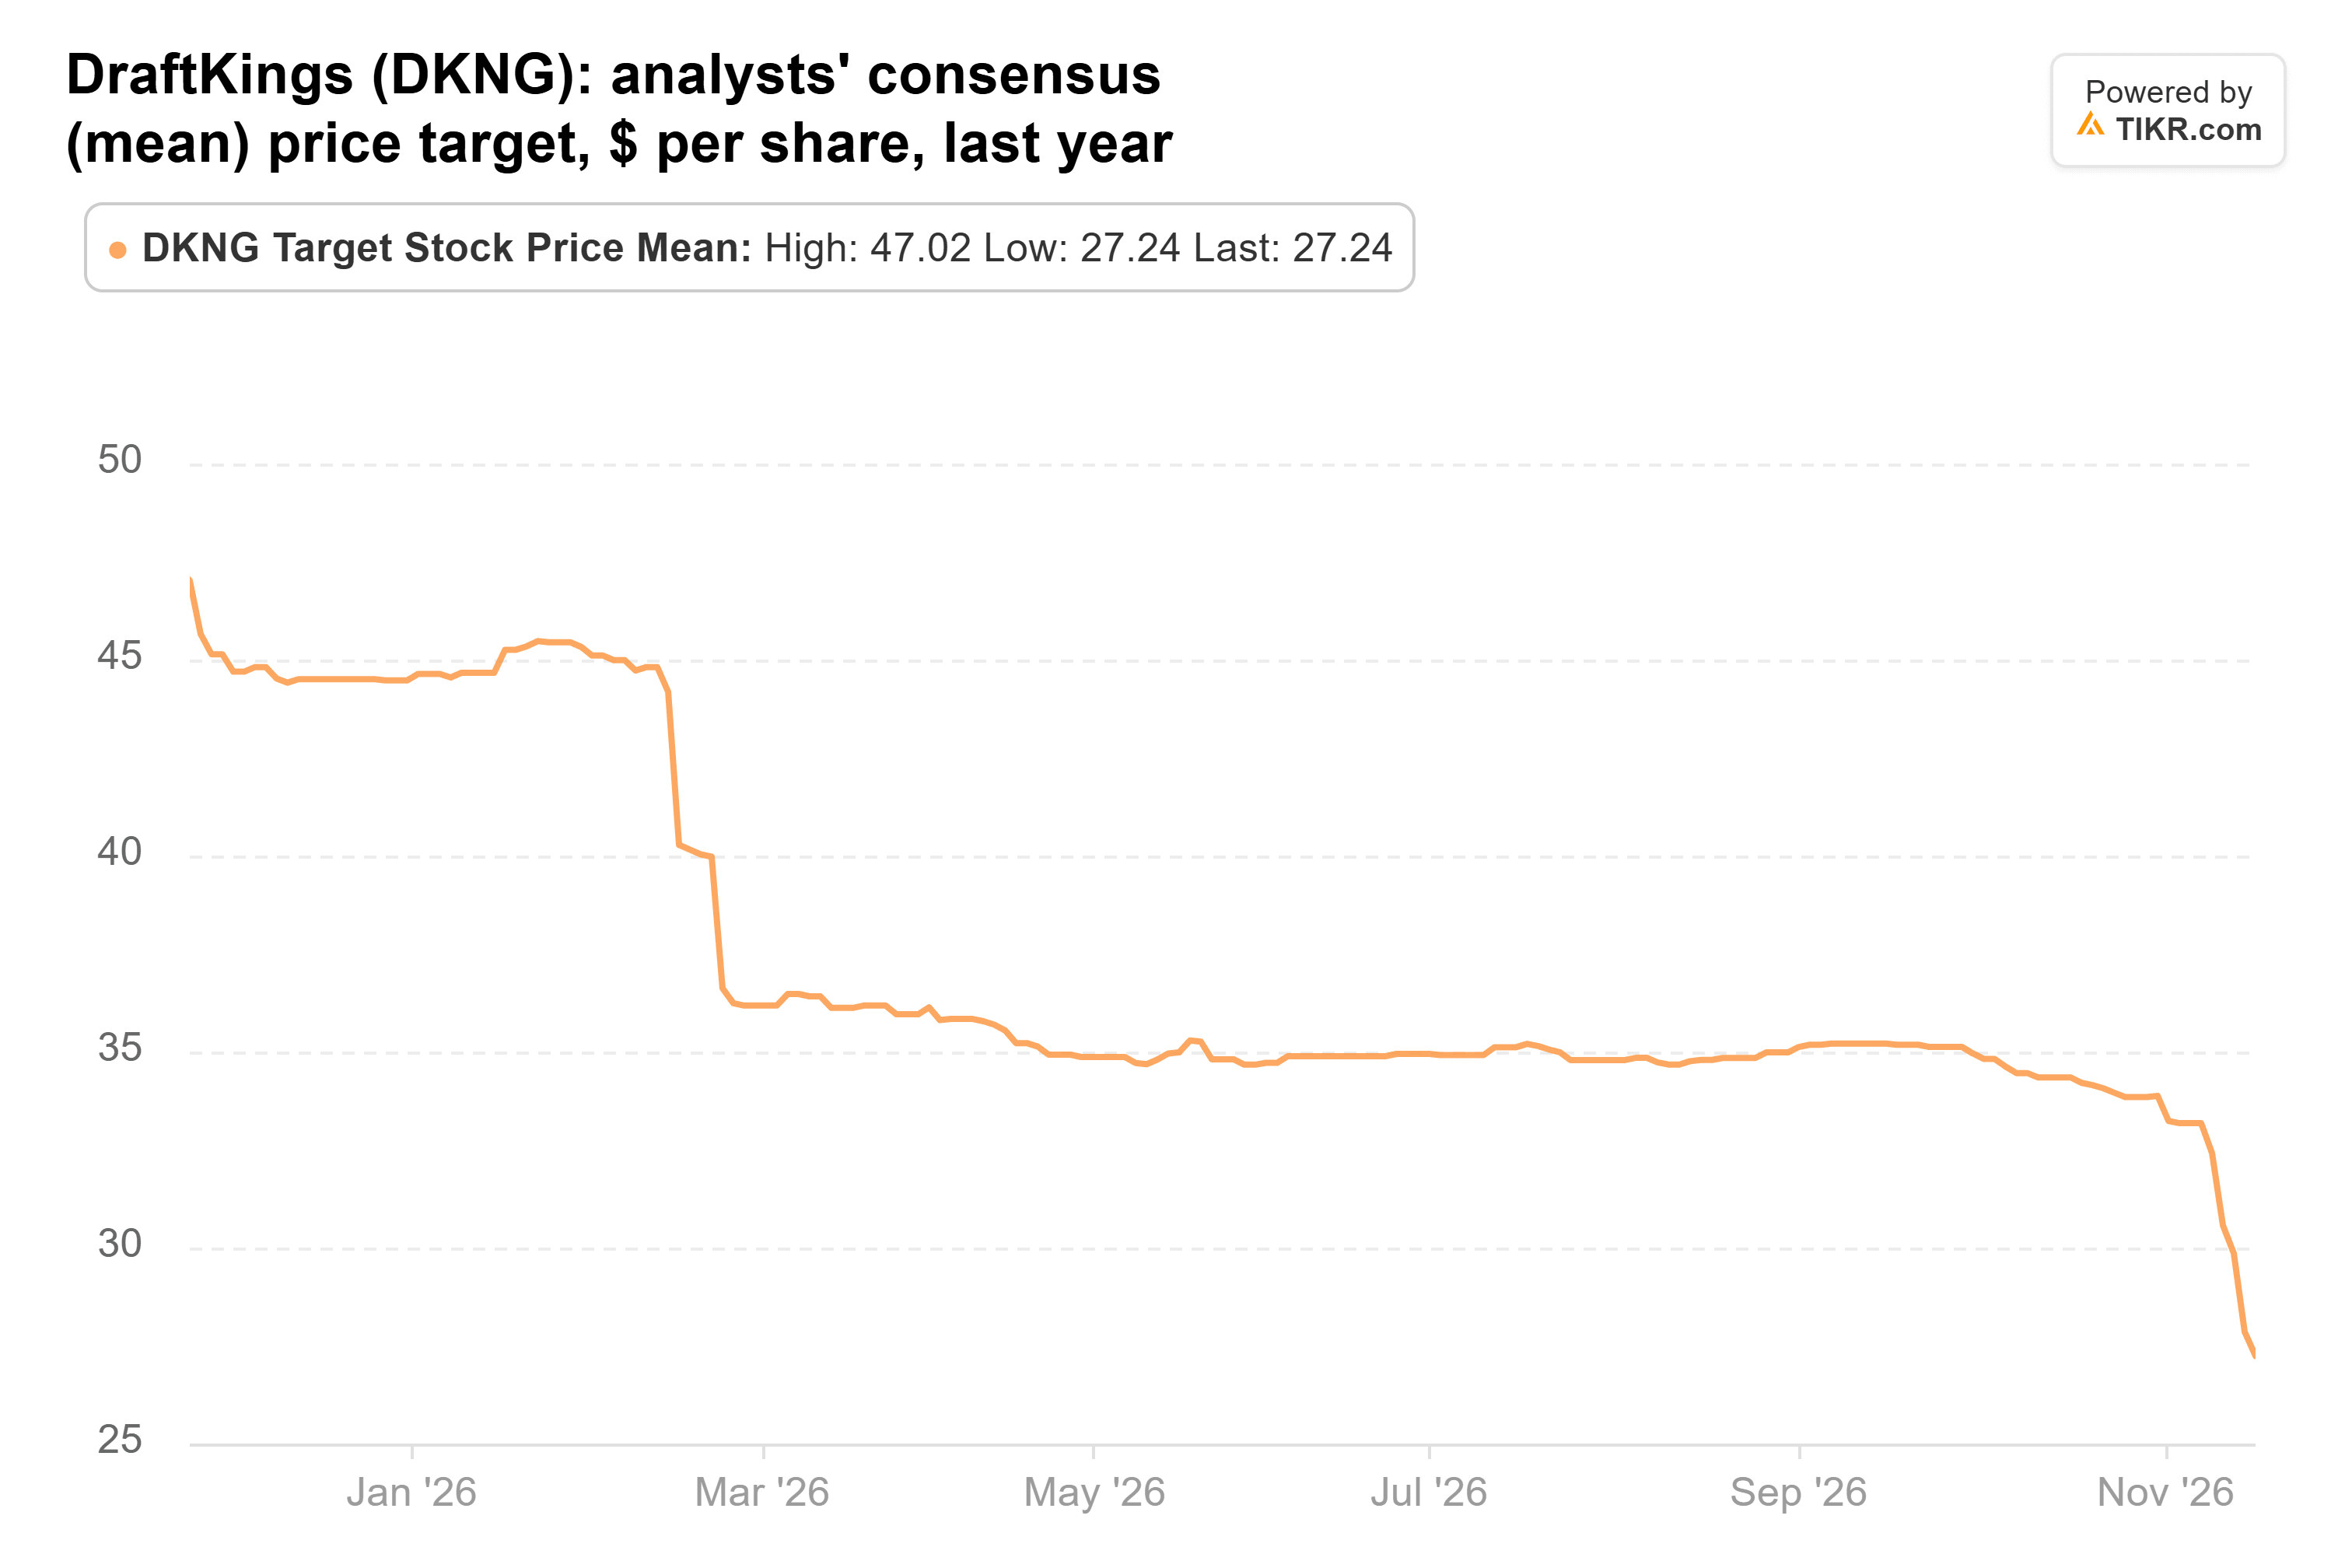
That’s still 37% above the share price.
The case that $20 is too cautious rests on the core business. Strip out Predictions, and DraftKings guides to $1.15 billion to $1.25 billion of core adjusted EBITDA in 2027. Chief Financial Officer Alan Ellingson also bought 18,908 shares for about $350,000 on Nov. 9.
But the core isn’t untouched. DraftKings cut its 2026 core outlook to $875 million to $925 million, from about $1 billion in August, and CEO Jason Robins put 60% of that cut on unfavorable sports results and the rest on spending to win online casino customers.
DraftKings’ Next Report Matters More Than the Discount
The selloff isn’t overdone yet, and both downgrades look right to me. Guidance for 2027 landed 20% under expectations, and there were no third-quarter buybacks to lean on. The next report is the test: if the adjusted EBITDA investment in Predictions stays within the $175 million to $225 million guided for the fourth quarter and 2027 guidance holds, $20 starts to look low.
So What Is DraftKings Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DraftKings could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


