

Key Takeaways
- Stanley Druckenmiller’s Duquesne Family Office raised its Amazon stake 43% in the third quarter, to 772,600 shares worth $192 million on Sept. 30. It also held call options with a notional value of $114 million.
- TIKR’s numbers back the bet: analysts expect Amazon’s normalized EPS to nearly double from 2025 to 2028, and its forward P/E sits near a five-year low.
- The risk is cash: Amazon’s free cash flow was a $42.4 billion outflow over the twelve months to Sept. 30 as it spends about $220 billion on capex this year.
- Amazon’s 2027 spending plan is expected with its fourth-quarter results in early February, and that’s the next test.
Stanley Druckenmiller made Amazon (AMZN) a bigger part of his portfolio last quarter.
His Duquesne Family Office’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows 772,600 Amazon shares worth $192 million at quarter’s end. That’s 43% more shares than the quarter before.
A top-three position, with calls on top
That makes Amazon 4.6% of the $4.15 billion of US stocks in Duquesne’s 13F, and its third-largest of 60 positions. Druckenmiller also held call options on Amazon with a notional value of $114 million on Sept. 30, which gives him a second way to profit if the stock climbs. A 13F only shows what a fund held on the last day of the quarter, so it can’t tell us when he added, what he paid, or why. Amazon stock is up 4% from its Sept. 30 price to the latest close. That isn’t Duquesne’s return, since we don’t know what it paid or whether it still holds every share.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
AWS is still speeding up
Amazon reported a strong third quarter on Oct. 29. AWS sales rose 39.3% to $46.0 billion, the cloud unit’s fastest growth in nearly five years. Amazon’s GAAP operating income jumped to $28.1 billion from $17.4 billion, for a record 13.9% operating margin. Management also put AWS’s backlog at $578 billion on the call.
Analysts expect Amazon’s normalized EPS to nearly double, from $7.17 in 2025 to $14.07 in 2028:

2027 is the slow step in that climb, at $10.93 against $9.60 for 2026, before the big jump in 2028. With AWS accelerating for another quarter, I don’t see much in the third-quarter report that should pull those estimates down. AWS CEO Matt Garman said on Sources with Alex Heath this month that demand is “far outstripping the supply.” He also expects AWS to be short of capacity for the next couple of years.
Investors are paying less for those earnings
Amazon trades at 25x forward earnings, near the bottom of its range over the last five years:

That’s about half its five-year average of 48x, and just above the 23x low it hit on Oct. 30, the day after the third-quarter report. The stock sits 10% below its 52-week high.
Wall Street sees room from here. The consensus target is $326 from 62 analysts, 26% above the last close, up from $293 a year ago:
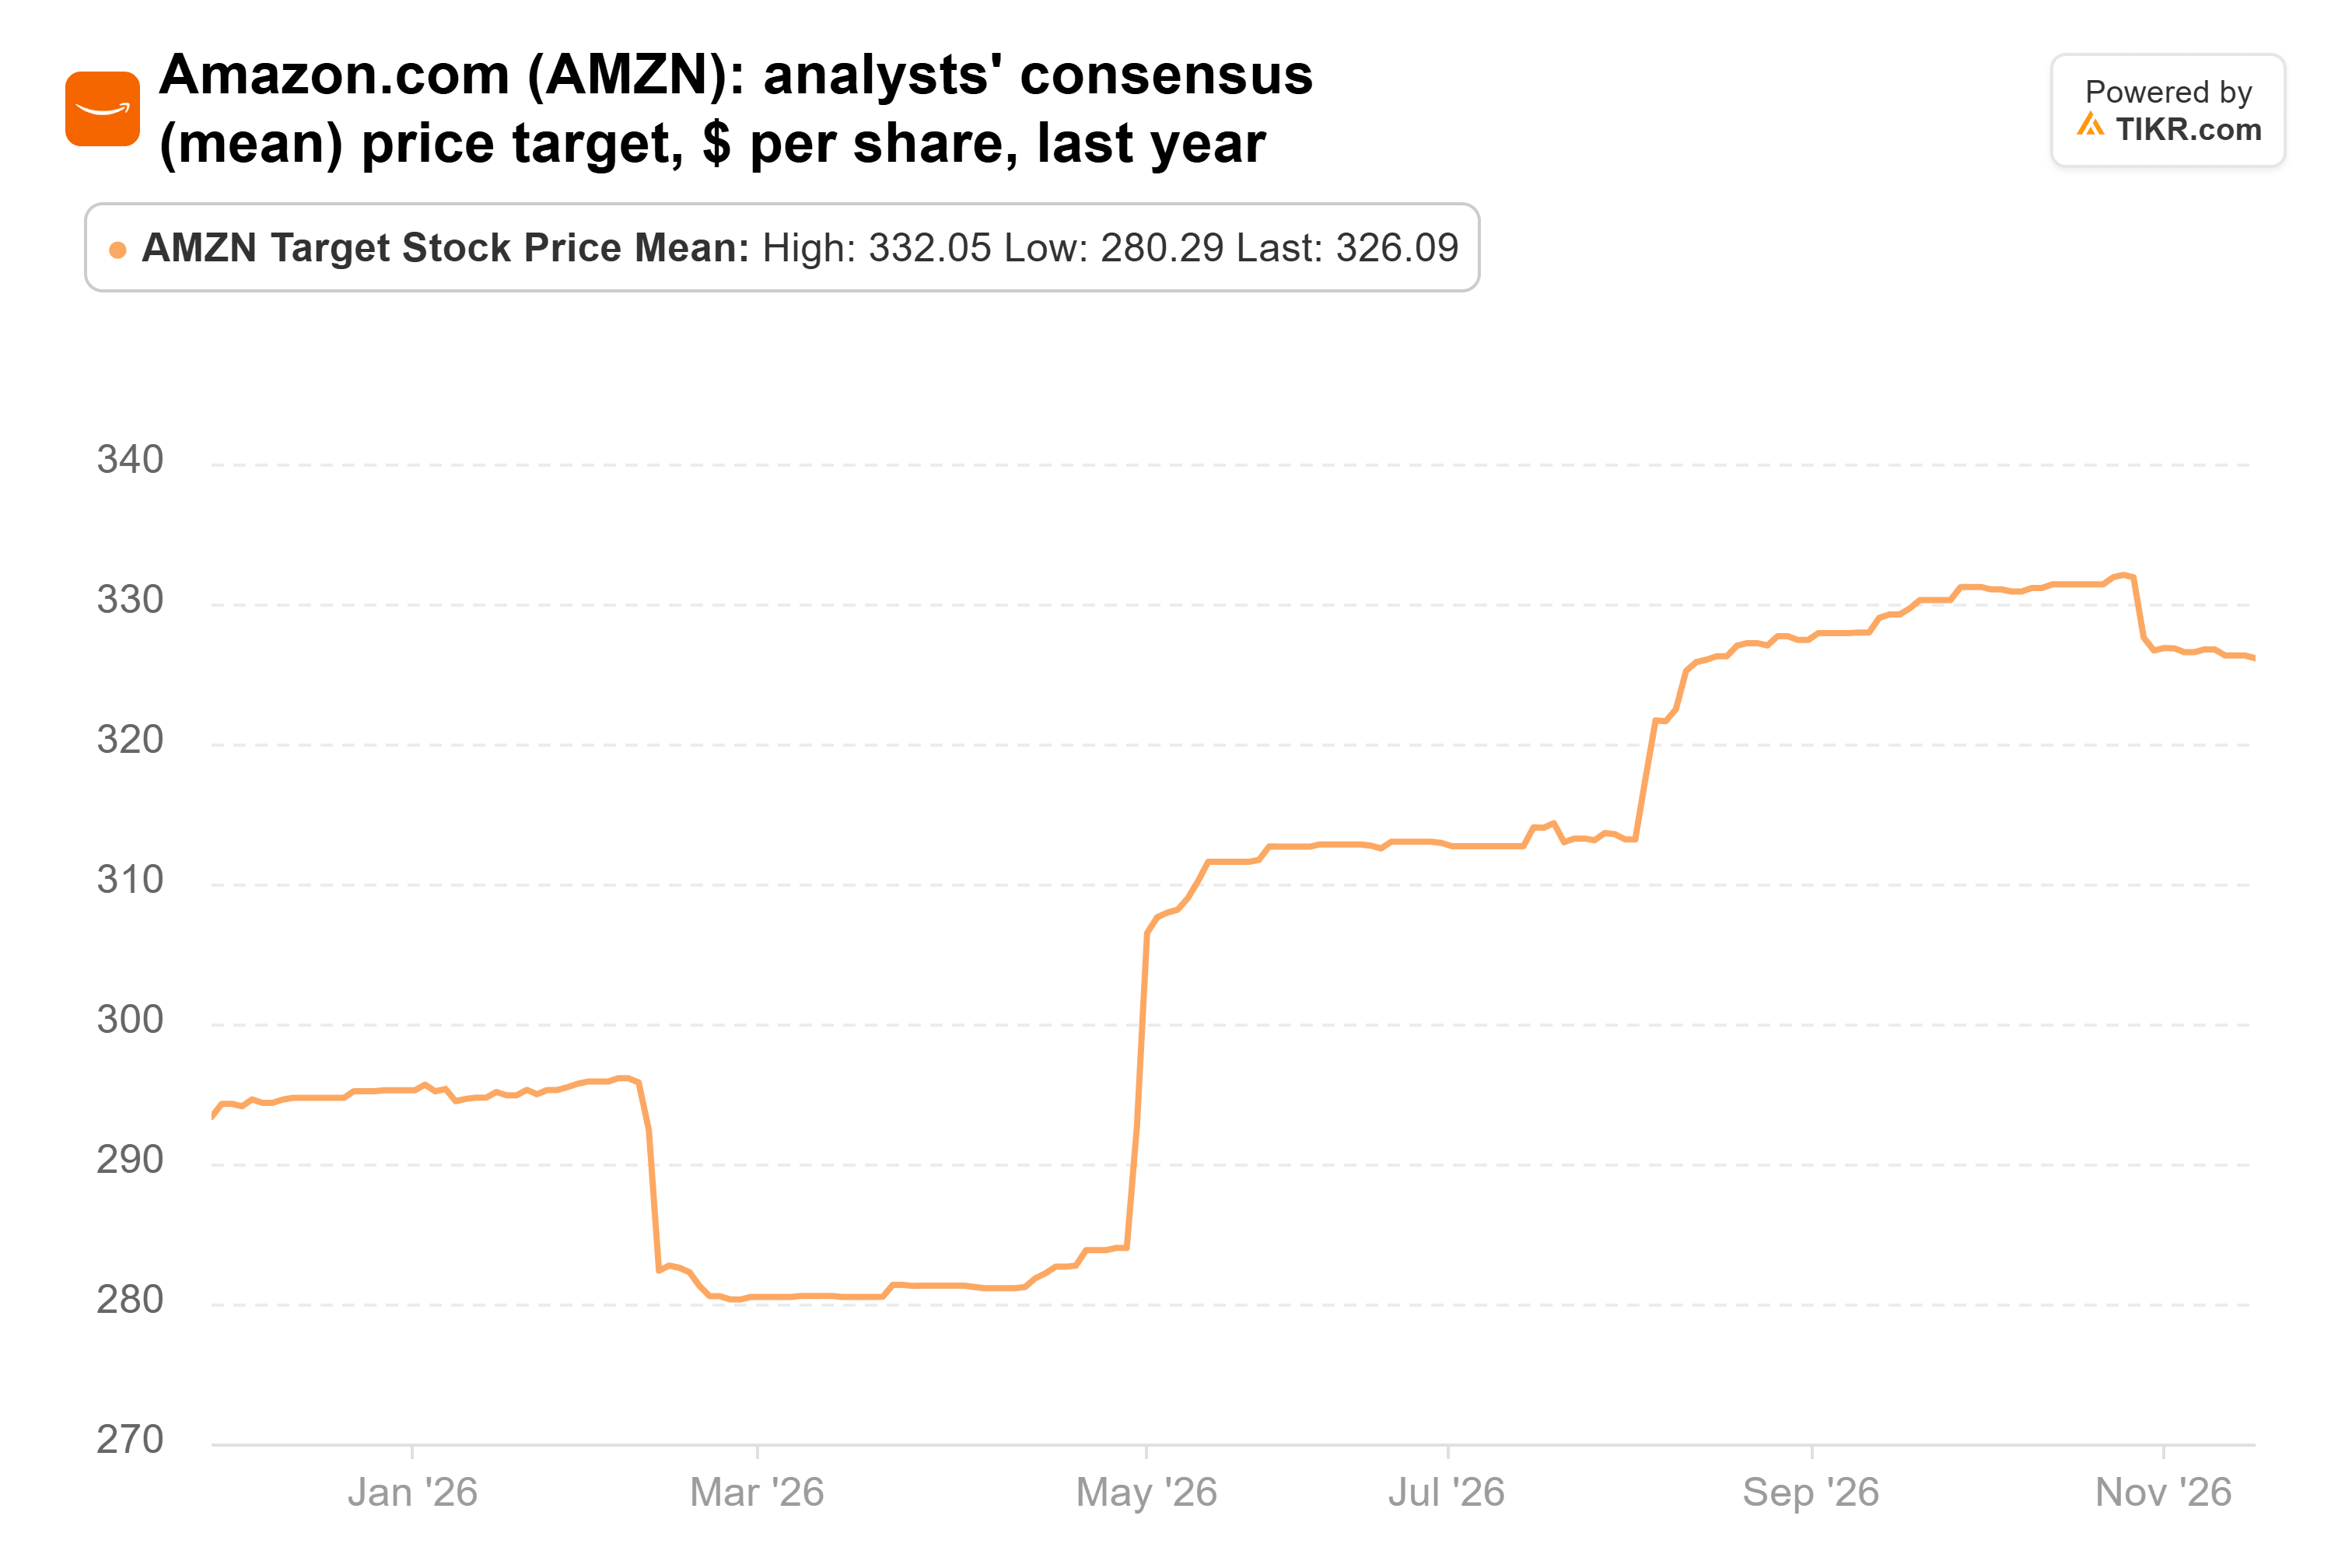
The individual targets run from $230 to $405. By my math, the $326 consensus is about 23x 2028 EPS estimates, a touch below today’s multiple. So it needs no re-rating, only for the estimates to hold.
Cash is the price of the build
Amazon expects about $220 billion of capital spending this year. Its free cash flow was a $42.4 billion outflow over the twelve months to Sept. 30, against an inflow a year earlier. Going into the third-quarter report, analysts didn’t expect free cash flow to turn positive again until 2028, so investors are being asked to wait.
Even so, I think the numbers back Druckenmiller. Amazon’s cloud business is growing faster than it has in years, and investors are paying close to the lowest multiple of the past five for it. At that price, waiting until 2028 for the cash looks like a fair trade.
The next test comes with fourth-quarter results in early February, when Amazon is expected to give its 2027 spending plan. Before the October report, analysts had 2027 capex at $278.2 billion. A plan at or below that, with AWS growth holding near 39%, would keep the 2028 cash turn on track. And Duquesne’s next 13F, due in mid-February, will show whether Druckenmiller kept adding.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


