Key Takeaways
- Spotify stock is up 12.5% in the past month as the Nasdaq 100 fell, on a third quarter that beat guidance.
- Warner Music Group, still negotiating over Spotify’s planned AI remix add-on, is sharing in streaming price increases.
- CFO Christian Luiga reaffirmed a 20%-plus operating margin target for 2030, against 12.8% in 2025.
- Spotify trades below its usual multiple, a buy if the fourth quarter delivers 10 million net adds and a 16% operating margin.
Spotify Technology (SPOT) stock is up 12.5% in the past month on a strong quarter and a planned AI add-on. Meanwhile, the Nasdaq 100 fell 10%.
On Nov. 19, CFO Christian Luiga told Morgan Stanley’s conference that Spotify still aims for an operating margin above 20% by 2030. The same day, record label Warner Music Group (WMG) reported faster streaming growth.
TIKR tracks 41 analysts on Spotify. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Spotify, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Spotify’s Analyst Ratings
Price did the heavy lifting
Spotify added 6 million Premium subscribers in the third quarter, 1 million above guidance. Premium revenue grew 17%, nearly twice as fast as subscribers, and gross margin hit a third-quarter record of 33.0%.
Operating expenses rose 26%, though, holding the operating margin to 13.5%. Co-CEO Alex Norström said Spotify’s “costs are moderating, and there is more runway ahead.” Its fourth-quarter guide of €820 million of operating income, a 15.8% margin, also topped Wall Street’s estimate.
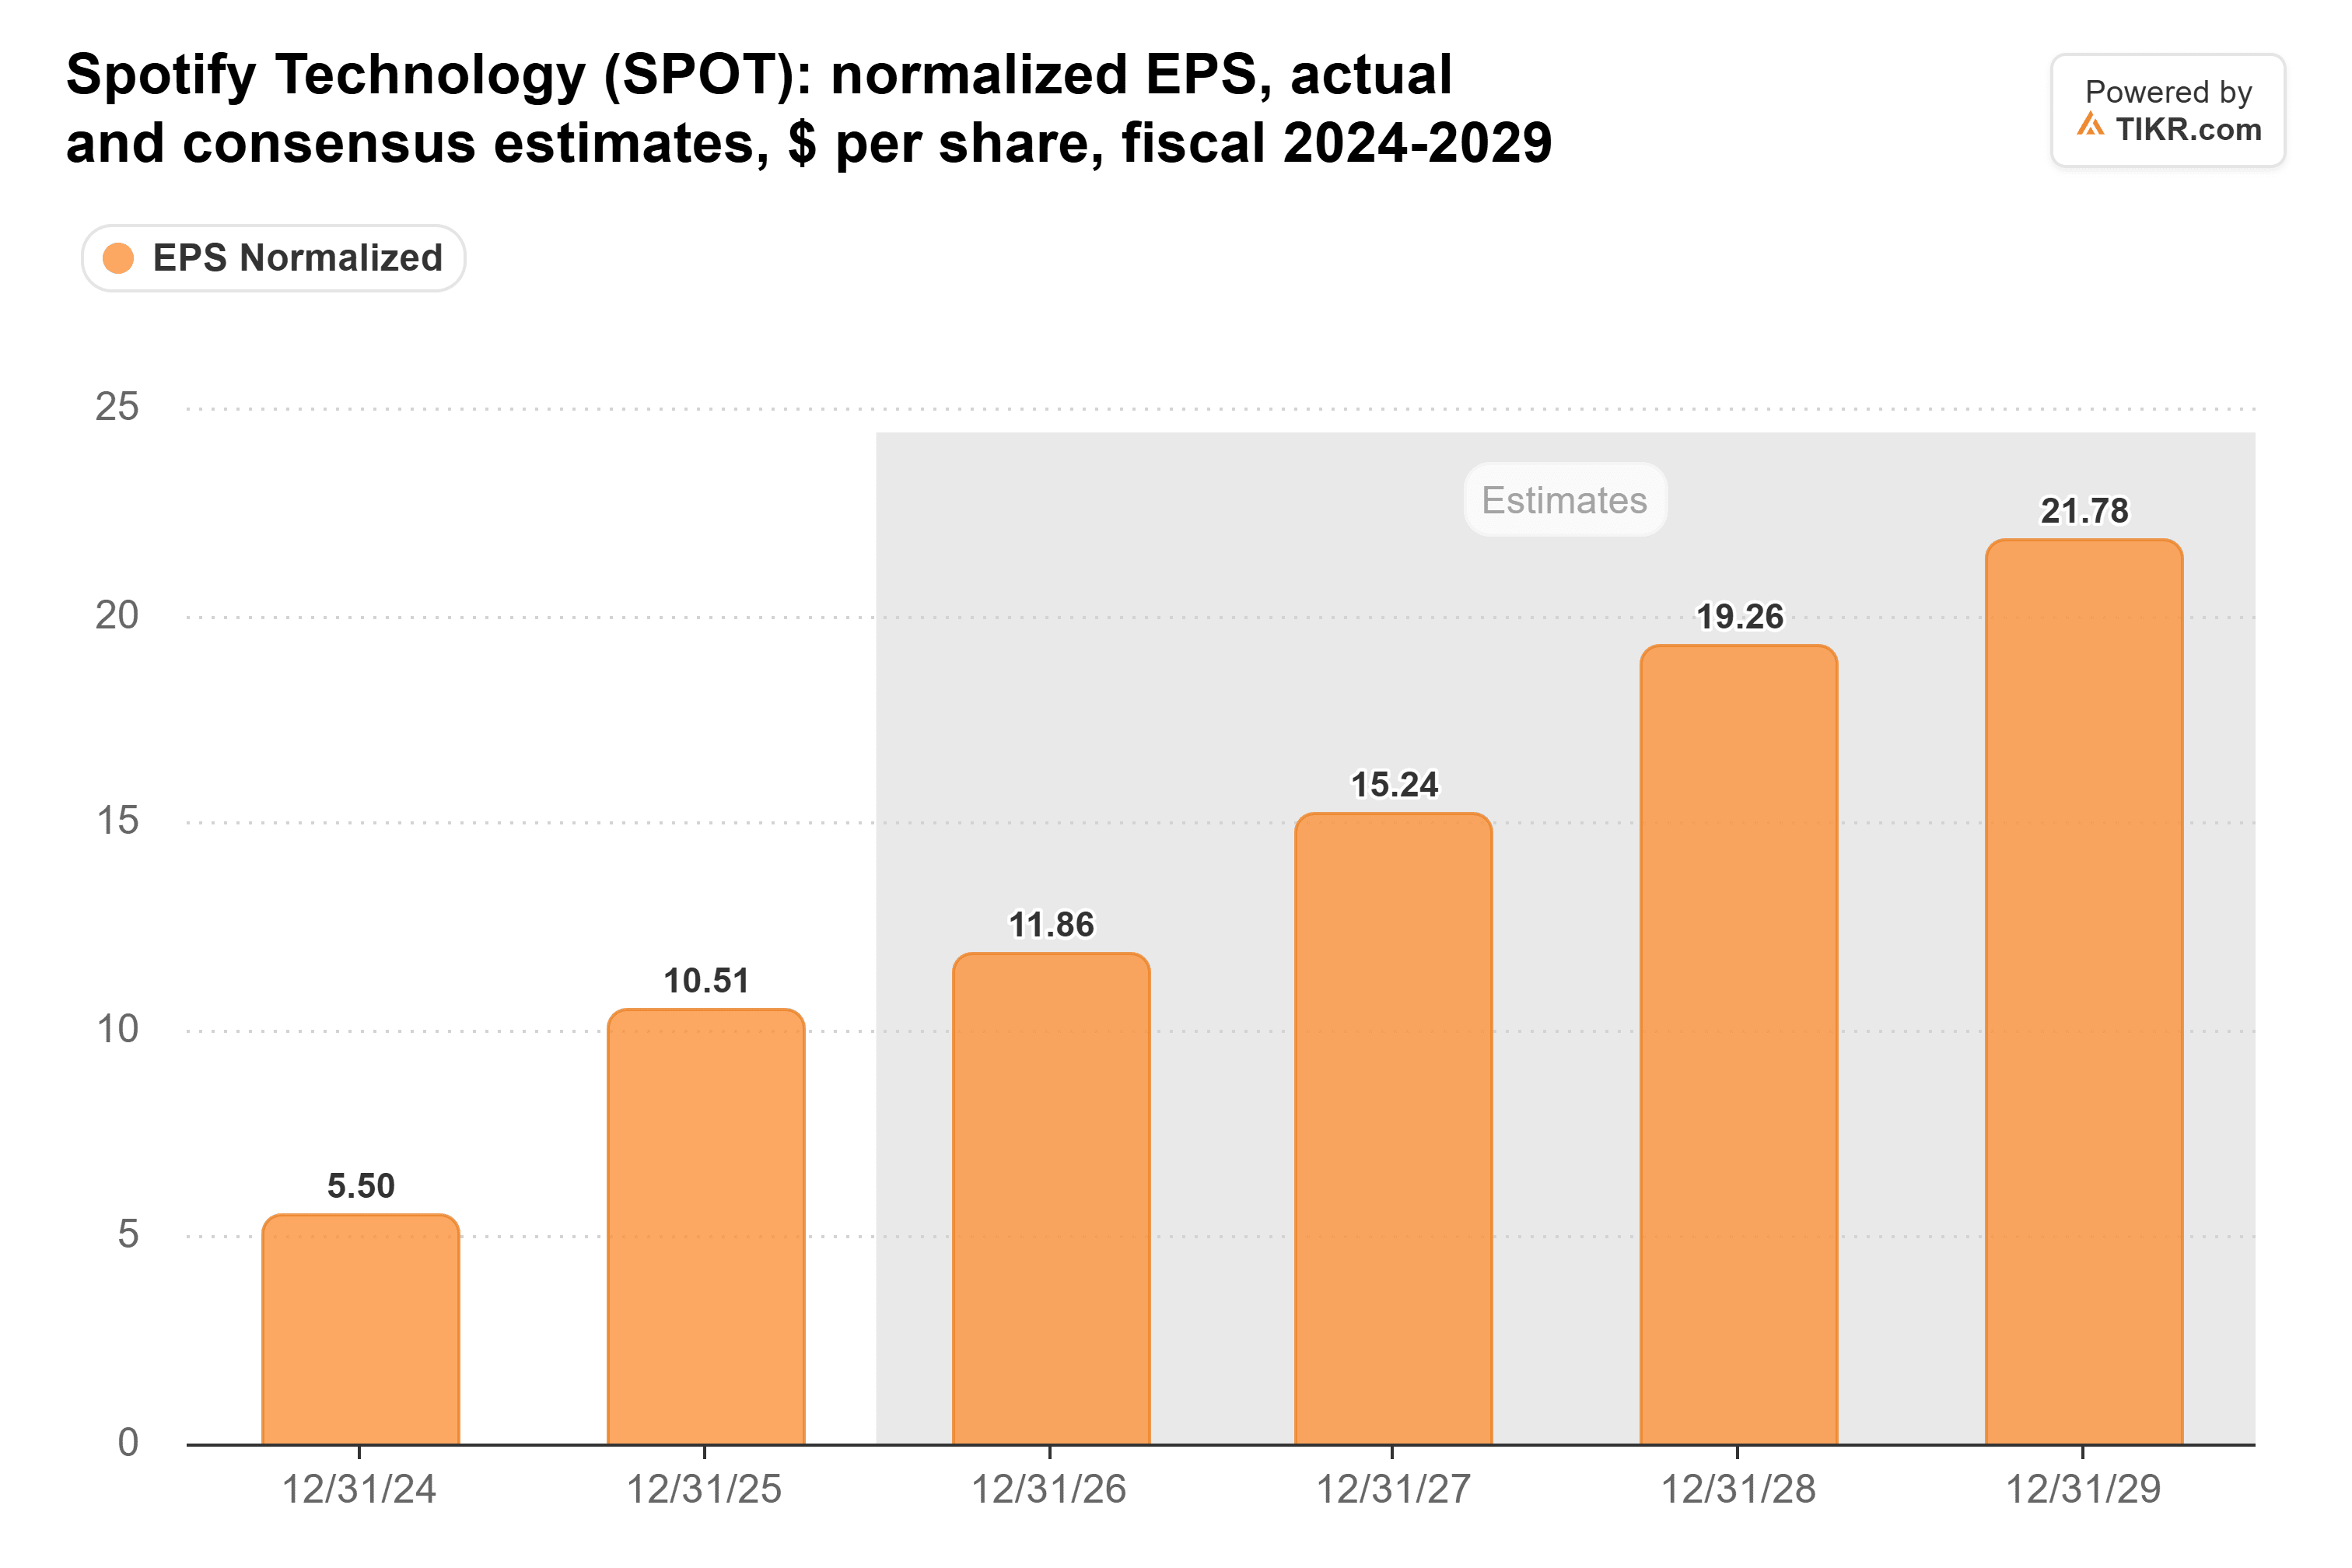
Analysts expect normalized EPS to rise about 45% from 2025 to 2027:
AI gives subscribers something new to pay for
Premium revenue per user grew 7.5% at constant currency in the third quarter. Management guides 4.5% to 5% for the fourth quarter as Spotify laps price increases in more than 150 markets.
On Oct. 30, the Financial Times reported that Spotify plans a paid AI remix and cover service for early 2027. It could cost $4 to $5 a month extra. Universal Music Group has reportedly signed, but Sony Music and Warner haven’t.
Warner has leverage. Its recorded-music subscription streaming growth sped up to 15% last quarter. Warner credits that partly to higher per-subscriber minimums from streaming services. It also lists AI licensing among its drivers for fiscal 2027. Whether it signs, and at what royalty, decides how much of that $4 to $5 Spotify keeps.
Wall Street is most of the way to 20%
Spotify set that target at its May investor day, and the operating margin has already climbed from -5.6% in 2022 to 12.8% in 2025:
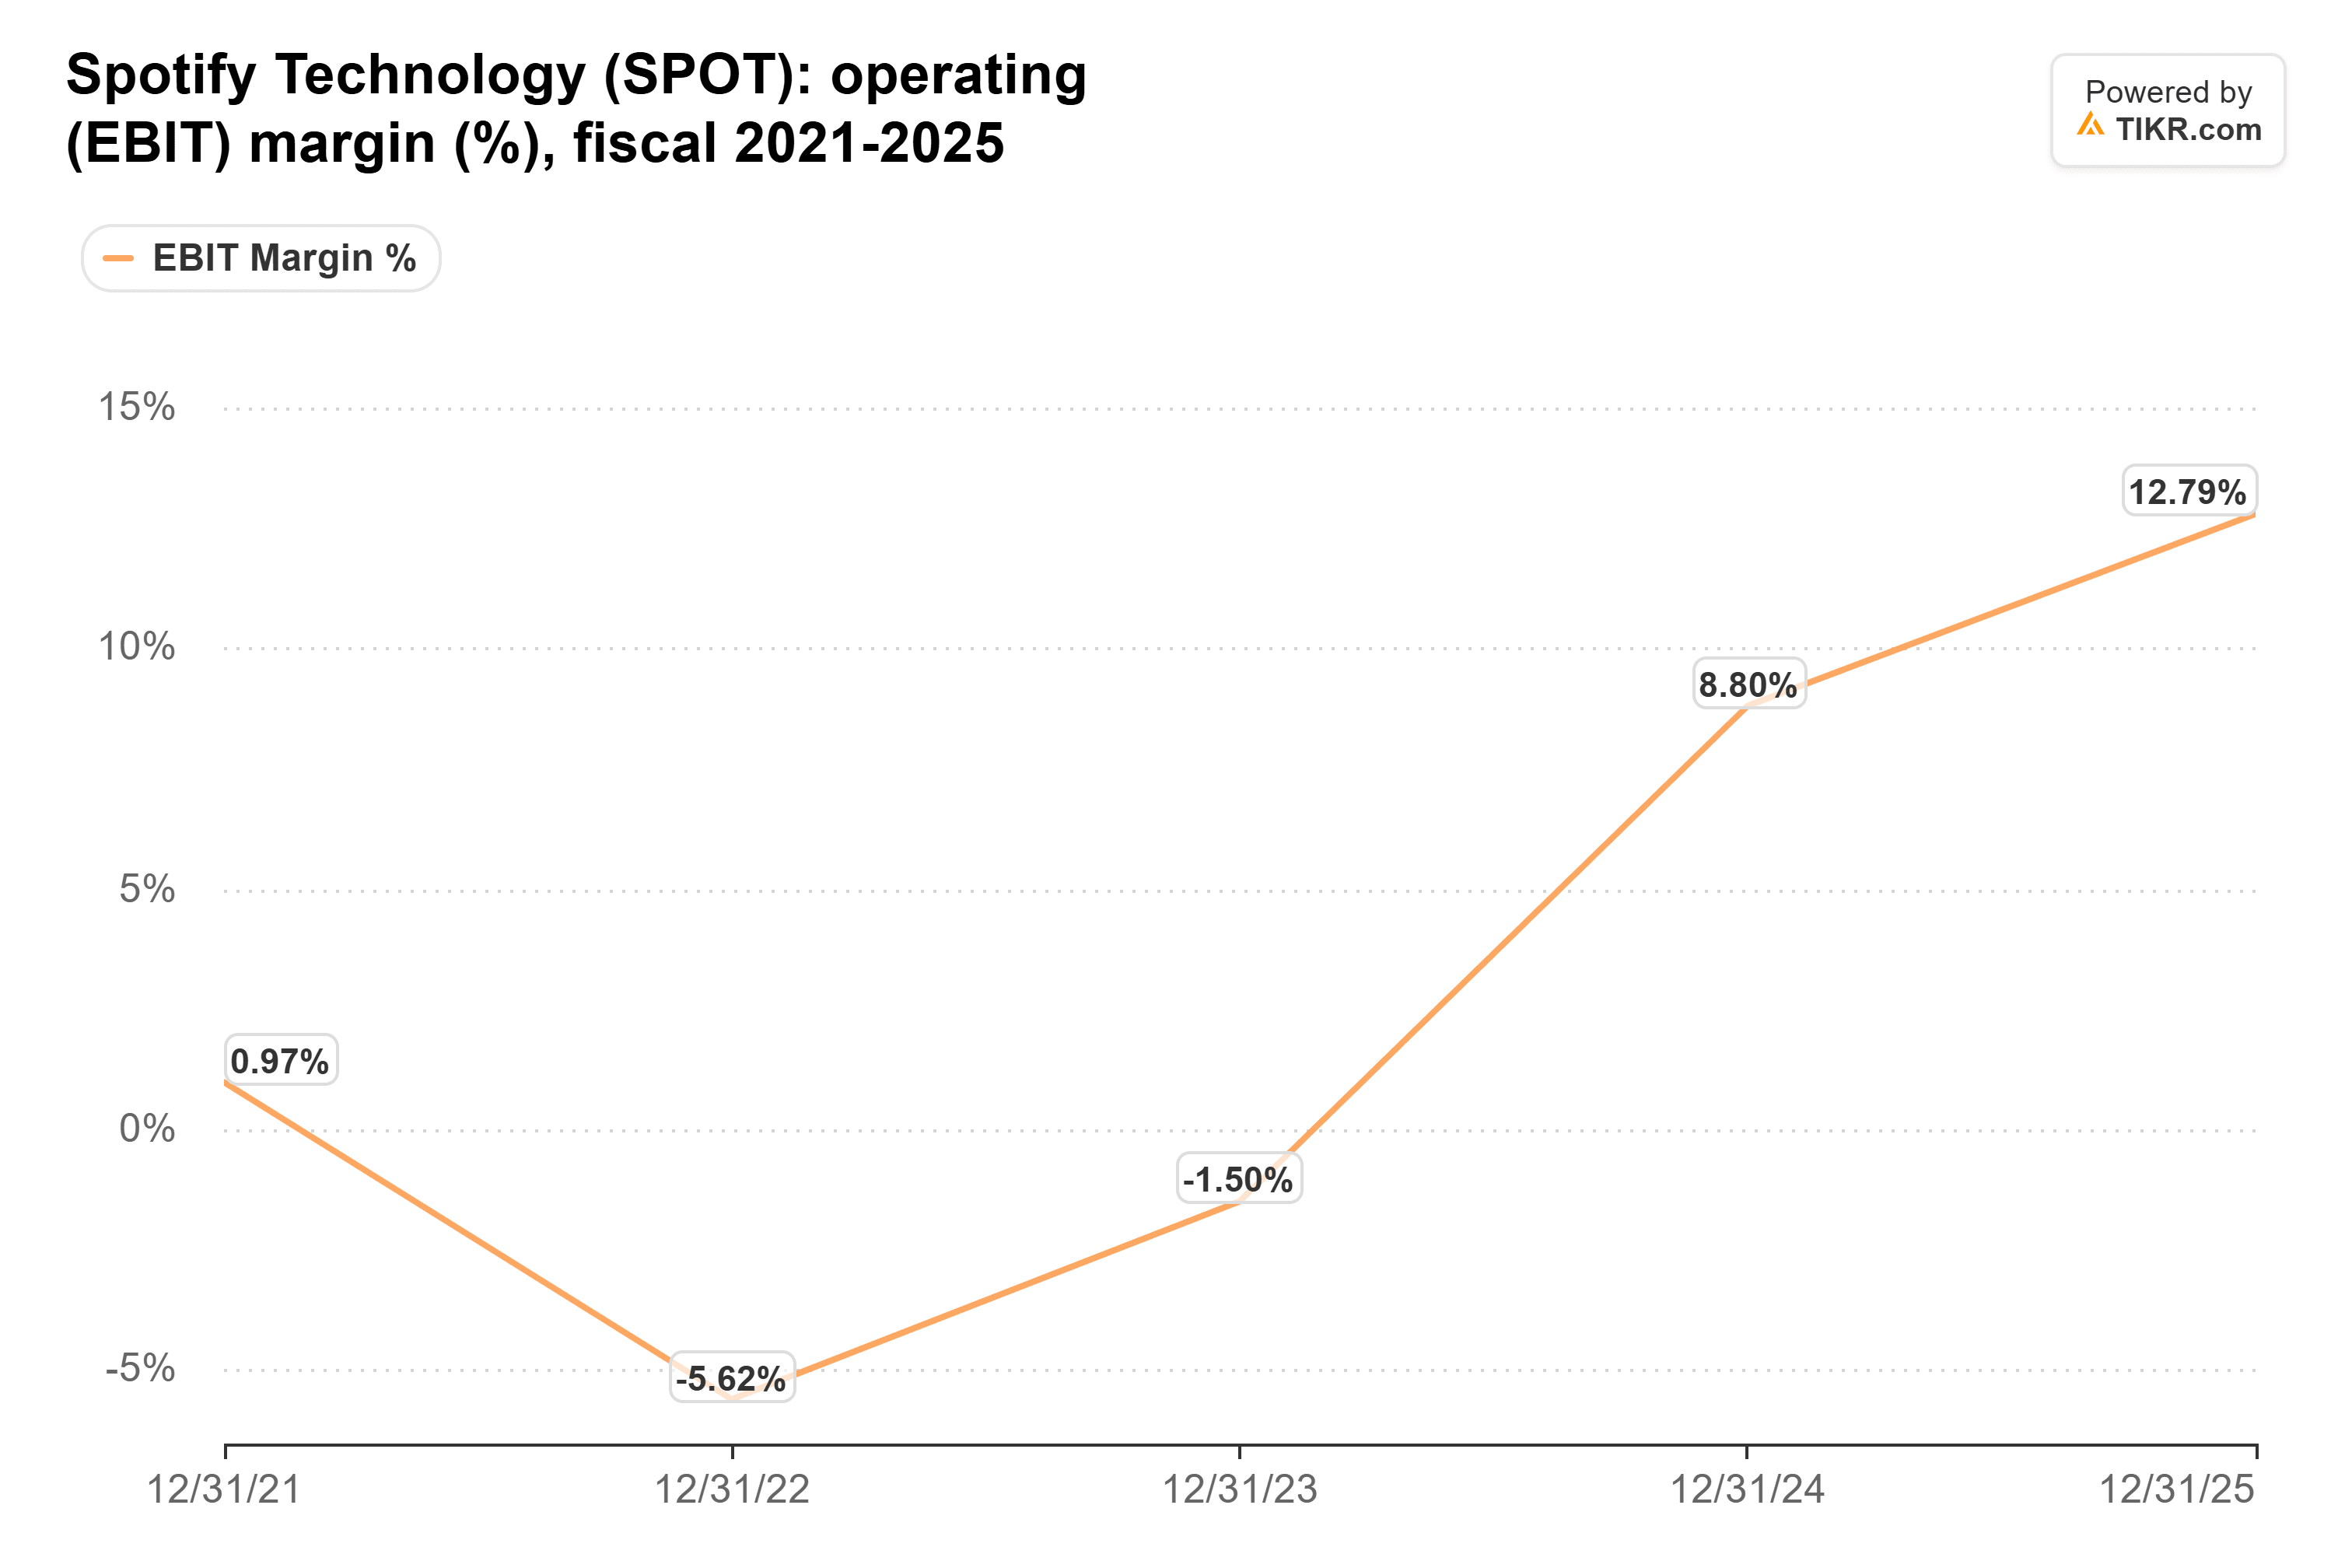
Analysts expect 18.6% by 2028. Yet Spotify trades under 40x forward earnings, below the roughly 48x it averaged at quarter-ends since early 2024.
I’d buy for the long haul: margins keep rising, and analysts’ estimates don’t include the remix add-on yet. The risk is AI spending, which co-CEO Gustav Söderström expects to stay near today’s level. The test comes in early February: 10 million net adds, €820 million of operating income, and a 2027 outlook with costs growing slower than revenue.
So what is Spotify stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Spotify could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!