Key Takeaways
- Shopify shares fell 8.7% on November 3 after merchandise volume and subscription gross profit missed estimates, even as revenue rose 32%.
- Merchant solutions revenue grew 35% to $2.91 billion, while subscription solutions grew a slower 20% to $836 million.
- Gross profit grew 28%, four points slower than revenue, and fourth quarter guidance keeps that gap.
- The fourth quarter report, expected in February, will show whether holiday volume reaccelerated and revenue growth stayed in the low 30s.
Shopify (SHOP) grew revenue 32% in the third quarter. Investors still sold the stock down 8.7% on November 3.
The trouble sat in two small lines. Gross merchandise volume reached $119.15 billion against a $120.03 billion StreetAccount estimate. Subscription gross profit of $661 million also missed by about $19 million.
Those are thin misses for a company growing this fast. By comparison, Amazon (AMZN) grew third quarter net sales 12%, and its North America segment grew just 6%.
Shopify is also betting its next leg of growth on AI agents. In September, it partnered with Meta Platforms (META) to put Shop Pay checkout inside Muse, Meta’s personal AI agent, across every Shopify store.
Strong quarter, two small misses
Adjusted EPS of $0.49 topped the 46 cent LSEG estimate. Revenue landed just below consensus, though, and Bloomberg noted it was Shopify’s first revenue miss since 2022.
The core numbers still looked healthy:
- Revenue rose 32% to $3.74 billion, from $2.84 billion a year earlier.
- Operating income jumped 66% to $568 million.
- Free cash flow margin reached 22%, up from 18% a year ago.
Shopify’s top line has barely wobbled in two years…
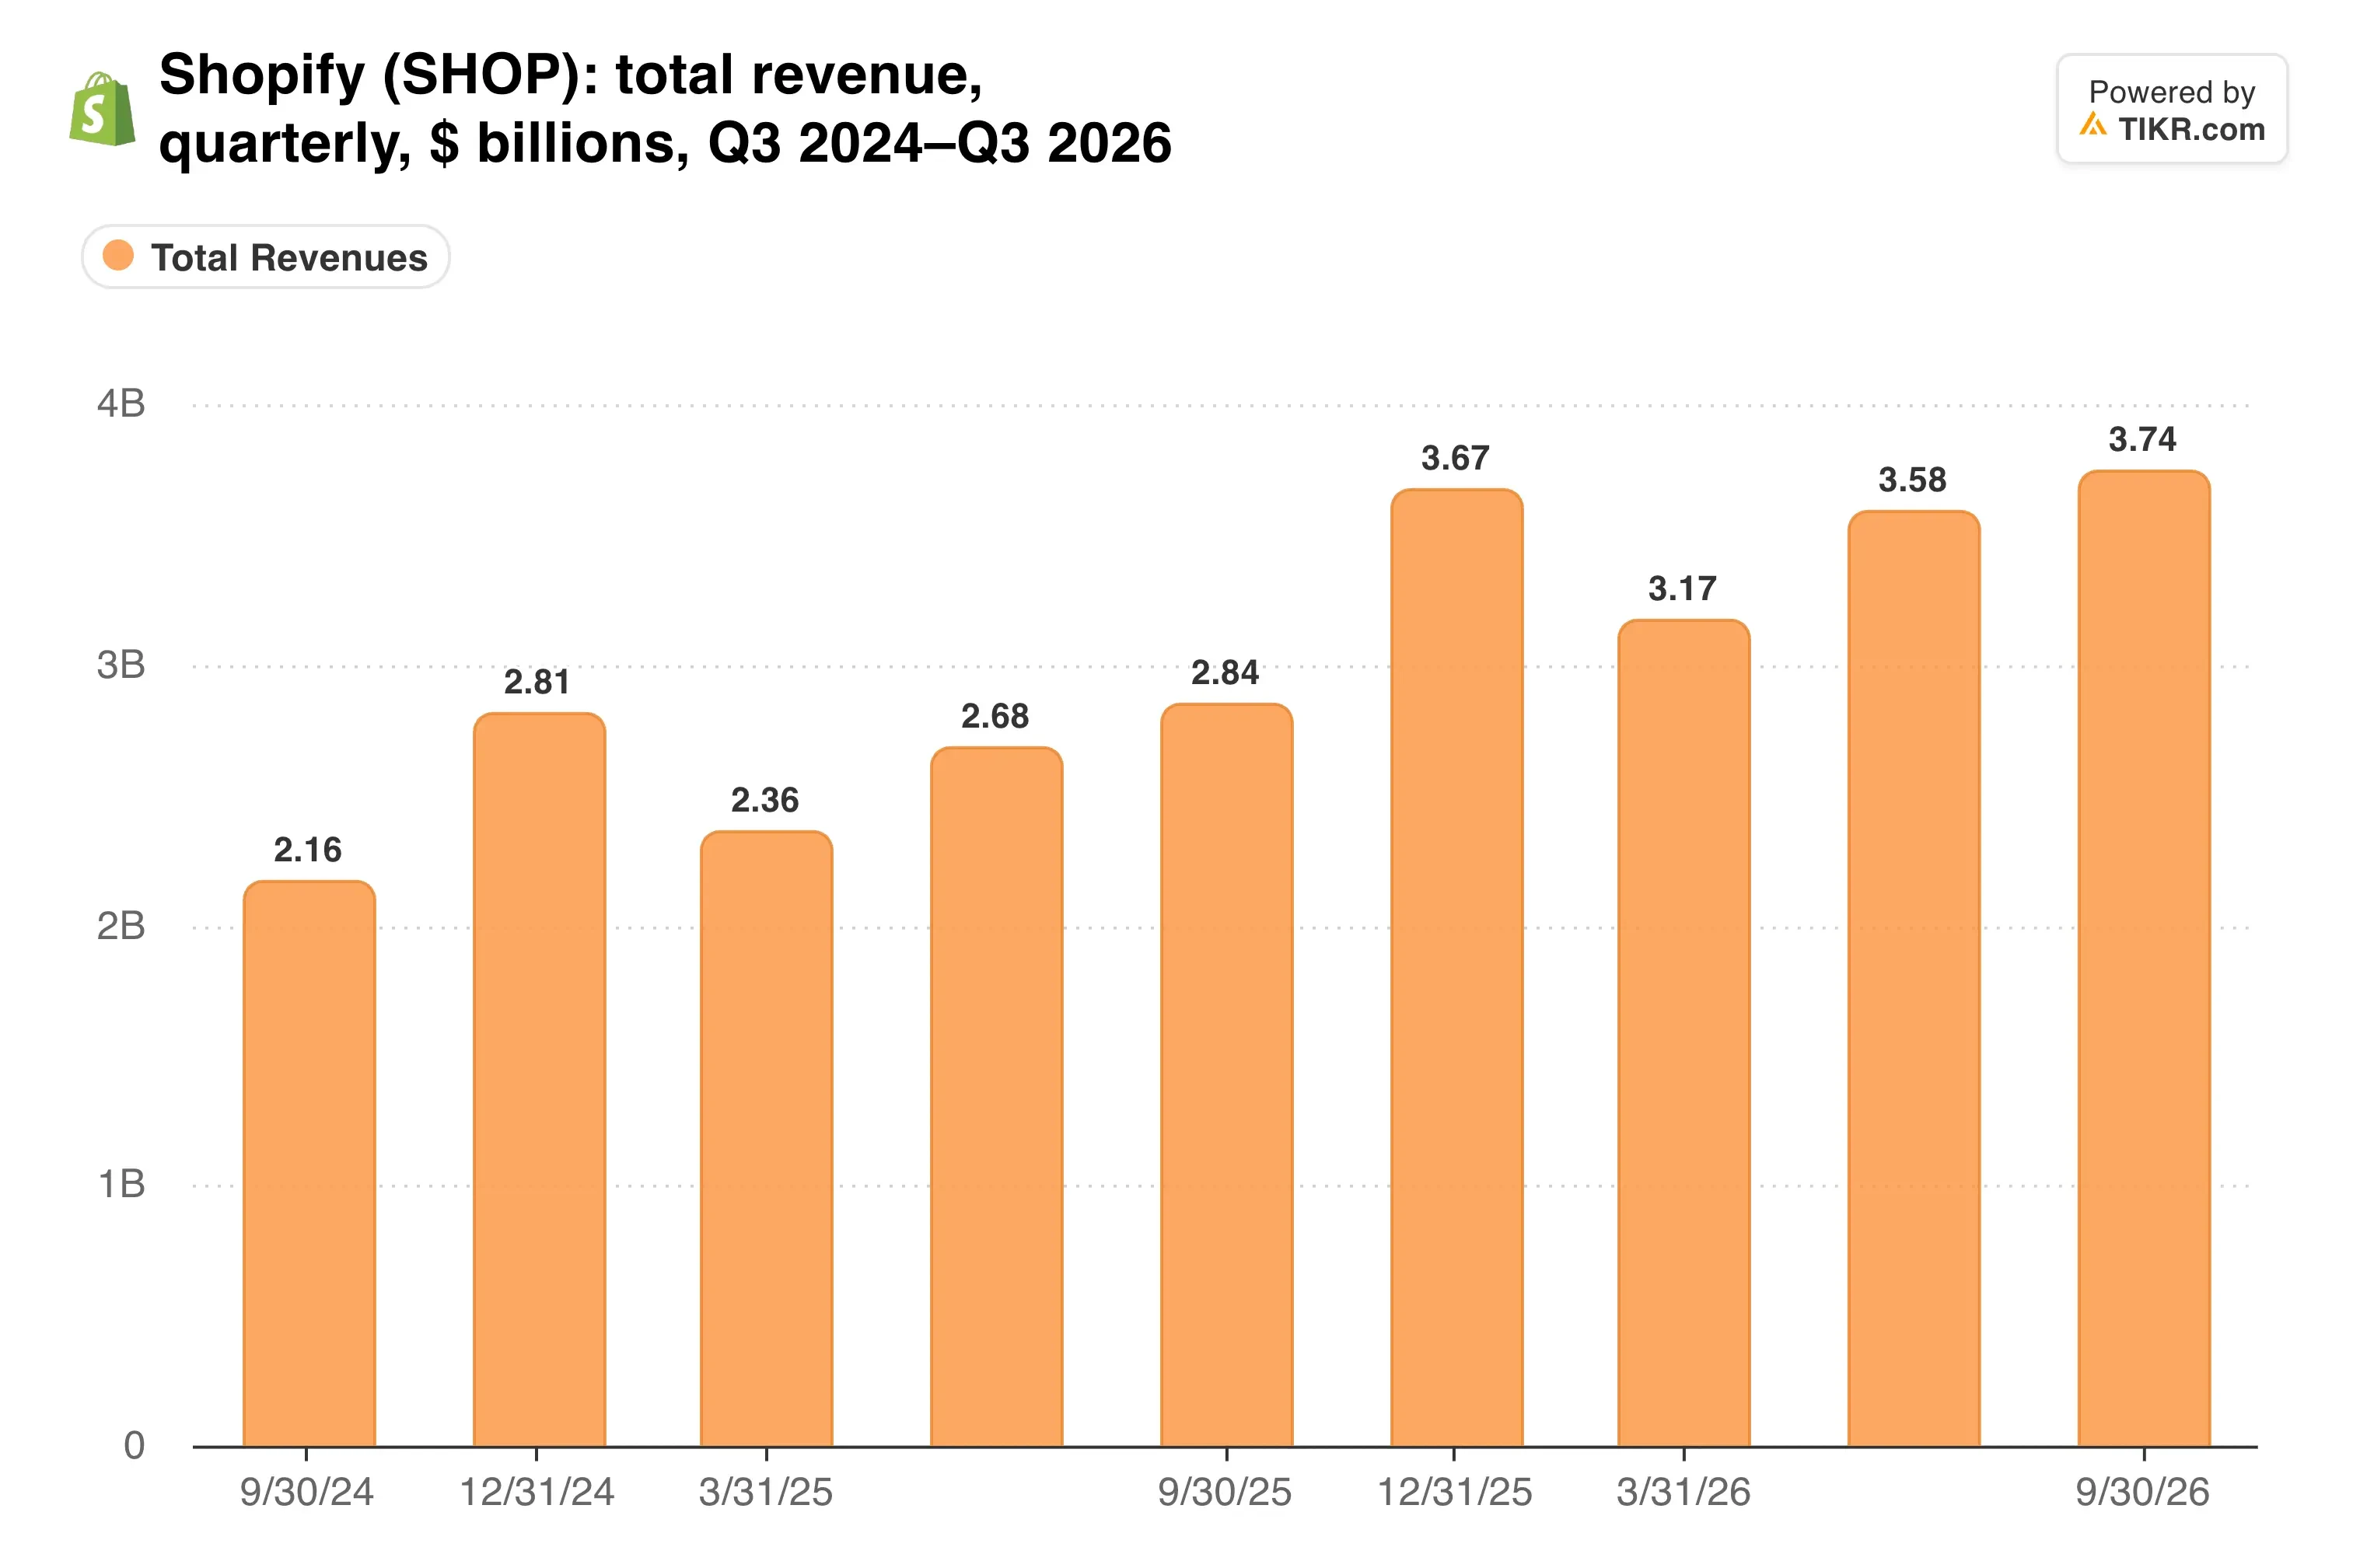
Growth has stayed between 31% and 34% for six straight quarters. That steadiness is exactly why a small miss stung, since the stock was priced for clean beats.
TIKR tracks 54 analysts on Shopify. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Shopify, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Shopify’s Analyst Ratings
Payments are doing the work
Merchant solutions, which is mostly payments, carries Shopify’s growth. Its revenue rose 35% to $2.91 billion. Subscription solutions grew 20% to $836 million, and that slower line is where analysts found their miss.
That mix matters. Merchant solutions now produces more than three quarters of revenue, and it’s where AI agents plug in.
On the earnings call, President Harley Finkelstein said Q3 “was the first time we saw shoppers experimenting with delegated purchasing through personal agents.” He added that orders from AI channels rose 3.3x from a year earlier.
The Meta deal widens that channel. CEO Tobi Lütke announced the Muse partnership on September 21, and agent checkouts through Shop Pay run on Shopify’s own payment rails at merchants’ usual rates.
The payments engine also throws off a lot of cash.
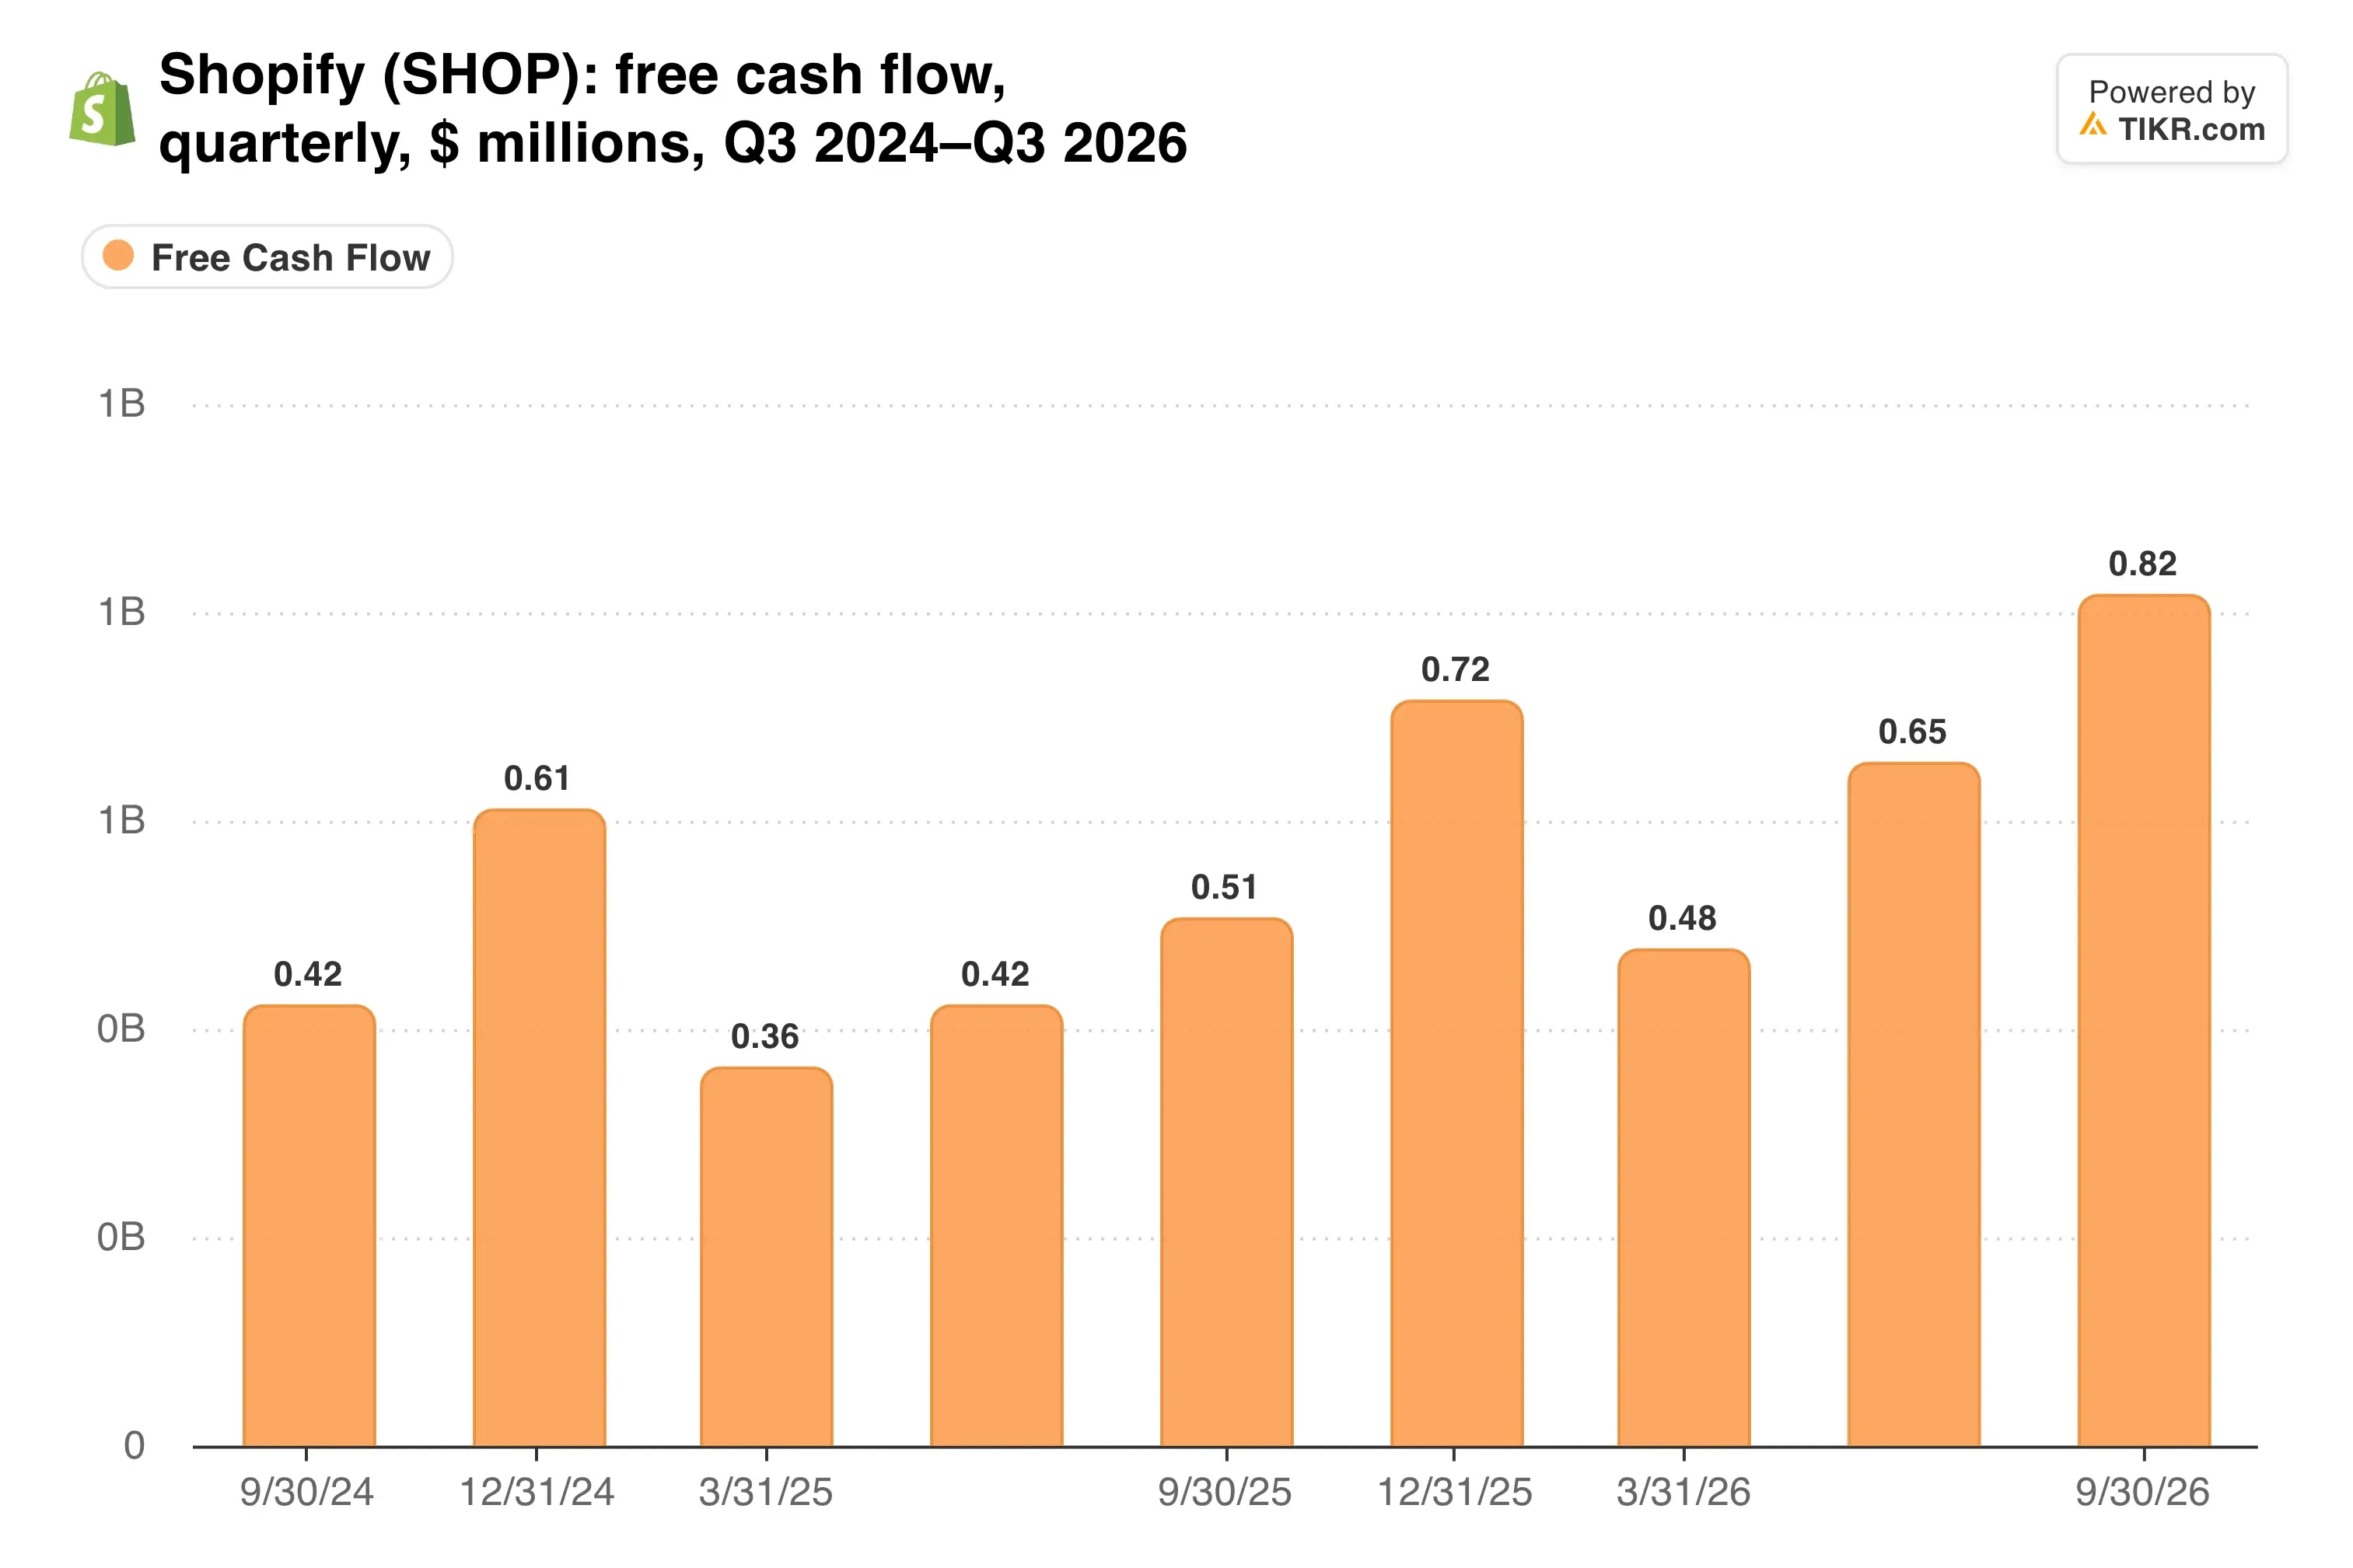
That cash pays for the agent buildout while free cash flow margins keep widening.
Still, Shopify hasn’t put a dollar figure on agentic sales. Until it does, the channel can’t offset an $885 million volume shortfall in investors’ eyes.
Gross profit trails revenue
Gross profit rose 28% to $1.78 billion, four points slower than revenue. Payments carry thinner margins than subscriptions, so a heavier payments mix weighs on the ratio.
Operating leverage hides much of that drag. Expenses fell to 32% of revenue from 37% a year earlier. Gross margin, on the other hand, has gone sideways…
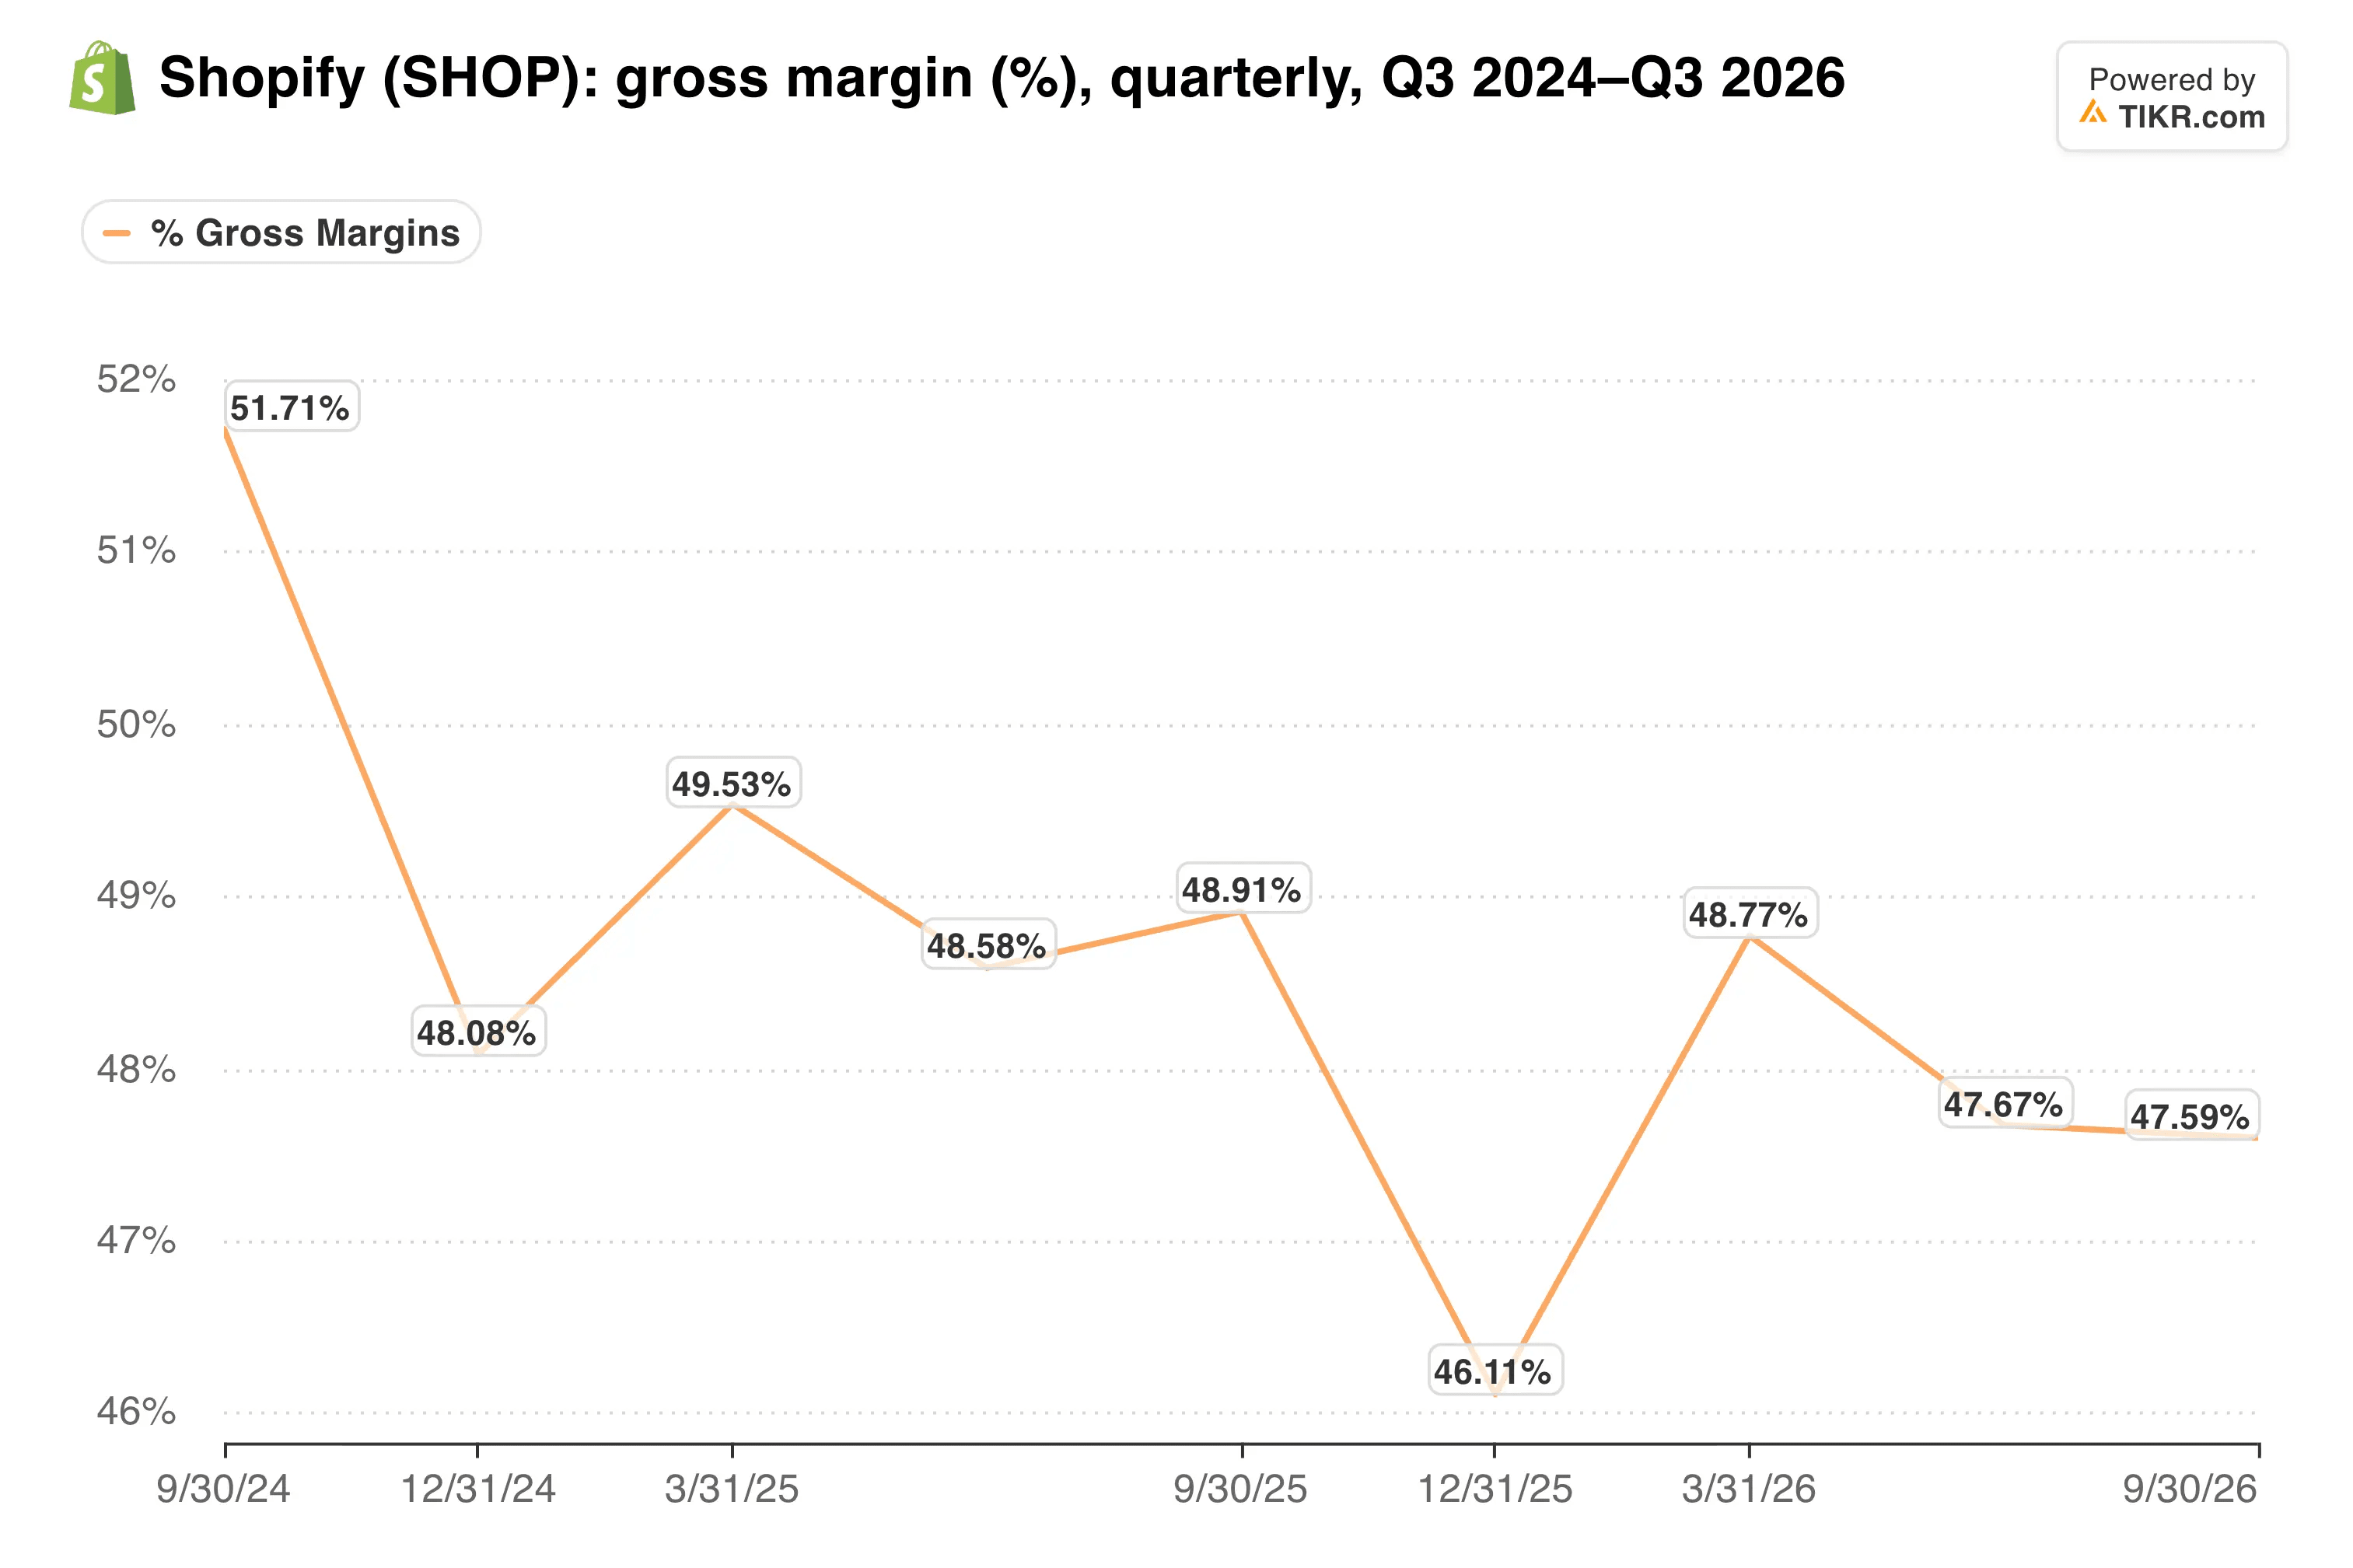
It held at 47.6% in the third quarter, unchanged from the second.
Fourth quarter guidance keeps the same gap. Shopify expects revenue growth in the low thirties and gross profit growth in the high twenties. It also sees operating expenses at 29% to 30% of revenue, while free cash flow margin should match the fourth quarter of 2025.
My take: The business delivered, and the selloff says more about the price than the quarter. Even after the drop, Shopify trades at a premium multiple to Amazon and most software peers. I’d hold rather than chase, because the stock needs volume growth back above 30% and a real agentic sales number to earn that premium.
The next test is the fourth quarter report, expected in February. It will show whether holiday volume reaccelerated and whether revenue growth stays in the low 30s for a seventh straight quarter.
So what is Shopify stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Shopify could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!