


Key Takeaways
- Sandisk fell 21% in the past week on no news of its own, as Jensen Huang’s Nvidia exit dragged down memory stocks, Micron and SK hynix included.
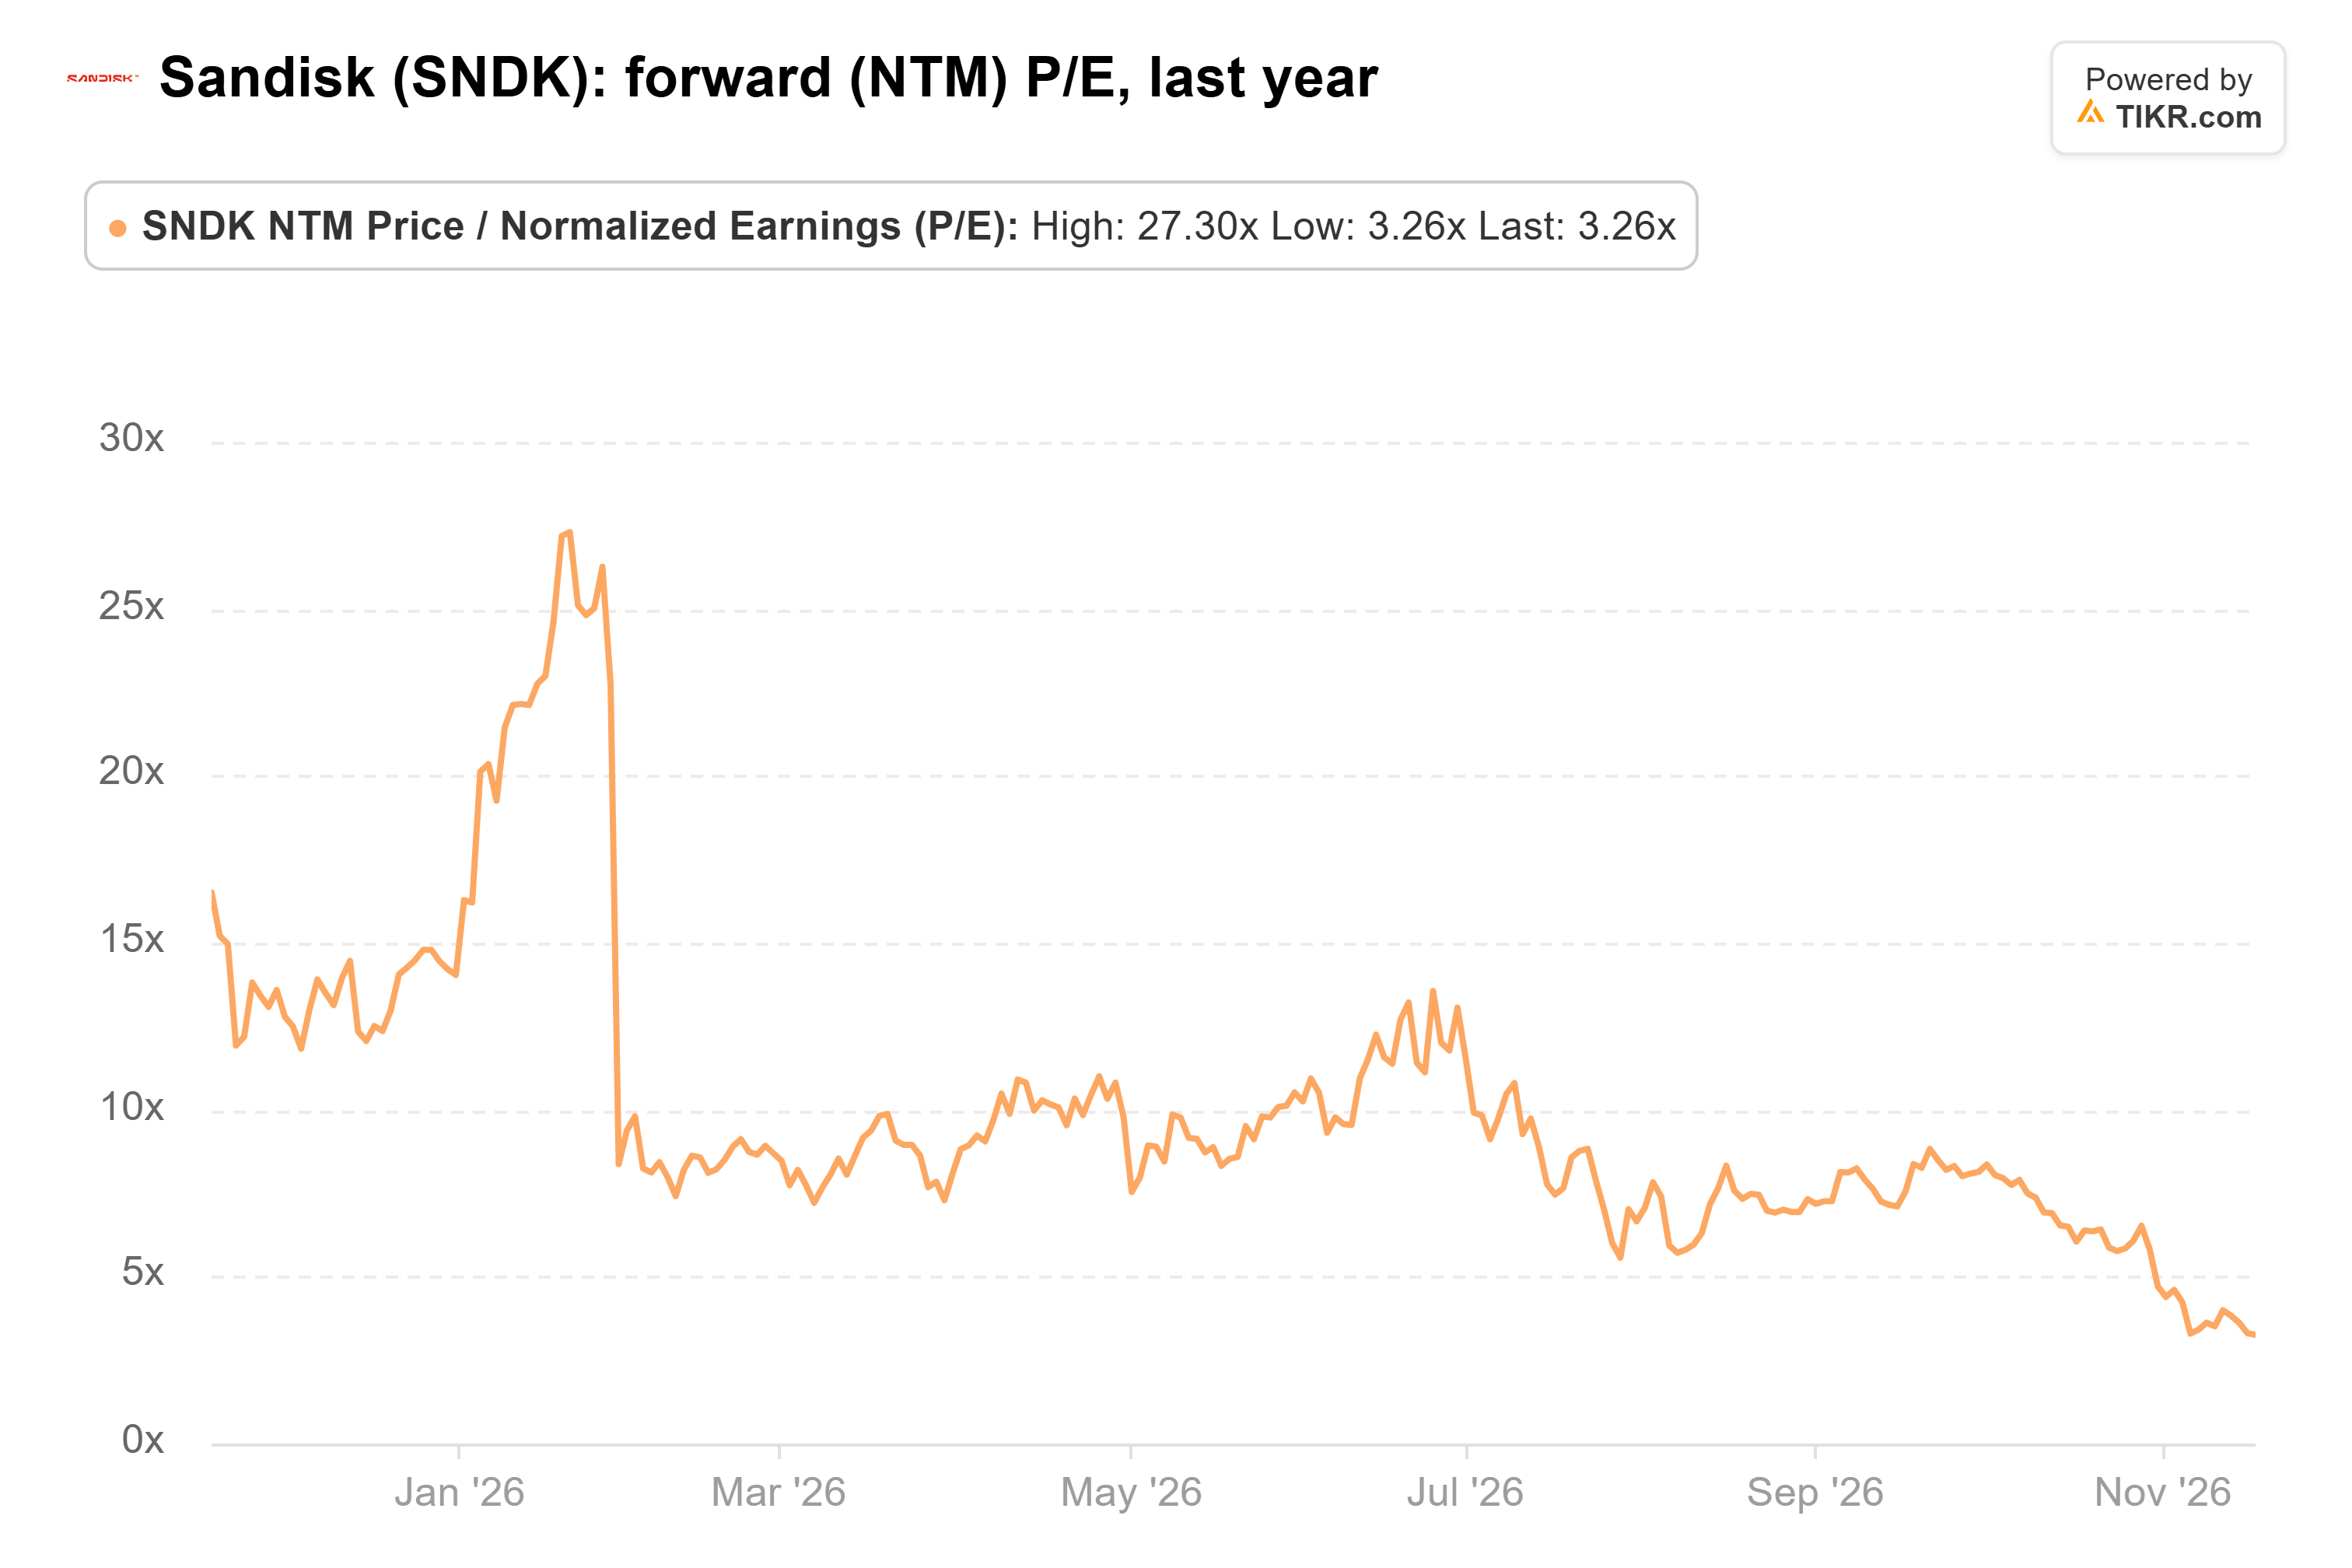
- Analysts still expect Sandisk’s earnings to more than triple this fiscal year, yet it trades near its lowest forward P/E in a year.
- Flash prices are the real risk, but Sandisk looks like a buy a piece at a time before its late-January report.
Sandisk (SNDK) is down 21% in the past week, and the news behind it was Nvidia’s. Jensen Huang’s exit as CEO of Nvidia (NVDA) set off a chip selloff that hit memory hardest: Micron (MU) fell 13%, and SK hynix (SKHY) 14%.
Memory took the worst of Nvidia’s week
Nvidia’s strong Nov. 17 report showed purchase commitments up to $390 billion from $279 billion in August. It brought only a brief bounce before Nvidia confirmed Huang won’t return.
Micron and SK hynix sell Nvidia the high-bandwidth memory in its AI chips, so they’re first in line for those commitments. Micron expects supply to stay tight through fiscal 2028, and SK hynix sees demand outrunning supply through 2030.
Sandisk sells flash, and flash prices were already cooling. Kioxia, its fab partner, said its NAND price gains slowed to the mid-20s percent in the September quarter, down from about 70%. My read: that’s why Sandisk fell harder than the memory makers Nvidia buys from.
TIKR tracks 25 analysts on Sandisk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Sandisk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Sandisk’s Analyst Ratings
The business hasn’t budged
Sandisk’s revenue rose 378% from a year earlier in the quarter to Oct. 2, to $11.0 billion, at an 85.1% non-GAAP gross margin. And analysts haven’t cut their estimates. They expect normalized EPS of $227.48 in fiscal 2027 and $289.05 in fiscal 2028, up from $70.88 in fiscal 2026:
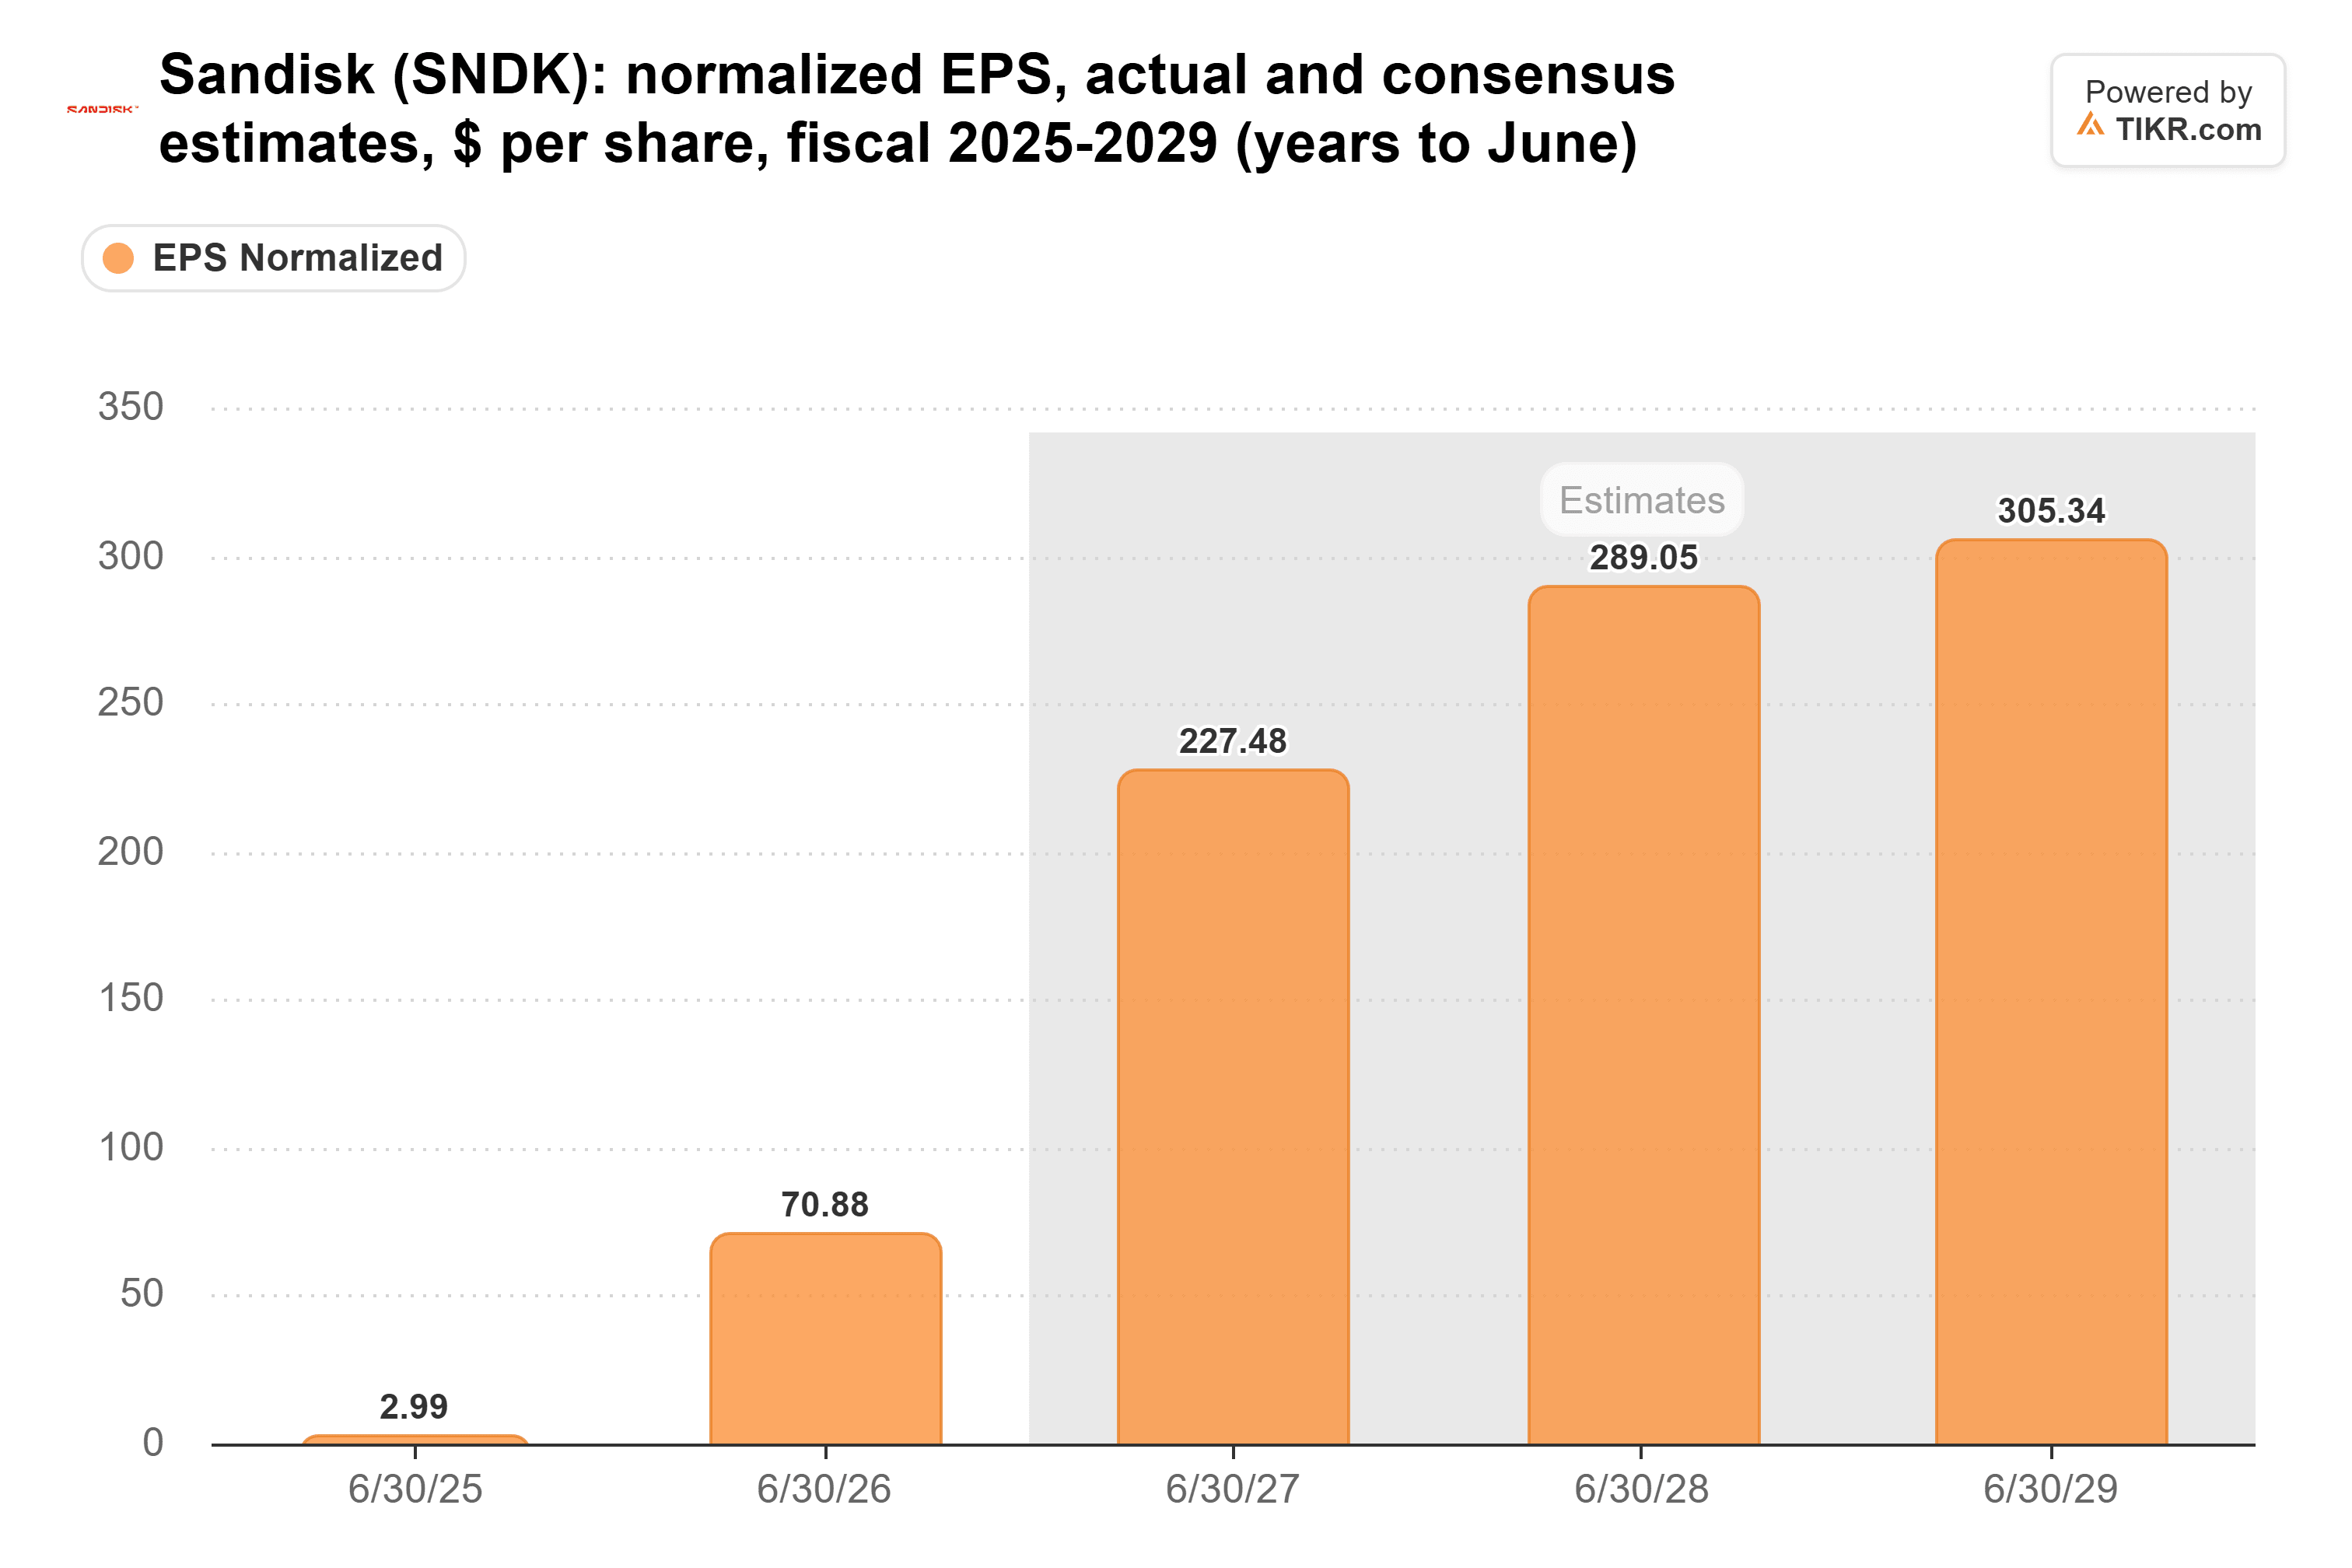
(Those are pre-split figures: the 8-for-1 split takes effect Nov. 20.)
Yet Sandisk traded at 3.3x forward earnings on Nov. 17, against a 10x average over the past year:
Priced for a bust
At that multiple, investors are betting on a bust, and Sandisk’s supply contracts are a cushion. It had $88.9 billion of remaining performance obligations on Oct. 2, priced at contract floors. Management says those floors still earn about an 80% gross margin. The contracts are young, and flash is a brutal cycle. Still, Bernstein’s $3,000 target (pre-split), kept on Nov. 17, is about 10x fiscal 2028 estimates by my math, right at Sandisk’s one-year average. I’d buy a piece at a time.
Sandisk reports in late January. Revenue at the top of its $12.2 billion to $12.6 billion guide would help confirm the case. So would a March-quarter outlook at or above the $12.48 billion analysts expect, plus a backlog above $88.9 billion.
So what is Sandisk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Sandisk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


