Key Takeaways
- NVIDIA closed at a 52-week low on Nov. 19, down 39% from its high, two days after reporting $115.8 billion of third-quarter revenue.
- D.A. Davidson’s Gil Luria called NVIDIA one of the “highest risk” chip stocks and pointed investors to Broadcom, AMD and Micron instead.
- At about 10x forward earnings, half Broadcom’s multiple, and on rising estimates, NVIDIA’s extra risk looks well priced to me.
- The risk every chip stock shares is slower AI spending by buyers like Amazon, which reports again in early February.
NVIDIA (NVDA) did everything you could ask of it on Nov. 17. Third-quarter revenue jumped 103% to $115.8 billion, and management guided to $130 billion for the fourth quarter without counting on any data center compute sales to China.
Its biggest buyers are still spending, too: Amazon (AMZN) put $94.8 billion more into property and equipment over the twelve months to Sept. 30 than a year earlier, mostly for AI.
And yet NVIDIA closed at a 52-week low two days later, down 33% in a month and 39% from its high.
Gil Luria, head of technology research at D.A. Davidson, saw the risk early. On the Prof G Markets podcast on Nov. 11, a day before NVIDIA announced Jensen Huang’s resignation, he said:
“There’s a buying opportunity in semis, but NVIDIA is now one of the highest risk semis.”
His lower-risk picks were Broadcom (AVGO), AMD (AMD) and Micron (MU), which he said are “going to grow 50% to 100% next year in a healthy market.”
Nine days later, the risk part looks spot on.
The risk showed up fast
Luria’s worry was that the board’s investigation would find NVIDIA knowingly sold chips to China, or to compute providers serving Chinese companies. If some of its Asia business “was just funneling to China, that would be an actual risk to the numbers,” he said.
Since then, CFO Colette Kress has become interim CEO while the board looks for a permanent one. On Nov. 16, the Commerce Department issued a rule requiring licenses to export advanced AI chips to data centers in Indonesia, Malaysia, Singapore, Thailand and Brazil. And we’re already seeing the fallout of Chinese companies pulling back as data center buildouts in Southeast Asia have been paused or delayed.
TIKR tracks 62 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Analysts haven’t blinked. Yet.
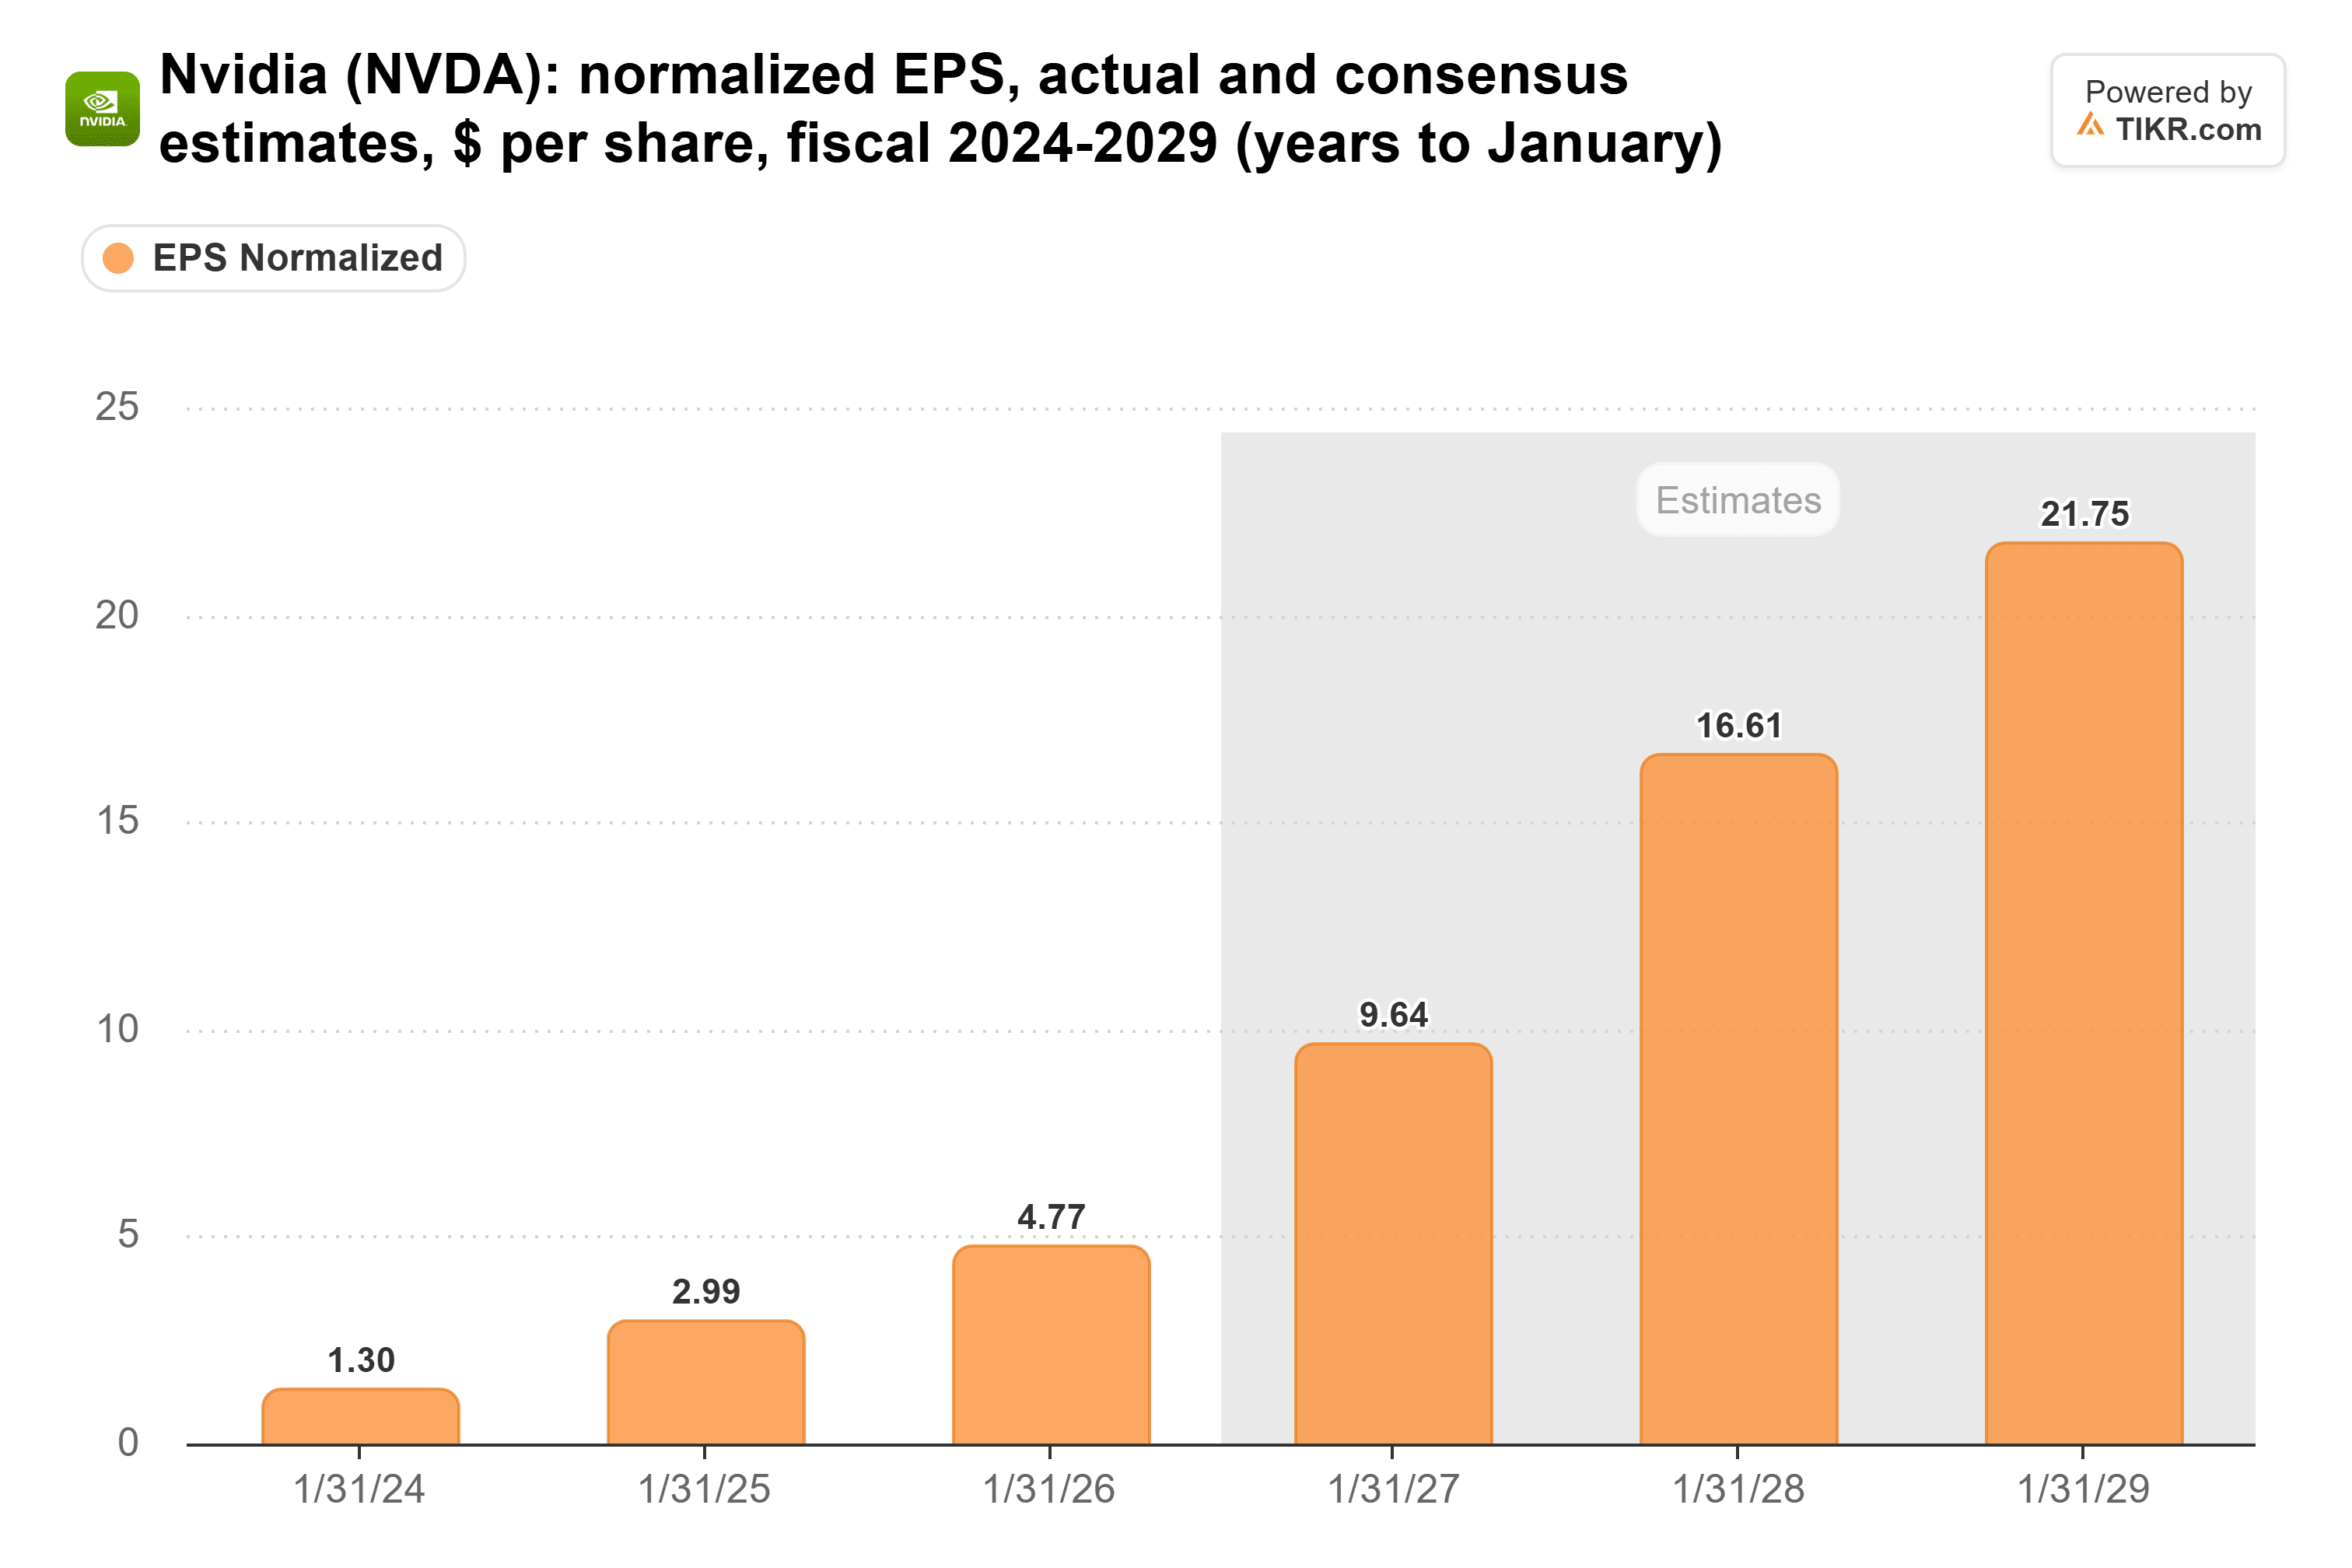
The earnings outlook hasn’t budged, though. Analysts expect normalized EPS of $16.61 for the fiscal year ending January 2028. That’s up from $15.92 in late October and more than triple the $4.77 NVIDIA earned in the year ended January 2026:
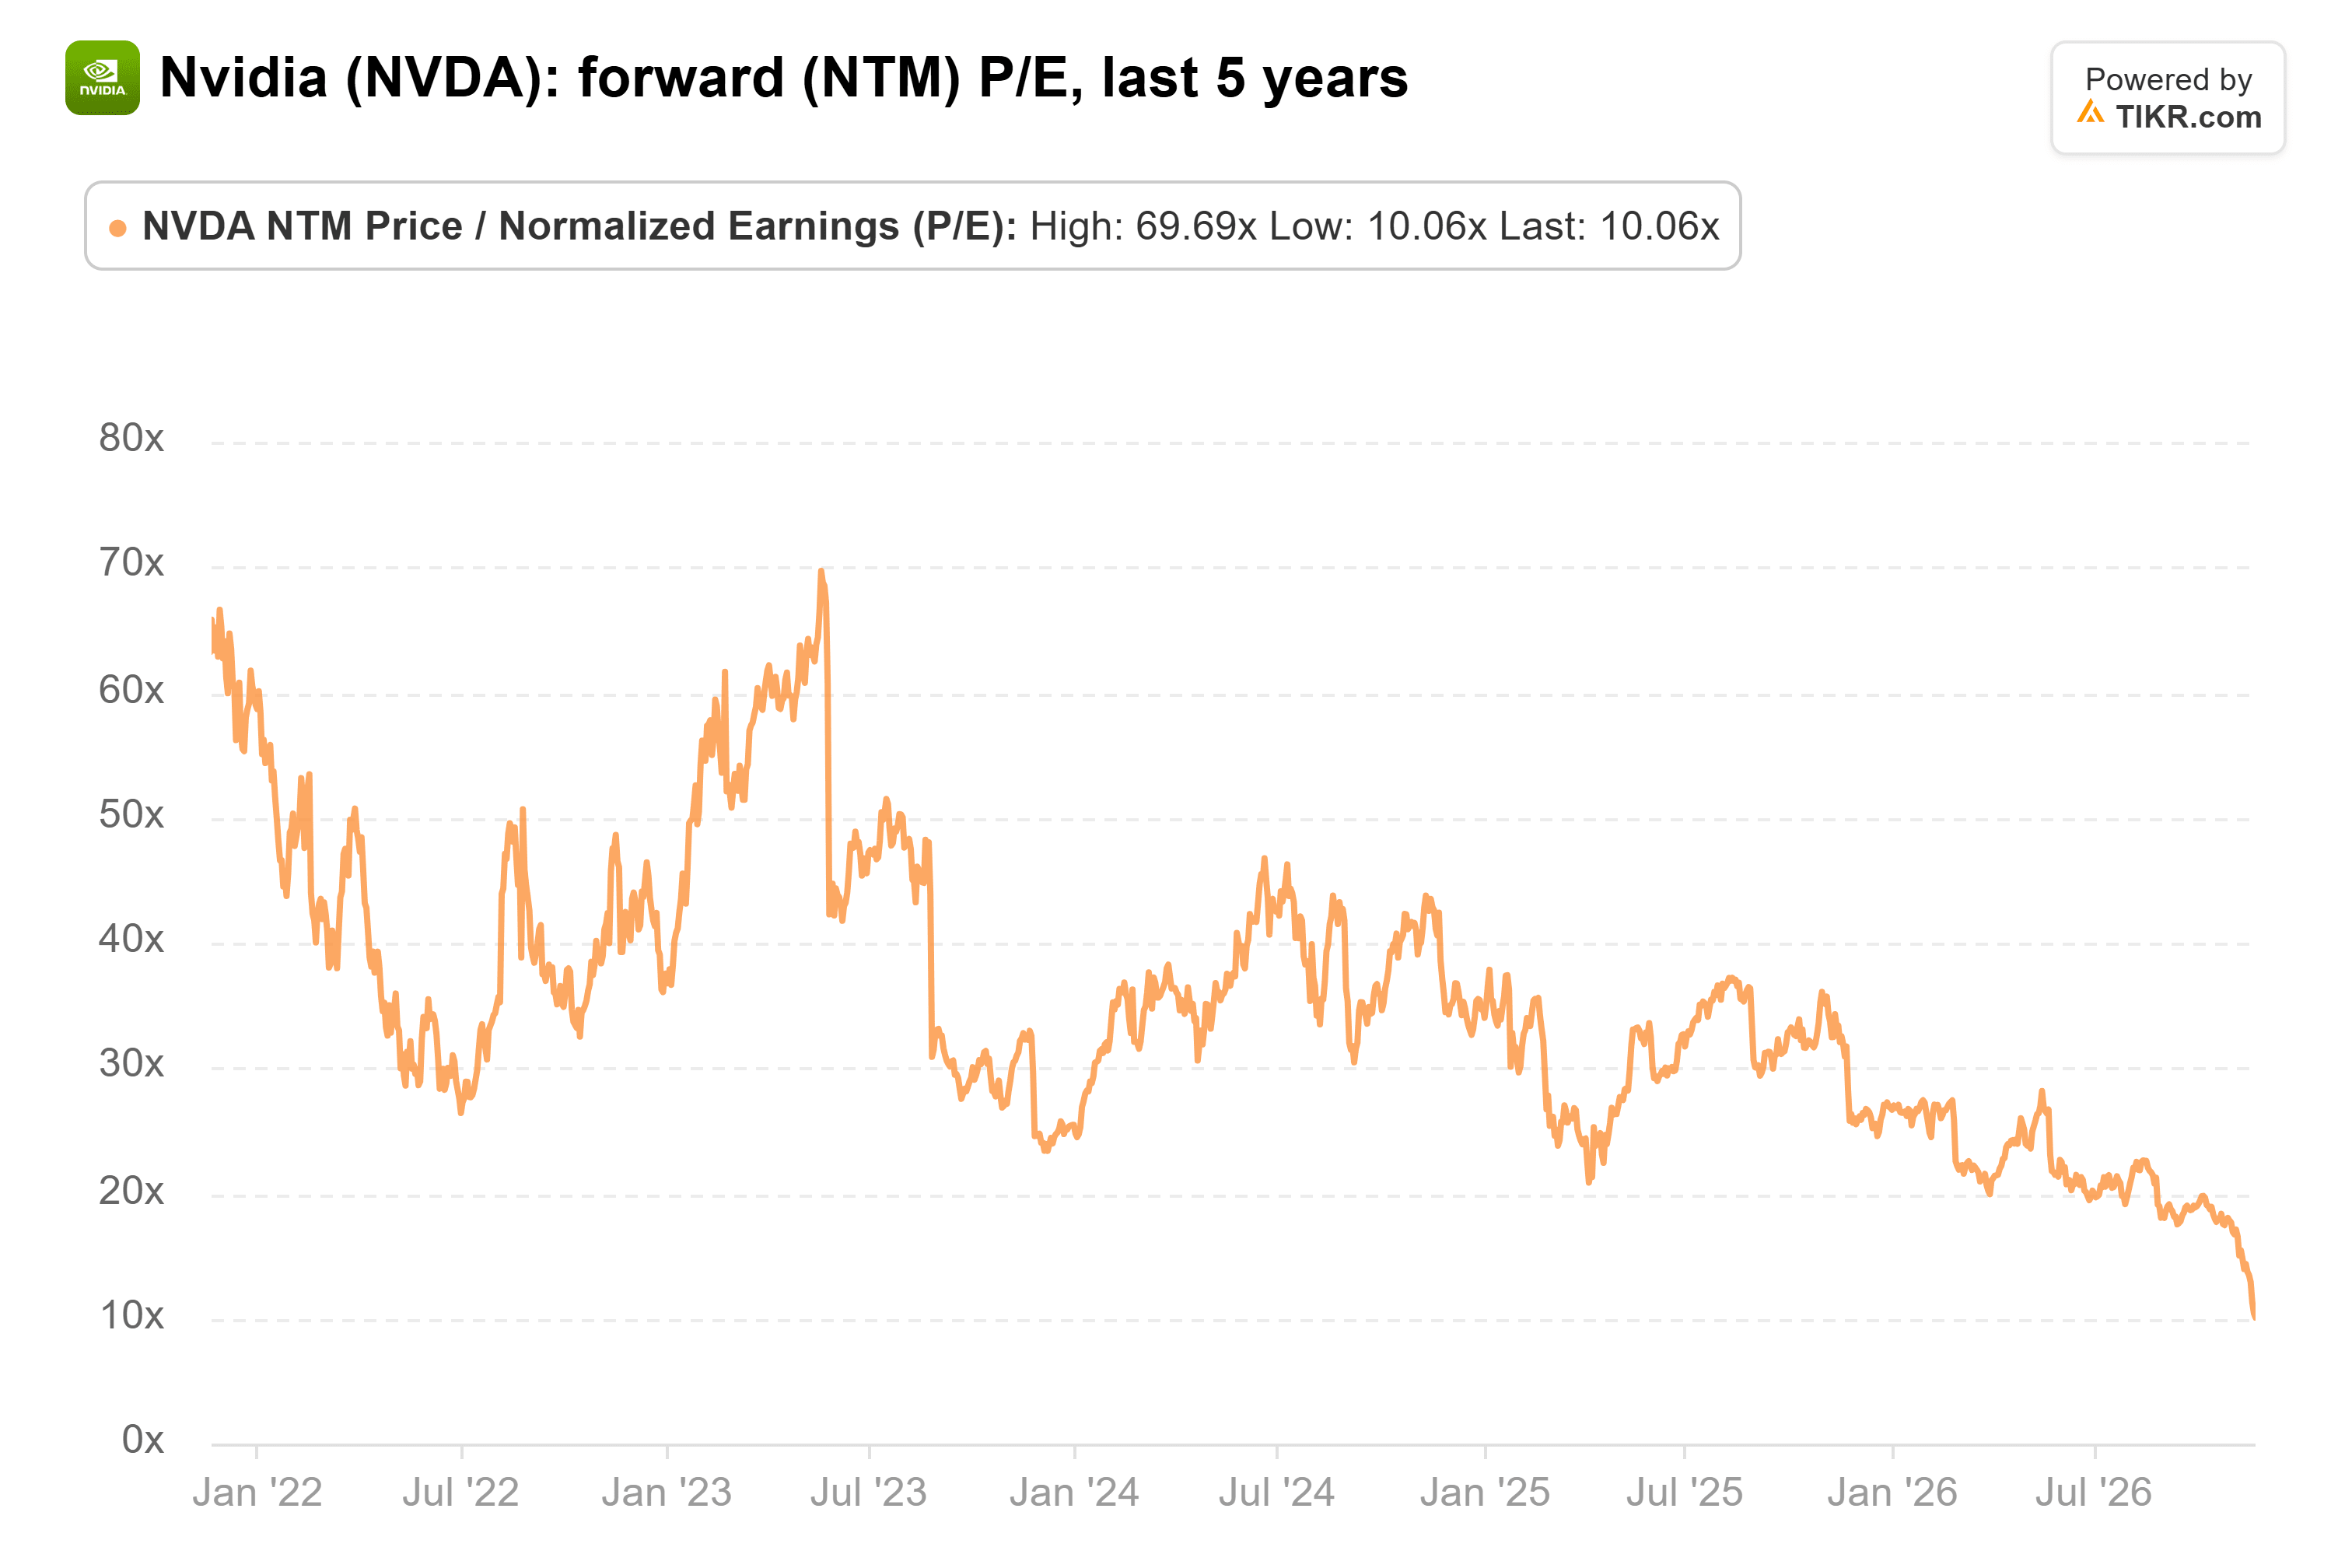
So the whole selloff has come out of the multiple. NVIDIA trades at about 10x forward earnings, the lowest point on its five-year chart and far below its 36x average:
Half off, minus the drama
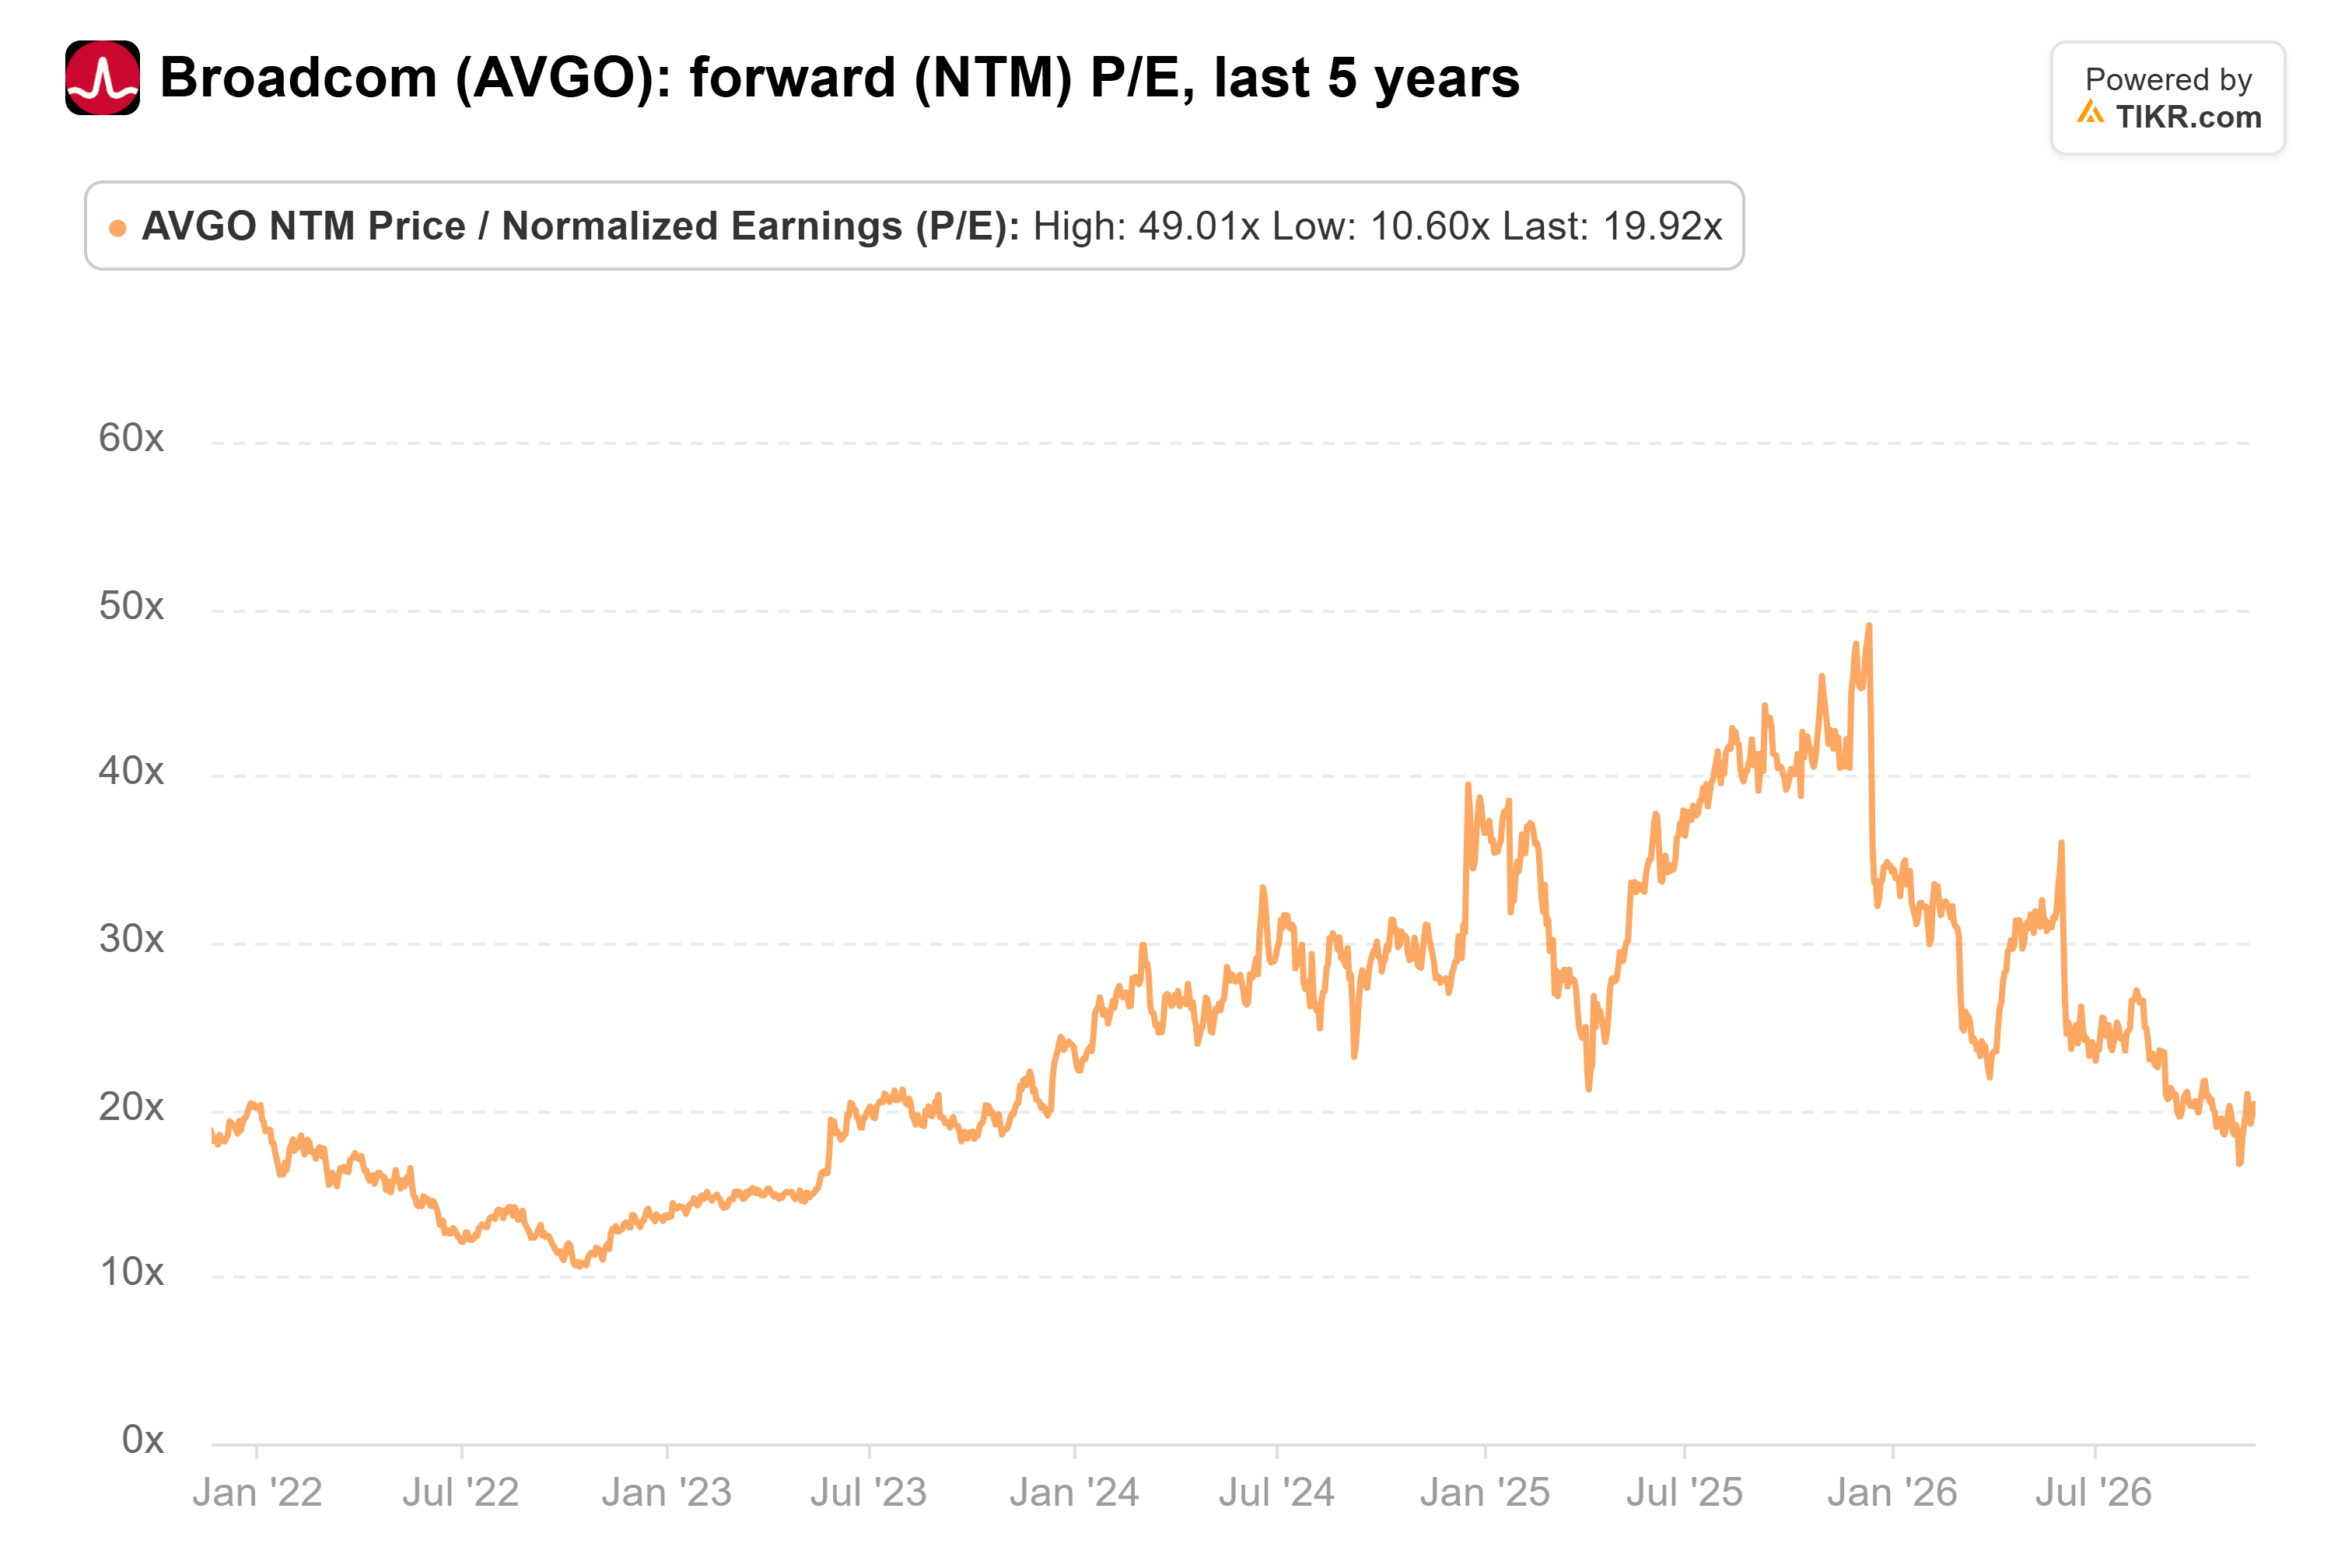
Luria’s alternatives are cheaper too. Broadcom’s forward P/E has fallen from 49x in December 2025 to 20x, below its five-year average of 24x:
Micron has locked in significantly higher prices on most of its 2027 high-bandwidth memory, per its September call. NVIDIA pays for that: it guided fourth-quarter gross margin to 71% to 72%, down from 74.8%, a drop management has tied to rising memory prices.
Luria’s picks carry some of NVIDIA’s risk, though. The Commerce rule covers advanced AI chips whoever makes them, so AMD, which has been closing in on NVIDIA, needs the same licenses there.
The bigger risk for all four is the broader spending. Amazon’s free cash flow was a $42.4 billion outflow over the twelve months to Sept. 30, even as AWS grew 39% in the third quarter.
If Amazon and its peers ease off to get that cash back, Broadcom, Micron and AMD feel it as much as NVIDIA does.
I’ll take the risk at 10x
Luria’s right: NVIDIA is one of the riskiest…and I’d say the riskiest chip stock out there. But the market is already charging for all of it, on estimates that have gone up since late October.
Frankly, I’d rather own that risk at 10x than pay Broadcom’s 20x to avoid it.
Of course, if the probe finds NVIDIA’s Asia sales were feeding China, those estimates come down, and 10x won’t look so cheap. And Amazon’s report in early February will show us whether the spending holds up for every chipmaker.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!