Key Takeaways
- Anthropic is giving away Office-style tools, but RBC analyst Rishi Jaluria says charging Microsoft’s roughly half a billion paying Office users more is the next leg of growth.
- Microsoft’s September quarter backs him up: Microsoft 365 commercial cloud revenue grew 17% while seats grew 5%.
- Every 45 million seats that add Copilot at its $30-a-month list price is worth about $16 billion a year.
- At 25x forward earnings, below its five-year average of 29x, the stock looks priced for more damage from Anthropic than Microsoft’s results show so far.
Microsoft (MSFT) shareholders have had a rough week.
Anthropic started rolling out Claude Sheets, Claude Whiteboards and Claude Data to paying Claude users at no extra charge, a direct shot at Office.
But Rishi Jaluria, a software analyst at RBC Capital Markets, thinks the market has the Office story backwards. He said this on the RiskReversal Pod:
“There was this viewpoint even six months ago that Office Copilot was completely a failure. Now look at the metrics, look at the engagement metrics … look at the fact that we’ve seen the Office line actually accelerate already.”
And what comes next? “That’s the next leg of the story is how do you drive that ARPU uplift within that, you know, call it half a billion odd users that are paying for Microsoft Office today.”
TIKR tracks 58 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
The upsell is already showing up
In the September quarter, Microsoft 365 commercial cloud revenue grew 17%, up from 14% in the June quarter (since this quarter, that line also counts GitHub’s cloud business). Commercial seats grew just 5% over the same period. Microsoft’s quarterly report credits higher revenue per user, as customers moved up to pricier plans including Copilot, E5 and E7.
And the lever is big. Microsoft last put its paid Microsoft 365 commercial seats at more than 450 million, in December 2025, and Copilot passed 30 million paid seats in the June quarter. At Copilot’s $30-a-month list price, every 45 million seats that sign up (a tenth of the base) adds about $16 billion a year before discounts.
Analysts expect revenue to climb from $332 billion in fiscal 2026 to $396 billion in fiscal 2027 and $477 billion in fiscal 2028:
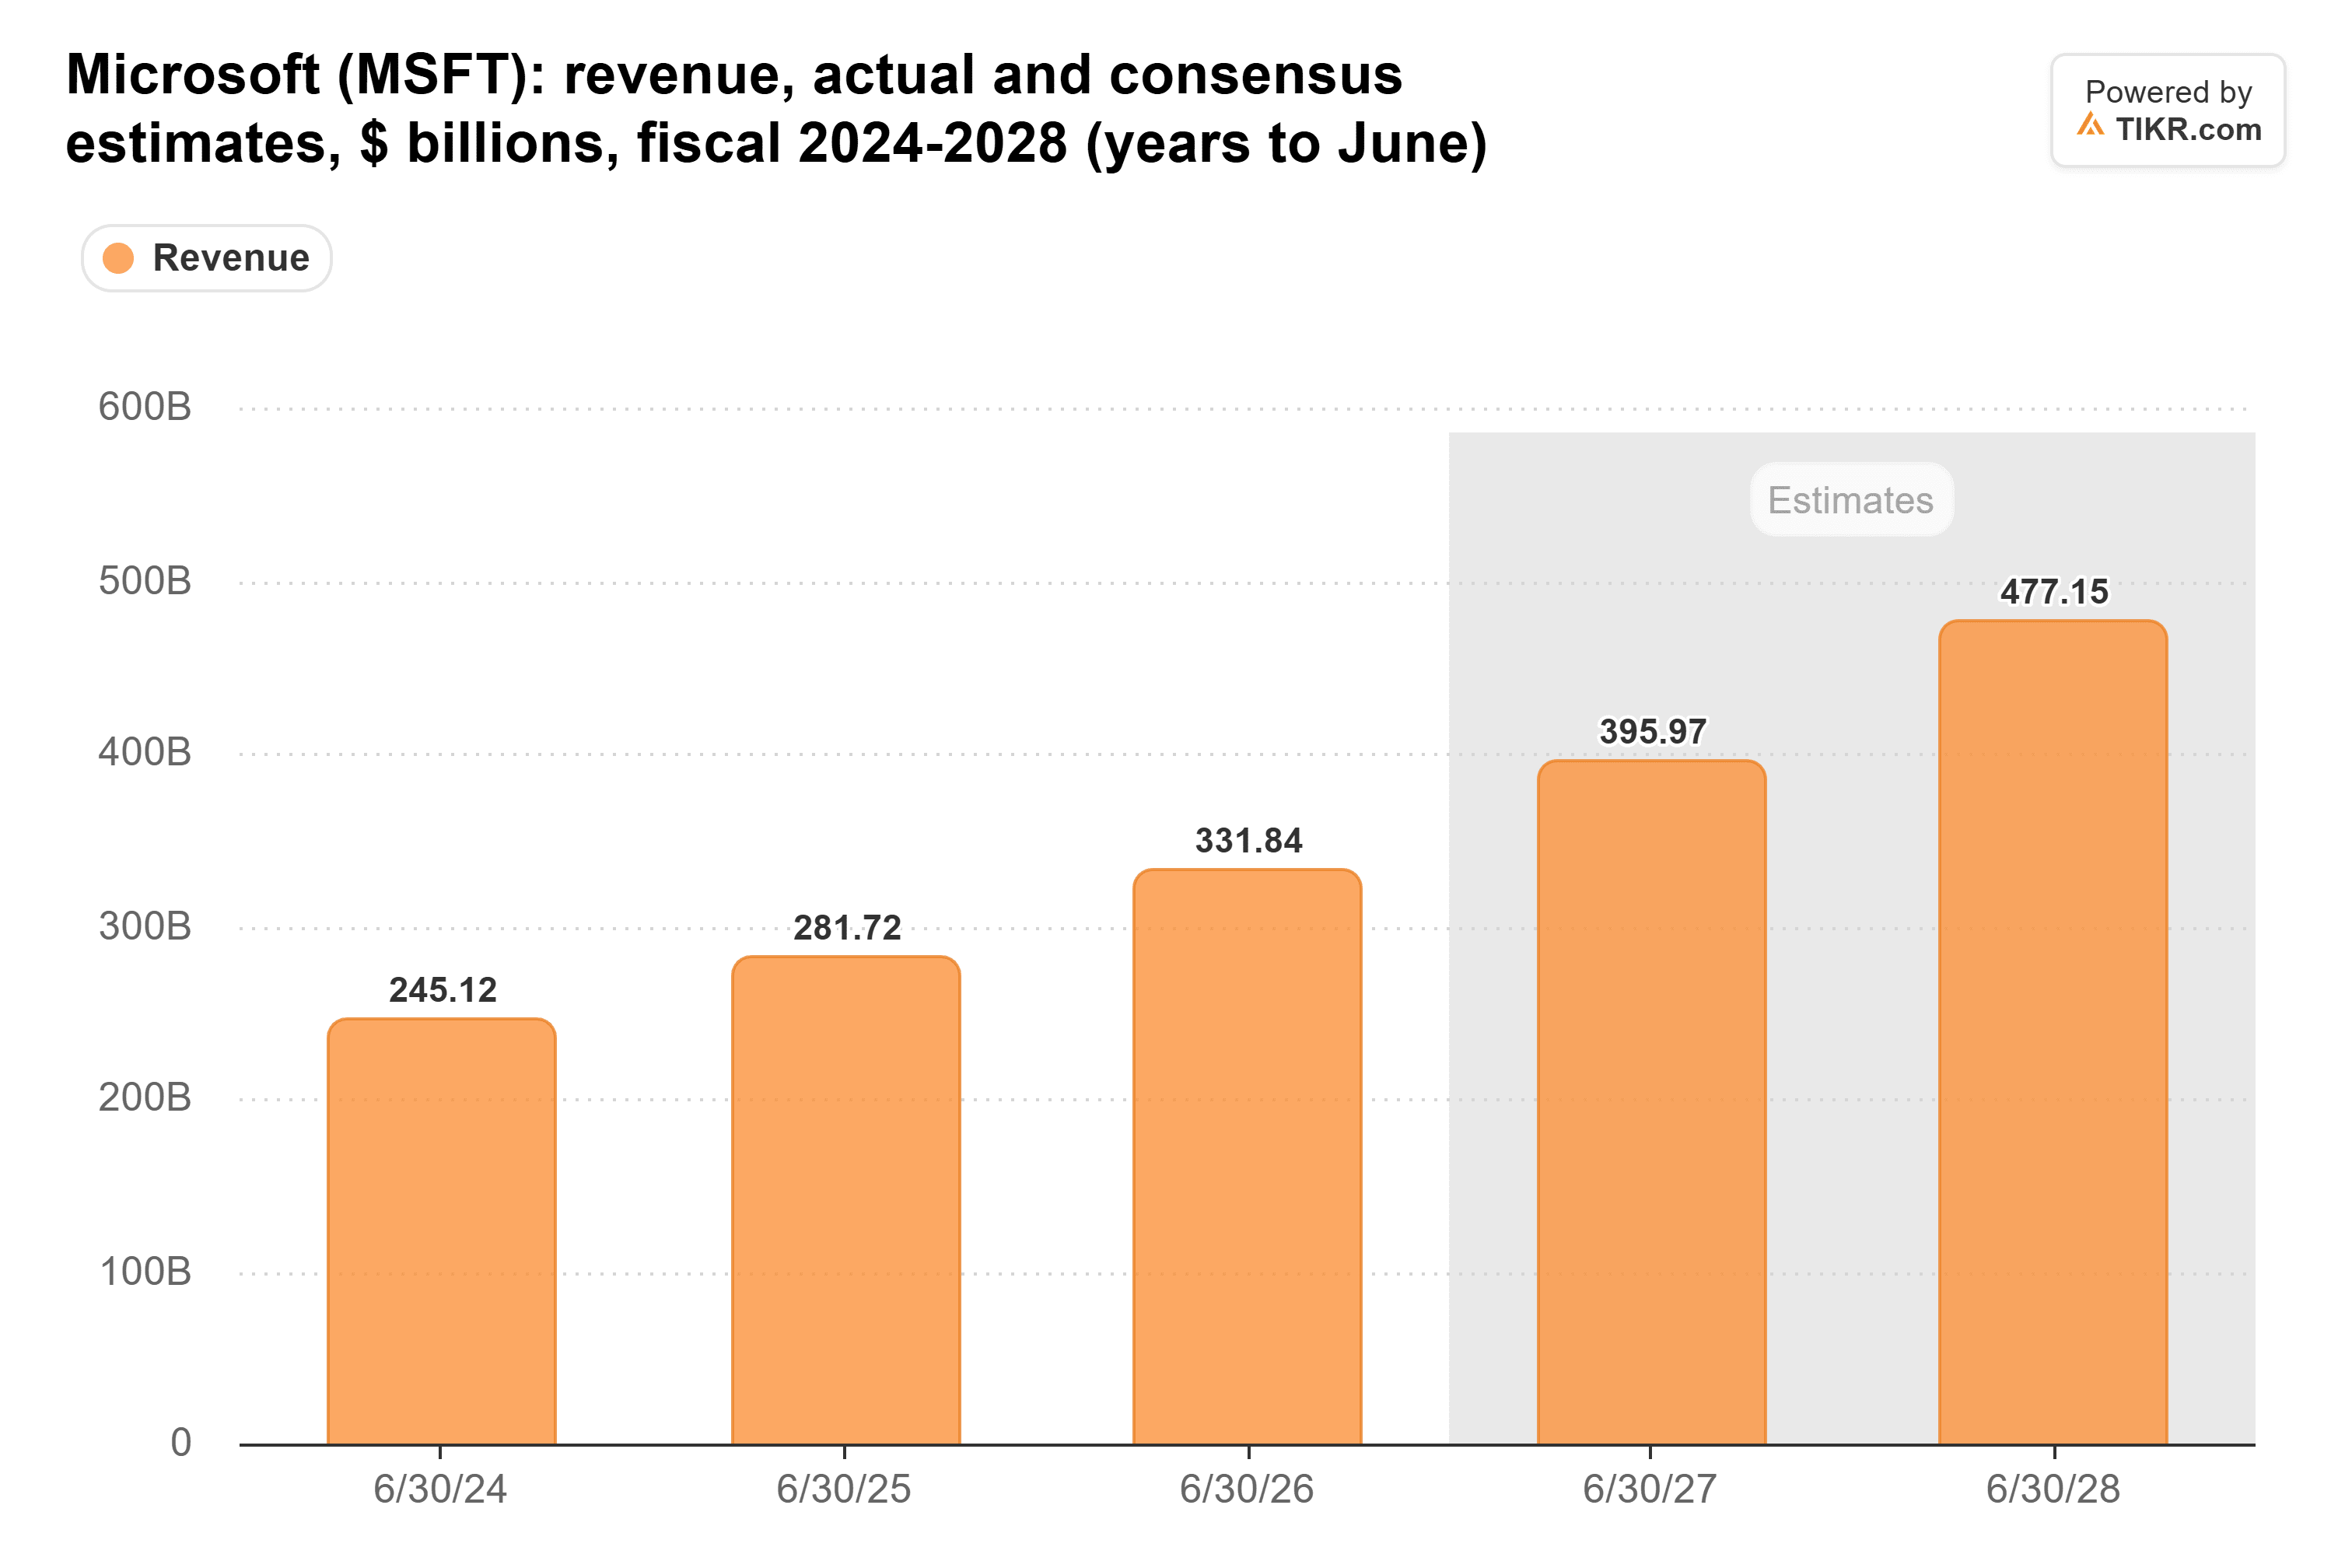
If Copilot picks up faster, those estimates should go up.
Anthropic’s freebies are a speed bump, for now
Anthropic does make price increases harder. A CFO weighing a $30 Copilot seat now has a free spreadsheet inside a Claude plan the company may already pay for.
But Anthropic product leader Nicholas Lin told Bloomberg that Claude Sheets is “fairly basic” for now, and that Microsoft’s and Google’s tools are still the ones for advanced work like financial modeling.
Plus: Microsoft has a piece of Claude’s success. Anthropic agreed in November 2025 to buy $30 billion of Azure compute, Microsoft agreed to invest up to $5 billion in Anthropic, and Microsoft booked a $3.2 billion gain on that stake in the June quarter.
Microsoft is guarding the margin
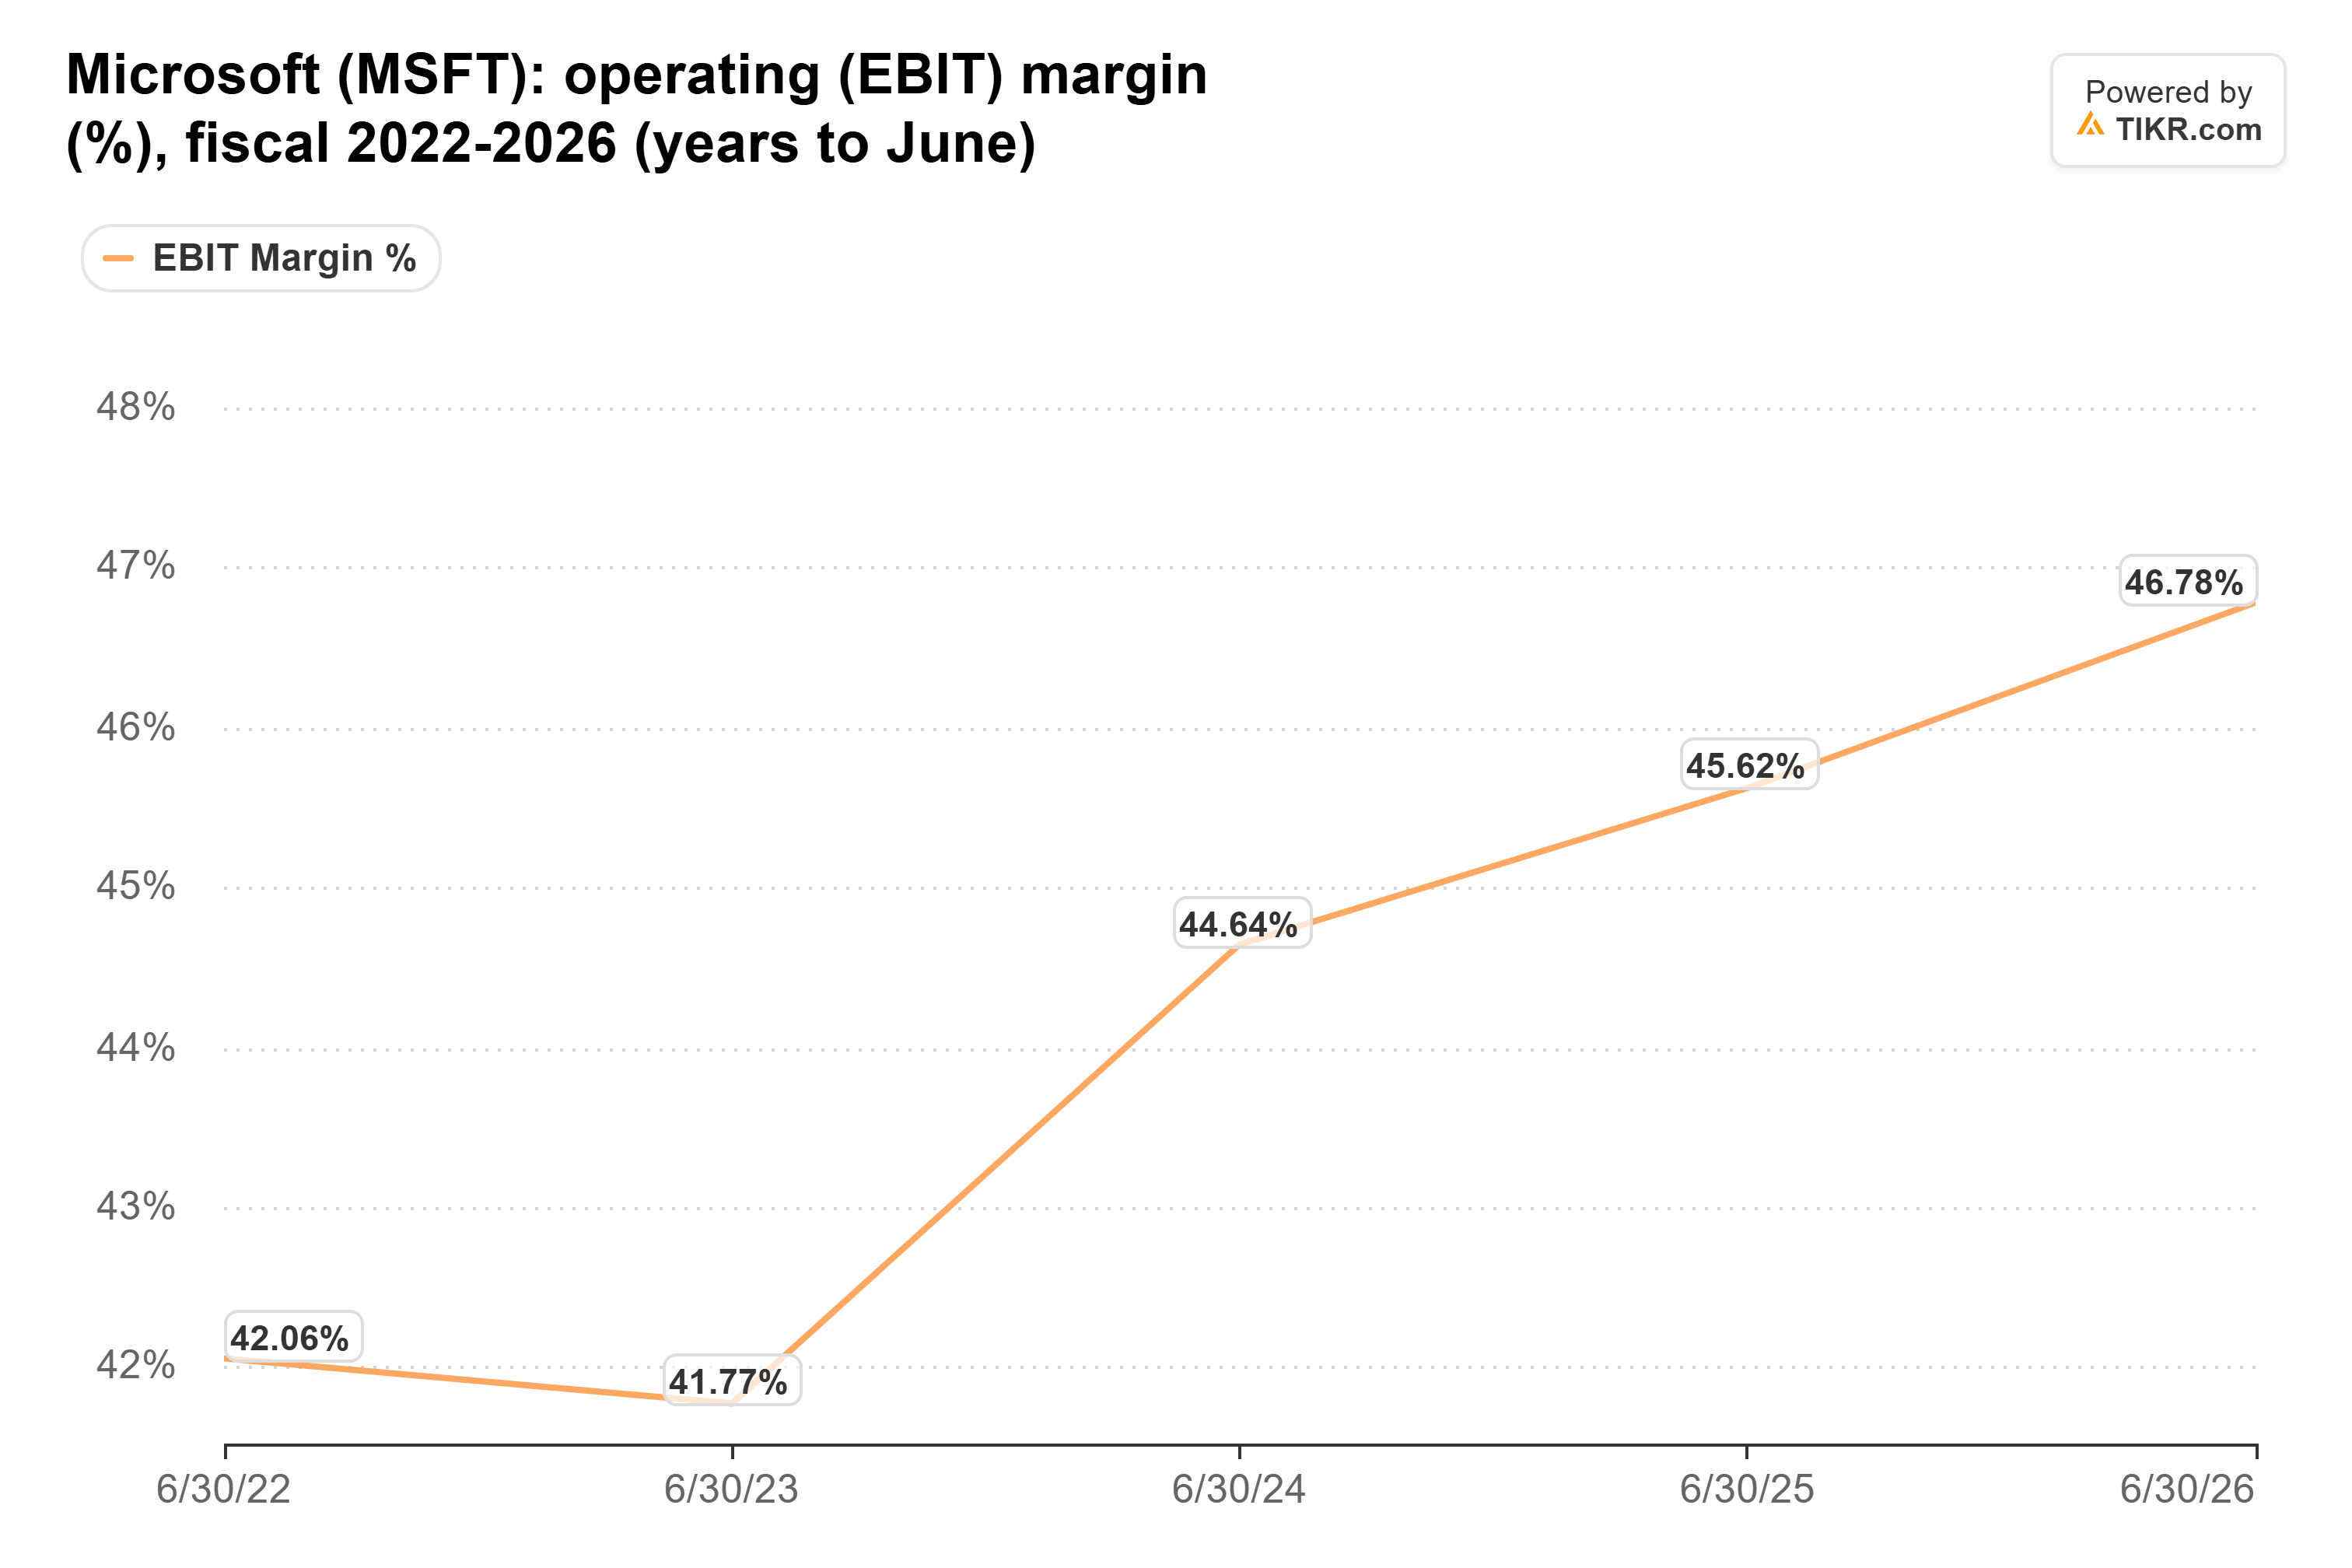
Microsoft’s operating margin climbed from 42.1% in fiscal 2022 to 46.8% in fiscal 2026:
On Oct. 26, Microsoft opened its first-ever voluntary exit offer to about 60,000 employees, roughly a quarter of its workforce.
In July, management guided fiscal 2027’s operating margin down by less than a point, even with capex rising again. With costs held down like that, more of any Copilot price increase should go straight to profit.
The discount looks too steep
Microsoft trades at 25x forward earnings, below its five-year average of 29x:

The way I see it, the market is treating Anthropic’s freebies as a bigger threat than Microsoft’s results show so far. I’m with RBC on this one.
The catch is that Microsoft didn’t update its Copilot seat count in October, so for now we’re partly relying on management’s word about engagement. The next report, likely in late January, should show Microsoft 365 commercial cloud growth at 17% or better. If it slips back toward 14%, Anthropic’s tools are starting to hurt.
So what is Microsoft stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Microsoft could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!