Key Takeaways
- Mastercard stock rose 10% in a week to a record. The run began with 14% revenue growth and ended the day after a Senate author of the swipe-fee bill, which also hangs over Visa, lost his seat.
- The quarter earned the run, but CFO Ling Hai said part of the beat came out of the fourth quarter.
- Analysts expect normalized EPS to grow about 16% a year through 2028, and the stock trades near its usual forward P/E.
- Hai’s first 2027 outlook, due in late January, is the next test.
Mastercard (MA) stock is up 10% in the past week to a record close of $672.68, a stretch in which the Nasdaq 100 fell 4.6%. The Oct. 29 earnings beat started the run with a 4.2% gain. The stock then added 3.9% on Nov. 4, the day after an election result that matters just as much to Visa (V).
The quarter cleared the bar
On Oct. 29, net revenue rose 14% to $9.8 billion, ahead of the $9.66 billion analysts expected. Adjusted EPS rose 21% to $5.31, against a $5.17 consensus. Value-added services revenue grew 19%.
The adjusted operating margin came in at 60.5%, clearing the 60% bar set going in, even with rebates and incentives up 18%.
Both Senate authors of the swipe-fee bill are leaving
Kansas Sen. Roger Marshall lost his seat to Democrat Adam Hamilton on Nov. 3. Marshall co-wrote the Credit Card Competition Act, which would make large banks put a network other than Visa or Mastercard on their credit cards. With Illinois Sen. Dick Durbin retiring, neither author returns in January.
Marshall’s loss lowers the risk without ending it: President Trump backed the bill again on Oct. 19, at a rally for Marshall outside Wichita.
Analysts expect Visa’s normalized EPS to grow about 14% a year to fiscal 2028, on the same fees a routing law would squeeze.
The CFO already told us Q4 gives some back
On the third-quarter call, JPMorgan’s Tien-Tsin Huang asked whether anything was one-time. New CFO Ling Hai said services projects and deal signings had moved into the third quarter from the fourth, then added: “You will see a similar offset in Q4.”
Rebates will also take a bigger share of gross assessments than in the third quarter, he said, and pricing gains will start to lap. The Street’s fourth-quarter normalized EPS estimate of about $5.18 implies growth of roughly 9%, well below the 21% adjusted EPS growth just reported.
TIKR tracks 40 analysts on Mastercard. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Mastercard, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Mastercard’s Analyst Ratings
Still a buy at a record
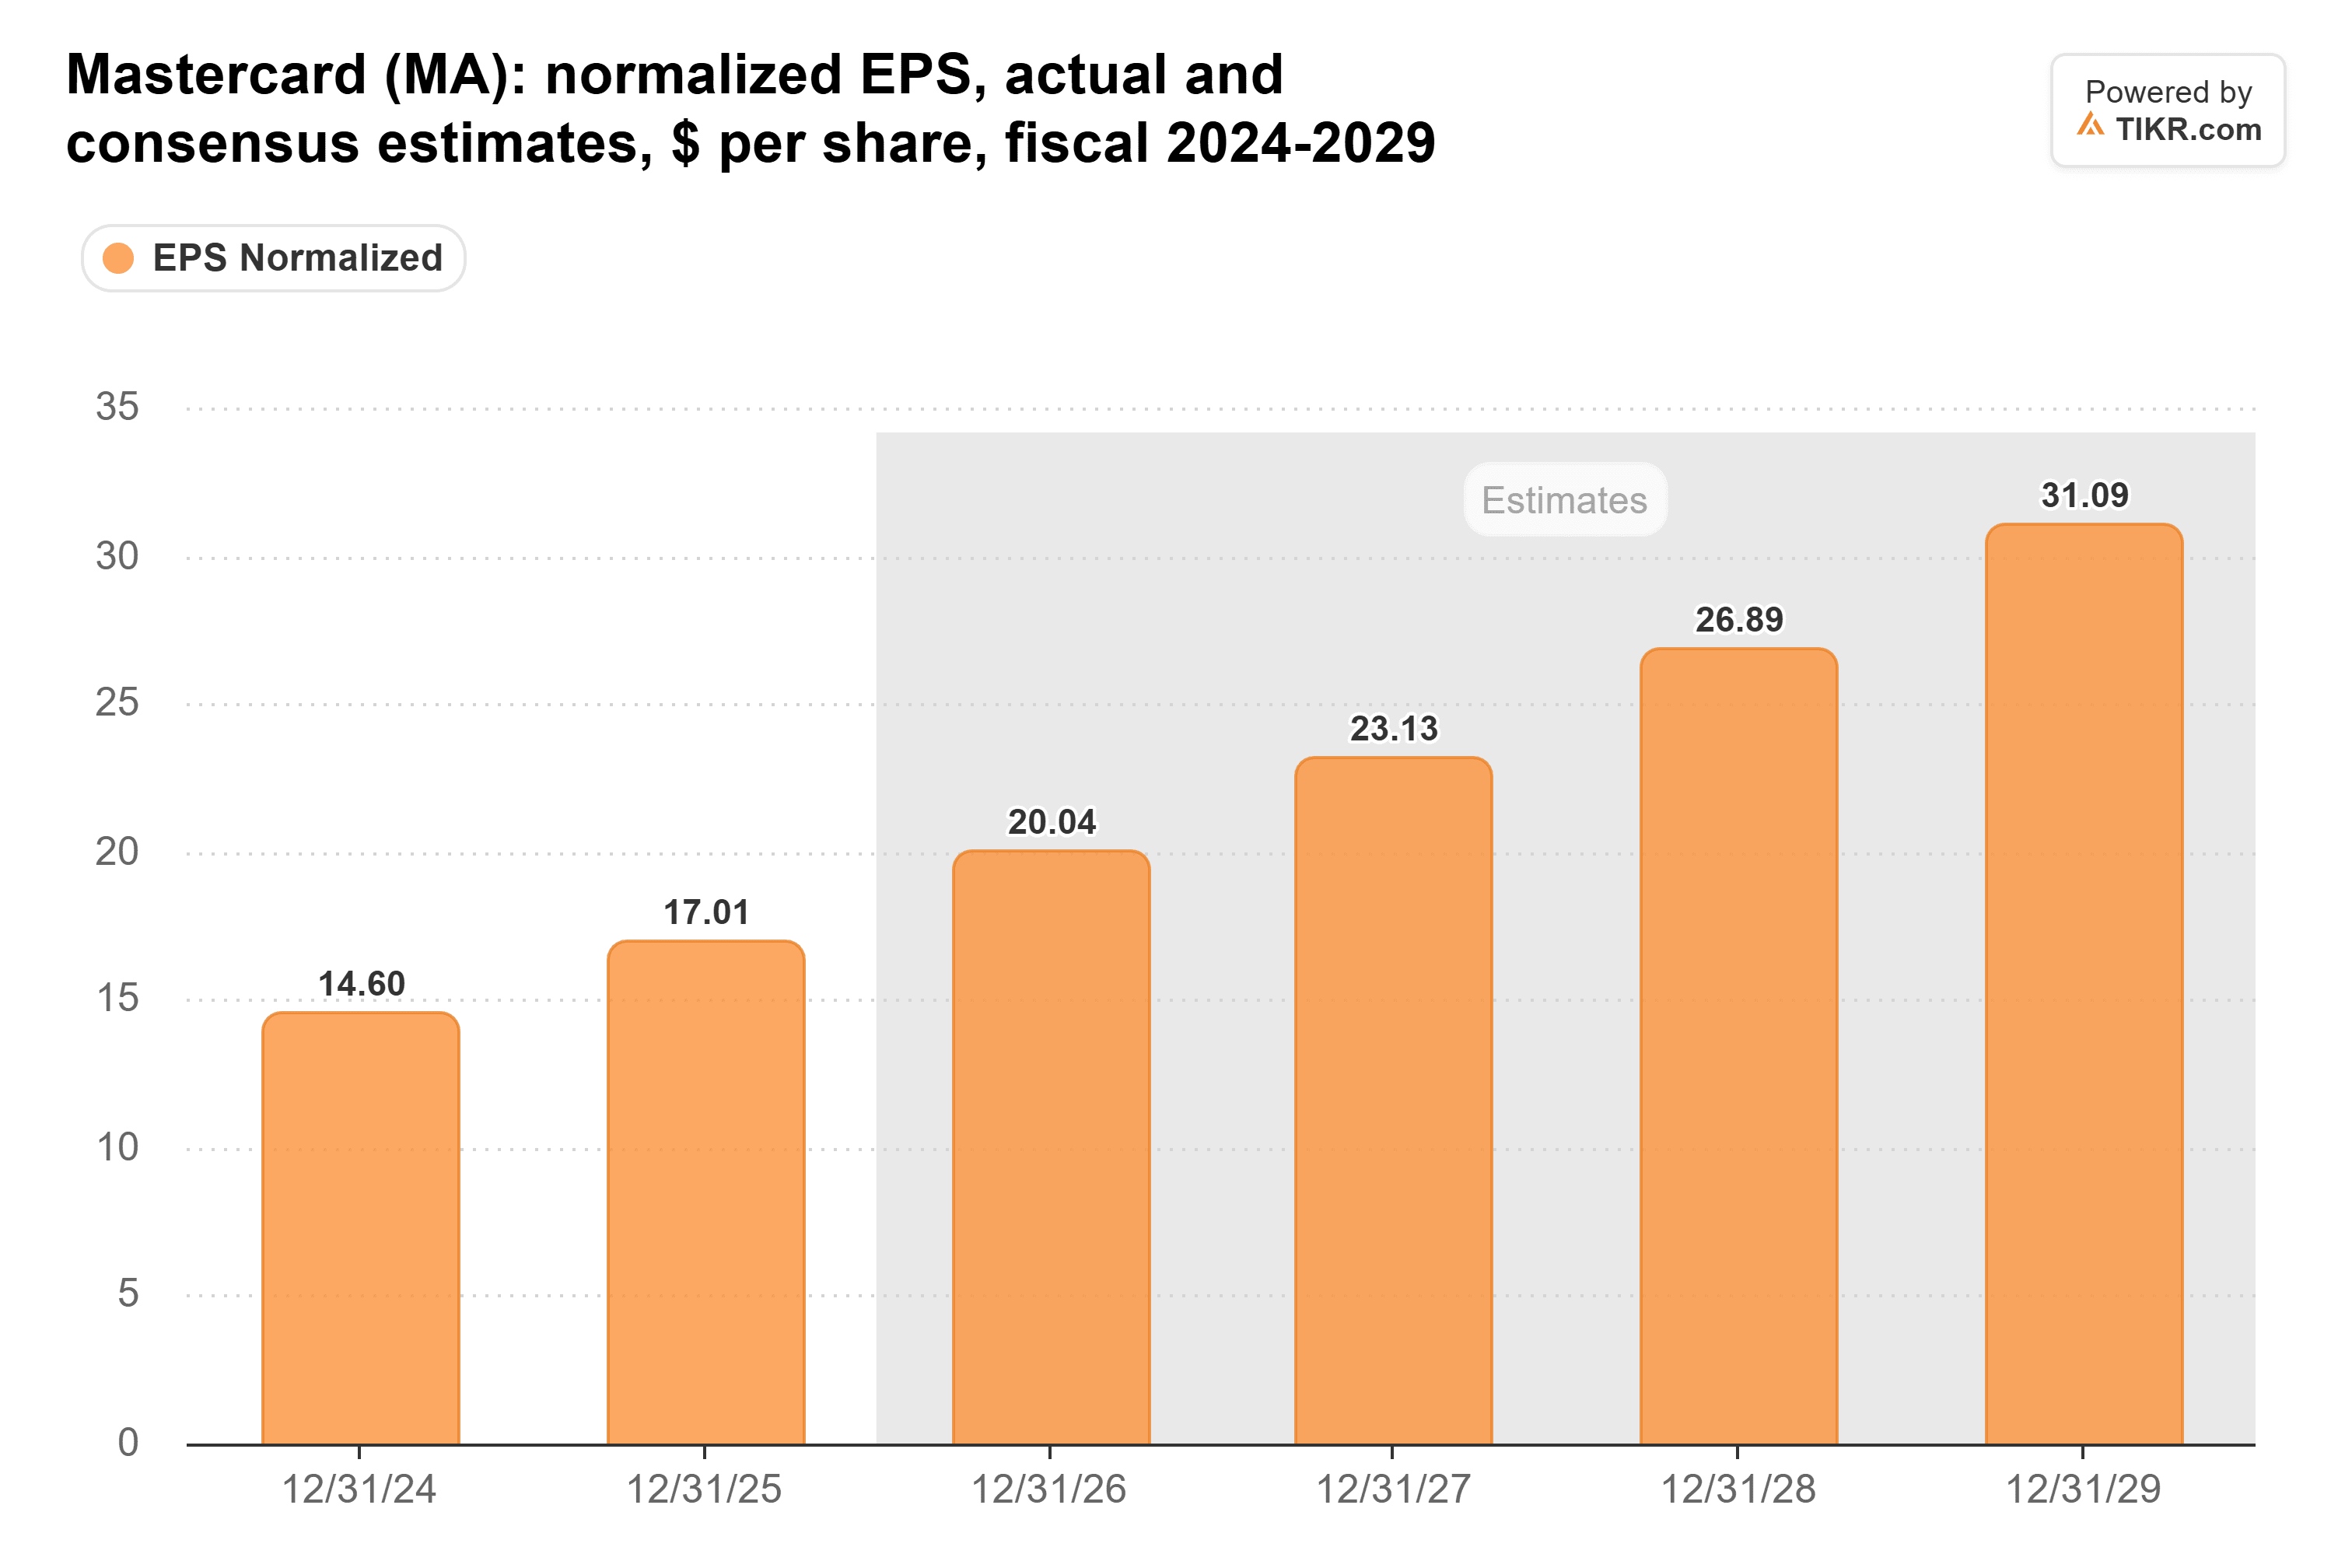
Mastercard’s normalized EPS is expected to climb from $17.01 in 2025 to $26.89 in 2028, about 16% a year:
The forward P/E has climbed from 23x in June to about 30x, against a five-year average of 31x:
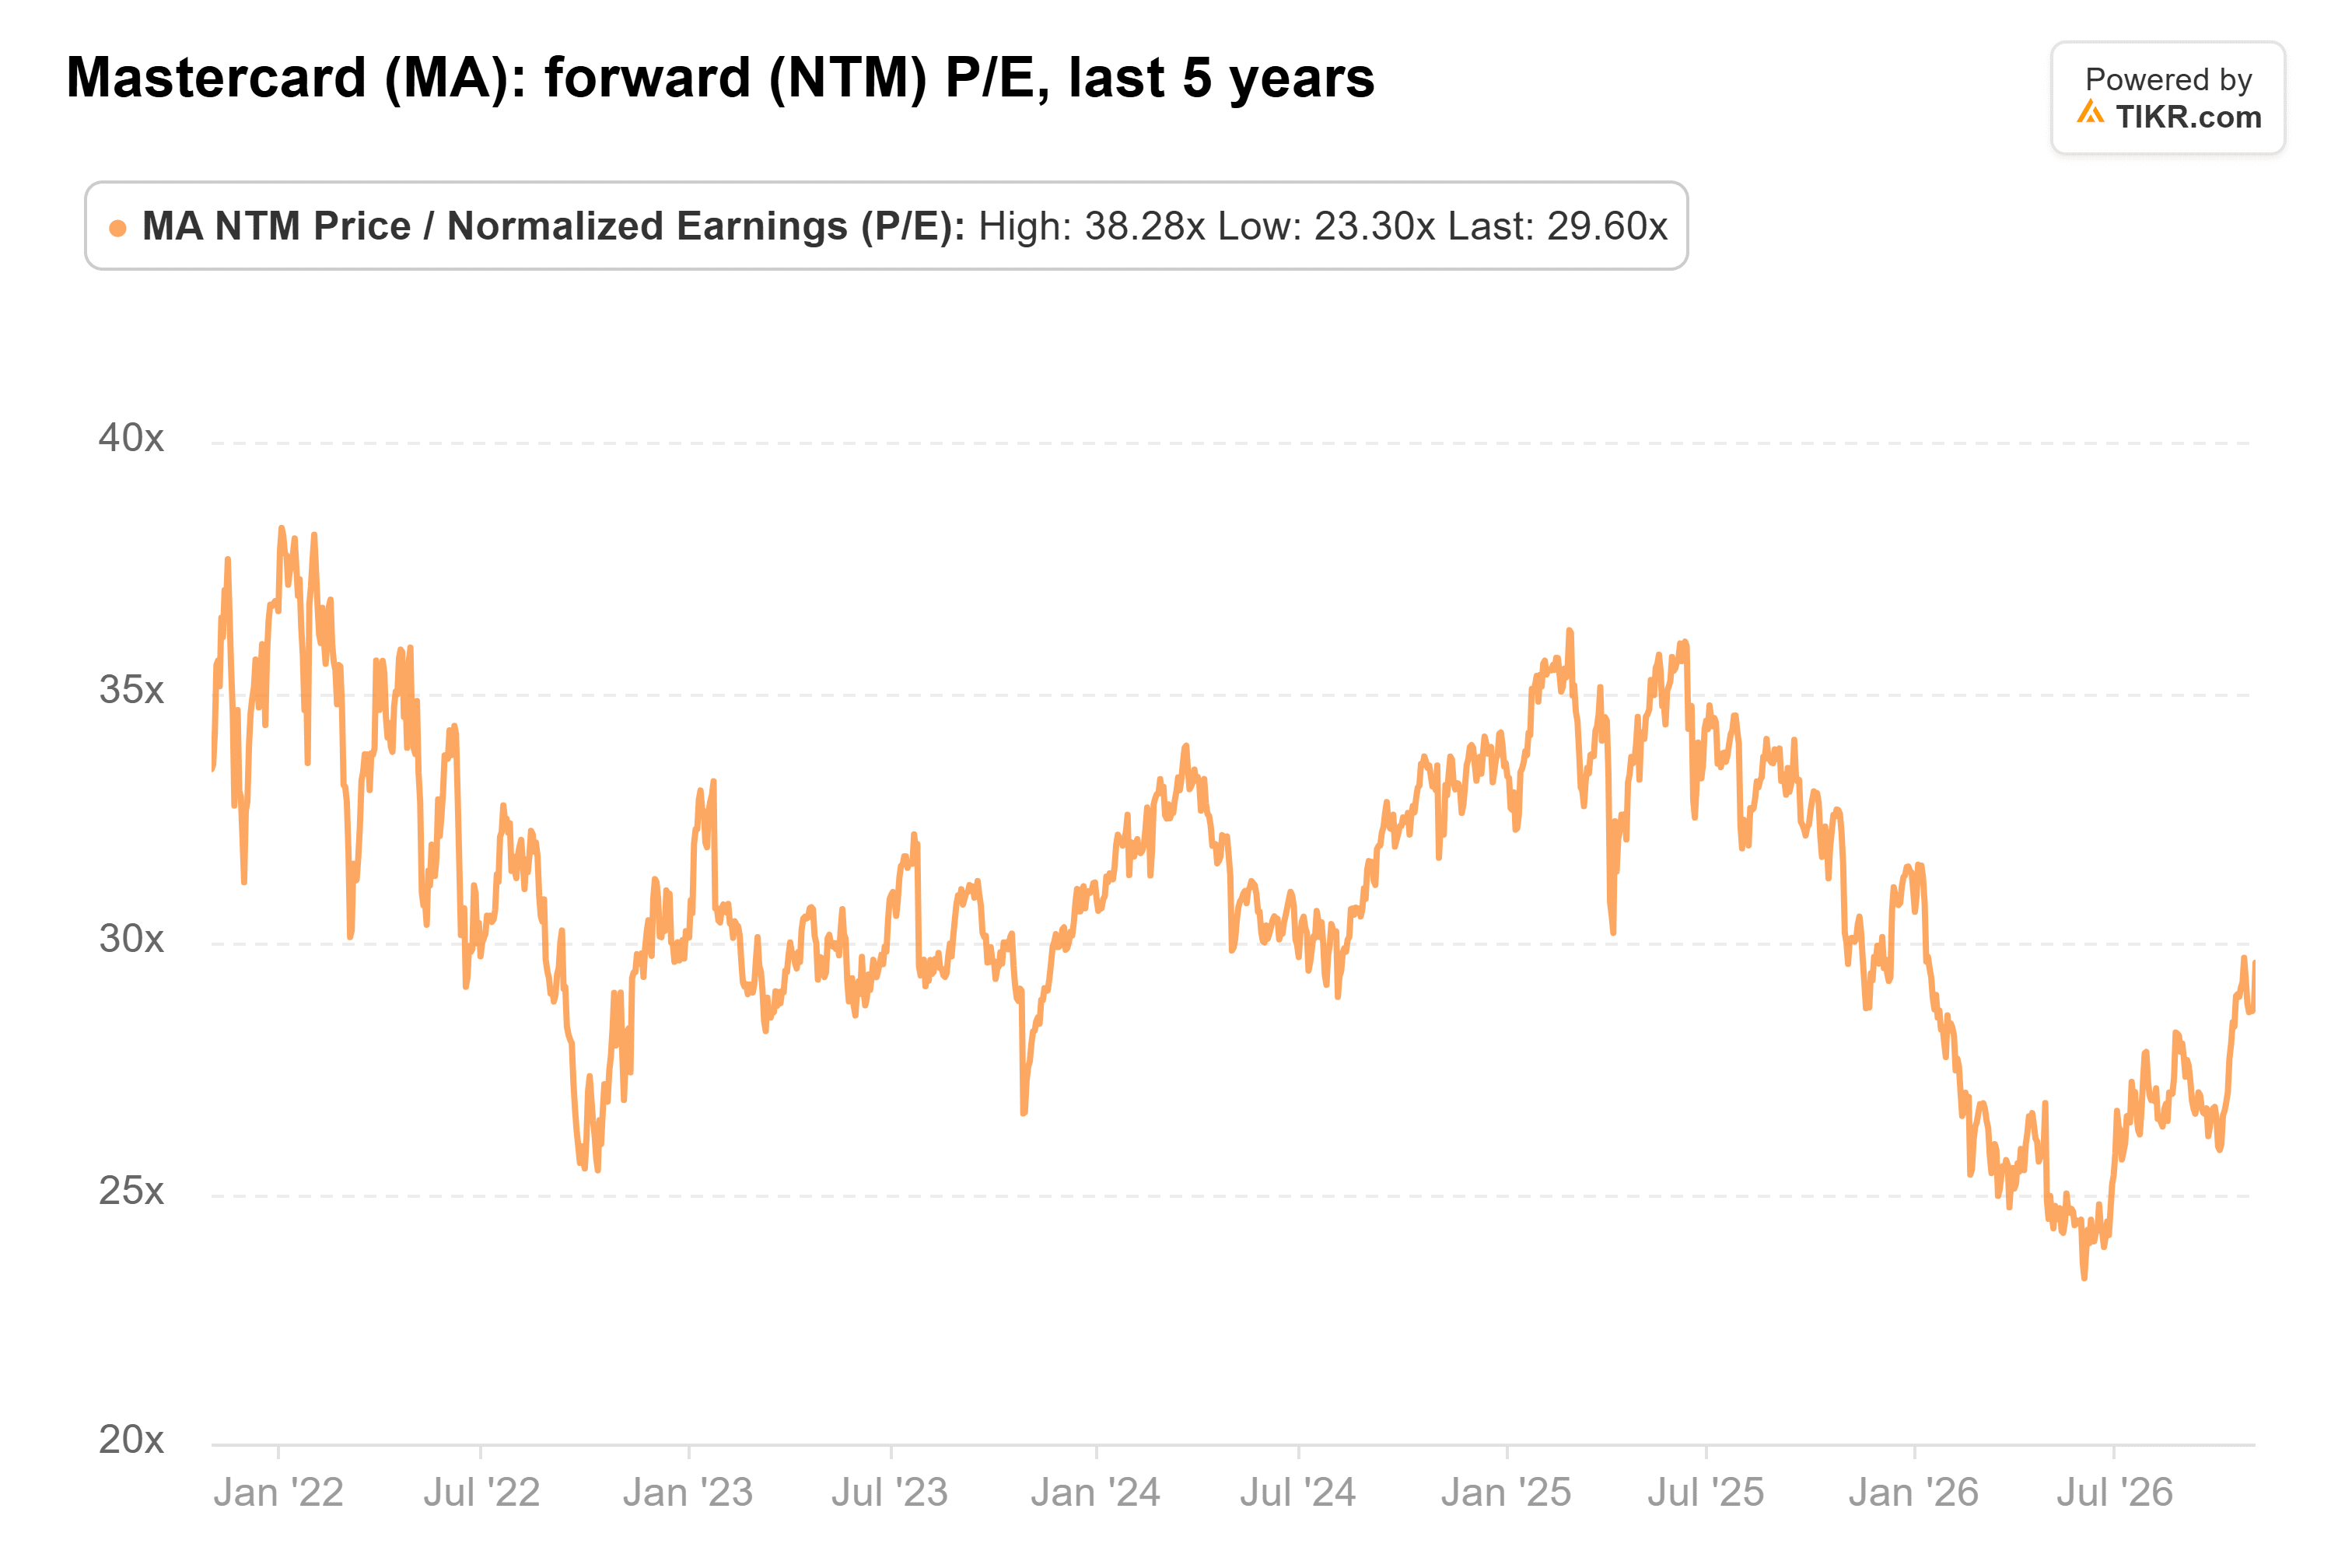
That’s a usual multiple for mid-teens growth, and the Street’s average target sits only about 5% above the Nov. 4 close.
That makes Mastercard a long-run buy, but not one to chase into January. The fourth-quarter report in late January brings Hai’s first 2027 outlook. Revenue that holds up despite the pulled-forward deals would show the record rests on the business. A pullback in consumer spending would cut those estimates fast.
So what is Mastercard stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Mastercard could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!