Key Takeaways
- Hims & Hers stock has lost 53% in a year. It fell again after a third-quarter report that cut its 2026 profit outlook and showed fewer subscribers than in the second quarter.
- Canaccord Genuity kept its Buy rating and $40 target on Nov. 10, 109% above the stock price.
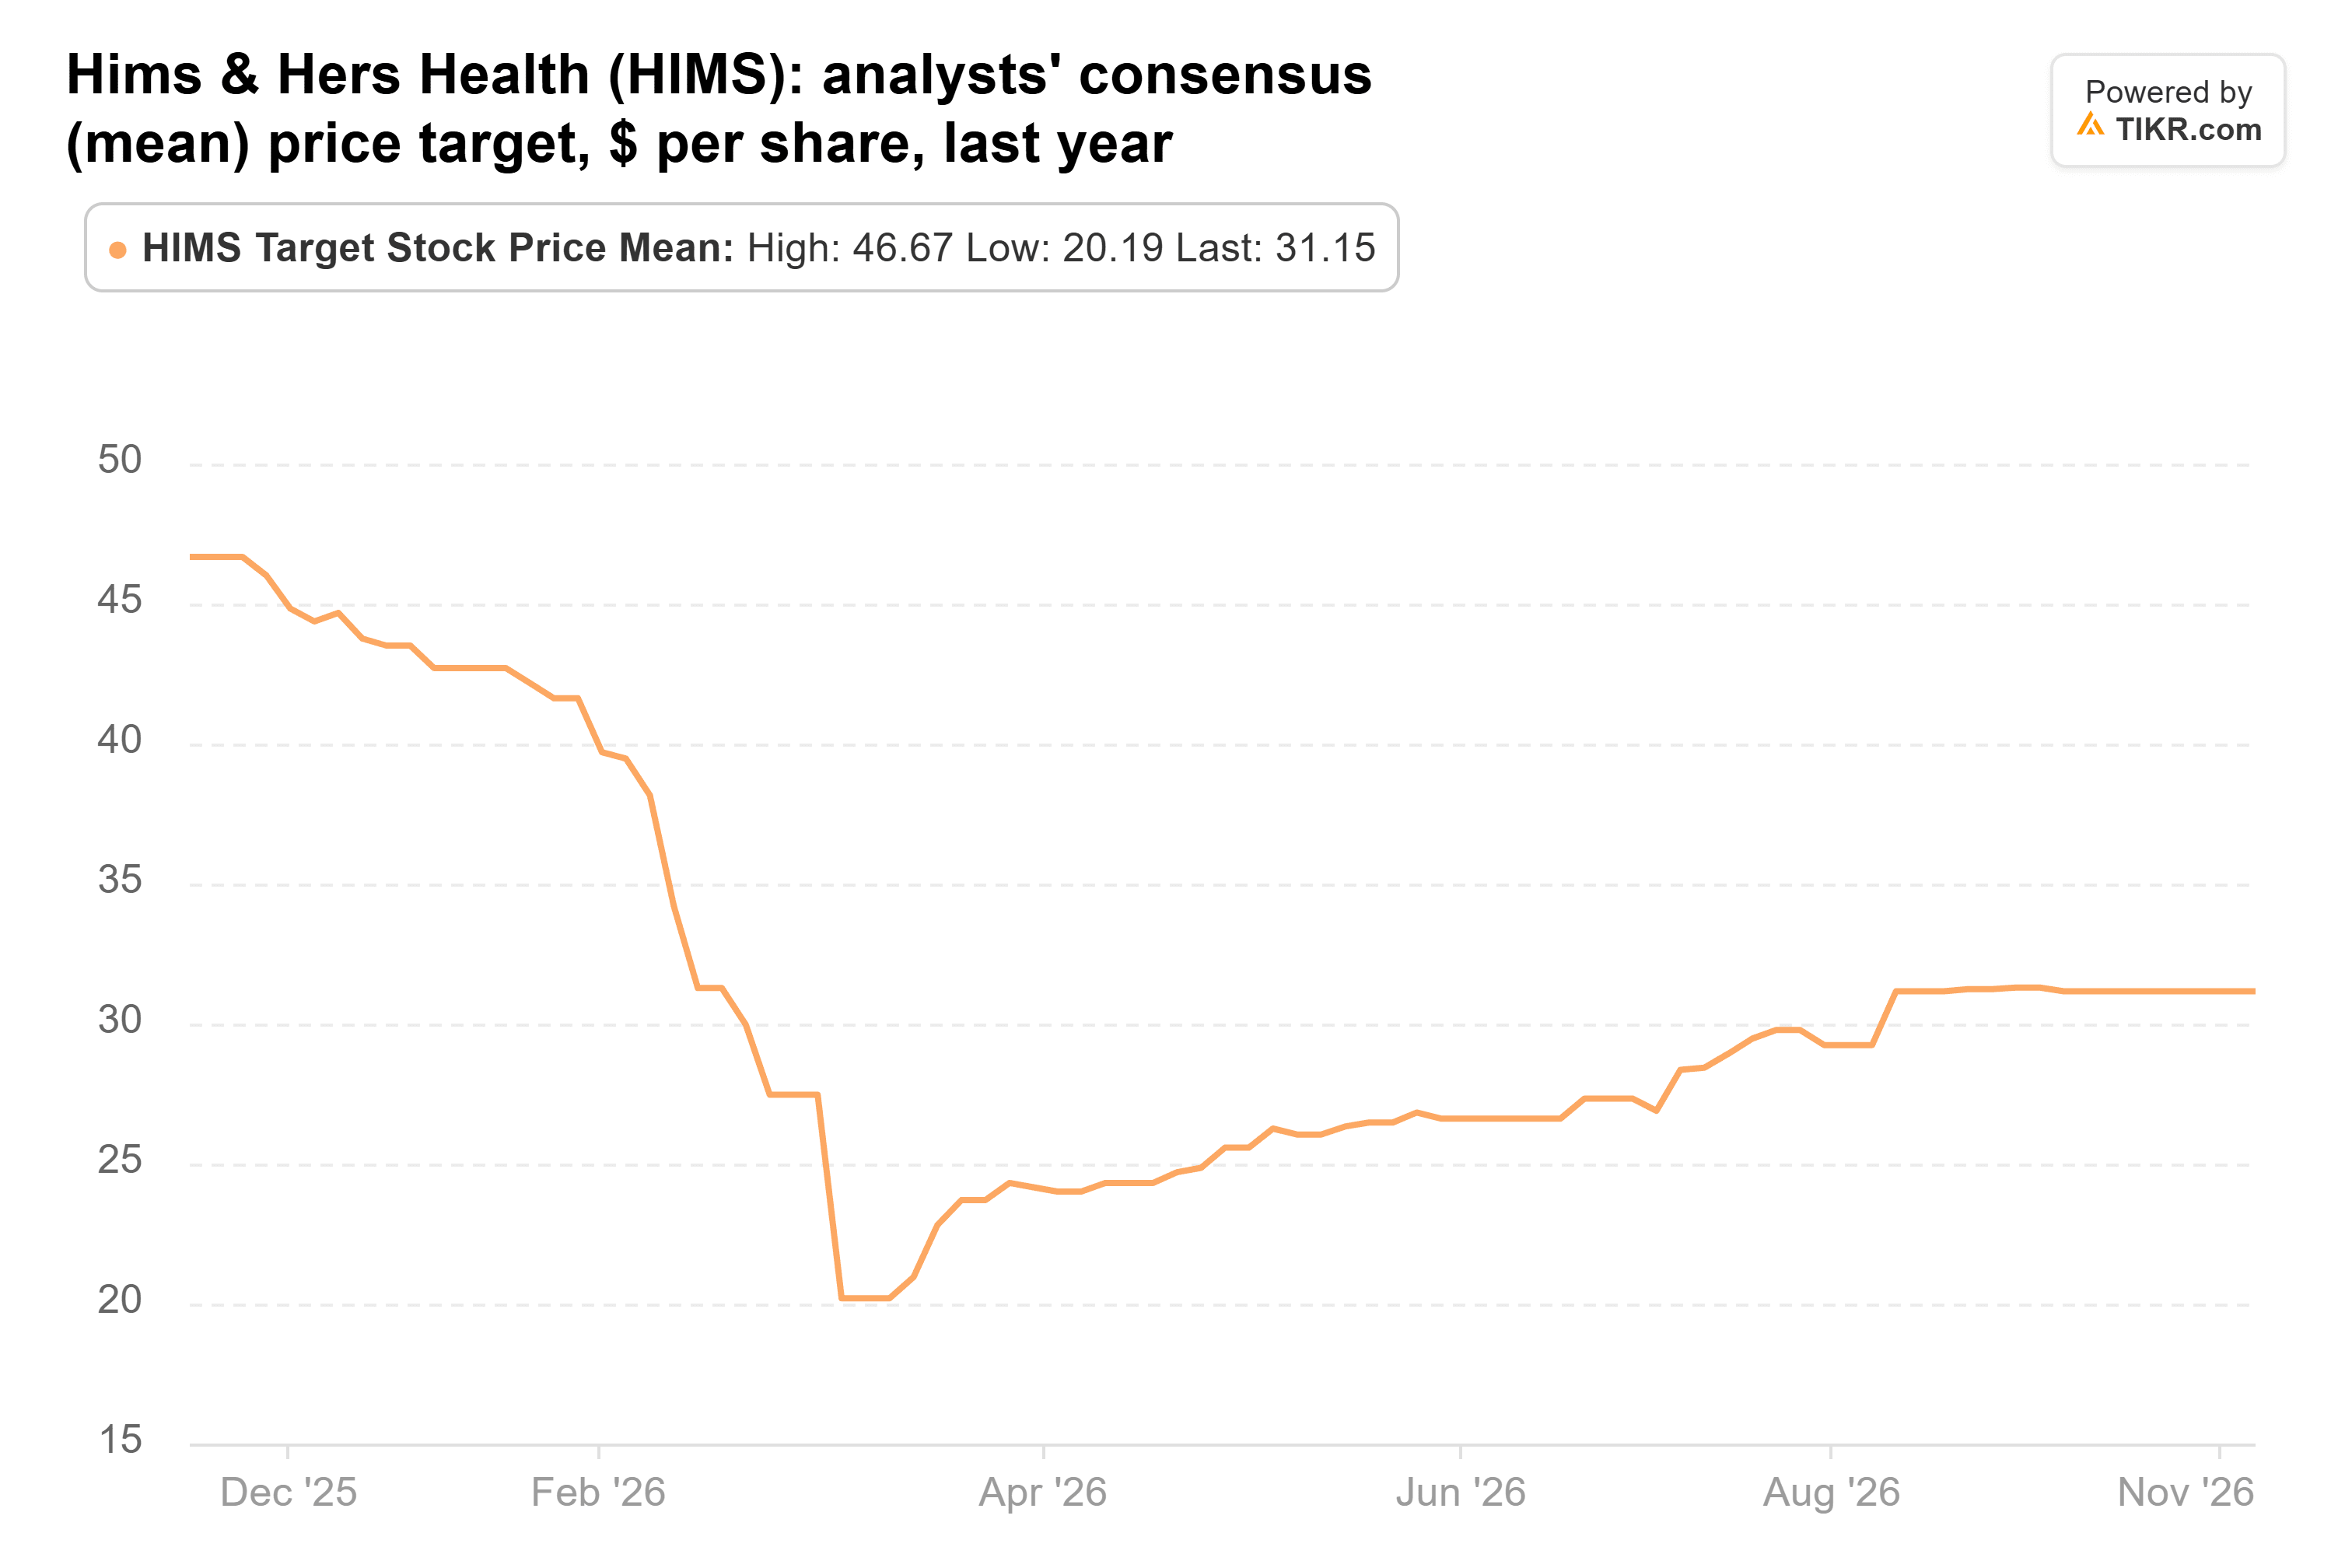
- The Street’s consensus target has fallen to $31 from $47 a year ago, and 2027 earnings estimates are still coming down.
- Revenue is still expected to grow. But earnings estimates are falling and Hims can pay an acquisition bill in stock, so its 2027 guidance is the signal to wait for before betting on a double.
Hims & Hers Health (HIMS) has lost 53% in a year, and it fell another 16.6% on Tuesday, Nov. 10, after its third-quarter report. Canaccord Genuity’s Maria Ripps still rates it a Buy, with a $40 target 109% above the $19.13 close.
Branded drugs brought customers back at a cost
Hims’ trouble began in February, when the FDA moved to restrict compounded GLP-1 drugs and named Hims. In March, Hims shifted its US weight-loss business toward Novo Nordisk’s branded Wegovy. That brought customers back, but gross margin fell to 57% in the third quarter from 74% a year earlier. Hims has also cut its 2026 adjusted EBITDA guidance three times, from $300 million to $375 million in February to $257 million to $277 million on Nov. 9.
That report showed subscribers down about 100,000 from the second quarter, to nearly 2.8 million, as Hims held back on marketing. Its fourth-quarter revenue guide, $875 million to $895 million, fell about 7% short of what analysts expected. CEO Andrew Dudum said on the call that the pullback “trades near-term subscriber growth for a stronger position in the years that follow.”
TIKR tracks 15 analysts on Hims & Hers. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Hims & Hers, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Hims & Hers’ Analyst Ratings
Canaccord is sticking with $40
Ripps raised her target to $40 from $32 on July 1, pointing to stronger branded weight-loss sales and Hims’ opportunity in peptides. She kept it there after the Nov. 9 report. Her $40 sits 28% above the Street’s $31 average. Since July, Hims has agreed with Eli Lilly to offer Zepbound and Foundayo on its platform and set its Peptides+ launch for later in November. International revenue also more than quadrupled from a year earlier to $233.3 million in the third quarter, helped by Eucalyptus, the Australian platform Hims bought in June.
Does $40 add up?
The consensus target has gone the other way, from about $47 a year ago to $31:
Even Needham, which also rates Hims a Buy, cut its target to $32 from $42.
Analysts still see revenue rising to $3.97 billion in 2027 from $3.14 billion this year:
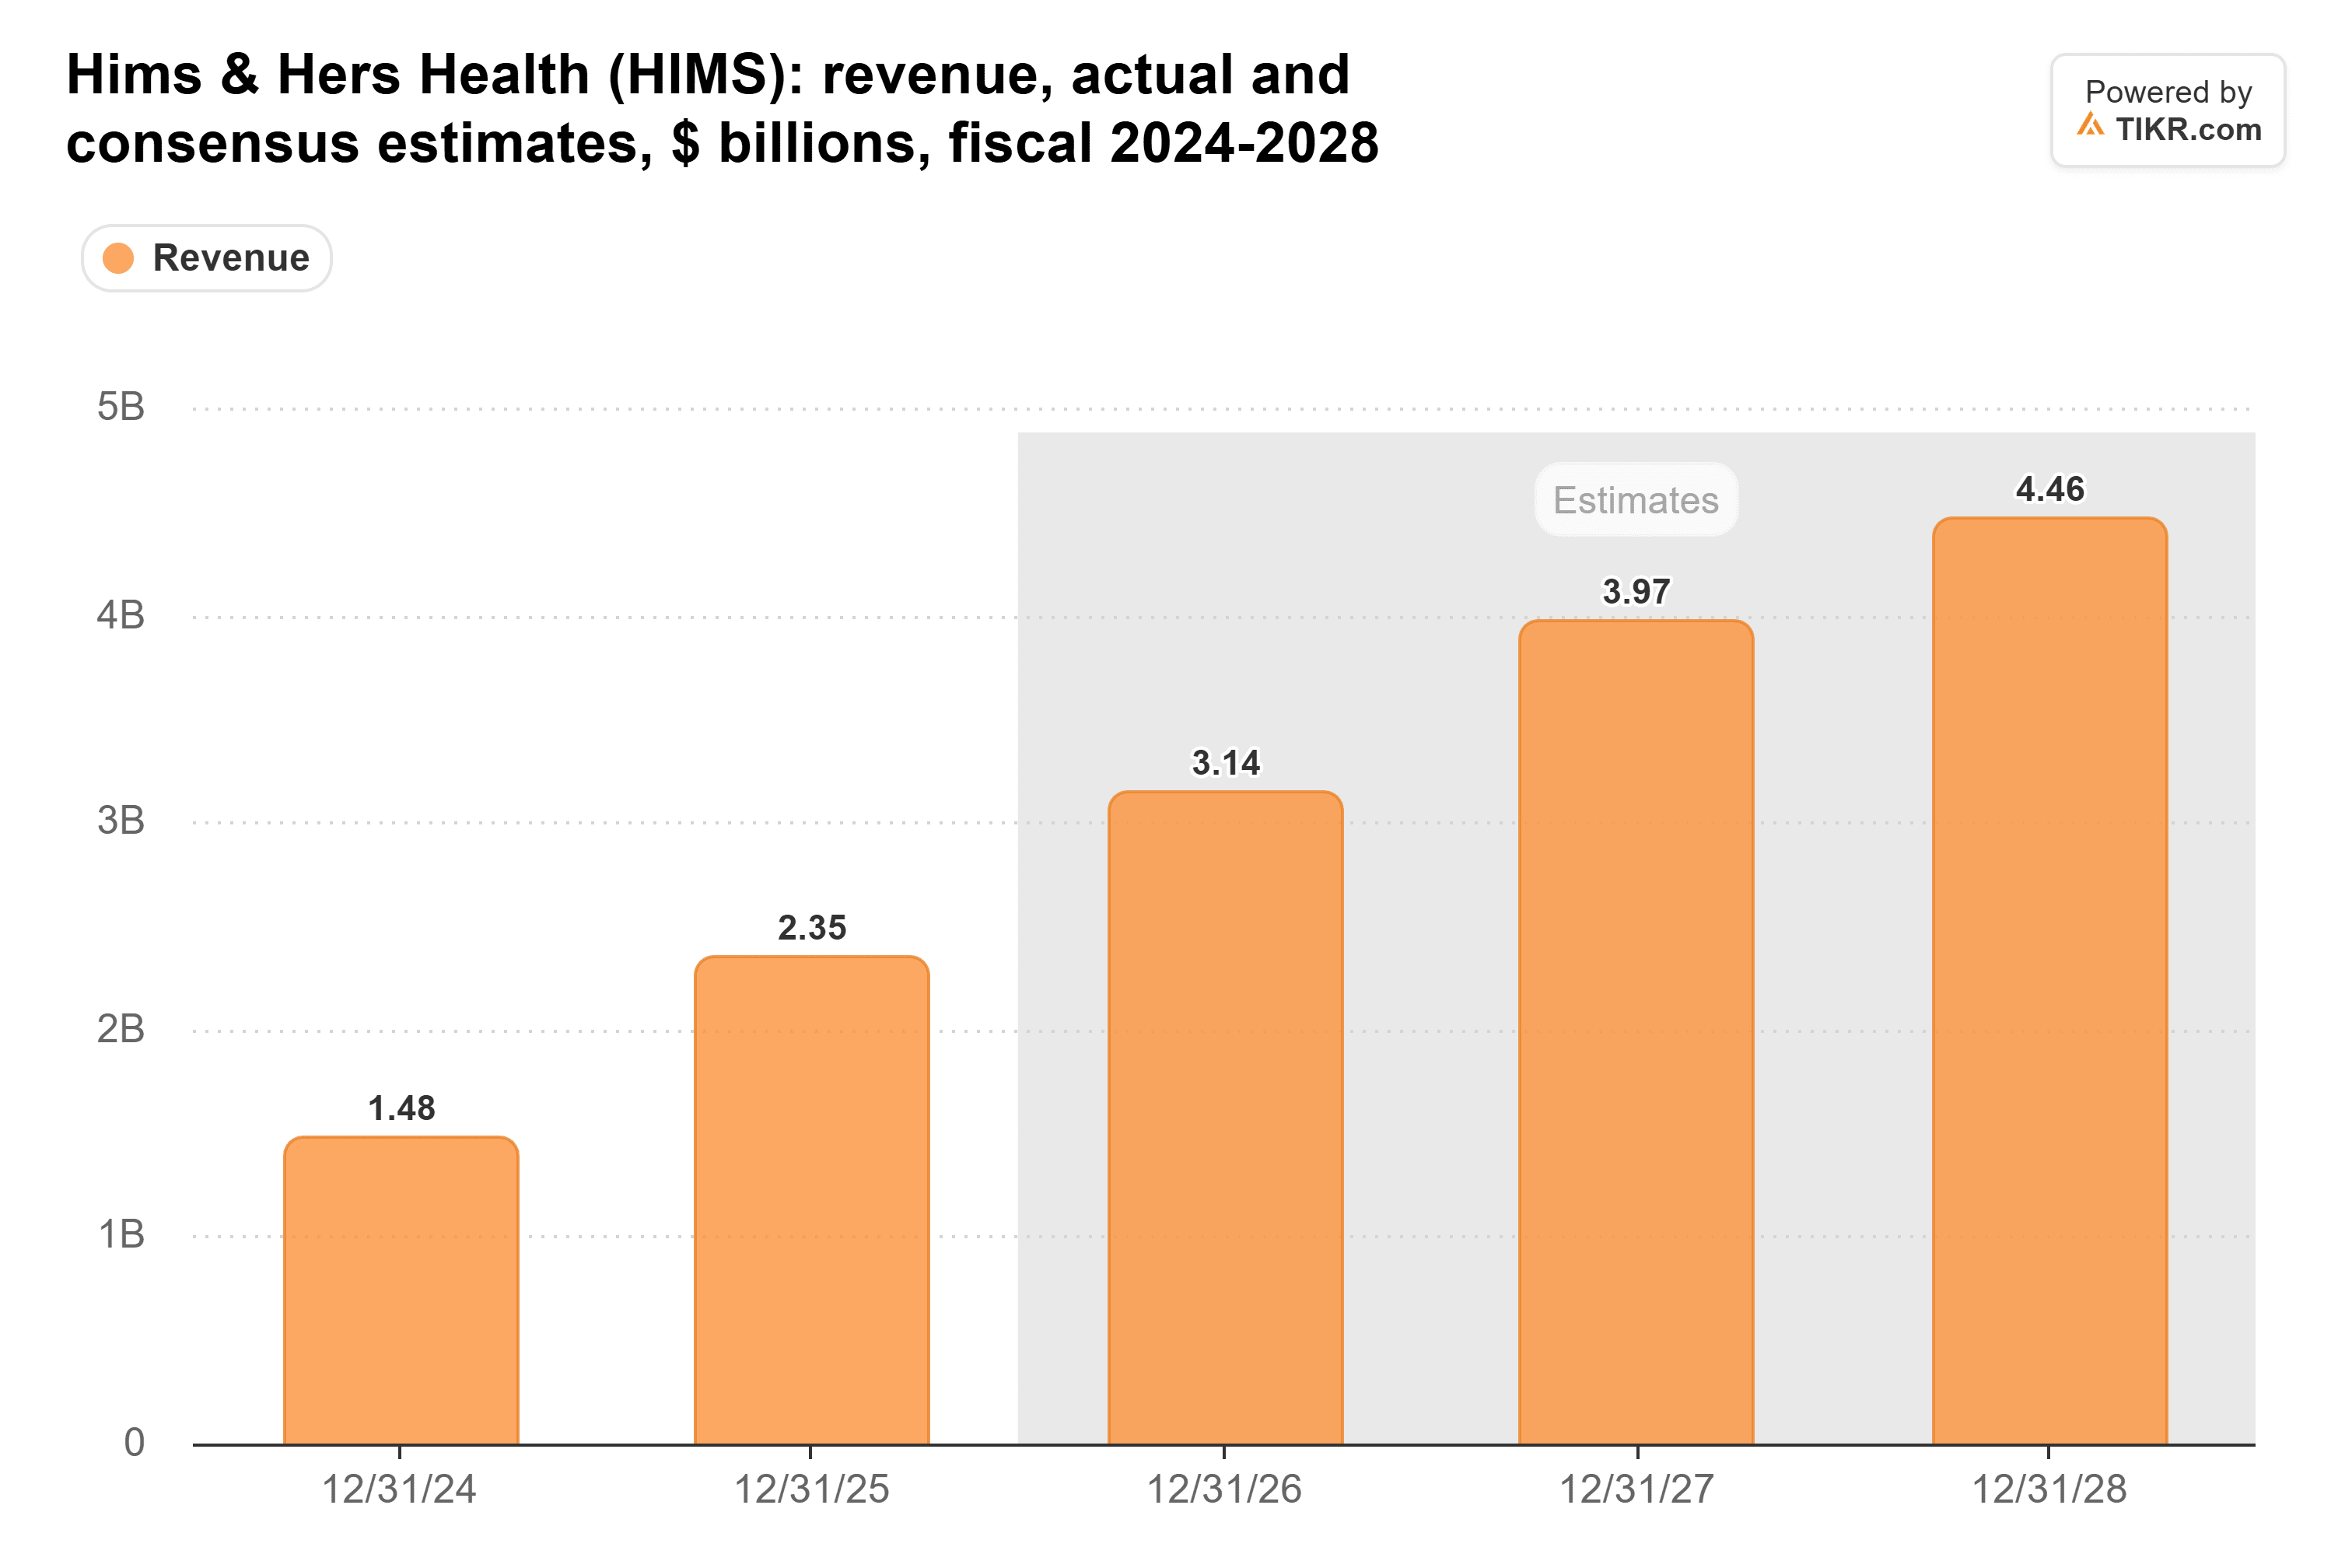
Earnings estimates are falling: Yahoo Finance’s consensus for 2027 earnings per share is $0.39, down from $0.61 three months ago.
So the top line isn’t the problem. For $40 to hold, Hims needs profit estimates to stop falling while revenue keeps growing.
Watch the share count
At Sept. 30, Hims owed $478.6 million of deferred acquisition payments due within a year, mostly for Eucalyptus. It had just over $710 million of cash and investments, and $1.37 billion of convertible notes. Its third-quarter filing says it can choose to pay most of what it owes for Eucalyptus in stock, which at the current price would spread earnings over more shares.
Canaccord’s $40 can work if revenue grows as analysts expect. But Hims also needs estimates to turn, and it has to pay for Eucalyptus without issuing much new stock. The fourth-quarter report and 2027 guidance, expected in early 2027, should show whether subscribers are growing again. That is the signal to wait for before betting on a double.
So what is Hims & Hers stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Hims & Hers could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!