


Key Takeaways
- Grab stock is up 23% in the past week after third-quarter adjusted EBITDA rose 73% to a record $237 million and the company raised its 2026 outlook.
- The jump came off a three-year low, and Grab still has $500 million left on its buyback.
- Even after the jump, the stock is down 33% in 2026, and I’d buy more.
- The risk is credit, as Grab’s loan book tripled to $2.71 billion in a year.
Grab Holdings (GRAB) stock is up 23% in the past week. The company reported a record third quarter after the close on Monday, Nov. 2, raised its outlook and said it had bought back $400 million of stock.
The jump came off a three-year low. Grab had agreed on Sept. 15 to pay $1.49 billion for 60% of the Singapore lender Atome Financial, and investors balked at the push into consumer lending.
A record quarter, and a bigger outlook
Revenue rose 27% to $1.11 billion, and adjusted EBITDA rose 73% to $237 million. The margin widened to 21.3% from 15.6% a year ago. Financial Services, the business Atome will join, made an adjusted EBITDA profit for the first time.
Grab lifted its 2026 outlook, too. It now sees revenue of $4.15 billion to $4.20 billion and adjusted EBITDA of $790 million to $800 million. Analysts expected $738 million of EBITDA going into the report. They’re now at the top of the new range, and they expect EBITDA to nearly double again by 2028:
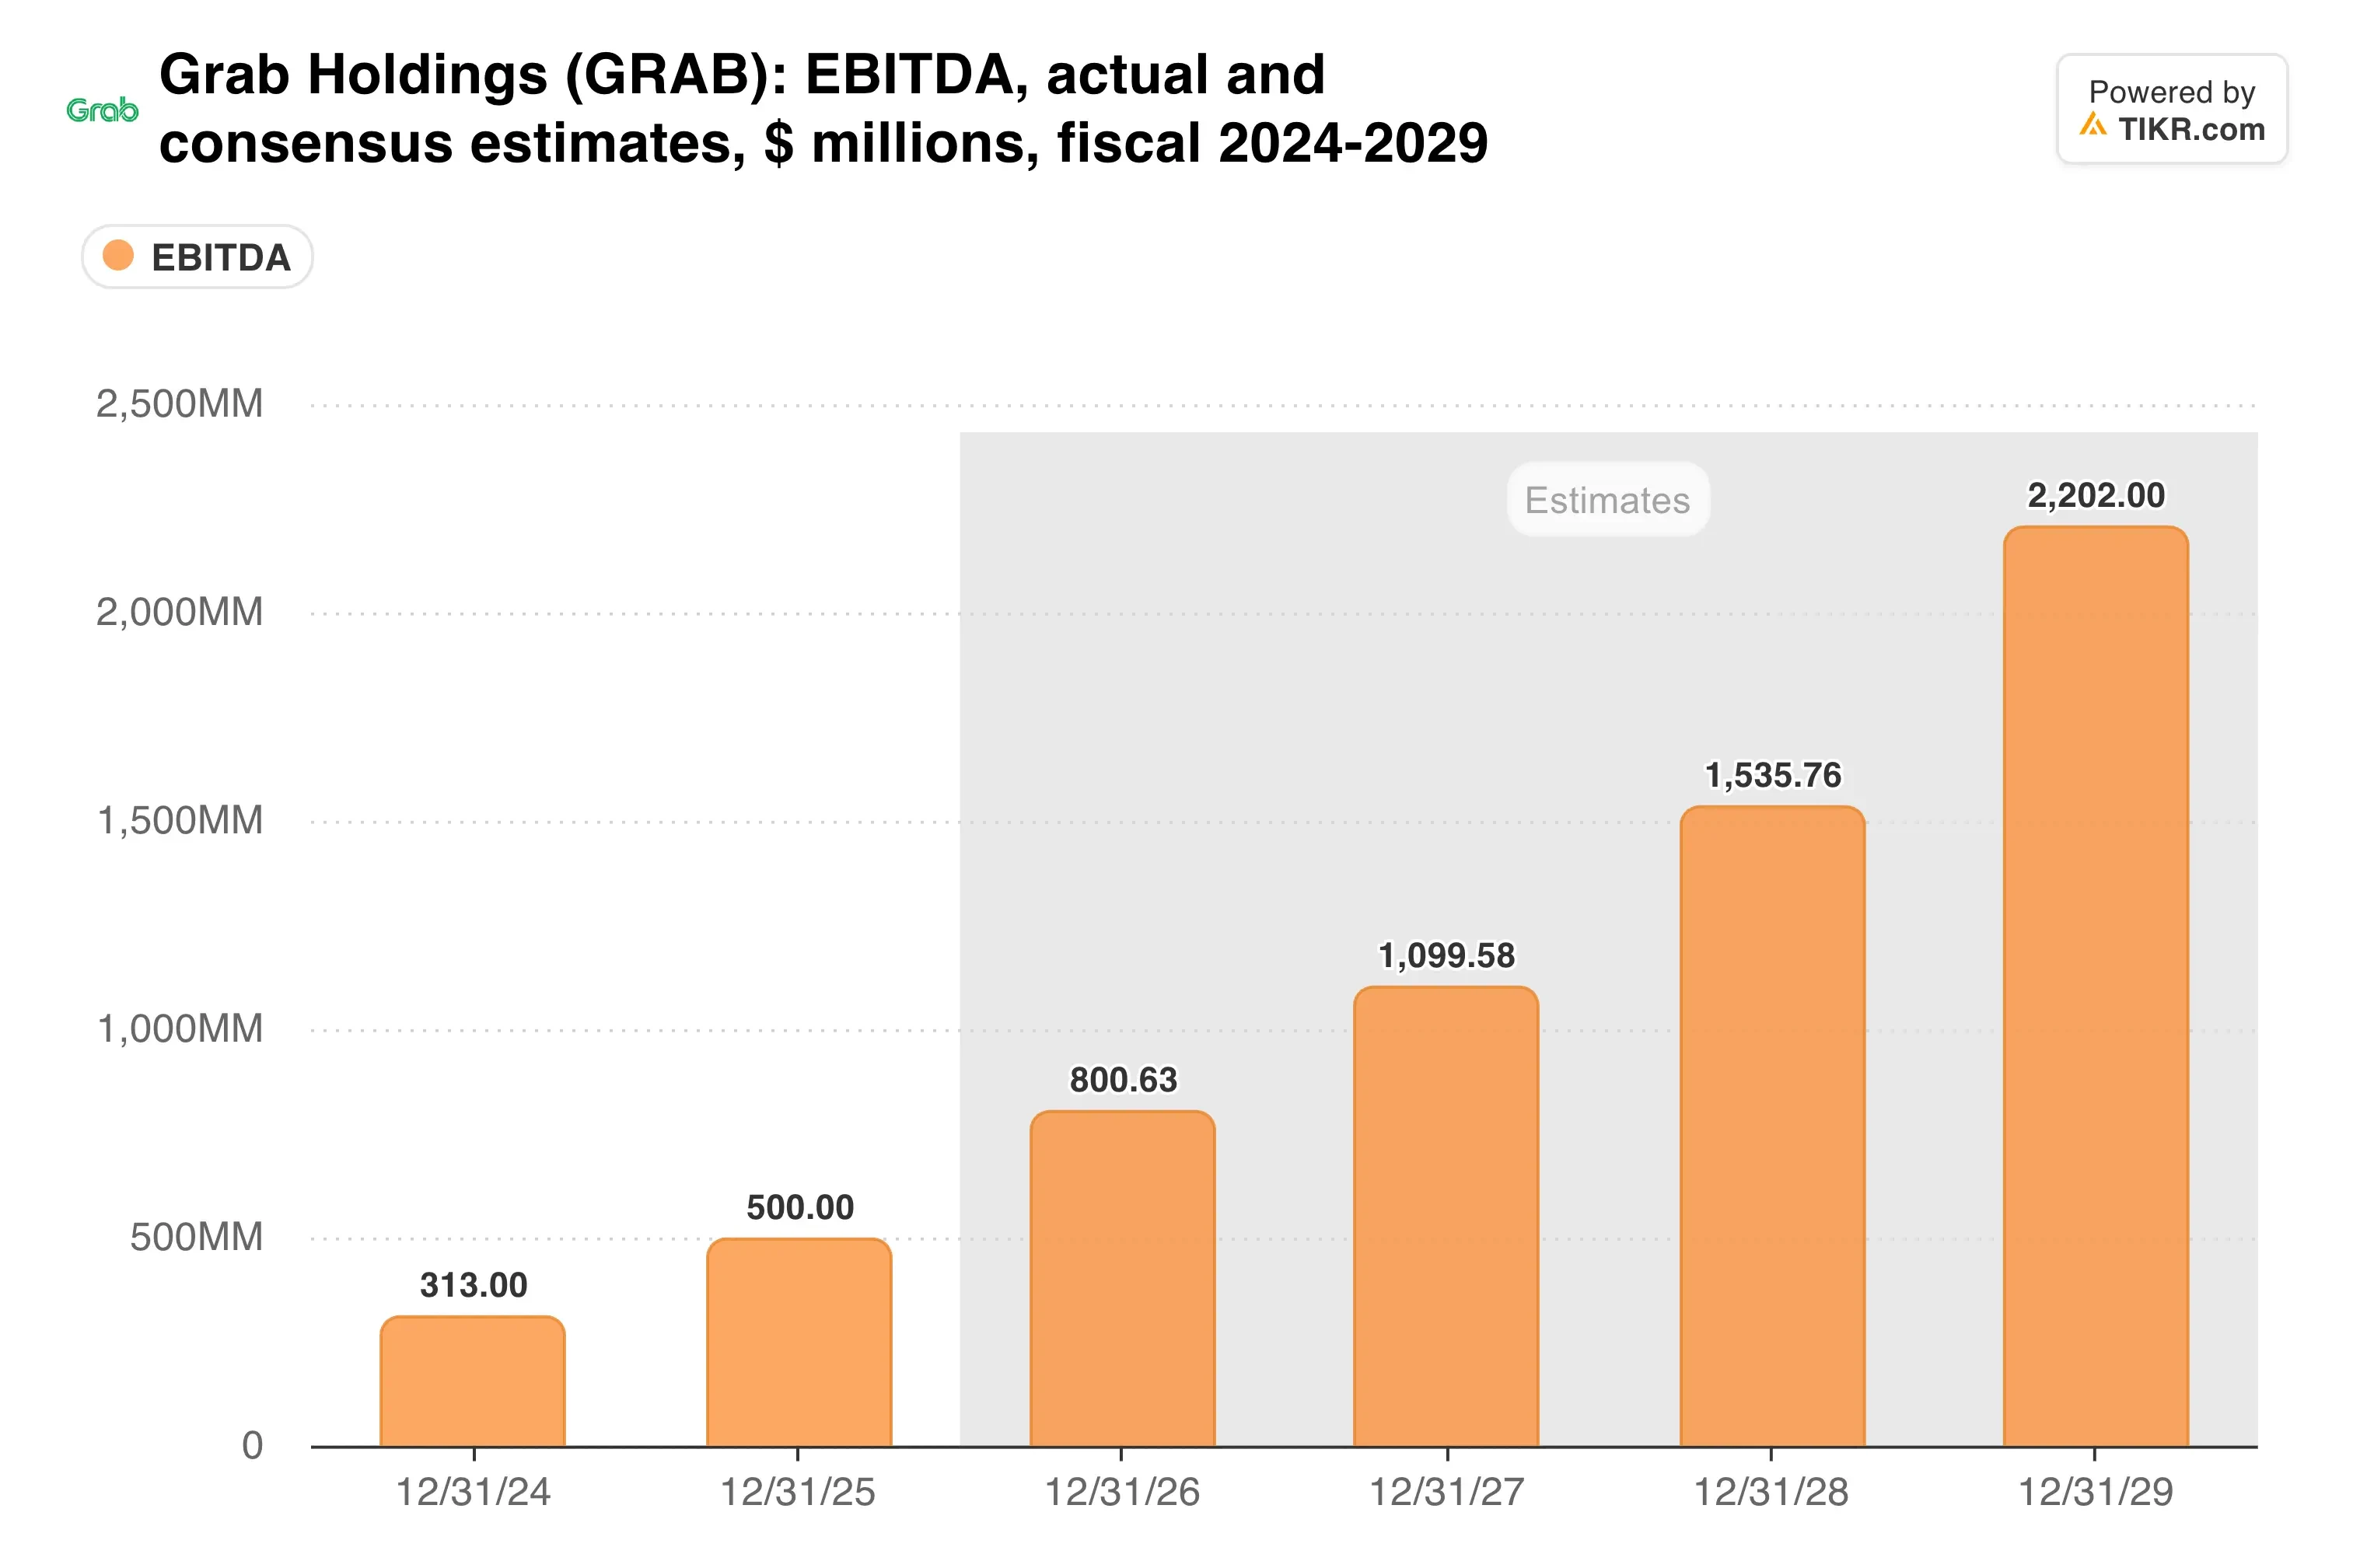
That $1.54 billion for 2028 is still short of management’s $1.7 billion target for the year.
Management is buying, too
Grab bought back $400 million of shares in September and October. The $500 million left on its program is about 3.6% of its $13.8 billion market value at Friday’s close. CEO Anthony Tan also bought $29.9 million of stock himself in September.
TIKR tracks 24 analysts on Grab Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Grab Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Grab Holdings’ Analyst Ratings
I’d buy more here
Even after the jump, Grab is down 33% in 2026. At Friday’s close, it traded at 24.5x forward earnings and 16.2x the $0.21 a share analysts expect it to earn in 2028. The Street’s $5.46 average target is about 60% above that close.
The risk is credit. Grab’s loan book tripled to $2.71 billion in a year, and losses on its loans held back the quarter’s gain in operating profit. Atome will add far more consumer loans once the deal closes.
Grab kept growing right through the sell-off, and management is buying at these prices, so I’d buy more. Of course, Atome’s loans have to perform, and the fourth-quarter report, likely in February, is the next check.
So what is Grab stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Grab could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



