Key Takeaways
- Grab is still down 37% in 2026, and shares hit a more than three-year low after its $1.49 billion deal for most of the lender Atome Financial in September.
- Third-quarter revenue rose 27%, adjusted EBITDA rose 73%, and Grab raised its 2026 guidance.
- Management has bought back $400 million of stock since September, and the CEO bought $29.9 million of shares himself.
- The main risk is the push into consumer lending, and the next report and the Atome deal’s closing are what to watch.
Grab Holdings (GRAB) is still down 37% in 2026, even though its business has grown all year.
After its third-quarter report on Monday evening, which showed record adjusted EBITDA and raised the outlook for the year, I think the selling has run well ahead of the facts.
A $1.49 billion bet on lending
On Sept. 15, Grab agreed to pay $1.49 billion in cash for 60% of the Singapore lender Atome Financial. CFO Peter Oey told CNBC that Grab plans to buy the remaining 40% roughly two years later.
The same day, Grab raised its 2028 targets to $1.7 billion of adjusted EBITDA and revenue growth of 30%+ a year.
Investors weren’t convinced. In the days after, the stock slid to a more than three-year low, and BofA, Citi, Maybank, Barclays and J.P. Morgan all cut their price targets between late September and late October.
The insiders bought instead. A filing late on Sept. 21 showed CEO Anthony Tan bought 10.4 million shares for $29.9 million, and other top executives bought too.
TIKR tracks 24 analysts on Grab Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Grab Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Grab Holdings’ Analyst Ratings
Management is putting its money down
Also on Sept. 15, Grab said it would spend the remaining $900 million of its buyback authorization over the next 12 months. That’s about 7% of its $12.9 billion market value at Monday’s close. With $7.4 billion of gross cash liquidity ($5.4 billion net) at June 30, Grab can afford it.
“The business continues to compound, and the dislocation between that performance and where our shares trade remains an opportunity we intend to act on,” Oey said in the announcement.
And Grab is acting on it. It bought back $400 million of stock in September and October, leaving $500 million to go.
Then came the third quarter
Third-quarter revenue grew 27% (30% in constant currency) to $1.11 billion. Adjusted EBITDA rose 73% to $237 million, a 21.3% margin against 15.6% a year earlier. Financial Services, the business Atome will join, turned an adjusted EBITDA profit for the first time. Grab now guides to $4.15-$4.20 billion of revenue and $790-$800 million of adjusted EBITDA for 2026.
Going into the report, analysts expected EBITDA to keep climbing steeply through 2028:
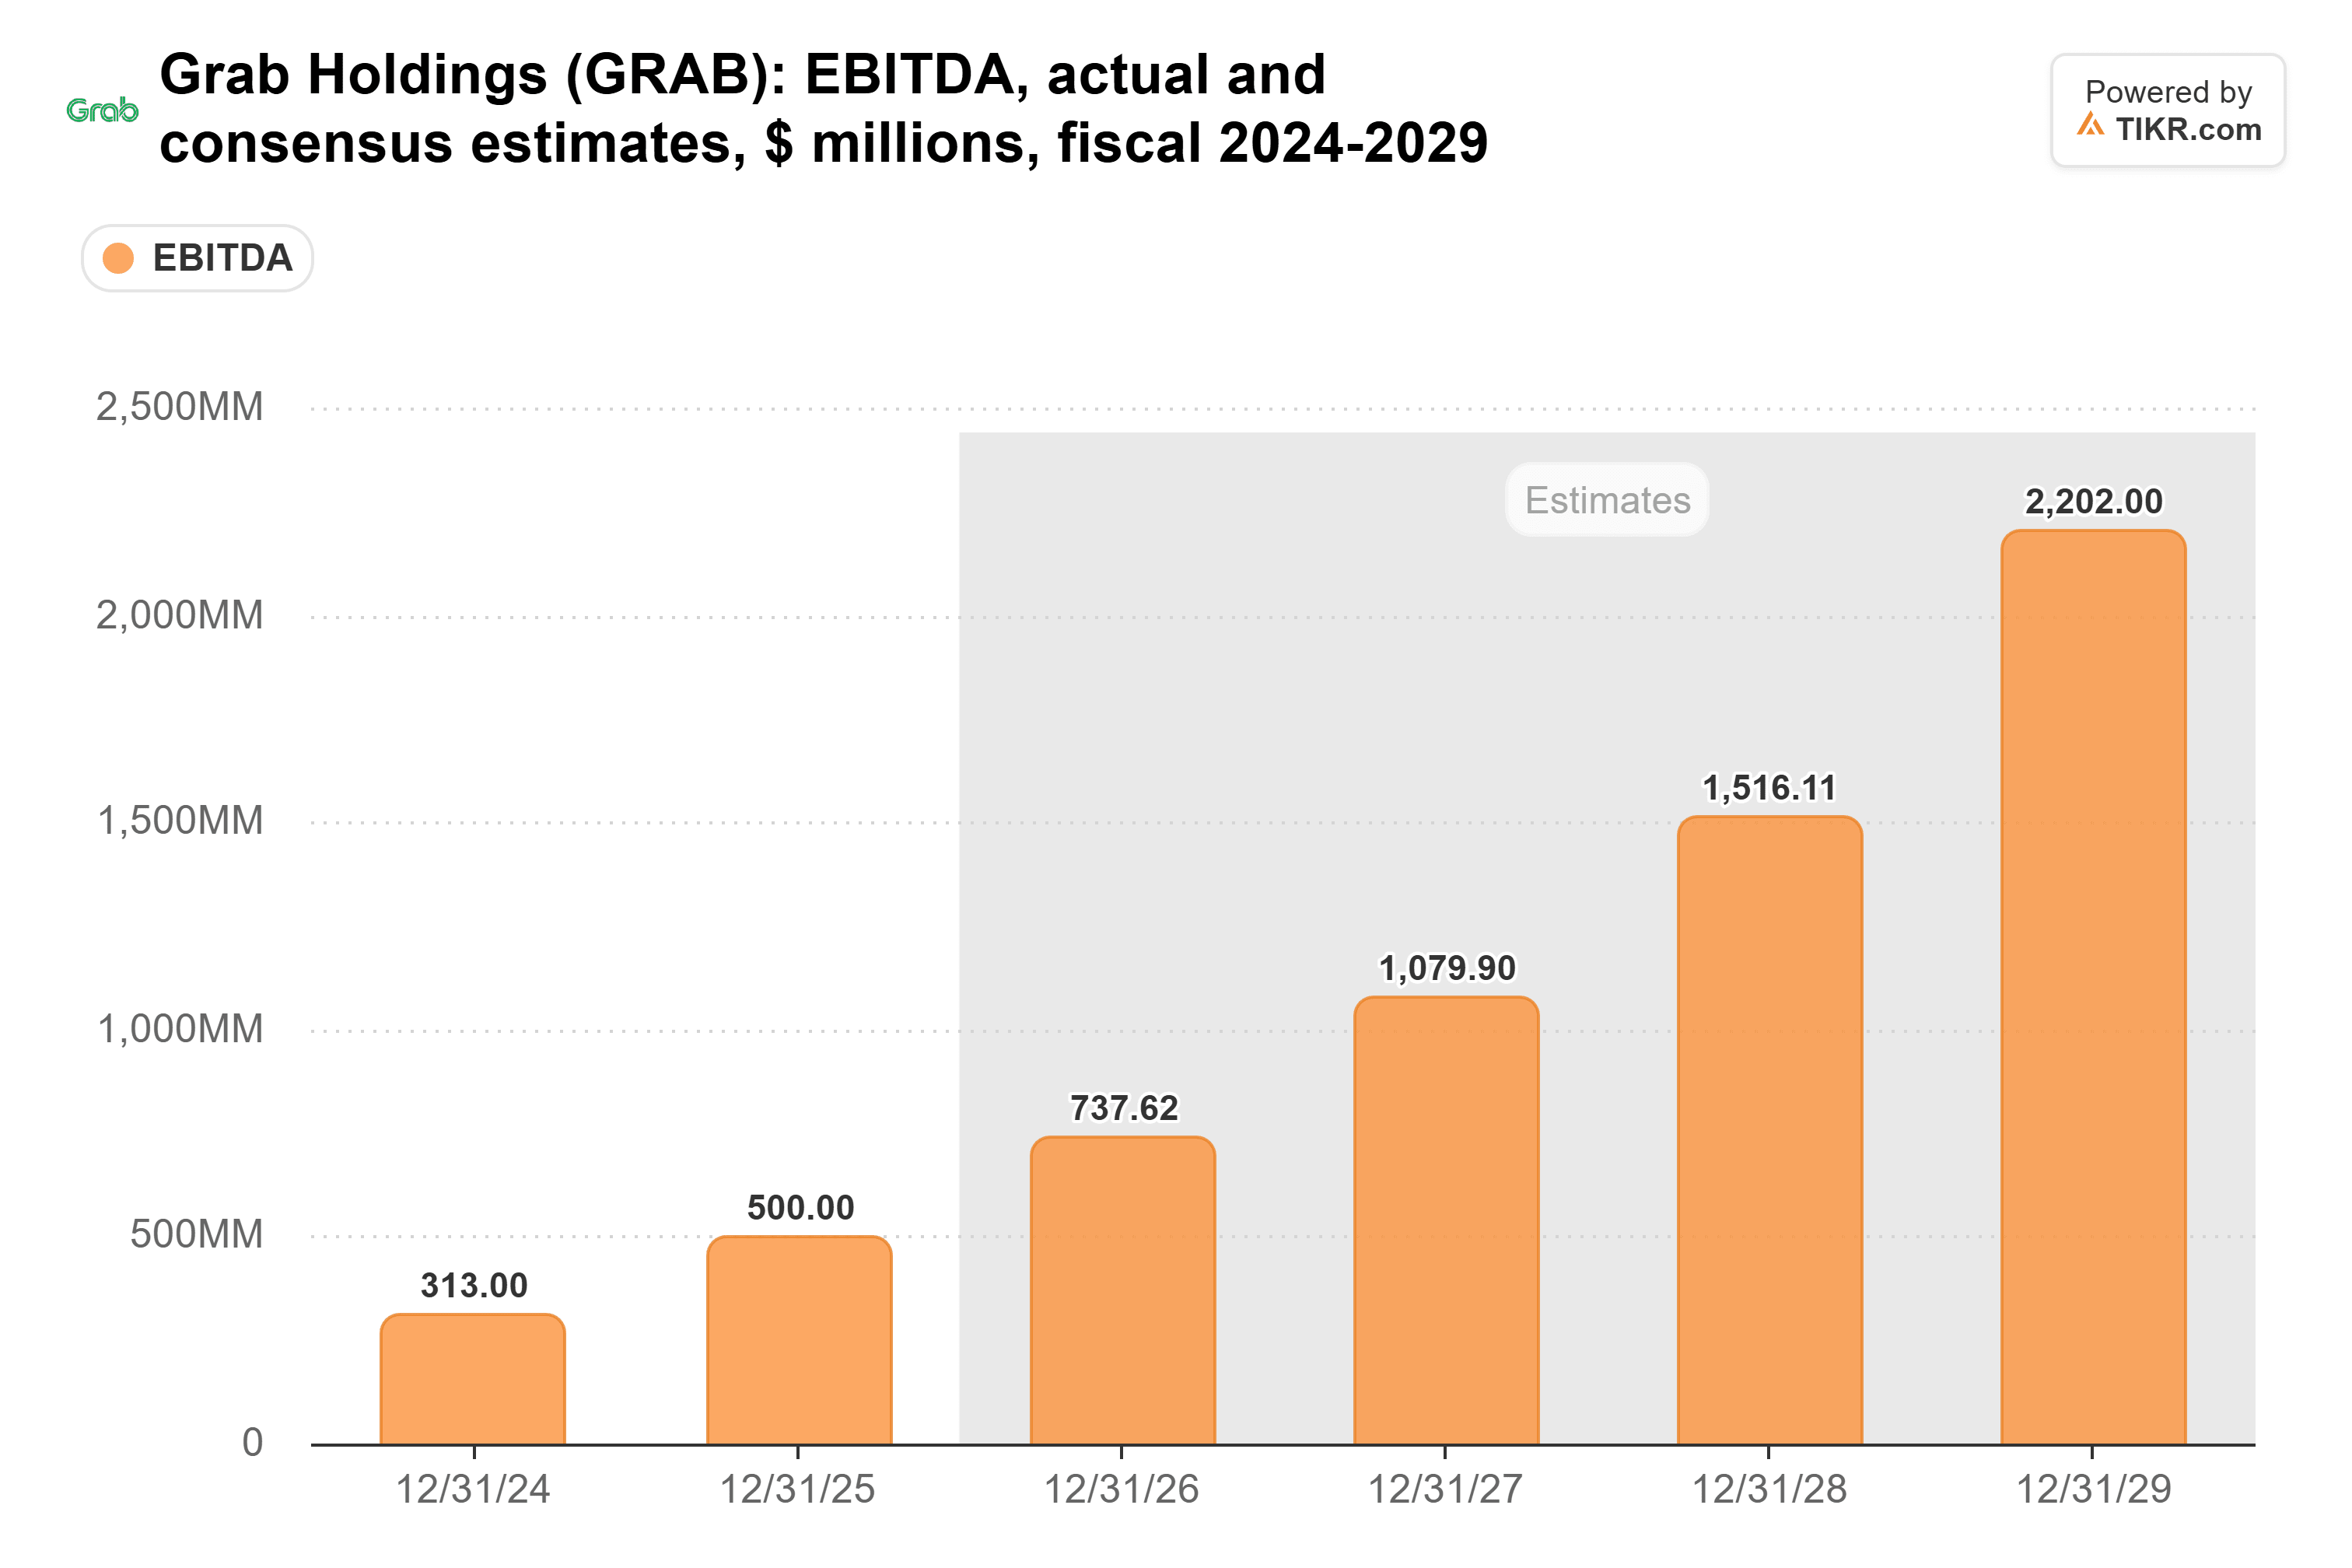
Grab’s new guidance is above the $738 million analysts expected for this year. And the $1.52 billion they see for 2028 is still short of management’s $1.7 billion target, so analysts aren’t fully buying it yet.
The risk is credit. Operating profit rose to $108 million, but higher losses on loans offset part of the gain, and Atome will put far more consumer loans on Grab’s books.
Is this the bottom?
At Monday’s close, Grab traded at about 21x forward earnings, for a company that just grew adjusted EBITDA 73%.
The Street’s average price target fell this autumn as the banks cut theirs, but it’s still far above the stock:
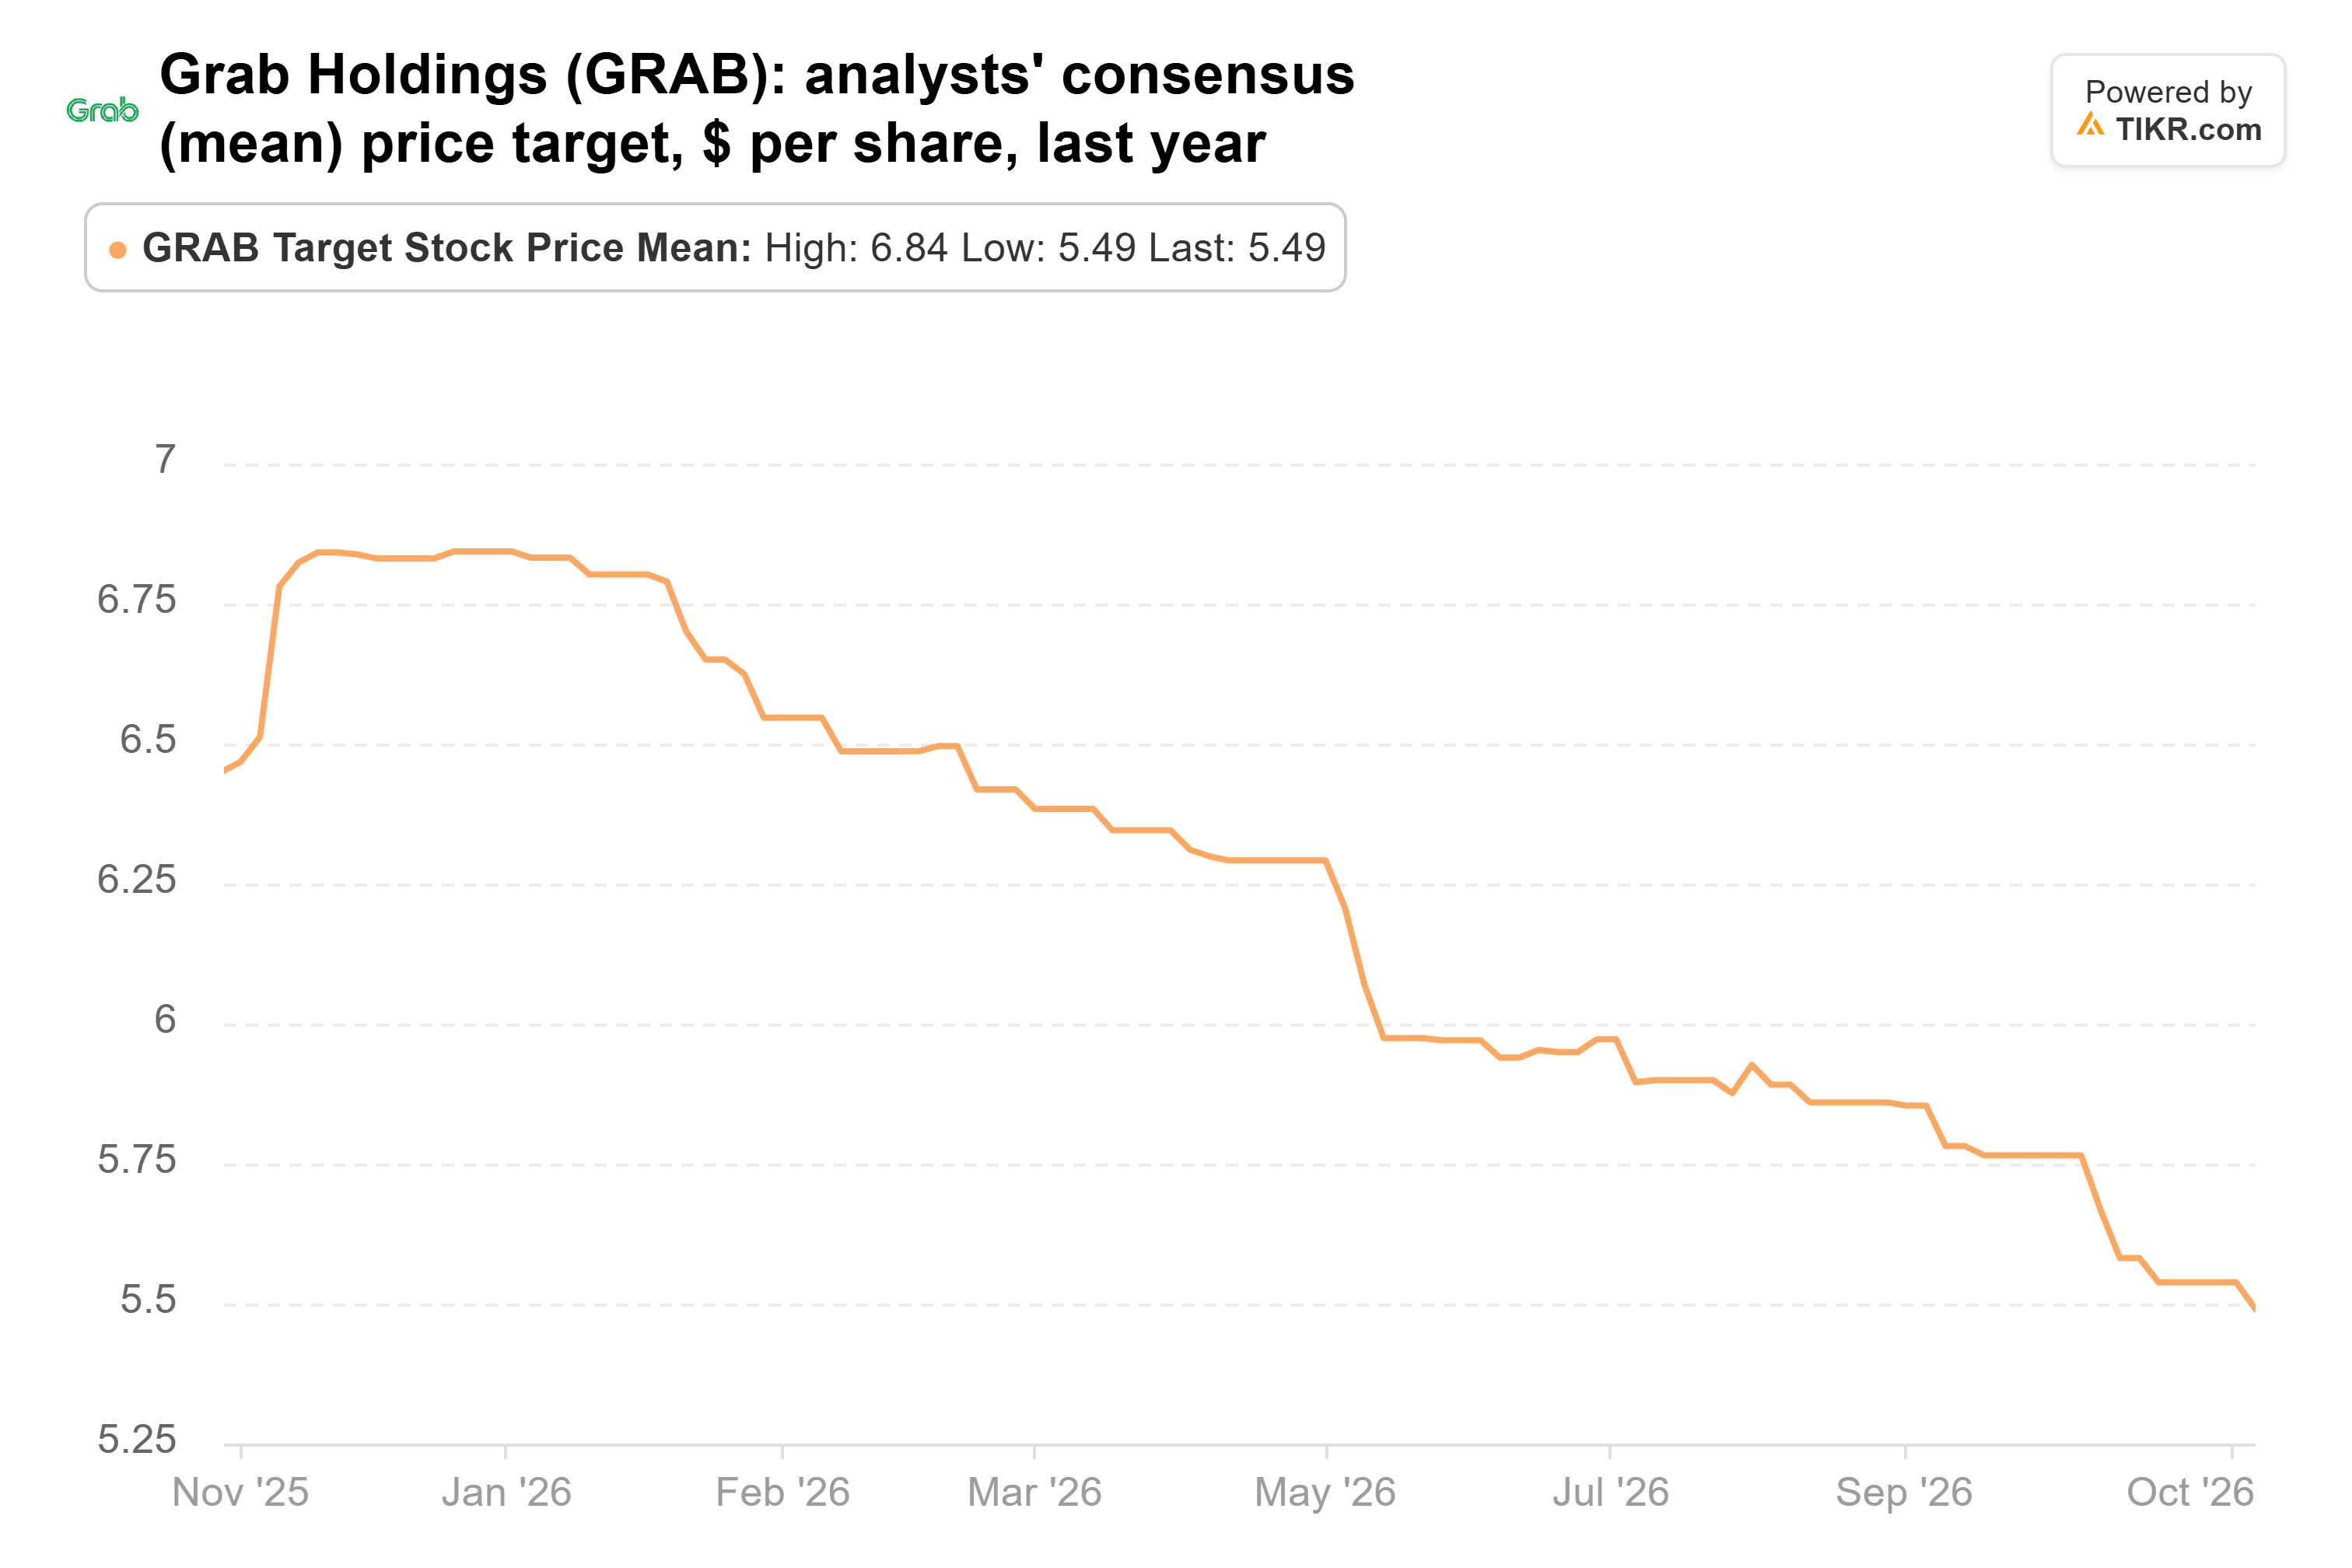
That $5.49 average is about 92% above Monday’s close, and even the lowest target, $4, is 40% above it. J.P. Morgan raised its target to $5.10 on Nov. 3, a week after cutting it to $4.80.
Grab’s business grew all year while its stock fell, and management is buying back shares as fast as it promised. I think the selling ran well ahead of the business, and at this price, Grab looks like a buy to me.
Of course, Atome still has to close, and its loans have to perform. The fourth-quarter report, likely in February, is the next check.
So what is Grab stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Grab could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!