Key Takeaways
- Fabrinet shares fell 32% in the past month as AI optics stocks, including Coherent, Lumentum and Marvell, sold off on fears about AI funding and hyperscaler spending.
- Fabrinet had no news of its own during the sell-off. Its Nov. 2 report showed record quarterly revenue of $1.47 billion, up 51% from a year earlier.
- Barclays rates the stock Buy with a $496 target. That target needs only about Fabrinet’s usual multiple on the earnings analysts expect for fiscal 2028.
- Before the next report in early February, watch hyperscaler spending and what Marvell’s reported deal for Lumentum, a key customer, means for Fabrinet’s orders.
Fabrinet (FN) stock has lost 32% in the past month, and the company gave investors no reason to sell.
The selling hit AI optics as a group. Coherent (COHR) fell 41% over the same month. Lumentum (LITE), which Northland counts among Fabrinet’s key customers, and Marvell Technology (MRVL), reportedly in advanced talks to buy Lumentum, fell 37% each. Then Fabrinet reported a record quarter after the close on Nov. 2, and on Nov. 3, Barclays rated the stock Buy with a $496 target, 58% above the Nov. 2 close.
Guilty by association
The trouble started on Oct. 12, when Broadcom CEO Hock Tan said capital would be the biggest constraint on the AI buildout. Two days later, warnings from Broadcom and Intel about AI funding hit optical stocks again. On Oct. 22, Fabrinet, Lumentum and Coherent fell together as tech stocks slid ahead of earnings, with no news from any of them. And Big Tech’s reports on Oct. 30 stirred up fears about how much the hyperscalers will spend.
Analysts followed the stock down: B. Riley cut its target twice, to $385, Susquehanna cut to $600 and JPMorgan to $465.
TIKR tracks 9 analysts on Fabrinet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Fabrinet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Fabrinet’s Analyst Ratings
Demand didn’t go anywhere
Meanwhile, Fabrinet’s business was booming. In its fiscal first quarter, the three months to September, revenue rose 51% from a year earlier to a record $1.47 billion. Non-GAAP EPS climbed to $4.34 from $2.92. Both came in well above its guidance. Data center revenue, more than half the total, jumped 78% to $777 million.
Management expects $1.6 billion to $1.65 billion of revenue this quarter. CEO Seamus Grady said in the release, “Broad-based demand across multiple significant programs drove these results, with new product ramps further supporting our growth.”
A key customer is changing hands
Lumentum’s own demand looks fine. StoneX initiated coverage on Oct. 26 with a Buy rating and a $1,200 target, on the view that it’s sold out into 2029. For Fabrinet, what counts is what Marvell does with Lumentum’s manufacturing once it owns the company. Do those orders stay put?
Coherent fell the hardest of the three, and StoneX gave it a Buy the same day, with a $425 target. If the optics makers analysts like best can sell off this hard, the market is worried about how AI gets paid for.
Does $496 add up?
Going into the report, analysts expected Fabrinet’s earnings to keep climbing for years:

Analysts see normalized EPS rising from $14.09 in fiscal 2026 (the year to June 2026) to $21.96 in fiscal 2028. After a record quarter and a bigger revenue guide, I’d expect analysts to raise those numbers before they cut them.
After the drop, the stock looks cheap on those estimates:
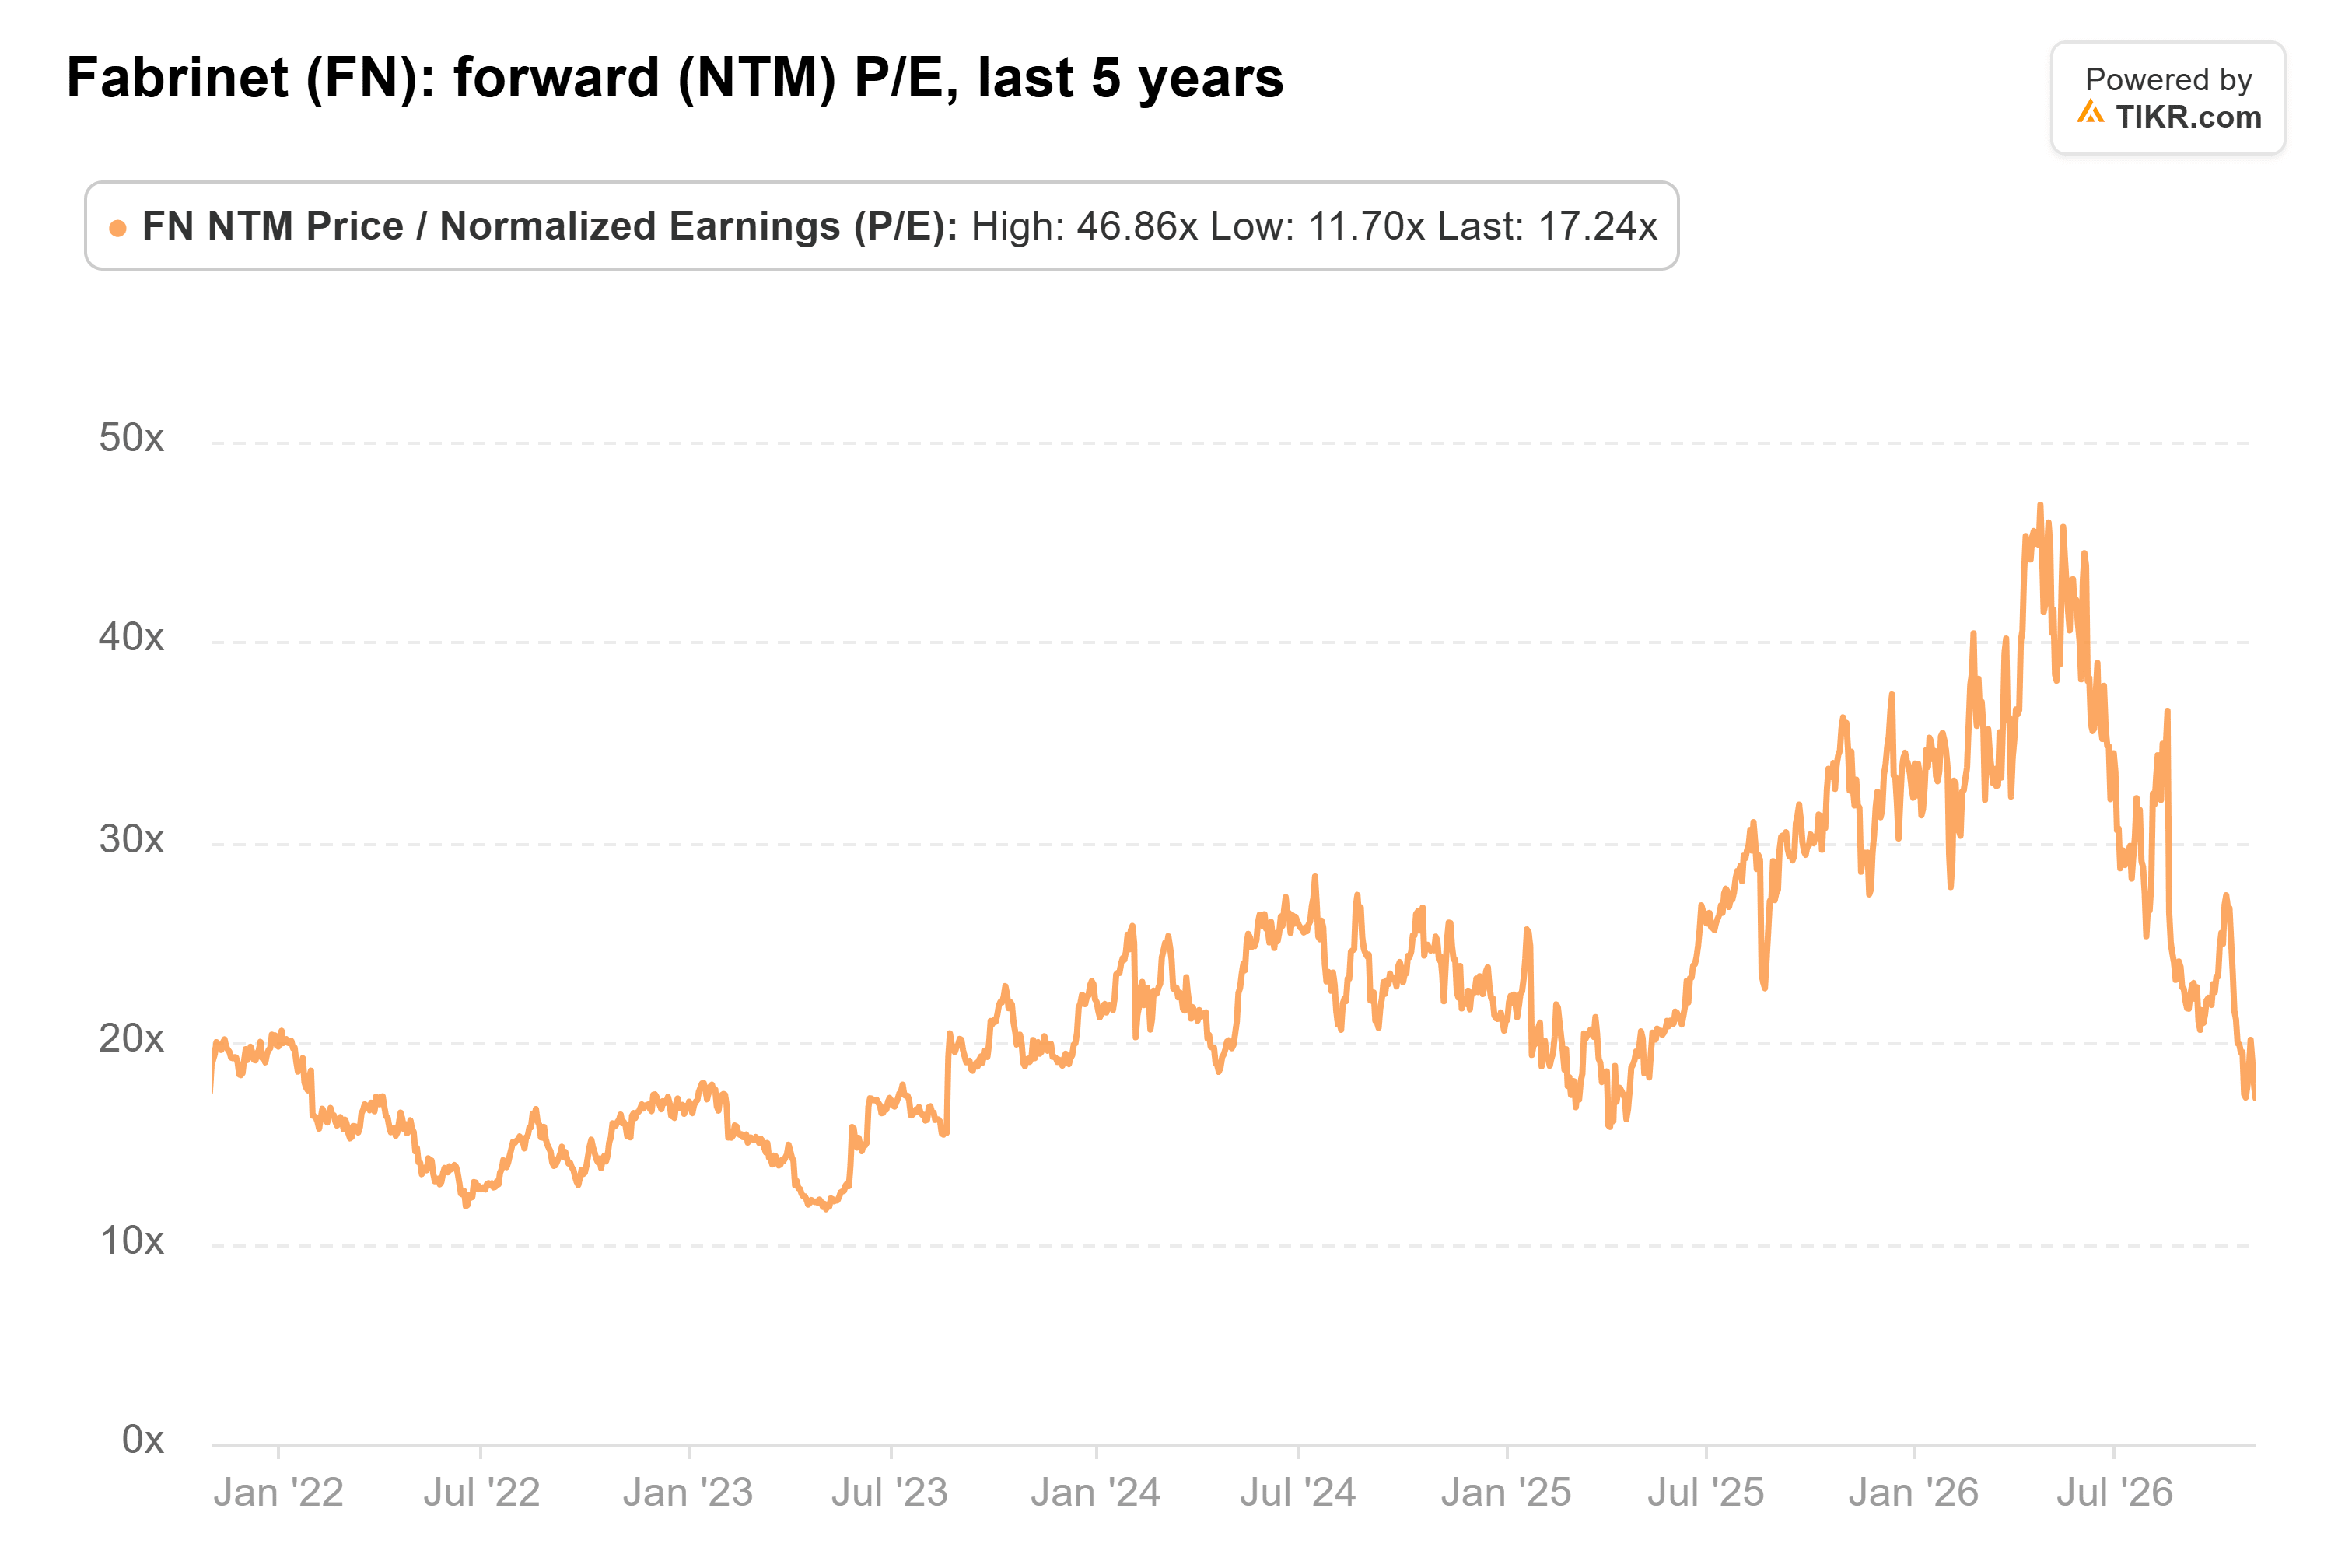
At the Nov. 2 close, Fabrinet traded at about 17x forward earnings, against a five-year average of 22x.
Barclays’ $496 is about 27x the next twelve months’ expected earnings. But a 12-month target looks a year out, and on fiscal 2028’s $21.96 it’s about 23x, right around Fabrinet’s usual multiple.
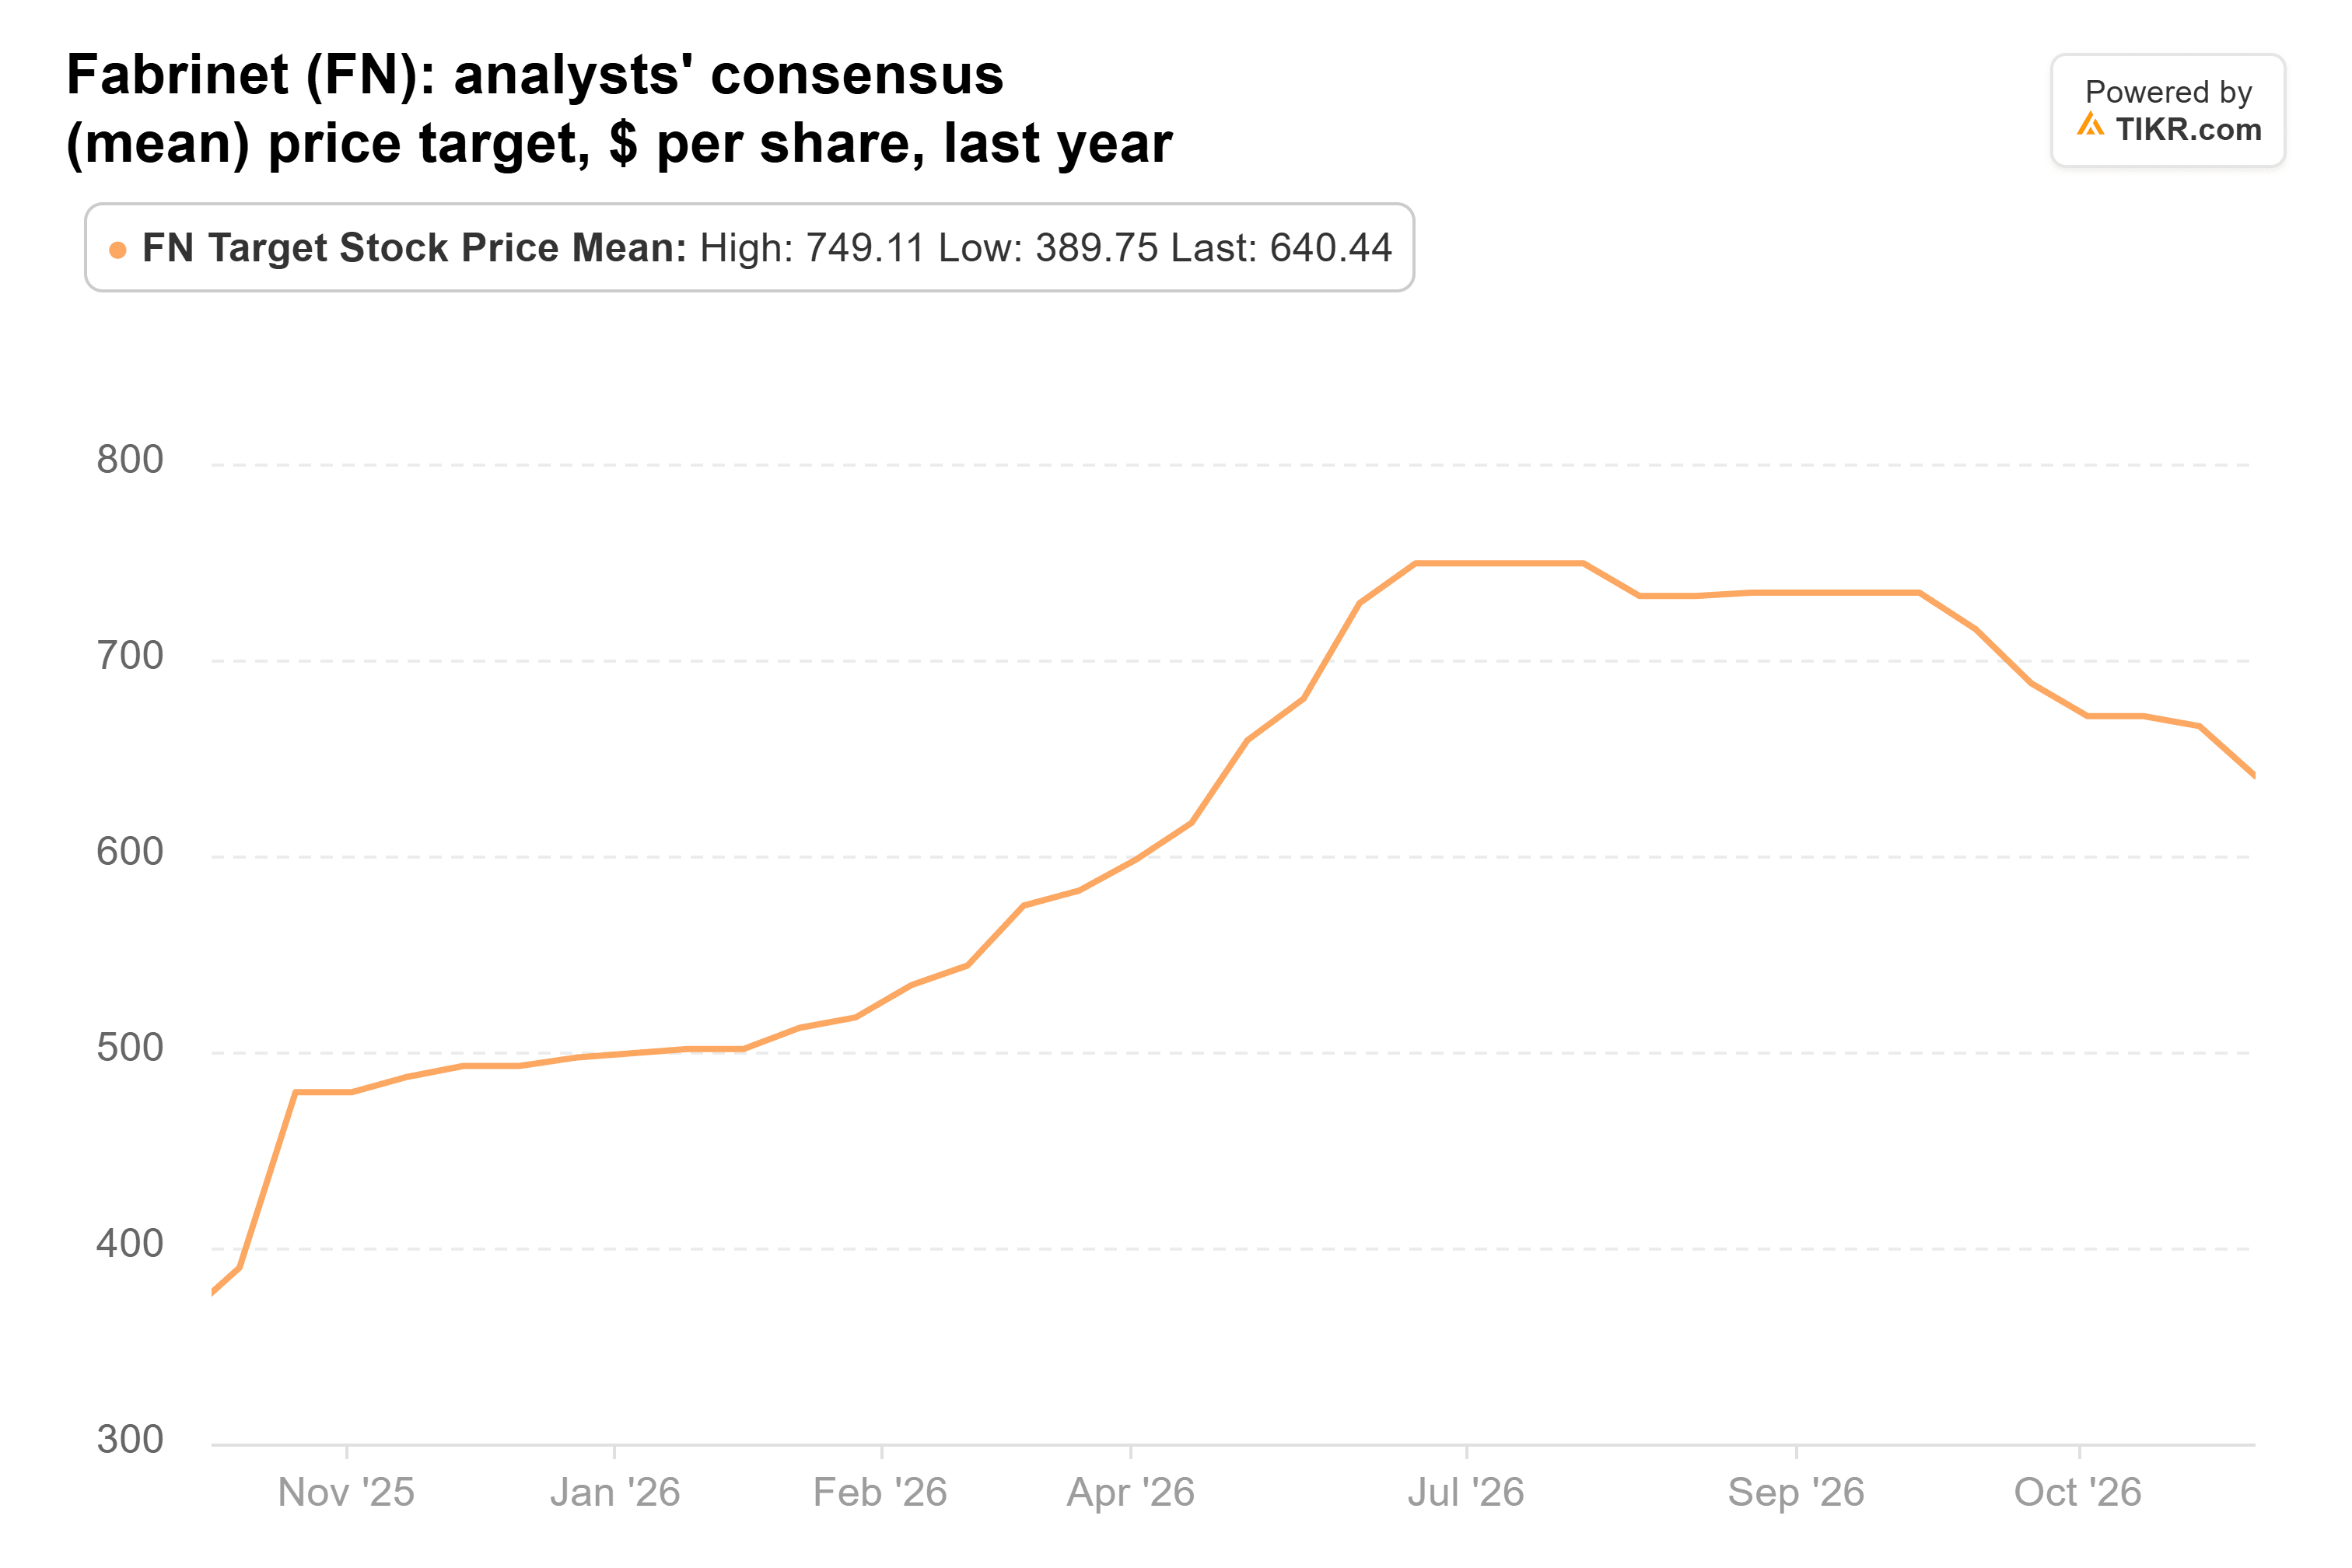
And Barclays is more cautious than most. The consensus target has come down from its June high of $749, but at $640, it’s still well above $496:
I’d buy here
I think Fabrinet is a buy at this price, and Barclays’ $496 looks conservative to me as long as the estimates hold.
The next check is the fiscal second-quarter report in early February. Before then, watch the hyperscalers’ spending plans and the terms of any Marvell-Lumentum deal. If the big spenders pull back, or Marvell moves Lumentum’s work away from Fabrinet, analysts will have reason to cut those estimates.
So what is Fabrinet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Fabrinet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!