Key Takeaways
- Enterprise Products Partners yields 6.0% and Altria Group 5.7%, and both raised their payouts in 2026: Altria by 4.7% in August and Enterprise by 2.8% with its third-quarter distribution.
- Enterprise’s distributable cash flow covered its distribution 1.7x in fiscal 2025, while Altria paid out 78% of its free cash flow in dividends over the twelve months to Sept. 30, 2026.
- Enterprise’s third-quarter adjusted EBITDA rose 16% and Altria’s net revenues rose 1.0%, but Altria carries far less debt.
- Enterprise expects more modest EBITDA growth in 2027, and Altria targets mid-single-digit dividend growth through 2028.
Any retiree hunting for a dividend near 6% is going to land on Enterprise Products Partners (EPD) and Altria Group (MO).
But their businesses are moving in different directions. On Oct. 29, Enterprise reported third-quarter adjusted EBITDA of $2.8 billion, up 16% from a year earlier, while Altria’s net revenues rose just 1.0% to $6.1 billion. So if I could hold only one for the next 10 years, which one gets my dividend dollars?
| Metric | Enterprise Products Partners (EPD) | Altria Group (MO) |
|---|---|---|
| Dividend yield | 6.0% | 5.7% |
| Annual dividend at the current rate | $2.24 a unit | $4.44 a share |
| Dividend growth, fiscal 2020-2025 | 4.0% a year | 4.1% a year |
| Coverage | 1.7x distributable cash flow coverage (fiscal 2025) | 78% cash dividend payout ratio (TTM) |
| Net debt/EBITDA (LTM) | 3.2x | 1.7x |
| Interest coverage (LTM) | 5.1x | 10.9x |
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Enterprise keeps adding capacity
Enterprise is an MLP, so it pays distributions on units, and holders get a K-1 at tax time. New assets placed in service over the past year, including its 11th Delaware Basin gas plant and the Bahia NGL pipeline, helped push its Permian natural gas processing volumes to a record 4.6 Bcf/d in the third quarter of 2026, up 12% from a year earlier.
Past projects have paid off. Distributable cash flow per unit nearly doubled from $1.96 in fiscal 2016 to $3.66 in fiscal 2025, while the distribution rose from $1.61 to $2.17 a unit:
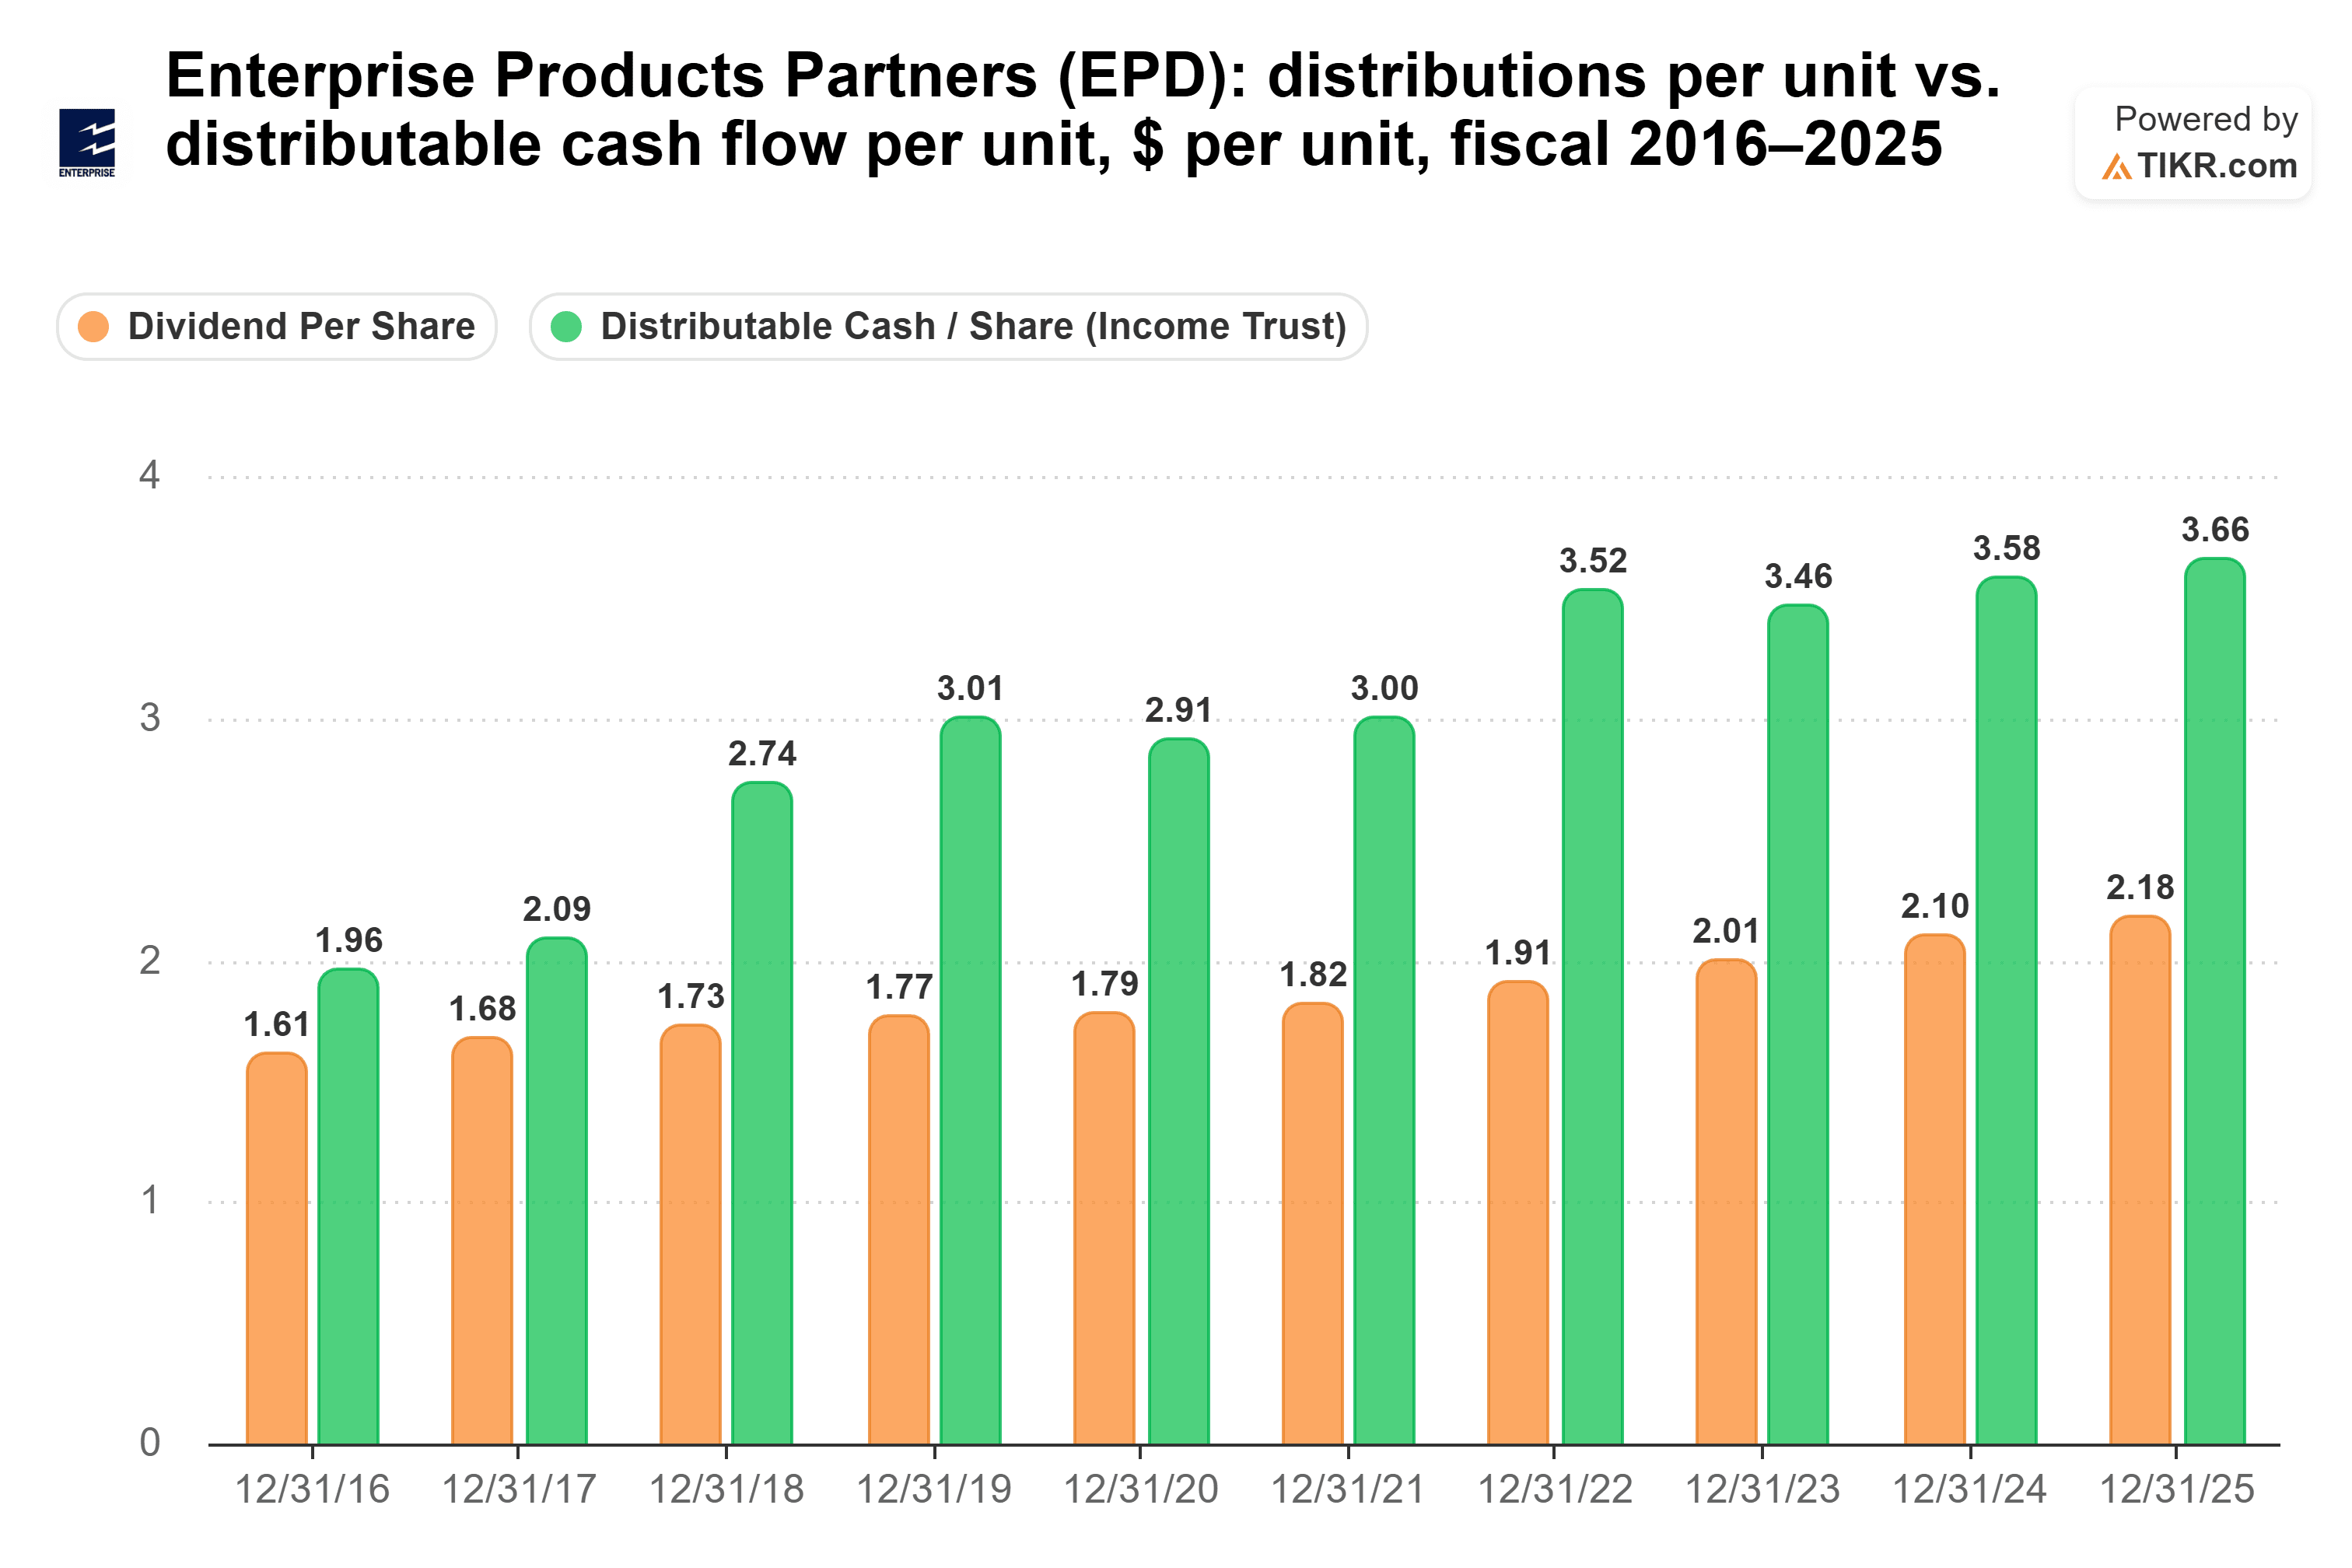
That’s comfortable coverage of 1.7x in fiscal 2025, and coverage hasn’t dipped below 1.58x since fiscal 2018.
The raise is the soft spot. The new $0.56 quarterly distribution is up 2.8% from a year earlier, below Enterprise’s 4.0% yearly pace from fiscal 2020 to fiscal 2025. Enterprise also carries more debt, at 3.2x EBITDA over the past twelve months.
Altria’s cash is mostly spoken for
Altria brings a similar yield from the other direction: a stronger balance sheet, and a core business it says is shrinking. With domestic cigarette shipment volumes declining, Altria is leaning on Marlboro’s premium Cowboy Cut and its on! nicotine pouches, whose shipment volume rose 13.3% in the third quarter of 2026. On Oct. 29, it also raised its 2026 adjusted EPS guidance to $5.66-$5.74.
In August, Altria raised its quarterly dividend 4.7% to $1.11, its “61st increase in 57 years.” Its third-quarter release says more raises are coming: “We maintain our progressive dividend goal that targets mid-single digits dividend per share growth annually through 2028.”
The cash to pay for that is there, but the cushion is thinner. Free cash flow has covered the dividend every year since fiscal 2018. Over that time, though, dividends paid rose from $5.42 billion in fiscal 2018 to $6.96 billion in fiscal 2025, while free cash flow went from $8.15 billion to $9.07 billion:
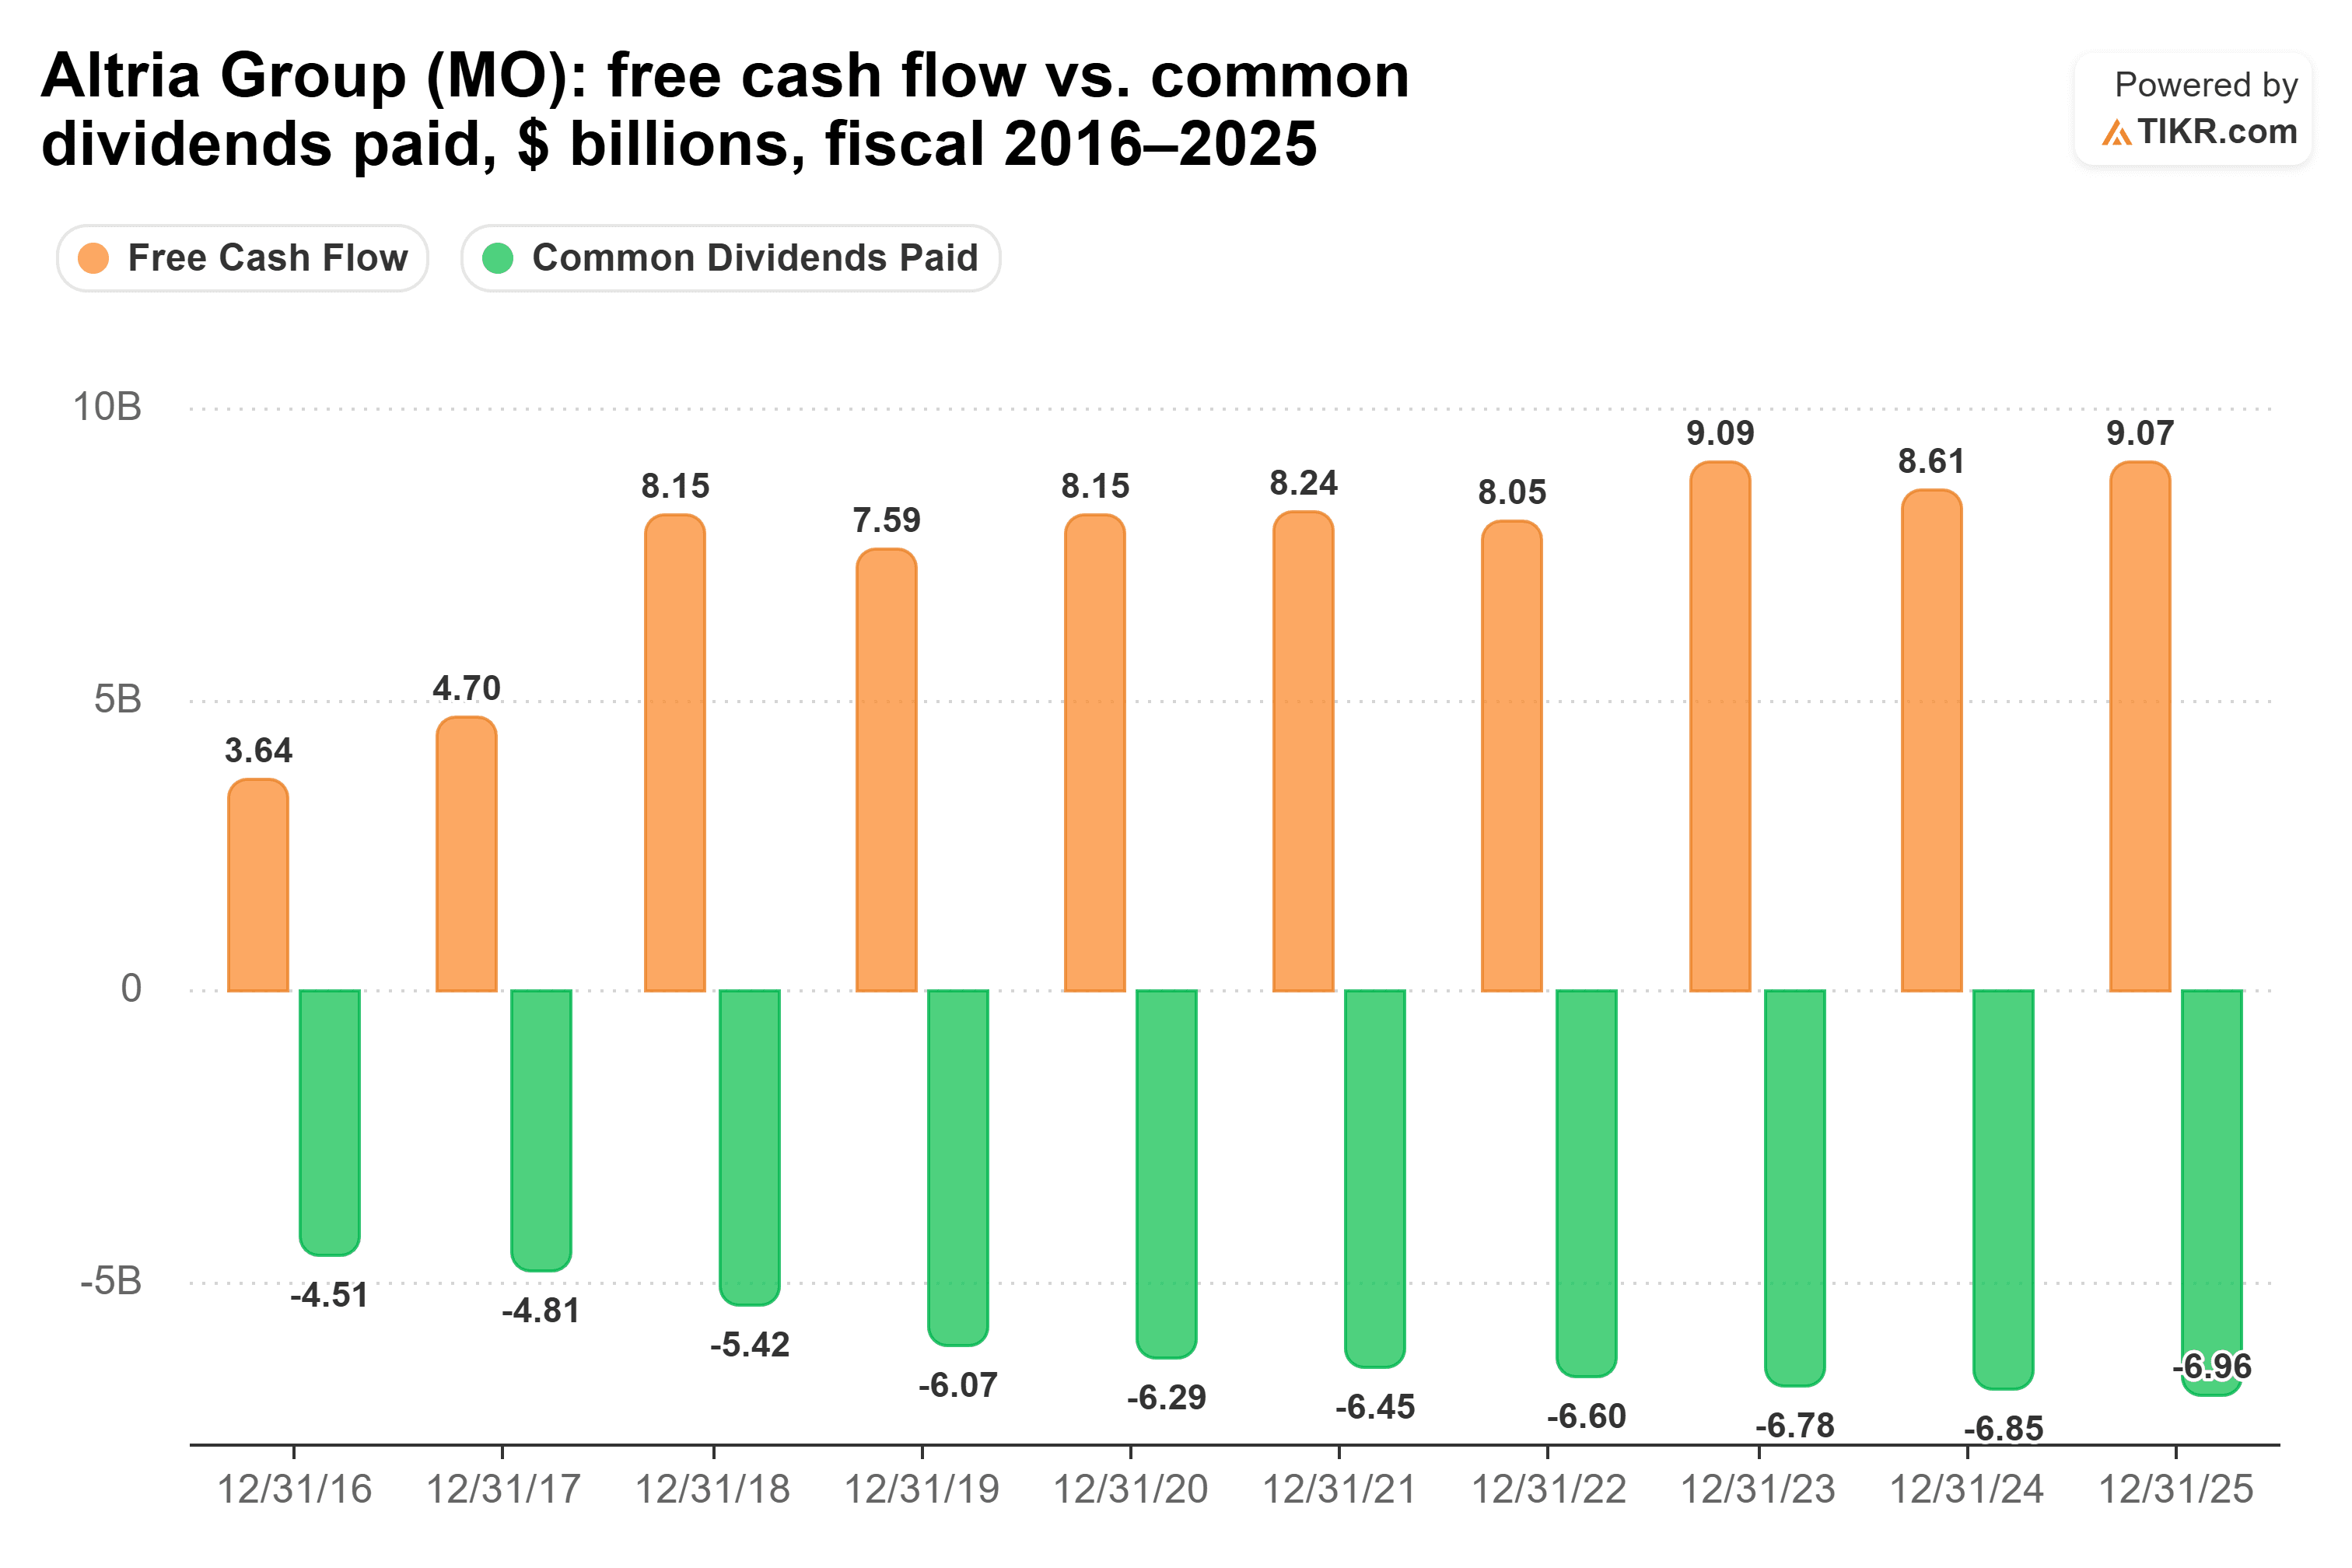
That leaves a heavy cash dividend payout ratio of 78% over the twelve months to Sept. 30, 2026, in line with the 75% to 82% it ran each year from fiscal 2021 to fiscal 2025. And the risk Altria names first is economic pressure on adult smokers, who are trading down to discount brands.
So which dividend wins?
I’m putting my 10-year dividend dollars in Enterprise Products Partners.
At each one’s five-year growth rate, $10,000 in Enterprise pays about $7,218 over the next 10 years, against about $6,881 for Altria. By year 10, Enterprise’s check would be about $857. Call it an 8.6% yield on the original $10,000.
Altria’s latest raise was bigger, 4.7% against 2.8%, and if it kept that pace, it could close the gap. I don’t think it can for a decade. At a 78% payout, Altria can’t keep growing its dividend much faster than its free cash flow, and its business is growing far slower than Enterprise’s. Enterprise’s distributions and buybacks took 54% of adjusted cash flow from operations over the twelve months to Sept. 30, 2026, below its own 55%-60% framework. It has room to raise faster, and a growing business to pay for it.
This isn’t to say Altria’s dividend is in trouble. It has a long record of raises, about half Enterprise’s debt relative to EBITDA, interest coverage of 10.9x, and freshly raised guidance. It’s just that, over 10 years, I’d rather own the check with more cash behind it.
Of course, Enterprise expects its 2027 EBITDA growth to be more modest than 2026’s, so I’ll be watching the size of next year’s raise.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!