Key Takeaways
- Barclays raised its Eli Lilly price target to $1,550 from $1,400 and kept its Overweight rating, with the stock close to a 52-week high.
- Lilly’s third-quarter revenue rose 39% to $24.4 billion because it sold 53% more, which more than made up for a 15% drop in realized prices.
- At $1,550, Eli Lilly would trade at about 33x analysts’ earnings estimates for the next twelve months, below its 5-year average of 40x, and the 2027 earnings estimate has risen since the third-quarter report.
- Barclays’ target holds up, but the upside is modest, and Lilly’s 2027 guidance in January has to show that falling prices aren’t eating into its volume gains.
Eli Lilly (LLY) is up 39% over the past year, and it closed at a 52-week high of $1,443.50 on Nov. 13. On Nov. 16, Barclays analyst Emily Field raised her price target to $1,550 from $1,400 and kept an Overweight rating. Shares touched $1,475.25 that day but closed down 0.8%. From the Nov. 17 close of $1,415.55, the new target leaves about 9% of upside.
Lilly keeps selling more for less
The raise comes after a big third quarter. Lilly’s revenue rose 39% to $24.4 billion as volume jumped 53%, which more than made up for a 15% drop in realized prices. The company also raised its 2026 revenue guidance by $5.5 billion at the midpoint, to $91 billion to $92 billion. Then on Nov. 12, China approved orforglipron, the daily pill Lilly sells in the U.S. as Foundayo. That made Lilly the first drugmaker with a GLP-1 weight-loss pill cleared there.
Field noted that one-time benefits helped the quarter. She still pointed to uptake of Lilly’s Medicare GLP-1 Bridge program, international demand and market-share gains as signs that the underlying growth is real.
And Lilly has plenty of room to grow volume. On the third-quarter call, CFO Lucas Montarce said Lilly reaches about 1 in 10 of its potential patients in the U.S. and 2 in 100 outside it.
TIKR tracks 31 analysts on Eli Lilly. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Eli Lilly, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Eli Lilly’s Analyst Ratings
Does $1,550 add up?
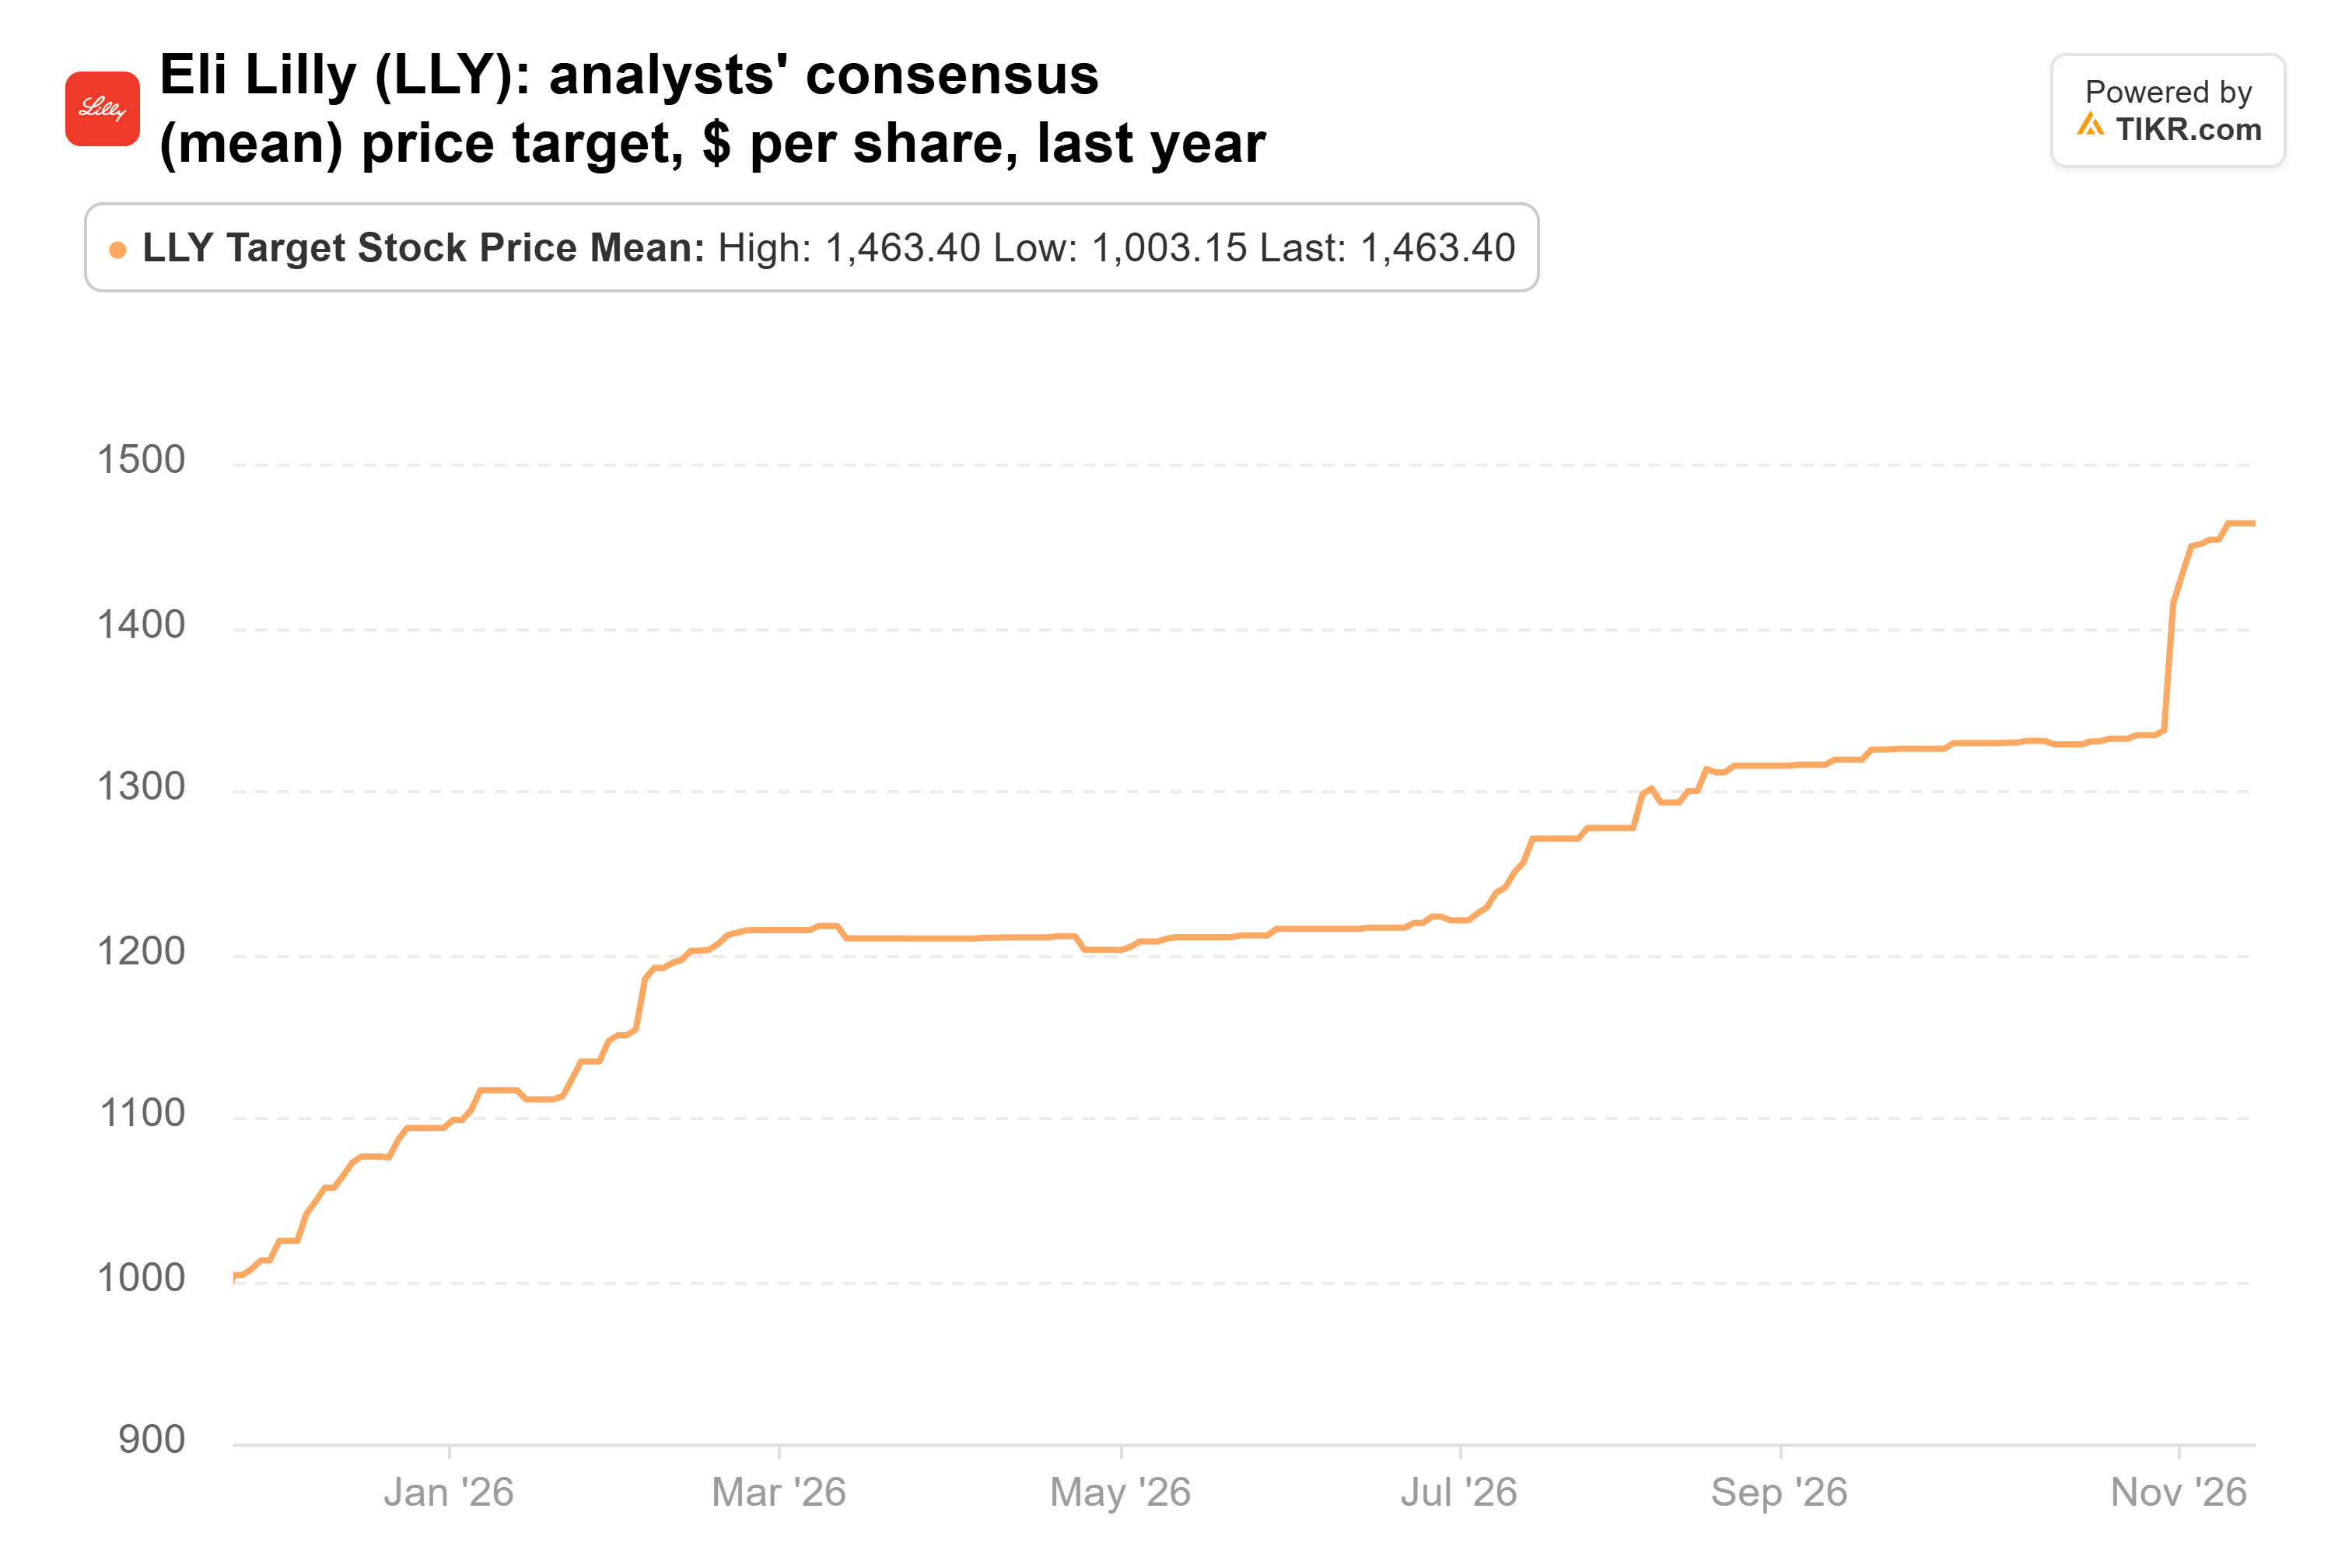
The rest of Wall Street has been moving the same way. Barclays’ $1,550 sits 6% above the $1,463 consensus target, though still below the $1,570 median. The consensus has climbed from $1,003 a year ago:
Earnings estimates are rising too. Analysts expect normalized EPS of $35.47 this year, held down by $4.57 a share of acquired IPR&D charges in the third quarter. After that, they expect $50.80 in 2027 and $58.05 in 2028:
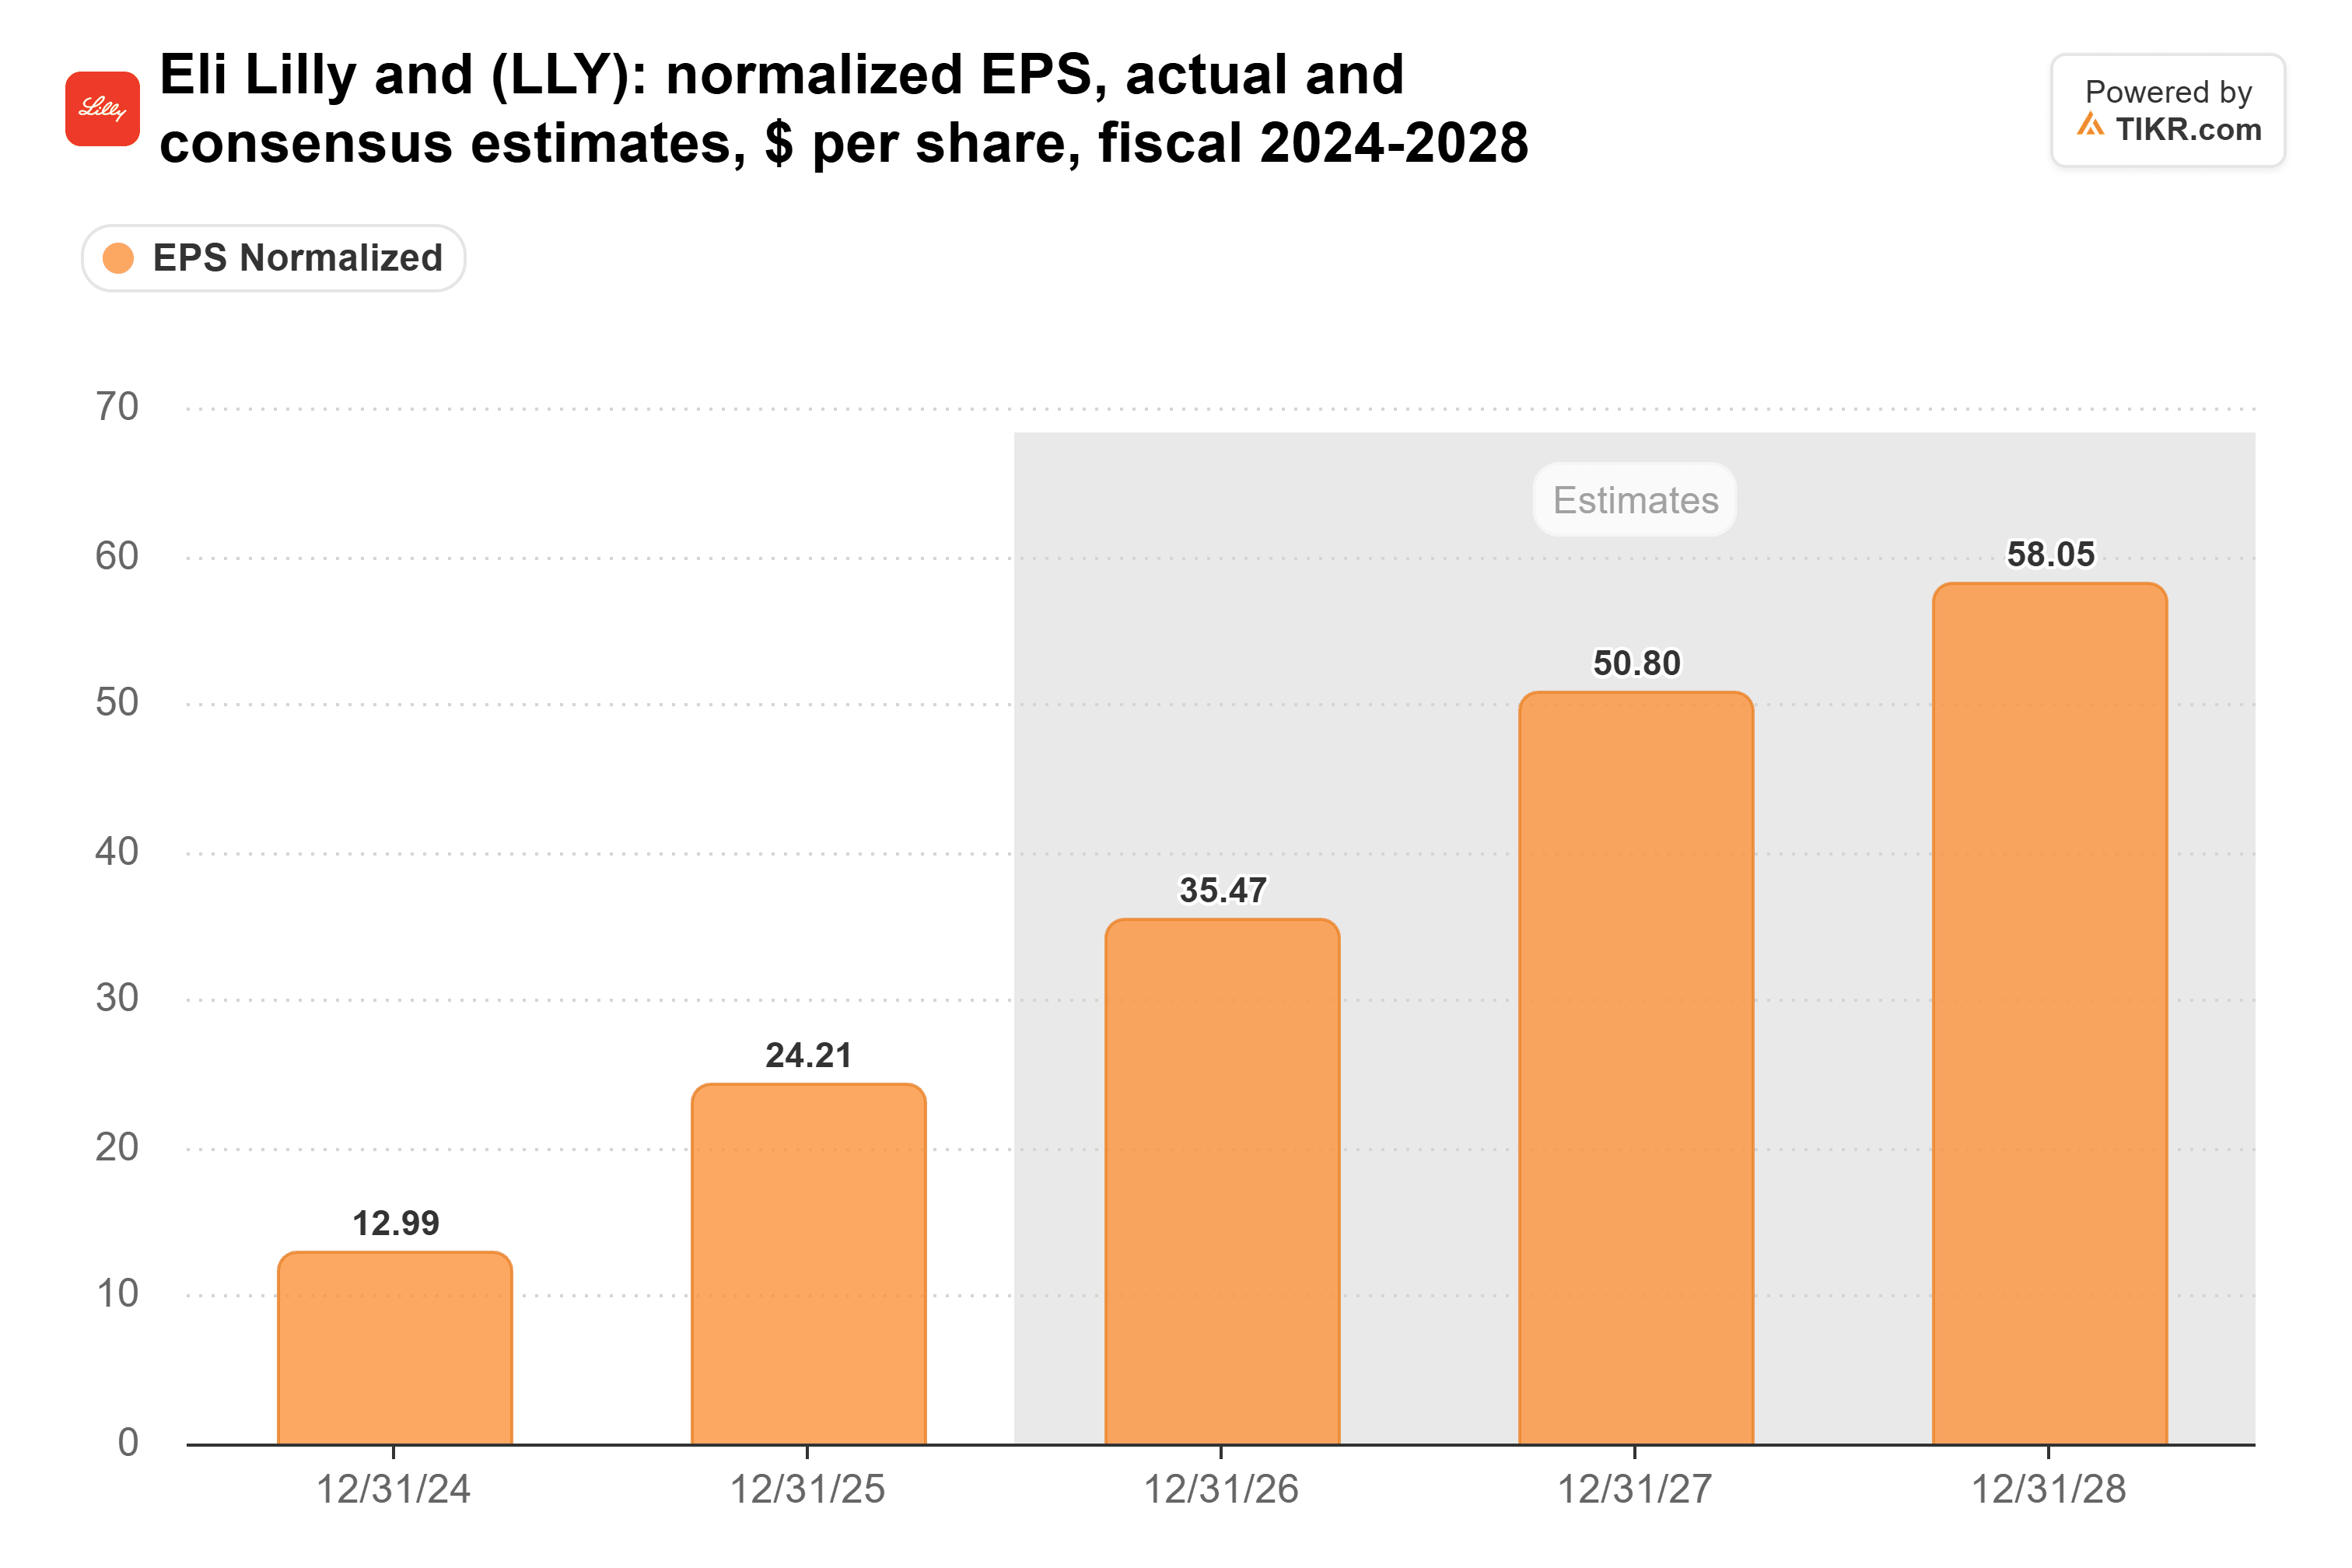
Before the third-quarter report, the 2027 estimate was closer to $47.50.
At the Nov. 13 close, Lilly traded at 31x those forward earnings, against a 5-year average of 40x. Barclays’ $1,550 works out to 33x:
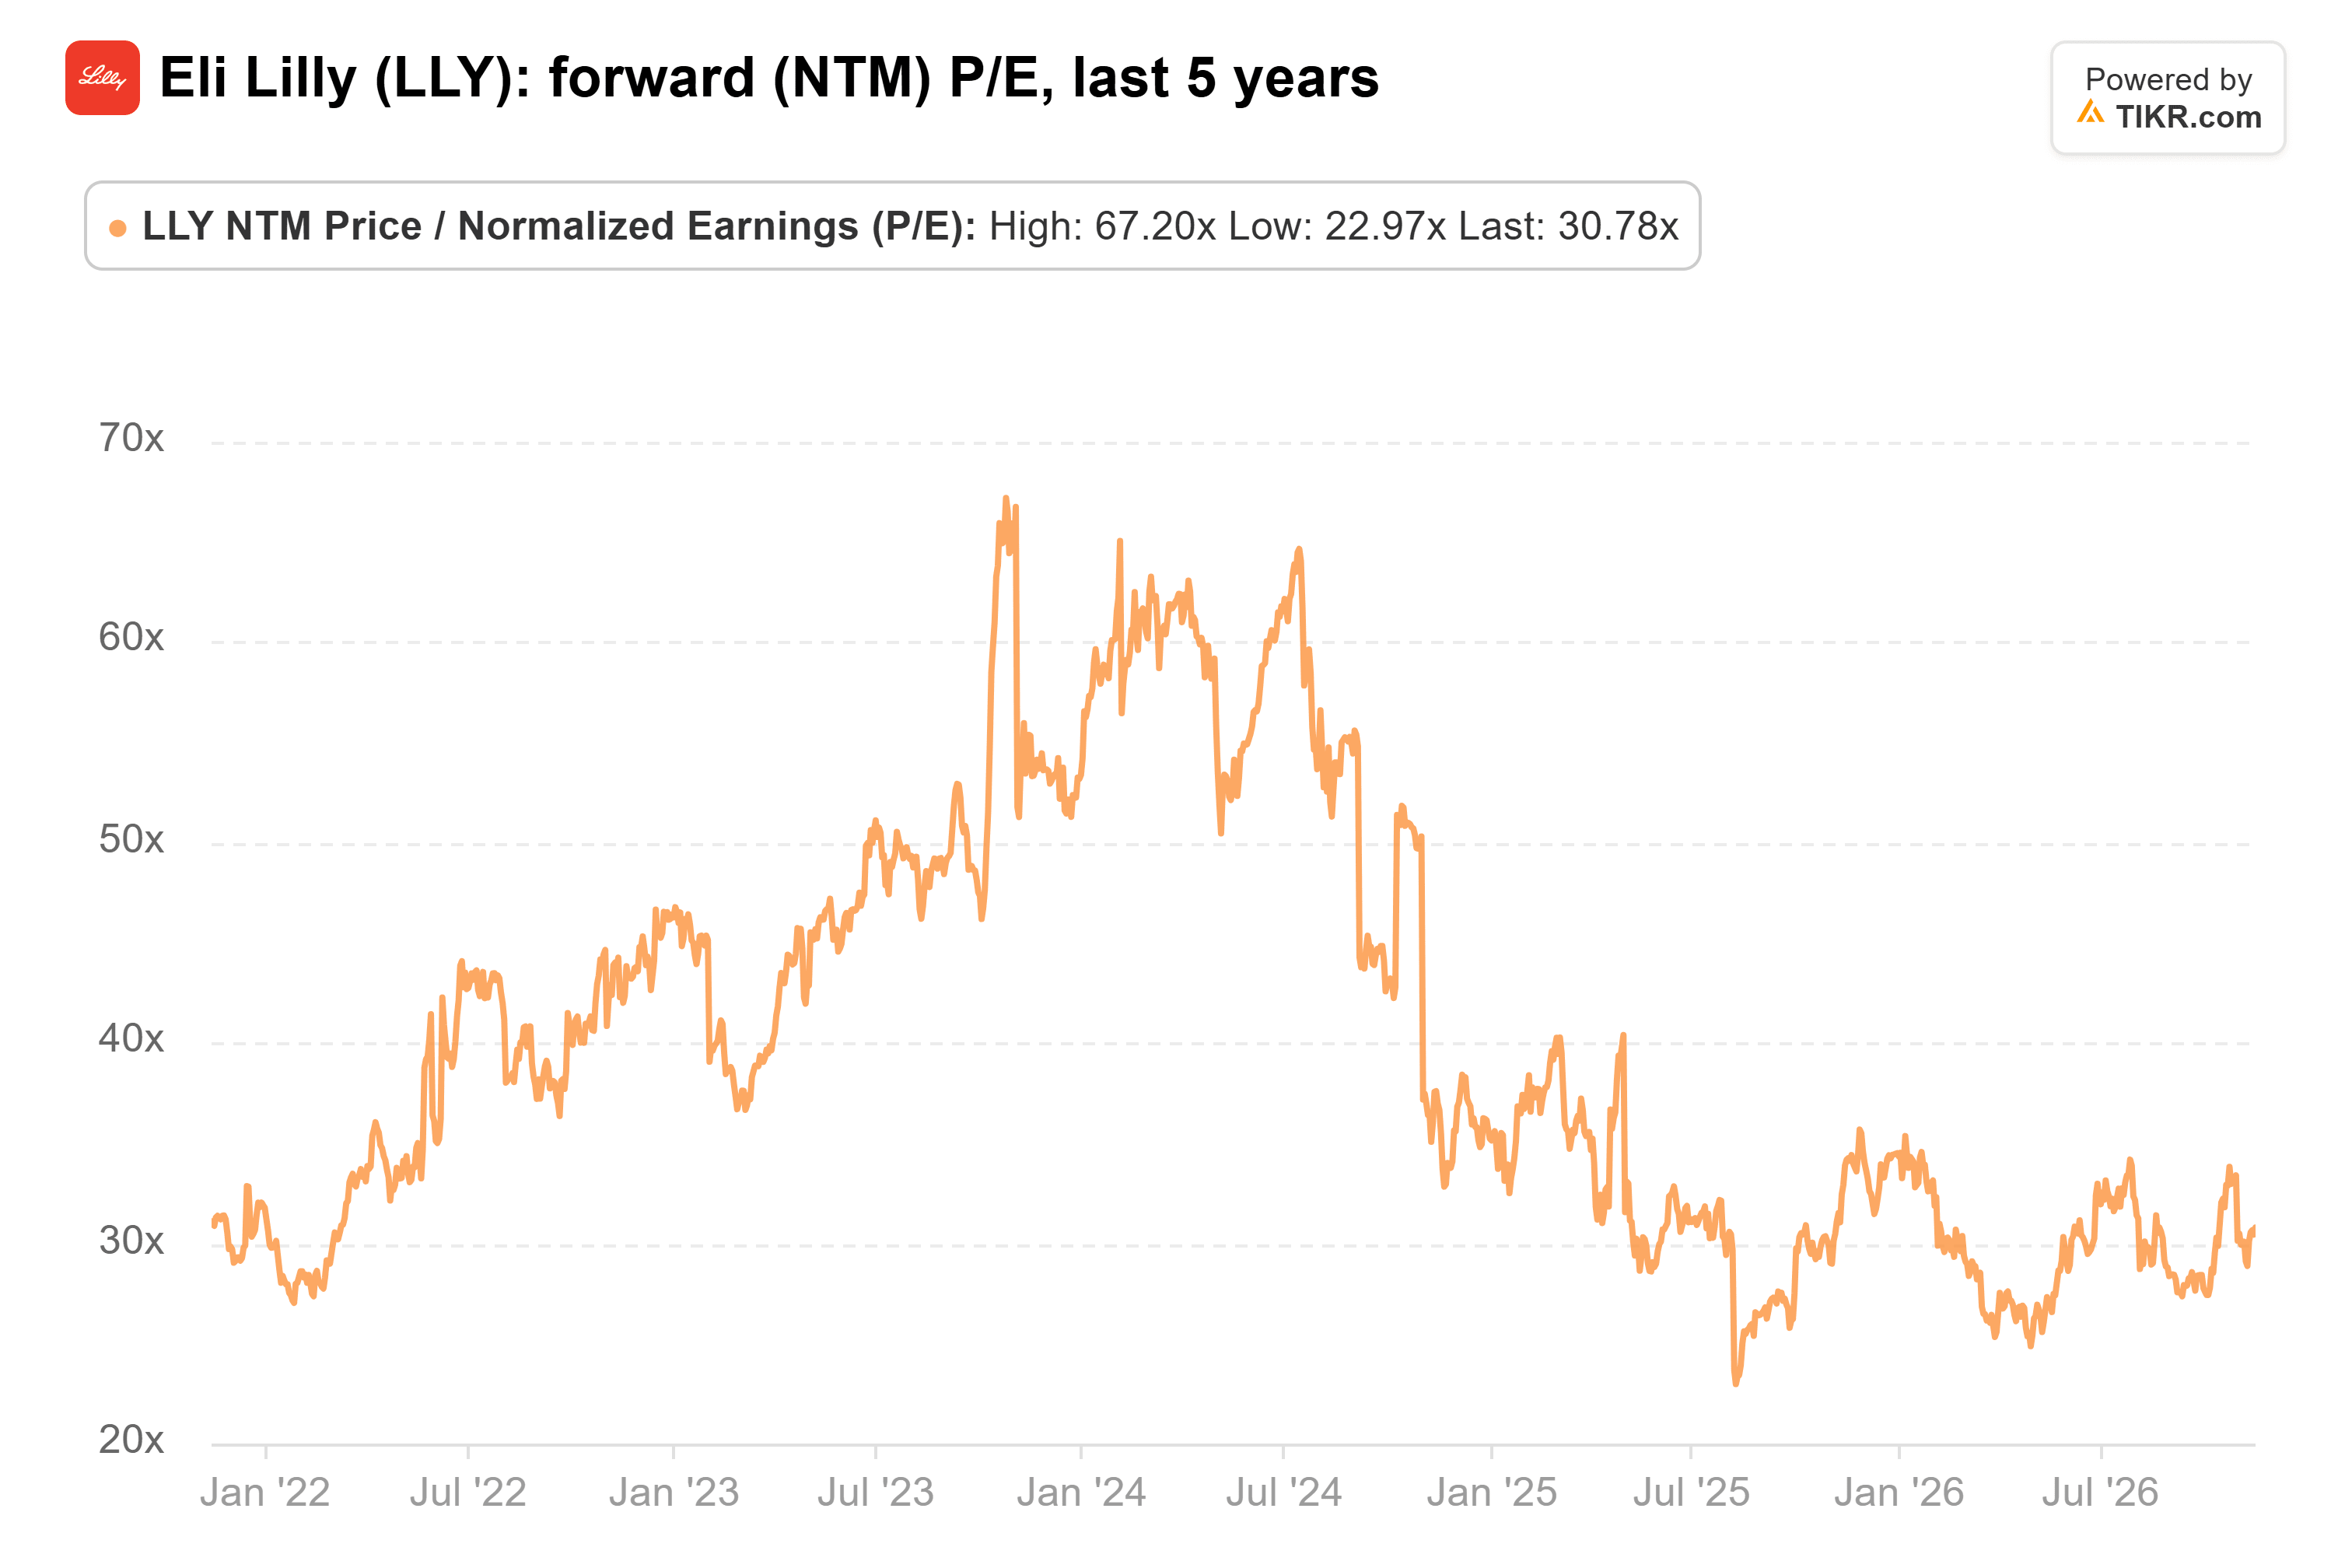
That 5-year average includes late 2023, when the multiple hit 67x. Over 12 years, Lilly’s quarter-end average is closer to 29x. So Barclays’ target implies a bit more than the stock’s long-run norm, on earnings that keep going up.
A fair target with a thin cushion
Price is the risk. Leaving out a favorable rebate adjustment, Lilly’s U.S. price fell 10% in the third quarter. Management also says about $2 billion of this year’s revenue came from one-time items it doesn’t expect to recur.
Barclays’ $1,550 holds up. At 33x, it sits between the stock’s 12-year and 5-year norms, and it rests on a 2027 earnings estimate that just jumped. But with about 9% upside, most of the run is already in the price. To go much higher, the stock needs volume to keep growing faster than prices fall. The next tests are Lilly’s Innovation Day on Dec. 7 and its first 2027 guidance in January. Barclays sees Innovation Day as a chance for management to lay out growth beyond obesity.
So what is Eli Lilly stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Eli Lilly could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!